
 Water Gel Market | 2026-2036
Water Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Water Gel Market Analytics
Asset-light leasing models for superabsorbent polymer production capacity are reshaping competitive dynamics in the Water Gel Market. Kemira leverages its backward integration into acrylamide monomers to sustain margin control across agricultural grades. SNF Group anchors its position through manufacturing scale in water treatment adjacent chemistries. BASF SE differentiates via R&D intensity in biodegradable hydrogel formulations.
Water gel denotes a cross-linked hydrophilic polymer matrix capable of absorbing and retaining aqueous solutions up to hundreds of times its dry mass, functioning primarily as a moisture reservoir or controlled-release medium in industrial and consumer systems. Sodium polyacrylate dominates volume due to mature supply chains and cost efficiency in diaper and agricultural applications, while natural polymers represent the fastest-expanding margin pool as European REACH compliance tightens synthetic additive restrictions. Personal care products command premium pricing relative to agricultural mulching, though the latter absorbs the majority of tonnage through bulk procurement contracts.
EPA guidelines on acrylamide monomer residuals and REACH registration requirements for polymer imports collectively elevate compliance costs for non-integrated producers. China's MEE enforces discharge standards that favor closed-loop manufacturing in domestic facilities. Stakeholders must monitor regulatory divergence between EU biodegradability certifications and US FDA medical device polymer standards when allocating R&D budgets across geographic markets.
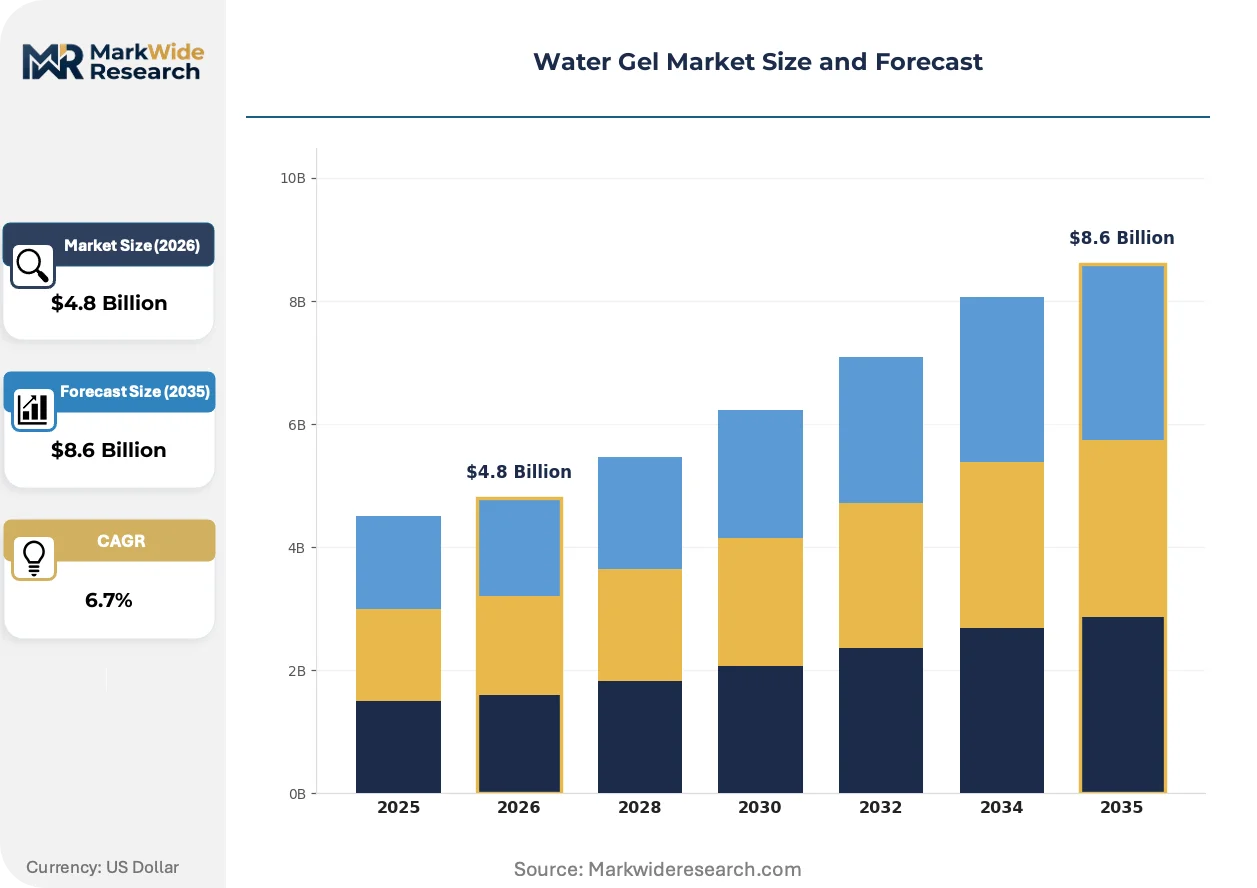
Market Dynamics
China's GB standards for biodegradable polymers are forcing a recalibration of product specifications across the Water Gel Market, compressing margins for non-compliant producers while rewarding integrated manufacturers with captive monomer supply.
Growth Catalysts
- Arid-zone agricultural mulching:Farmers in Rajasthan and Gujarat deploy superabsorbent polymers to cut irrigation frequency by half, locking in multi-year procurement contracts with state irrigation departments.
- REACH synthetic additive restrictions:ECHA's tightening polymer registration requirements accelerate substitution toward natural hydrogel formulations in European personal care applications.
- India's PM-KUSAN irrigation efficiency programs:Central government subsidies for drip-mulch integration drive bulk SAP procurement through district cooperative networks.
Market Restraints
- Acrylamide monomer price volatility:Propylene feedstock swings transmit directly to sodium polyacrylate production costs, squeezing toll manufacturers without backward integration.
- MEE discharge compliance:China's Ministry of Ecology and Environment standards favor capital-intensive closed-loop facilities, disadvantaging smaller batch producers in Shandong province.
- Biodegradation rate limitations:Cross-linked polyacrylates resist microbial breakdown in soil applications, inviting regulatory scrutiny under EU soil health directives.
Strategic Opportunities
- Medical device hydrogel coatings:FDA polymer standards for wound-care matrices create a premium tier distinct from commodity agricultural grades.
- Cell-culture substrate convergence:Hyaluronic acid-chitosan hybrid gels bridge cosmetic and pharmaceutical applications, opening regenerative medicine channels.
- Asset-light production leasing:Kemira-style tolling arrangements let regional distributors capture margin without reactor capex, penetrating undersupplied African markets.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for controlled-release kinetics concentrates in Basel and Shanghai clusters, inflating compensation for mid-tier producers.
- ISO 10993 biocompatibility timelines:Medical-grade hydrogel certification cycles stretch 18-24 months, freezing R&D pipelines for cross-over agricultural suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Gel Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Superabsorbent Polymer, Sodium Polyacrylate, Natural Polymers, Cellulose Derivatives Application: Agricultural Mulching, Personal Care Products, Medical Devices, Packaging End User: Agriculture, Healthcare, Consumer Goods, Food Industry Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Kemira, MAXAM, SNF Group, Poly Union Chemical Holding Group Co., Ltd., Shenzhen King Explorer Science and Technology Corporation, BASF SE, Kuraray Co. Ltd, 3M, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Gel Market Evolving Landscape
Process analytical technology is digitizing quality control across hydrogel production lines, compressing batch-release cycles while tightening monomer residual tolerances.
Sensor-integrated reactor monitoring is digitizing real-time cross-link density measurement, replacing offline gel fraction testing. Agricultural SAP buyers in Australia's Murray-Darling basin now specify digitized certificate-of-analysis data streams in supply agreements. This capability is digitizing audit costs for exporters serving multiple regulatory jurisdictions simultaneously.
REACH polymer registration deadlines are forcing reformulation investments ahead of 2026 dossier submissions. ECHA's revised guidance on cross-linked polymer biodegradability testing elevates analytical spending for importers. European diaper manufacturers are accelerating natural polymer sourcing to preempt supply disruption.
Cooperative procurement pooling is consolidating buyer power among Indian state irrigation departments. Bulk tender aggregation through NABARD-linked farmer producer organizations displaces fragmented distributor purchasing. This concentration is most visible in Maharashtra and Karnataka, where district-level SAP procurement now flows through single-window clearance portals.
Water Gel Market Segmentation
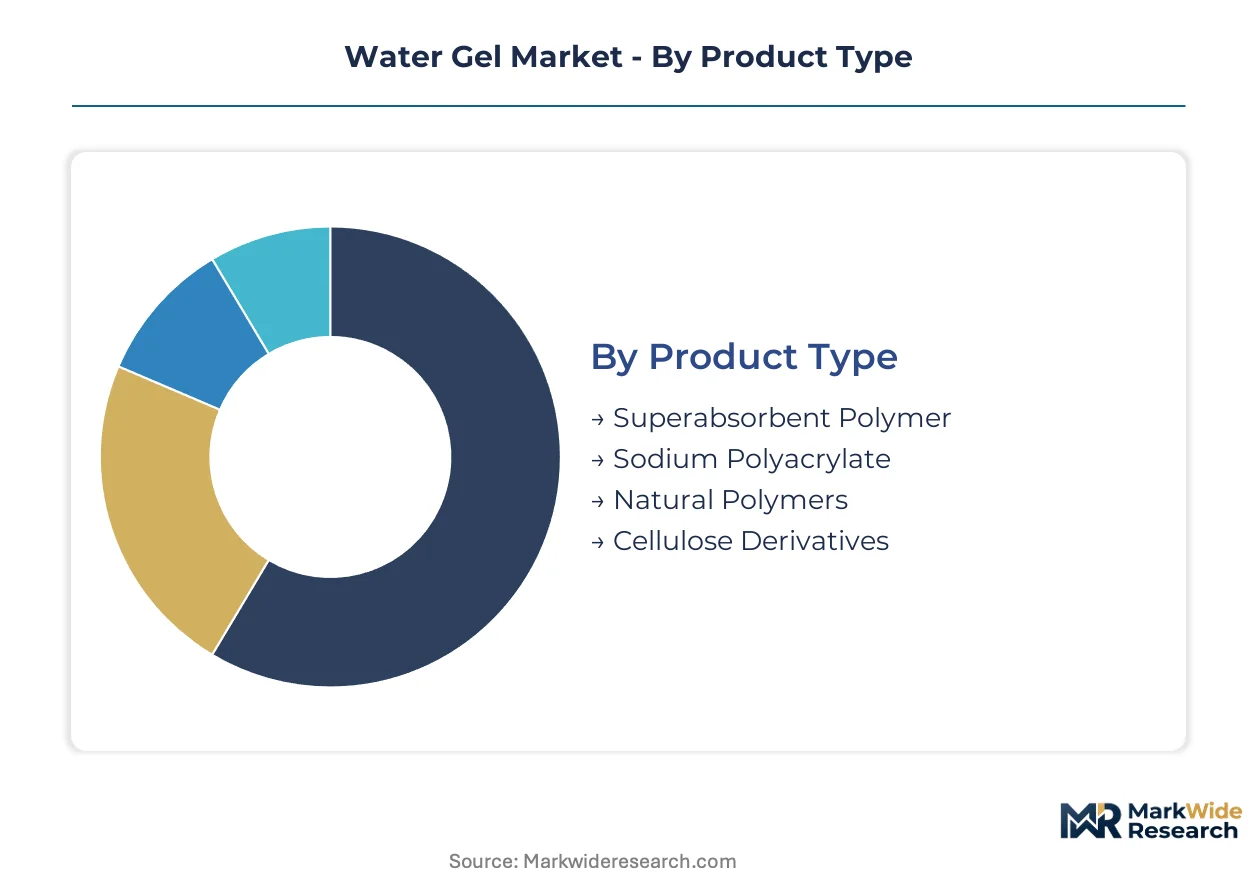
Water gel segmentation reveals divergent margin structures across polymer chemistries and end-use specifications. Technical requirements for medical biocompatibility create pricing premiums unreachable in bulk agricultural procurement.
Product Type:
After-sales service intensity escalates sharply from commodity sodium polyacrylate to medical-grade natural polymers, with formulation troubleshooting and regulatory documentation support becoming critical revenue attachments.
- Sodium Polyacrylate:Cross-linked polyacrylate chains absorb hundreds of times their dry mass through osmotic pressure gradients. Demand concentrates in Indian state irrigation cooperatives where PM-KUSAN subsidies lock in multi-year bulk contracts for mulching applications.
- Natural Polymers:Starch-graft copolymers and polysaccharide matrices biodegrade under soil microbial action. European REACH registration deadlines accelerate substitution from synthetics, with ECHA's revised cross-linked polymer guidance forcing reformulation investments ahead of dossier submissions.
- Superabsorbent Polymer:Broad-category absorbent matrices span synthetic and hybrid formulations. Specifications vary by cross-link density and particle size distribution.
- Cellulose Derivatives:Carboxymethyl cellulose and hydroxyethyl cellulose provide viscosity-controlled gelation. Pharmaceutical coating applications in Basel and Shanghai clusters command technical support premiums.
By volume, sodium polyacrylate leads. By growth pace, natural polymers are expanding most quickly.
Application:
Cost tier stratification separates commodity agricultural grades from premium medical device coatings, with certification overhead creating insurmountable barriers for cross-over suppliers.
- Agricultural Mulching:Soil-incorporated moisture reservoirs cut irrigation frequency by half in Rajasthan and Gujarat. Australia's Murray-Darling basin buyers now mandate digitized certificate-of-analysis data streams in supply agreements.
- Personal Care Products:Diaper cores and cosmetic matrices demand residual monomer control below EPA thresholds. ECHA's tightening synthetic additive restrictions accelerate natural hydrogel sourcing among European manufacturers.
- Medical Devices:Wound-care matrices and drug-delivery substrates require ISO 10993 biocompatibility certification. FDA polymer standards create a premium tier distinct from commodity grades.
- Packaging:Absorbent pads for fresh produce and moisture-sensitive goods utilize controlled-release kinetics. Food-contact compliance varies by regional regulator requirements.
Agricultural mulching absorbs majority tonnage through bulk procurement. Medical devices command the steepest margin expansion trajectory.
End User:
Customer type determines specification stringency, with healthcare procurement mandating batch traceability absent in consumer goods channels.
- Agriculture:State irrigation departments and farmer producer organizations aggregate demand through NABARD-linked cooperative pooling. Maharashtra and Karnataka district-level procurement flows through single-window clearance portals.
- Healthcare:Hospitals and wound-care clinics specify hydrogel coatings with 18-24 month ISO 10993 certification timelines. Polymer chemist talent scarcity concentrates formulation expertise in Basel and Shanghai.
- Consumer Goods:Diaper manufacturers and cosmetic brands balance absorbency performance against biodegradability positioning. REACH compliance pressures reshape European sourcing patterns.
- Food Industry:Fresh produce packaging and moisture-control applications require food-contact approvals. Regulatory divergence between EU and US standards complicates multi-market supply.
Agriculture dominates volume procurement. Healthcare is gaining share fastest on per-kilogram value metrics.
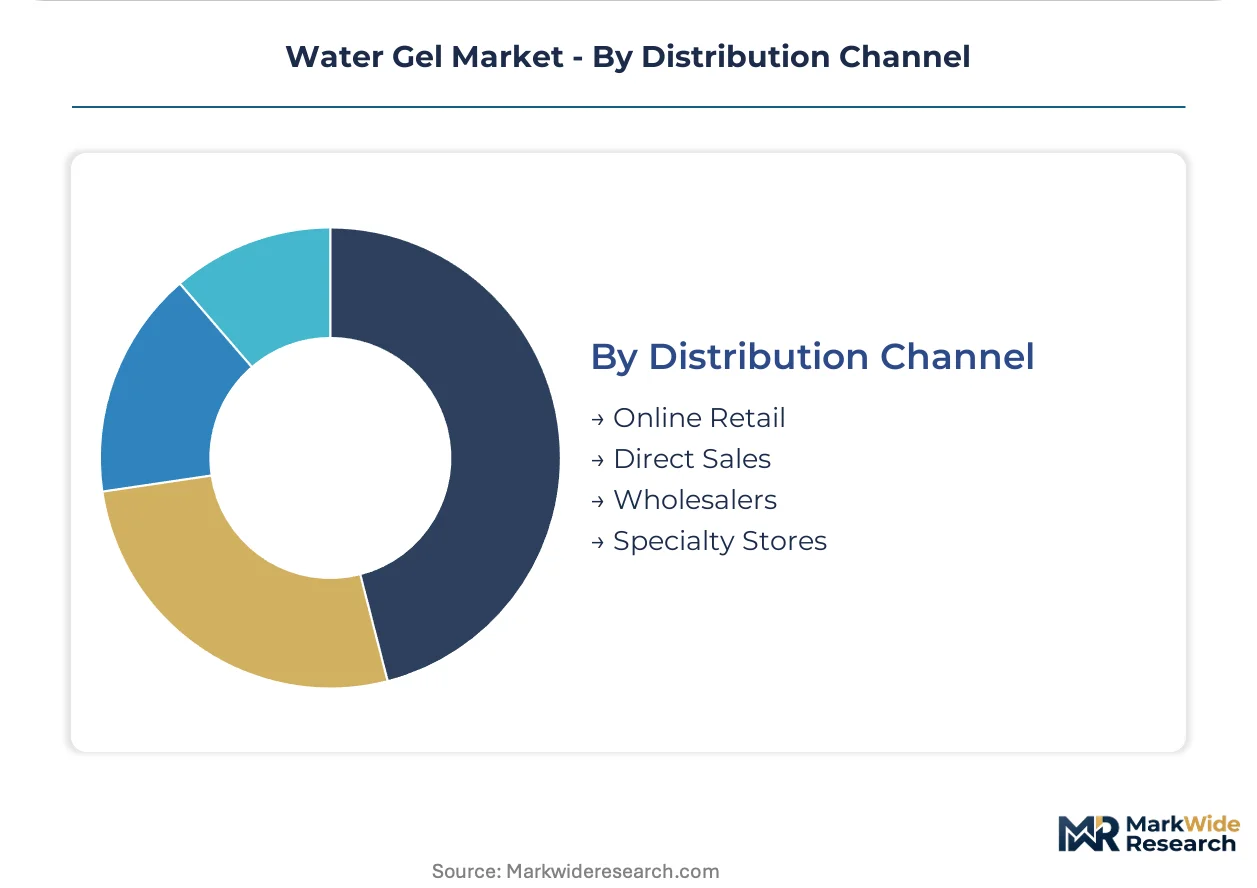
Distribution Channel:
Supply concentration favors direct sales for bulk agricultural contracts, while specialty stores capture premium medical and cosmetic segments requiring technical consultation.
- Direct Sales:Kemira-style tolling arrangements and asset-light production leasing penetrate undersupplied African markets without reactor capex. State irrigation departments in India prefer direct manufacturer relationships for multi-year agreements.
- Wholesalers:Regional distributors aggregate fragmented agricultural demand across smaller farming operations. China's Shandong province batch producers rely on wholesale channels to reach domestic buyers.
- Online Retail:E-commerce platforms serve small-scale agricultural buyers and consumer goods purchasers. Digitized audit capabilities reduce compliance costs for exporters serving multiple regulatory jurisdictions.
- Specialty Stores:Medical supply distributors and cosmetic ingredient boutiques provide formulation support. Personal care product buyers seek premium pricing through technical service differentiation.
Direct sales leads by contract value. Online retail is climbing the fastest on transaction volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water gel trade flows reveal a pronounced export concentration from Chinese manufacturers toward agricultural importers in India and Australia, while European demand shifts toward biodegradable formulations that domestic capacity struggles to supply.
China
Shandong province hosts the densest cluster of sodium polyacrylate reactors serving agricultural export contracts. The Ministry of Ecology and Environment enforces wastewater discharge standards that favor capital-intensive closed-loop facilities over smaller batch producers. Yangtze River Delta manufacturers are digitizing certificate-of-analysis streams to satisfy Australian buyers in the Murray-Darling basin.
India
Rajasthan and Gujarat farmers deploy superabsorbent polymers to halve irrigation frequency, locking in multi-year procurement through state irrigation departments. The PM-KUSAN program channels central subsidies toward drip-mulch integration via NABARD-linked cooperative networks. Maharashtra and Karnataka district-level procurement now flows through single-window clearance portals that aggregate bulk demand.
Germany
ECHA's REACH registration deadlines force reformulation investments ahead of 2026 dossier submissions for cross-linked polymer imports. The Rhine-Ruhr industrial corridor concentrates formulation expertise for controlled-release kinetics, inflating compensation for polymer chemists. Baden-Württemberg medical device manufacturers specify ISO 10993 biocompatibility timelines that stretch 18-24 months.
United States
EPA guidelines on acrylamide monomer residuals elevate compliance costs for non-integrated producers importing sodium polyacrylate. FDA polymer standards for wound-care matrices create a premium tier distinct from commodity agricultural grades. Texas and Louisiana petrochemical corridors supply propylene feedstock that transmits price volatility directly to toll manufacturers.
Australia
Murray-Darling basin agricultural buyers now mandate digitized certificate-of-analysis data streams in supply agreements with superabsorbent polymer exporters. The country's national agricultural regulator enforces import documentation standards that compress audit costs for multi-jurisdictional suppliers. Sydney and Melbourne distribution hubs consolidate regional demand for moisture-retention solutions in arid-zone farming.
Water Gel Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on monomer supply and formulation IP. The vendor base organizes around three archetypes: backward-integrated chemical conglomerates with captive acrylamide production, toll manufacturers leasing reactor capacity without asset ownership, and natural polymer specialists pivoting from starch derivatives toward REACH-compliant alternatives. Dominant competitive moves include asset-light production leasing arrangements and R&D alliances bridging cosmetic and pharmaceutical hydrogel applications.
Among European-headquartered multinationals, BASF SE exemplifies the integrated archetype with in-house monomer production, while Kemira anchors the Nordic cluster through upstream control over acrylamide supply chains. SNF Group represents the scale-driven specialist model with manufacturing breadth across water treatment adjacent chemistries.
| Leading Market Players |
|---|
| Kemira |
| MAXAM |
| SNF Group |
| Poly Union Chemical Holding Group Co., Ltd. |
| Shenzhen King Explorer Science and Technology Corporation |
| BASF SE |
| Kuraray Co. Ltd |
| 3M |
| Ashland |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta port freight corridors transmit propylene feedstock cost swings directly to sodium polyacrylate producers, concentrating pricing power among Shandong manufacturers with captive monomer supply while fragmenting margin structures for toll-dependent competitors serving Indian agricultural cooperatives.
Pricing Analysis
Industrial OEM buyers anchor contract pricing across three performance tiers: medical-grade ISO 10993-certified hydrogels command premiums, agricultural bulk grades trade on volume scale, and personal care formulations balance residual monomer control against biodegradability positioning. Price differentiation hinges on certification overhead and backward integration into acrylamide production. Cost compression in commodity agricultural tiers intensifies as PM-KUSAN subsidy pools concentrate buyer leverage. State irrigation departments exhibit lowest price sensitivity; toll manufacturers without captive feedstock face highest margin pressure.
Supply Chain Analysis
Propylene feedstock draws from Texas and Louisiana petrochemical corridors, with acrylamide monomer production concentrating in China's Shandong province and Germany's Rhine-Ruhr industrial cluster. Sodium polyacrylate reactors depend on cross-linker chemicals and catalyst systems sourced from Basel and Shanghai formulation specialists. Single-source vulnerability runs through Shandong's closed-loop MEE-compliant facilities, which now capture majority export contract flow. Distribution runs through direct manufacturer relationships for Indian state irrigation departments, with African markets penetrated via Kemira-style asset-light tolling arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water gel markets reward service-attach revenue models, with formulation troubleshooting and regulatory documentation support expanding faster than base polymer tonnage as REACH compliance deadlines force importer reformulation investments.
For Market Incumbents: Insulate margin structures by deepening captive acrylamide supply and digitizing certificate-of-analysis streams for Australian Murray-Darling basin buyers. ECHA's tightening cross-linked polymer biodegradability guidance threatens non-integrated European importers; certification investment in ISO 10993 biocompatibility timelines creates defensive moats against agricultural-grade cross-over competitors. For New Entrants and Emerging Players: Establish a beachhead in natural polymer formulations for European personal care applications, where REACH synthetic additive restrictions accelerate substitution demand. Underserved African agricultural markets offer penetrable volume via asset-light production leasing without reactor capex. Go-to-market leverage rests on NABARD-linked cooperative procurement pooling in Maharashtra and Karnataka districts. For Investors and Strategic Acquirers: Carve-out targets emerge from chemical conglomerates' non-core hydrogel divisions, particularly those with stranded sodium polyacrylate capacity lacking REACH-compliant natural polymer pipelines. Long-term viability centers on R&D alliances bridging cosmetic and pharmaceutical applications. Signal to monitor: FDA polymer standard revisions for wound-care matrices that would elevate premium tier entry barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Monomers | Kemira sustains margin control across agricultural grades through captive upstream supply. |
| Green Manufacturing Transition | ECHA's REACH deadlines force reformulation investments ahead of dossier submissions. |
| Long-term Supply Agreement | PM-KUSAN subsidies lock multi-year bulk contracts with Rajasthan and Gujarat irrigation departments. |
| Joint Venture | Hyaluronic acid-chitosan hybrid development bridges cosmetic and regenerative medicine channels. |
| Capacity Expansion | Shandong province closed-loop facilities capture export contract flow under MEE discharge standards. |
Research Methodology
A spread of perspectives from polymer chemists, agricultural procurement officers at Indian state irrigation departments, medical device regulatory affairs leads, and water treatment chemical distributors converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from customs trade databases, SEC filings of listed chemical producers, ECHA registration dossiers, and NABARD cooperative procurement records. Bottom-up tonnage estimates from district-level SAP procurement portals triangulated against top-down market value reconstruction.
Demand-supply balance modeling across the projection horizon segmented by polymer chemistry type, application specification tier, end-user procurement channel, and regional regulatory cluster. CAGRs derived from trend extrapolation of PM-KUSAN subsidy disbursement trajectories, ECHA registration deadline impacts on import substitution, and digitized certificate-of-analysis adoption curves in Australian agricultural supply agreements. Forecast inputs incorporated propylene feedstock price volatility transmission coefficients and polymer chemist talent scarcity compensation inflation in Basel and Shanghai clusters.
Macroeconomic conditions sit as an overlay; deviation in Indian monsoon patterns, EU soil health directive enforcement intensity, or Chinese dual carbon goal implementation pace would shift the trajectory. Forecasts reflect documented assumptions about REACH compliance cost pass-through rates and medical device certification timeline compression. Cross-checking against ECHA registration database updates and NABARD quarterly procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Global Turbidity Meters Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Global Naphthalene Water Reducers Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market