
 Process Water Treatment Market | 2026-2036
Process Water Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Process Water Treatment Market Analysis
The split between premium membrane-based systems and commodity chemical dosing packages is realigning how vendors structure their portfolios and service models. Veolia leverages its integrated design-build-operate capabilities to anchor large industrial contracts across multiple geographies. Xylem competes through advanced digital monitoring platforms that extend equipment lifecycle and reduce unplanned downtime. Evoqua specializes in high-purity water systems for pharmaceutical and microelectronics clients, occupying a defensible niche with stringent specification requirements.
Process water treatment encompasses the physical, chemical, and biological methods used to condition water for industrial operations, including reverse osmosis membranes rated to 0.0001 micron retention and ion exchange resins for dissolved mineral removal. Its primary purpose is to protect capital equipment, ensure product quality, and maintain regulatory compliance across manufacturing environments. Membrane technology leads capital allocation due to rising energy efficiency standards and declining module costs, while UV treatment segments grow fastest in food and beverage applications seeking chemical-free disinfection. Chemical treatment remains mature with stable margins concentrated in boiler and cooling tower applications where established supplier relationships limit switching.
The EPA enforces effluent limitation guidelines that shape discharge permit requirements for power generation and manufacturing facilities, directly driving retrofit demand for advanced biological treatment and filtration upgrades. China's MEE implements increasingly strict industrial water reuse quotas that force manufacturing plants to invest in closed-loop process water systems rather than once-through cooling. ISO 14001 environmental management certification now functions as a market access threshold for multinational supply chain participation. Stakeholders must monitor how tightening water stress indices in semiconductor manufacturing clusters will reshape regional investment priorities and technology selection criteria.
Market Dynamics
Membrane technology is compressing equipment replacement cycles as semiconductor fabs and pharmaceutical plants demand higher purity thresholds that legacy chemical systems cannot achieve. This technical displacement is redrawing vendor competitive boundaries.
Growth Catalysts
- EPA Effluent Guidelines:Tightening discharge standards for power plants are forcing retrofits of biological treatment and advanced filtration systems across US industrial corridors.
- Semiconductor Water Demand:Chip fabrication facilities in Taiwan, South Korea, and the United States are scaling ultrapure water capacity to match wafer output expansion.
- China Water Reuse Mandates:MEE industrial quotas are accelerating closed-loop system deployment in manufacturing clusters previously dependent on once-through cooling.
Market Restraints
- Membrane Module Supply Concentration:Reverse osmosis and nanofiltration element production clusters in East Asia create vulnerability to logistics disruptions and input cost spikes.
- Skilled Technician Shortage:Specialized expertise in membrane autopsy, resin regeneration optimization, and digital control integration remains scarce across service networks.
- High Purity Water Capital Intensity:Multi-effect distillation and electrodeionization systems for pharmaceutical applications require substantial upfront investment with extended payback periods.
Strategic Opportunities
- India Industrial Water Reuse:BIS standards adoption and state-level zero liquid discharge mandates are opening retrofit markets in textiles, chemicals, and food processing.
- UV-C LED Convergence:Mercury-free disinfection technology combined with advanced oxidation processes is penetrating food and beverage applications seeking chemical elimination.
- Digital Twin Integration:Predictive maintenance platforms for membrane performance modeling are creating new recurring revenue streams for equipment vendors.
Industry Challenges
- Legacy Control System Integration:Brownfield facilities struggle to interface new membrane skids with existing SCADA architectures without costly downtime.
- ISO 14001 Certification Timelines:Multinational supply chain participation now requires environmental management certification that stretches smaller vendor compliance resources.
- Cross-Contamination Risk Management:Pharmaceutical and microelectronics clients demand validated cleaning protocols that complicate multi-product service operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Water Treatment Market |
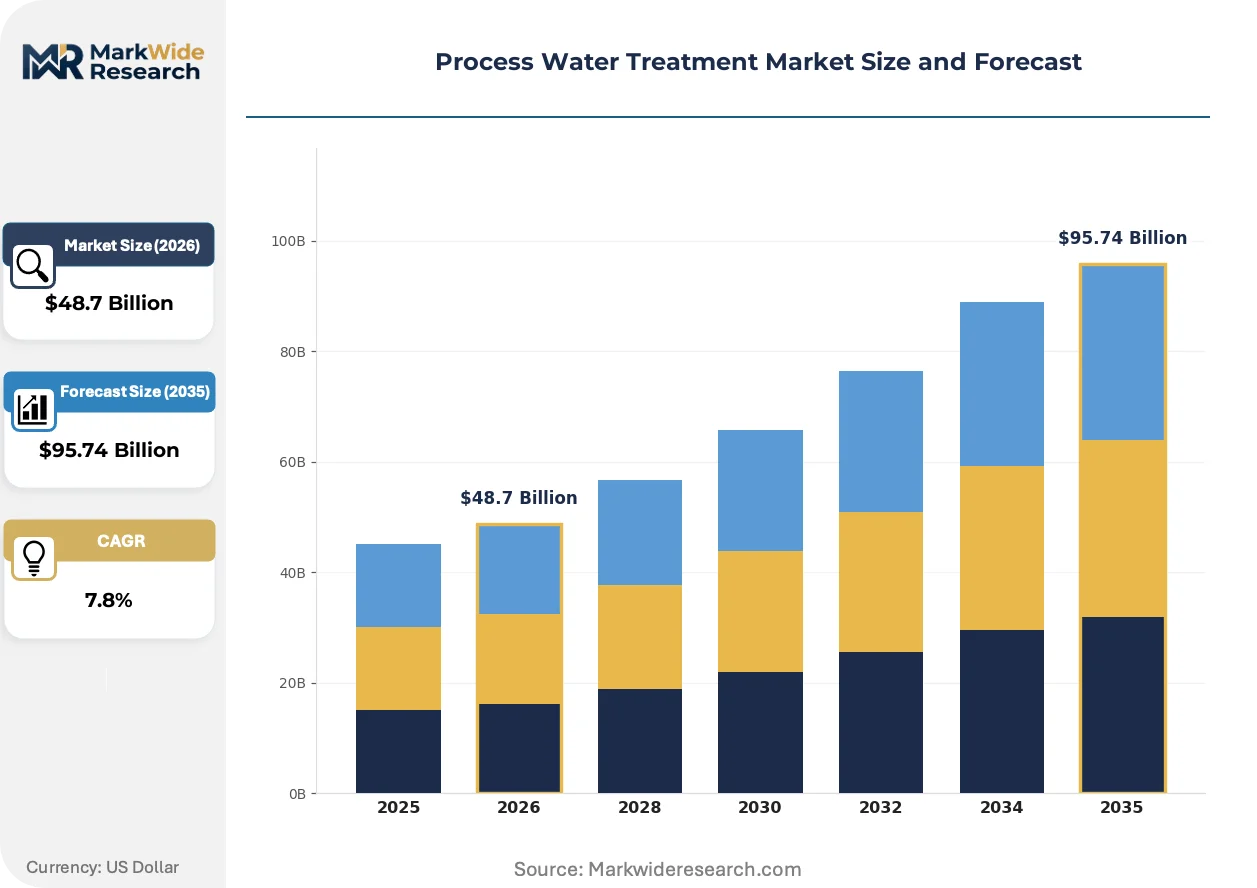
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $95.74 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtration Systems, Chemical Treatment, Biological Treatment, Disinfection Systems Application: Industrial Processes, Agriculture, Pharmaceutical, Municipal Technology: Membrane Technology, UV Treatment, Electrochemical, Activated Sludge End User: Manufacturing, Food & Beverage, Oil & Gas, Power Generation |
| Companies Covered | Xylem, Fluence Corporation, Veolia, Pentair, Culligan, Evoqua, SUEZ, Hella Water, Aquatech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Water Treatment Market Emerging Trajectories
Digital monitoring platforms are redefining how treatment performance is guaranteed, shifting vendor-customer relationships from equipment transactions to continuous optimization partnerships.
Forward osmosis draw-solute regeneration systems are expanding into high-salinity industrial wastewater applications where reverse osmosis faces fouling limitations. Mining operations and oilfield produced water managers are piloting these configurations to reduce energy intensity. This technology is expanding into markets previously dominated by thermal evaporators.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating certain membrane chemistries and antiscalant formulations from European supply chains. Chemical suppliers are reformulating product lines to maintain registration compliance. Membrane manufacturers serving EU pharmaceutical and electronics clients are accelerating fluoropolymer-free material qualification programs.
Performance-based service contracts are displacing traditional capital purchase models in municipal and industrial accounts. Contractors assume operational risk while clients pay for guaranteed output quality and volume. This structure is most visible in US power generation and refining sectors where OPEX flexibility outweighs balance-sheet preferences.
Process Water Treatment Market Segmentation
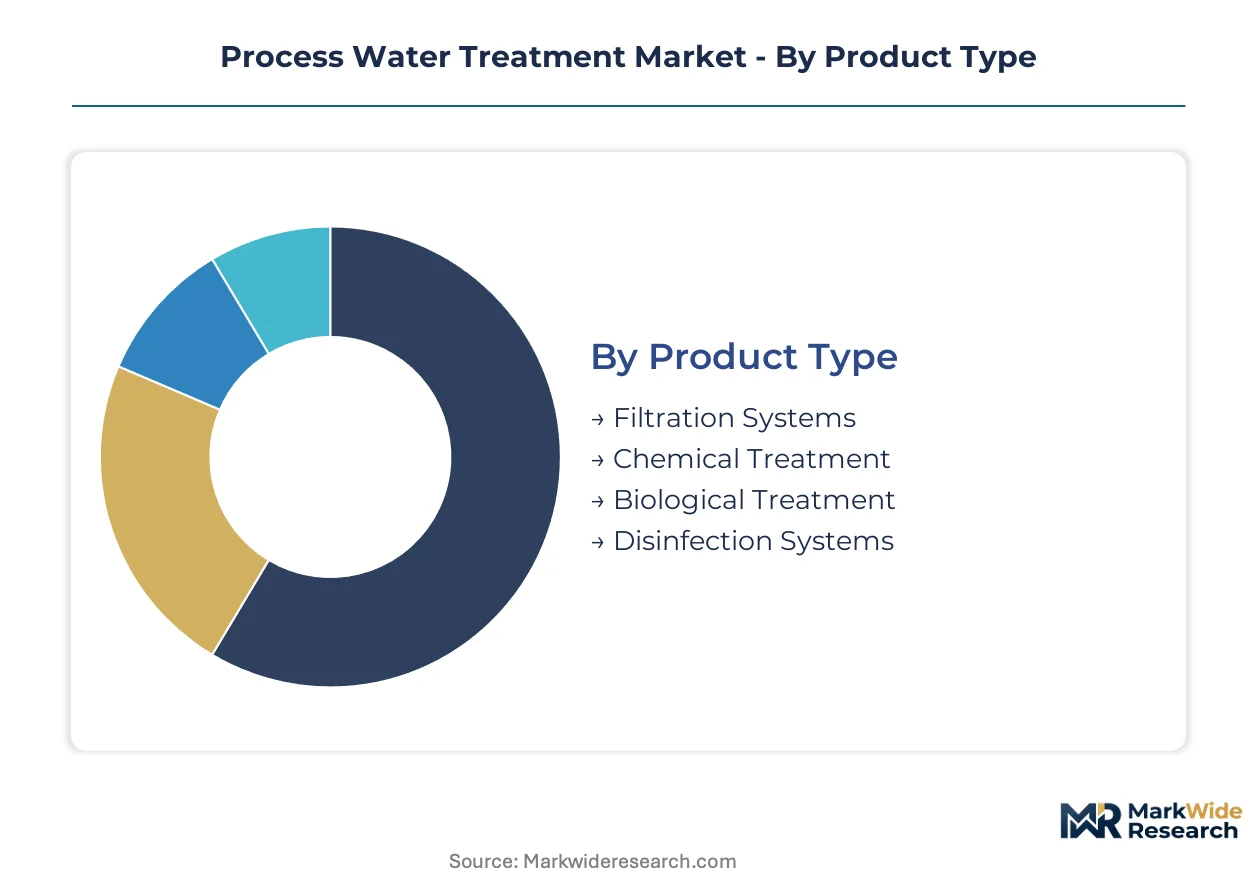
Technology selection in process water treatment hinges on effluent specifications, energy constraints, and regulatory discharge limits rather than capital cost alone. Buyers prioritize operational reliability and compliance assurance over upfront equipment expenditure. Segmentation reveals where membrane displacement of legacy systems is accelerating versus where chemical dosing retains defensible economics.
Product Type:
Capital deployment intensity varies sharply between consumable chemical programs and durable equipment systems, reshaping vendor revenue models and customer lifetime value calculations.
- Filtration Systems:Physical separation technologies span media filters rated to 10 micron through ultrafiltration membranes at 0.01 micron retention. Semiconductor fabs in Taiwan and South Korea are scaling ultrapure water capacity to match wafer output expansion, driving demand for multi-stage filtration trains with automated backwash cycles.
- Chemical Treatment:Coagulation, flocculation, and pH adjustment using alum, ferric chloride, and sulfuric acid remain entrenched in boiler and cooling tower applications. Stable supplier relationships and proven performance specifications limit switching despite membrane technology advances.
- Biological Treatment:Activated sludge and moving bed biofilm reactor systems degrade organic loads in food processing and pharmaceutical effluent.
- Disinfection Systems:Chlorination, ozonation, and UV irradiation eliminate pathogens prior to discharge or reuse.
Volume sits with Chemical Treatment; growth tilts toward Filtration Systems.
Application:
End-use purity thresholds dictate technology selection, with pharmaceutical and microelectronics applications demanding specification rigor that excludes commodity suppliers.
- Industrial Processes:Cooling water makeup, boiler feed conditioning, and rinse water recycling across manufacturing operations. China's MEE industrial reuse quotas are accelerating closed-loop system deployment in manufacturing clusters previously dependent on once-through cooling.
- Pharmaceutical:Water for injection and purified water systems governed by FDA and EMA validation requirements. Multi-effect distillation and electrodeionization systems require substantial upfront investment with extended payback periods, concentrating supply among qualified vendors.
- Agriculture:Irrigation water treatment and livestock operation effluent management.
- Municipal:Drinking water treatment and wastewater reclamation for industrial offtake.
Revenue concentrates in Industrial Processes; specification intensity peaks in Pharmaceutical.
Technology:
Energy efficiency standards and module cost declines are compressing equipment replacement cycles as facilities demand purity thresholds legacy systems cannot achieve.
- Membrane Technology:Reverse osmosis, nanofiltration, ultrafiltration, and microfiltration modules rated from 0.0001 to 10 micron retention. Reverse osmosis and nanofiltration element production clusters in East Asia create vulnerability to logistics disruptions and input cost spikes.
- UV Treatment:Medium-pressure mercury and emerging UV-C LED systems for chemical-free disinfection. Mercury-free disinfection technology combined with advanced oxidation processes is penetrating food and beverage applications seeking chemical elimination.
- Electrochemical:Electrocoagulation and electro-oxidation for heavy metal removal and refractory organics.
- Activated Sludge:Conventional biological treatment for biodegradable wastewater streams.
Membrane Technology commands capital allocation; UV Treatment expands most quickly.
End User:
Operational risk tolerance and balance sheet preferences determine whether customers favor capital purchase or performance-based service structures.
- Manufacturing:Electronics, automotive, and textiles operations requiring process water for fabrication and cleaning. Performance-based service contracts are displacing traditional capital purchase models where OPEX flexibility outweighs balance-sheet preferences.
- Power Generation:Cooling tower makeup and boiler feedwater treatment across thermal and combined-cycle plants. EPA effluent limitation guidelines are tightening discharge standards, forcing retrofits of biological treatment and advanced filtration systems.
- Food & Beverage:Product water, CIP rinse, and effluent treatment with stringent microbiological limits.
- Oil & Gas:Produced water management and refinery process water treatment.
Manufacturing leads absolute spend; Power Generation drives retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors global ultrapure water treatment demand as Taiwan Semiconductor Manufacturing Company scales 3nm and 2nm fabrication capacity. Industrial water stress indices are reshaping capital deployment priorities across major manufacturing corridors.
United States
Power generation utilities in the Ohio River Valley and Texas Gulf Coast are retrofitting biological treatment systems to meet EPA effluent limitation guidelines for coal ash and cooling tower discharge. The EPA's tightening standards for selenium and mercury removal are forcing multi-billion dollar filtration upgrades across aging thermal fleets. Semiconductor fabs in Phoenix and Austin are expanding deionized water capacity to support domestic chip manufacturing reshoring.
China
MEE industrial water reuse quotas are accelerating closed-loop system deployment in the Yangtze River Delta manufacturing belt. The dual carbon goals framework is restricting freshwater withdrawal permits for steel and chemical plants in Jiangsu and Zhejiang provinces. Electronics assemblers in Shenzhen and Dongguan are investing in zero liquid discharge systems to maintain export certification compliance.
Germany
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer membrane chemistries from pharmaceutical water systems in the Rhine-Main industrial corridor. EMA validation requirements for water-for-injection production are concentrating supply among qualified equipment vendors serving BASF and Bayer manufacturing sites. Chemical producers in Ludwigshafen are qualifying fluorine-free antiscalant formulations to maintain registration compliance.
South Korea
Samsung and SK Hynix are scaling ultrapure water treatment capacity in the Gyeonggi-do semiconductor cluster to match memory chip output expansion. METI-aligned energy efficiency standards are driving membrane technology displacement of thermal distillation in Pyeongtaek and Icheon fabrication facilities. National water reuse mandates are forcing electronics suppliers to invest in closed-loop rinse water recovery systems.
India
BIS standards adoption and state-level zero liquid discharge mandates are opening retrofit markets in the Gujarat textile belt and Maharashtra chemical corridor. The PLI scheme for semiconductor manufacturing is attracting ultrapure water system vendors to the Dholera Special Investment Region. Food processors in Punjab and Haryana are deploying UV-C LED disinfection to meet FSSAI microbiological limits without chemical residuals.
Process Water Treatment Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and service integration depth. The vendor base organizes into three tiers: integrated design-build-operate contractors, equipment specialists with digital monitoring platforms, and regional chemical dosing providers. Consolidation pressure is intensifying as membrane module cost declines compress standalone equipment margins. Dominant competitive moves include strategic partnerships for forward osmosis draw-solute regeneration licensing and geographic expansion through performance-based service contract assumptions.
Within the integrated service tier, Veolia and SUEZ exemplify the design-build-operate archetype spanning multiple industrial geographies. Xylem occupies a position on the digital monitoring vector, while Evoqua anchors the high-purity specialization niche for pharmaceutical and microelectronics validation requirements. These three patterns represent how vendors are restructuring portfolios around operational risk assumption rather than equipment transaction economics.
| Leading Market Players |
|---|
| Xylem |
| Fluence Corporation |
| Veolia |
| Pentair |
| Culligan |
| Evoqua |
| SUEZ |
| Hella Water |
| Aquatech |
| Others |
Supply Flow & Price Mechanics
Semiconductor fabs and pharmaceutical manufacturers concentrate procurement authority among a handful of validation-qualified buyers, anchoring pricing to guaranteed uptime and regulatory compliance rather than capital equipment cost. This buyer concentration forces vendors toward performance-based contracts where payment hinges on continuous output quality.
Pricing Analysis
Value-based pricing anchors on guaranteed water purity throughput and system uptime commitments rather than equipment list prices. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical systems from industrial commodity packages. Pricing pressure stems from declining membrane module costs compressing standalone equipment margins. Municipal and small manufacturing accounts exhibit highest price sensitivity, while semiconductor and pharmaceutical buyers prioritize compliance assurance over capital expenditure.
Supply Chain Analysis
Freight cost volatility from East Asia to North American and European installation sites amplifies total cost of ownership for membrane-based systems. Reverse osmosis and nanofiltration element production clusters in Japan, South Korea, and China create geographic concentration risk. Polyamide membrane chemistries and specialty ion exchange resins draw from petrochemical feedstocks vulnerable to commodity swings. Distribution runs through authorized service networks requiring certified technician deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The process water treatment market functions as a vertical-integration race where membrane manufacturers seek captive resin supply and service providers acquire installation capabilities to capture lifecycle revenue.
For Market Incumbents: Acquire membrane autopsy and resin regeneration service capabilities to lock in aftermarket revenue streams. Incumbents must defend against digital-native entrants by embedding predictive maintenance platforms into existing equipment bases. Backward integration into specialty chemical formulations protects margin compression from raw material volatility. For New Entrants and Emerging Players: Mid-sized food processors in India and Southeast Asia represent an underserved buyer archetype seeking chemical-free disinfection without pharmaceutical-grade validation costs. UV-C LED systems penetrate this segment through pay-per-volume service models. Joint ventures with regional engineering contractors accelerate local certification and service network buildout. For Investors and Strategic Acquirers: The window for entry favors vertically integrated water technology platforms with both equipment manufacturing and performance-contract execution capabilities. Targets should demonstrate recurring revenue above fifty percent and validated positioning in semiconductor or pharmaceutical verticals. Watch for MEE enforcement acceleration in China as the signal for regional consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Chemistry | Captive polyamide supply secures margin control against East Asian module cost declines. |
| Performance-Based Service Contract Expansion | OPEX flexibility appeals to power generators facing EPA retrofit mandates with constrained capital budgets. |
| Digital Twin Platform Development | Predictive membrane performance modeling creates recurring revenue and raises customer switching costs. |
| Fluoropolymer-Free Material Qualification | REACH compliance in EU pharmaceutical corridors maintains market access for membrane suppliers. |
| Zero Liquid Discharge System Deployment | China MEE quotas and India BIS standards accelerate closed-loop system retrofit demand. |
Methodological Framework
Independent corroboration across plant engineers at semiconductor fabrication facilities, procurement leads at power generation utilities, and regulatory affairs directors at pharmaceutical manufacturers underwrites the qualitative findings. Secondary validation draws from EPA effluent guideline filings, MEE water reuse quota announcements, and SEC disclosures by publicly traded water technology vendors. Bottom-up equipment shipment data triangulates against top-down capital expenditure surveys across industrial verticals.
Comparable-period anchoring to historical membrane replacement cycles and regulatory implementation timelines structured the projection methodology. The analytical framework segments by technology type, application purity threshold, end-user operational risk tolerance, and regional regulatory enforcement intensity across the modeling period. CAGRs derive from equipment deployment trajectories tied to semiconductor fab buildouts and power plant retrofit mandates. Forecast inputs incorporate membrane cost decline curves and skilled technician availability constraints.
Revisions become necessary when EPA effluent guideline implementation timelines shift, MEE enforcement intensity fluctuates, or membrane supply chain disruptions alter equipment availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
Global Water Softeners Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Industrial Wastewater Treatment Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Global Naphthalene Water Reducers Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market