
 Asia-Pacific Water Treatment Chemicals Market | 2026-2036
Asia-Pacific Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Water Treatment Chemicals Market Analysis
Multi-source procurement among municipal water utilities is realigning supplier relationships across the Asia-Pacific basin. Ecolab leverages its integrated service-chemistry model to anchor long-term contracts with metropolitan water authorities. Kemira competes through specialized coagulant manufacturing at scale in Australia and Southeast Asian hubs. Kurita Water Industries Ltd differentiates via on-site technical service teams that reduce dosage variability for power plant cooling circuits.
Water treatment chemicals comprise formulated additives—coagulants, flocculants, disinfectants, and pH regulators—designed to remove suspended solids, control microbial growth, and stabilize acidity in processed water streams, typically dosed at parts-per-million to parts-per-thousand concentrations depending on influent turbidity and target effluent quality. Coagulants and flocculants dominate product-type revenue due to their indispensability in primary clarification across municipal and industrial facilities, while pH regulators command premium pricing in semiconductor and pharmaceutical effluent treatment where narrow operational bands are mandatory. Industrial wastewater applications are outpacing municipal segments in growth velocity as manufacturing clusters in Vietnam and Indonesia expand pre-treatment capacity ahead of tightening discharge permits.
China's MEE enforces progressively lower total dissolved solids and heavy metal limits, forcing upgrade cycles in chemical feed systems and driving substitution toward polymeric flocculants from inorganic alum. India's Central Pollution Control Board mandates zero-liquid-disclosure readiness for textile clusters in Tiruppur and Surat, redirecting procurement toward advanced oxidation-compatible chemistries. Japan's METI efficiency standards for thermal power plants sustain demand for corrosion inhibitors and scale control formulations. Stakeholders must monitor regulatory divergence across these jurisdictions to align product registration portfolios and local blending capacity with jurisdiction-specific compliance timelines.
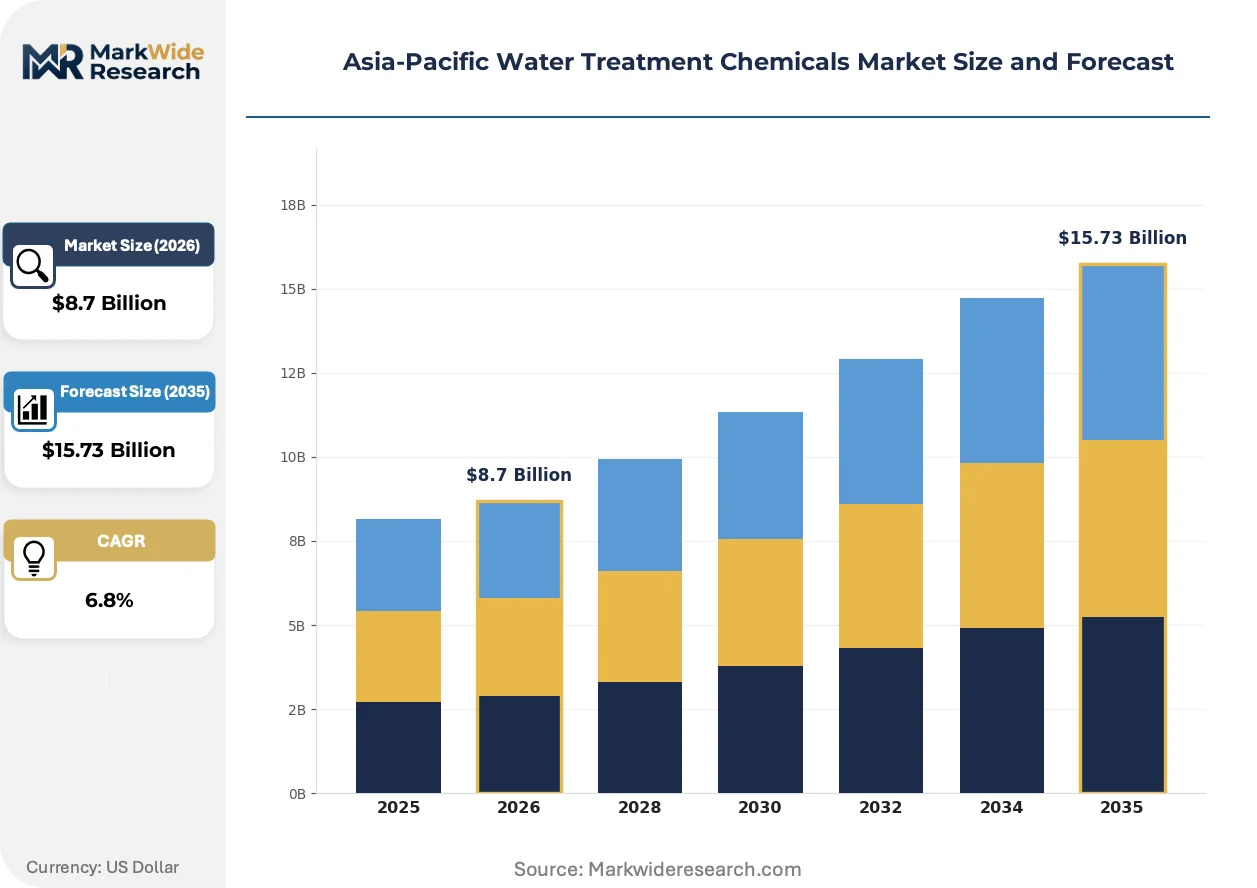
Market Dynamics
China's MEE discharge standards are compressing demand for commodity alum and ferric chloride, forcing a wholesale pivot toward polymeric flocculants and advanced oxidation chemistries across municipal and industrial procurement channels.
Growth Catalysts
- MEE discharge mandates:China's progressively lower total dissolved solids and heavy metal limits are triggering chemical feed system upgrades in textile and electronics manufacturing clusters, accelerating substitution from inorganic to polymeric formulations.
- Zero-liquid-disclosure readiness:India's Central Pollution Control Board mandates for Tiruppur and Surat textile corridors are redirecting procurement toward advanced oxidation-compatible chemistries and membrane pre-treatment additives.
- Industrial corridor expansion:Manufacturing clusters in Vietnam and Indonesia are expanding pre-treatment capacity ahead of tightening discharge permits, outpacing municipal segment velocity.
Market Restraints
- Feedstock volatility:Bauxite and sulfuric acid price swings constrain margin stability for inorganic coagulant producers operating at scale in Australian and Southeast Asian hubs.
- Technical substitution limits:Polymeric flocculants face performance ceilings in high-salinity brine treatment for thermal power plants, preserving incumbent corrosion inhibitor formulations.
- Regulatory fragmentation:Divergent registration timelines across China's MEE, India's CPCB, and Japan's METI inflate product portfolio compliance costs for multi-jurisdiction suppliers.
Strategic Opportunities
- Indonesia's emerging industrial zones:Batang and Karawang manufacturing corridors lack established chemical service infrastructure, creating first-mover advantage for on-site technical service deployment.
- Semiconductor effluent specialization:Narrow pH operational bands in chip fabrication wastewater are opening premium pricing tiers for buffered pH regulators with real-time dosing integration.
- Dual carbon alignment:China's carbon neutrality targets are incentivizing bio-based coagulant development through provincial green procurement preferences.
Industry Challenges
- Dosage optimization expertise:Power plant operators lack personnel trained in variable-frequency chemical feed system calibration, widening performance gaps between specified and actual consumption rates.
- Legacy infrastructure integration:Municipal utilities in older Southeast Asian metropolitan networks face mechanical incompatibility when retrofitting automated polymer make-down systems onto manual dosing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Water Treatment Chemicals Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, pH Regulators Application: Municipal Water Treatment, Industrial Wastewater, Pool Maintenance, Oil & Gas End User: Water Utilities, Food & Beverage, Power Plants, Pulp & Paper Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers |
| Companies Covered | Ecolab, Solenis, Kemira, Kurita Water Industries Ltd, Suez, BASF, Dow Chemical Company, Akzo Nobel NV, Thermax Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Water Treatment Chemicals Market Emerging Trajectories
Digital dosing control and real-time turbidity feedback are compressing the gap between laboratory-specified and field-actual chemical consumption, reshaping supplier value propositions toward outcome-guaranteed service models.
Automated polymer make-down systems with integrated viscosity sensing are automating dosage precision in municipal clarification trains. Metropolitan water authorities in Thailand and Malaysia are piloting these units to reduce operator-dependent variability. The technology is automating the transition from fixed-dose protocols to dynamic feed control, compressing chemical overfeed margins.
Japan's METI efficiency standards for thermal power plant cooling circuits are tightening corrosion inhibitor performance benchmarks. These rules are forcing reformulation of traditional phosphate-zinc blends toward molybdate and all-organic alternatives. Combined cycle gas turbine operators in the Kansai and Chubu regions are accelerating qualification trials for compliant scale control chemistries.
Integrated service-chemistry contracts are displacing transactional bulk chemical purchasing among Australian municipal utilities. Metropolitan water authorities are bundling chemical supply with on-site technical staffing and performance guarantees. This consolidation is most visible in Sydney and Melbourne, where long-term operator contracts now specify maximum allowable chemical cost per megalitre treated.
Asia-Pacific Water Treatment Chemicals Market Segmentation
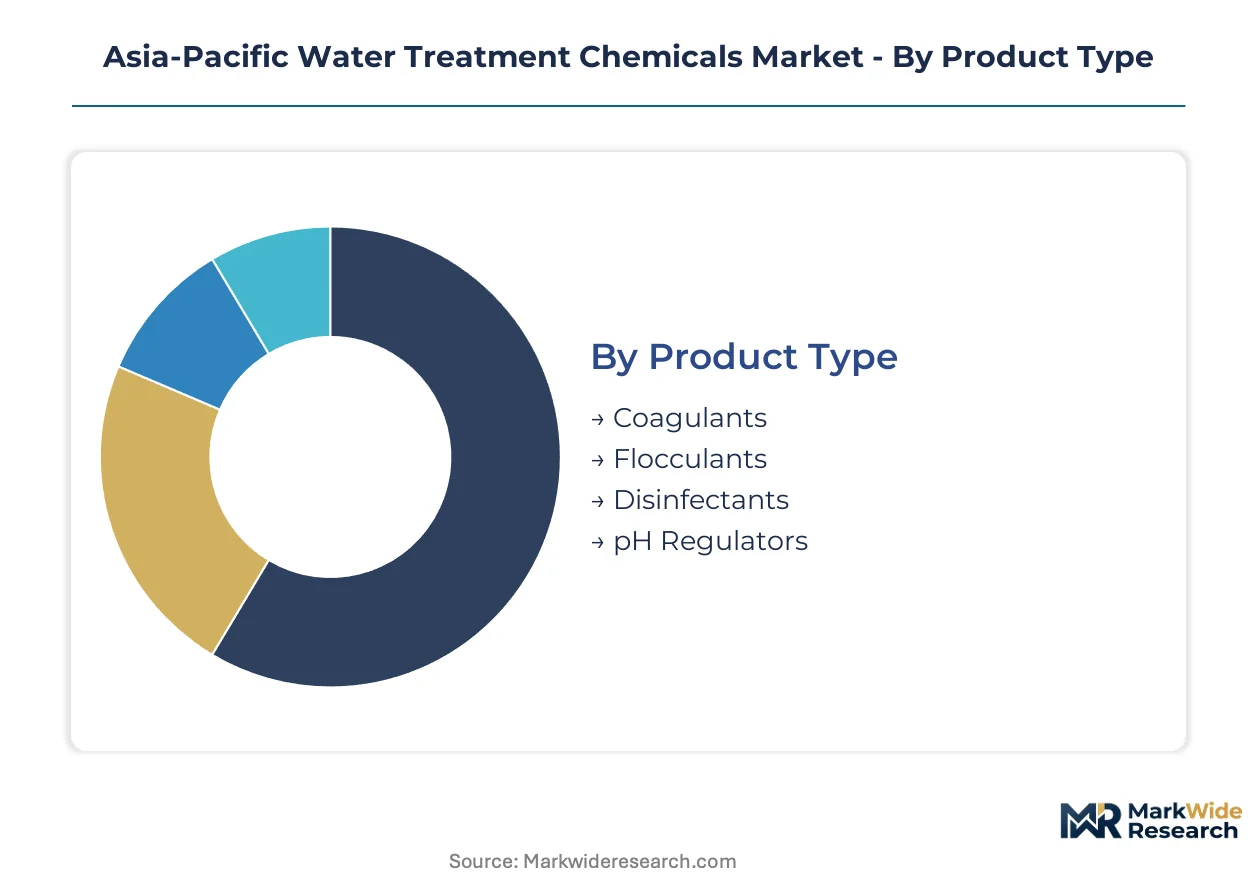
Water treatment chemicals operate across distinct technical and commercial layers that reshape procurement economics. Product chemistry determines dosing precision requirements. Application context dictates regulatory exposure and service intensity. End-user verticals concentrate volume differently across municipal and industrial channels.
Product Type:
Coagulants and flocculants function as standalone primary treatment chemistries, while pH regulators and disinfectants embed into multi-stage process trains with tighter integration dependencies.
- Coagulants:Inorganic aluminum and iron salts precipitate suspended solids through charge neutralization. Municipal utilities across China's Yangtze River Delta procure commodity alum at scale, though MEE discharge limits are forcing substitution toward pre-hydrolyzed variants.
- Flocculants:High-molecular-weight polyacrylamides bridge destabilized particles into settleable flocs. India's Tiruppur textile cluster consumes anionic polymers for dye wastewater clarification under CPCB zero-liquid-disclosure mandates.
- Disinfectants:Chlorine-based and alternative biocides control microbial load in distribution networks. Japan's metropolitan water authorities specify chloramine for residual stability in extended pipeline systems.
- pH Regulators:Sulfuric acid, caustic soda, and buffered formulations adjust influent acidity. Semiconductor fabs in South Korea's Pyeongtaek corridor demand precision-grade sulfuric for etching effluent neutralization.
Volume placements concentrate in Coagulants; the faster expansion belongs to Flocculants.
Application:
Cost tier stratification separates capital-intensive industrial pre-treatment from operational municipal clarification, with oil and gas commanding premium chemistry pricing.
- Municipal Water Treatment:Surface water clarification and distribution disinfection for metropolitan populations. Bangkok and Jakarta utilities are automating polymer feed systems to reduce operator-dependent overfeed.
- Industrial Wastewater:Pre-treatment for manufacturing effluent ahead of discharge or reuse. Vietnam's Bac Ninh electronics corridor is expanding chemical capacity ahead of tightened provincial permits.
- Pool Maintenance:Residential and commercial recreational water sanitization. Australia's seasonal demand peaks concentrate procurement through distributor networks in Queensland and New South Wales.
- Oil & Gas:Produced water treatment and injection fluid conditioning. Indonesia's Rokan and Mahakam fields specify scale inhibitors and biocides for high-salinity formation water.
Industrial Wastewater captures the steepest expansion trajectory as manufacturing corridors multiply pre-treatment obligations.
End User:
Customer type determines service model intensity, with power plants requiring continuous technical presence and food processors emphasizing certification documentation.
- Water Utilities:Metropolitan and regional authorities managing potable supply and sewage treatment. Sydney Water bundles chemical procurement with performance-guaranteed service contracts.
- Food & Beverage:Process water and effluent treatment for hygiene and compliance. Philippine beverage bottlers near Laguna de Bay face escalating discharge monitoring under DENR orders.
- Power Plants:Cooling water chemistry and boiler feed treatment. Japan's Chubu Electric qualifies molybdate corrosion inhibitors under revised METI efficiency standards.
- Pulp & Paper:Whitewater recycling and effluent clarification. New Zealand's Kinleith and Kawerau mills consume retention aids and defoamers for mechanical pulp processing.
Water Utilities anchor current volume; Power Plants are gaining share fastest on cooling circuit reformulation cycles.
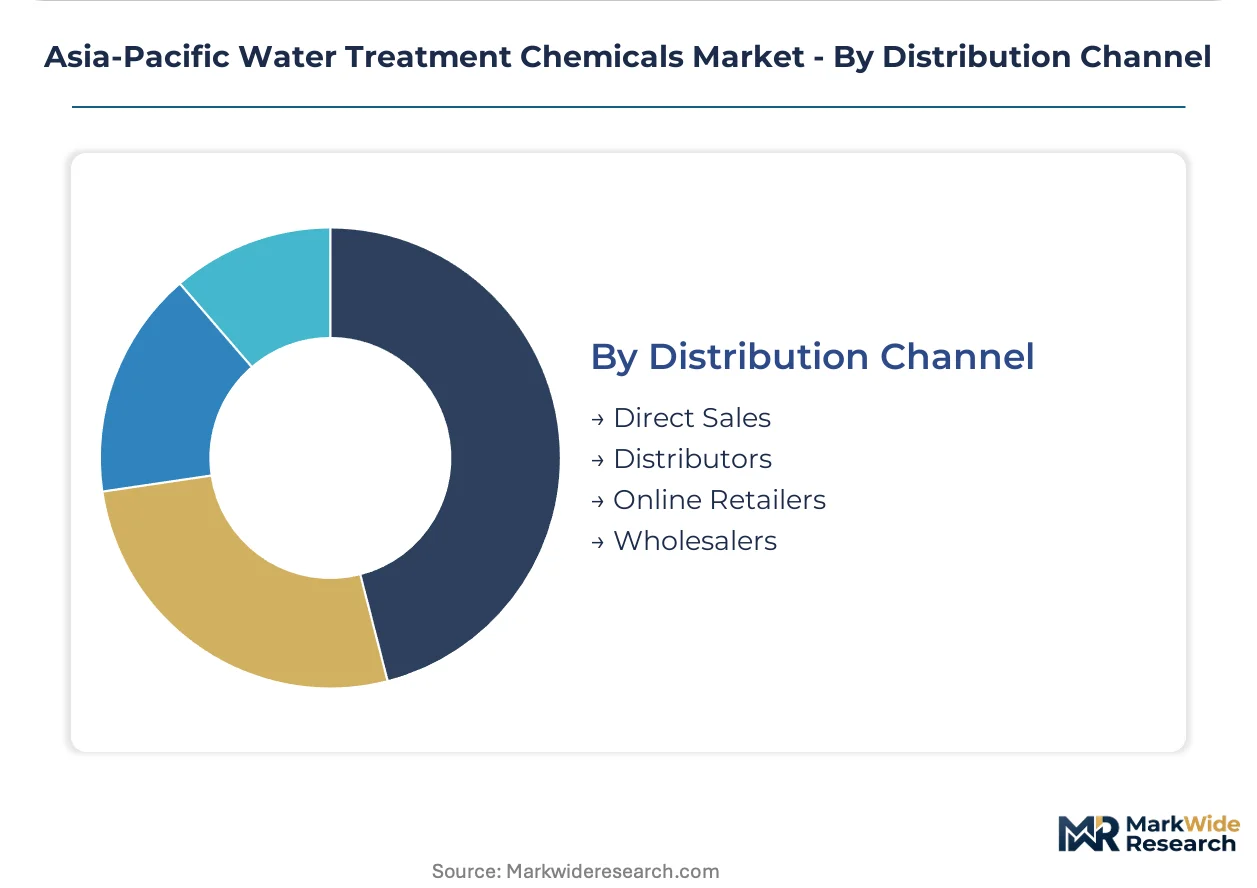
Distribution Channel:
Supply concentration varies by geography, with direct sales dominating contractual municipal accounts and distributors penetrating fragmented industrial bases.
- Direct Sales:Long-term supply agreements with integrated technical service. Kemira operates direct sales teams anchored at Australian and Southeast Asian manufacturing hubs.
- Distributors:Regional stocking and logistics for mid-scale industrial accounts. Thai chemical distributors serve second-tier manufacturing provinces beyond Bangkok's direct sales radius.
- Online Retailers:Small-volume procurement for pool maintenance and specialty applications. Australian e-commerce platforms aggregate residential disinfectant demand during summer peaks.
- Wholesalers:Bulk breaking and credit extension for peripheral municipal utilities. Indian wholesalers bridge cash-flow gaps for state water boards in Gujarat and Maharashtra.
Direct Sales command the largest transaction values; Distributors are climbing the fastest as industrial corridor fragmentation multiplies account density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bauxite deposits in Australia's Queensland and Western Australia anchor regional feedstock supply for inorganic coagulant manufacturing. Sulfuric acid production clusters in China's Shandong and Jiangsu provinces feed downstream formulation capacity across the basin.
China
Textile and electronics manufacturing clusters in the Yangtze River Delta consume polymeric flocculants at scale. MEE discharge standards enforcing lower total dissolved solids limits are forcing chemical feed system upgrades in Jiangsu and Zhejiang provinces. Suzhou and Hangzhou industrial parks are substituting pre-hydrolyzed aluminum variants for commodity alum in wastewater clarification.
India
Pharmaceutical and textile corridors in Gujarat and Maharashtra face escalating wastewater compliance obligations. Central Pollution Control Board zero-liquid-disclosure mandates for Tiruppur and Surat clusters are redirecting procurement toward advanced oxidation-compatible chemistries. The Ankleshwar industrial estate is expanding membrane pre-treatment additive capacity ahead of enforcement deadlines.
Japan
Thermal power plant operators in the Kansai and Chubu regions sustain demand for corrosion inhibitors and scale control formulations. METI efficiency standards are tightening performance benchmarks for cooling water chemistry. Osaka and Nagoya metropolitan utilities specify chloramine for residual stability in extended pipeline distribution networks.
Vietnam
Electronics manufacturing corridors in Bac Ninh and Hai Phong are expanding pre-treatment capacity ahead of tightened provincial discharge permits. Provincial environmental departments are modeling permit structures on China's MEE framework. Northern industrial zones lack established chemical service infrastructure, creating procurement fragmentation.
Indonesia
Batang and Karawang manufacturing corridors are multiplying pre-treatment obligations for textile and food processing effluent. National discharge regulations are tightening heavy metal limits for industrial clusters. Jakarta metropolitan water authorities are automating polymer feed systems to reduce operator-dependent overfeed in surface water clarification.
Asia-Pacific Water Treatment Chemicals Market Vendor Landscape
Integrated service-chemistry contracts dominate the current landscape as metropolitan utilities consolidate procurement. The vendor base separates into three tiers: multinational formulators with technical service networks, regional manufacturers with feedstock proximity, and specialized distributors serving fragmented industrial accounts. Two strategic archetypes are gaining share: outcome-guaranteed service integrators and feedstock-integrated regional producers. Competitive moves concentrate on long-term operator contracting and automated dosing system deployment.
Among multinational service integrators, Ecolab, Kemira, and Kurita Water Industries Ltd exemplify the integrated model. Ecolab anchors performance-guaranteed contracts with metropolitan water authorities. Kemira operates manufacturing scale in Australian and Southeast Asian hubs. Kurita Water Industries Ltd occupies a position emphasizing on-site technical service teams for power plant cooling circuits. These three represent divergent geographic emphases within the same service-chemistry archetype.
| Leading Market Players |
|---|
| Ecolab |
| Solenis |
| Kemira |
| Kurita Water Industries Ltd |
| Suez |
| BASF |
| Dow Chemical Company |
| Akzo Nobel NV |
| Thermax Limited |
| Others |
Supply Flow & Price Mechanics
Metropolitan water authorities in Sydney and Melbourne anchor procurement volume through integrated service-chemistry contracts, binding chemical supply to performance-guaranteed pricing models that specify maximum allowable cost per megalitre treated. This buyer concentration compresses transactional spot markets and elevates long-term operator contracting as the dominant commercial structure.
Pricing Analysis
Service-bundling separates integrated technical staffing contracts from unbundled bulk chemical transactions, with metropolitan utilities paying premium rates for on-site dosage optimization and guaranteed effluent quality. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and real-time dosing integration, with semiconductor fabs in South Korea's Pyeongtaek corridor absorbing premium sulfuric acid costs for etching effluent neutralization. Pricing pressure stems from bauxite and sulfuric acid feedstock volatility constraining margin stability for inorganic coagulant producers. Municipal utilities exhibit highest price sensitivity, while oil and gas operators in Indonesia's Rokan field accept premium biocide pricing for high-salinity formation water treatment.
Supply Chain Analysis
Workforce availability constraints in Australia's Queensland and Western Australia limit expansion of inorganic coagulant manufacturing capacity despite abundant bauxite deposits. Supply concentrates in China's Shandong and Jiangsu provinces for sulfuric acid production, India's Gujarat and Maharashtra corridors for pharmaceutical-grade formulations, and Japan's Kansai region for corrosion inhibitor blending. Raw material dependencies center on bauxite for aluminum salts, sulfuric acid for pH regulators, and acrylamide monomers for polymeric flocculants. Single-source vulnerability runs through China's sulfuric acid clusters feeding downstream formulation across the basin. Distribution runs through direct sales teams for municipal accounts and regional distributors penetrating Vietnam's Bac Ninh electronics corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated polymer make-down systems with integrated viscosity sensing are displacing manual dosing platforms across Southeast Asian municipal utilities, compressing the transition window for suppliers still anchored to fixed-dose protocols.
For Market Incumbents: To counter feedstock volatility eroding inorganic coagulant margins, Kemira and Ecolab should deepen backward integration into bauxite refining in Australian hubs while accelerating qualification of bio-based coagulant alternatives under China's provincial green procurement preferences. Capacity addition in Vietnam's Bac Ninh corridor captures electronics manufacturing pre-treatment expansion ahead of tightened provincial permits. For New Entrants and Emerging Players: Second-tier manufacturing provinces beyond Bangkok's direct sales radius present the most penetrable white-space, with Thai chemical distributors already bridging logistics gaps that multinational service integrators leave exposed. Batang and Karawang manufacturing corridors in Indonesia lack established chemical service infrastructure, creating first-mover advantage for on-site technical service deployment targeting textile and food processing effluent pre-treatment. For Investors and Strategic Acquirers: Distressed-cycle entries favor feedstock-integrated regional producers in Australian and Southeast Asian hubs with captive bauxite supply and established MEE registration portfolios. Long-term viability hinges on dual carbon alignment and automated dosing system deployment capability. The signal to watch is provincial environmental department permit structures in Vietnam modeling China's MEE framework, which would accelerate chemical feed system upgrade cycles and concentrate procurement among qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Captive feedstock supply in Queensland secures margin stability against sulfuric acid price swings. |
| Automated Polymer Make-Down System Deployment | Thailand's metropolitan water authorities pilot viscosity-sensing units to eliminate operator overfeed. |
| Bio-Based Coagulant Development | China's dual carbon goals incentivize provincial green procurement preferences for sustainable formulations. |
| On-Site Technical Service Expansion | Indonesia's Batang corridor lacks chemical service infrastructure, creating first-mover positioning. |
| MEE Registration Portfolio Alignment | Jiangsu and Zhejiang industrial parks demand pre-hydrolyzed aluminum variants under tightened discharge limits. |
Methodological Framework
Multi-period observation of chemical procurement volumes, regulatory enforcement timelines, and feedstock price movements anchored the trend analysis, supplemented by interviews with plant managers at municipal utilities, procurement leads at textile and electronics manufacturing clusters, distribution channel partners in Thailand and Indonesia, and technical R&D directors at polymeric flocculant formulators. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical companies, and provincial environmental department discharge permit databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the Asia-Pacific basin.
Input-output matrices mapped product chemistry grades to end-use applications and regional production hubs, with segmentation dimensions spanning coagulant and flocculant molecular weights, pH regulator purity tiers, industrial wastewater versus municipal application contexts, and direct sales versus distributor channel structures. CAGRs were derived from fitted growth curves applied to historical procurement trajectories and projected regulatory enforcement schedules. Forecast inputs included MEE discharge standard implementation timelines in China's Yangtze River Delta and CPCB zero-liquid-disclosure readiness deadlines in India's Tiruppur and Surat clusters.
Revisions become necessary when bauxite or sulfuric acid price volatility exceeds historical bands, when provincial environmental departments in Vietnam or Indonesia accelerate permit structures beyond modeled timelines, or when automated dosing technology adoption rates diverge from utility capital expenditure patterns. Material deviation in feedstock costs, regulatory enforcement speed, or technology substitution rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
North America Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Global Water Treatment Technology Market
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
Global Water Softeners Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market