
 Flocculants Market | 2026-2036
Flocculants Market Size, Share, and Industry Trends Forecast 2026-2036
Flocculants Market Analysis
REACH is broadening the cost-of-entry calculus for European flocculant suppliers by mandating extensive toxicity dossiers for polymer chemistries. SNF leverages its integrated acrylamide production to absorb compliance costs without outsourcing. Kemira Oyj anchors its position through deep R&D partnerships with Nordic pulp mills. BASF SE competes by controlling specialty monomer supply chains that feed high-molecular-weight flocculant grades.
Flocculants are water-soluble polymers, typically polyacrylamides or polyDADMACs with molecular weights ranging from 10^5 to 10^7 g/mol, that neutralize and bridge suspended particles to form settleable flocs for solid-liquid separation in industrial and municipal systems. Organic flocculants dominate value pools due to premium pricing on tailored charge densities, while biopolymer variants from chitosan and starch derivatives represent the fastest-growing structural pocket as food-grade and aquaculture applications expand. The mining end-user segment sustains outsized volume pull through tailings dewatering and process water recycling requirements.
EPA effluent guidelines in the United States, China's MEE discharge standards for industrial wastewater, and the EU Water Framework Directive collectively tighten permissible suspended solids limits and accelerate flocculant substitution for legacy alum and ferric salts. Product registration burdens favor suppliers with existing toxicology databases and regional formulation labs. Stakeholders must monitor how tightening polymer monomer residue limits reshape raw material sourcing and regional manufacturing footprints.
Market Dynamics
REACH compliance in Europe is forcing wholesale reformulation of polyacrylamide chains toward lower-toxicity architectures, while China's MEE discharge standards compress substitution timelines for legacy metal salts across the Yangtze River industrial corridor.
Growth Catalysts
- EPA Effluent Guidelines:The United States EPA's tightened suspended solids limits for industrial wastewater are accelerating flocculant substitution for alum and ferric salts in metal finishing and food processing facilities.
- Mining Tailings Dewatering:Copper and iron ore operations in Chile and Australia are scaling polymer flocculant volumes to meet water recycling mandates and dry-stack tailings requirements.
- Chitosan Biopolymer Maturation:Food-grade and aquaculture applications are pulling starch-derivative and chitosan-based flocculants into premium pricing tiers as marine-sourced alternatives gain regulatory acceptance.
Market Restraints
- Acrylamide Monomer Volatility:Propylene price swings and acrylonitrile supply tightness transmit directly to polyacrylamide production costs, squeezing margin buffers for non-integrated formulators.
- European Registration Burdens:REACH toxicity dossier requirements for polymer chains are extending product launch timelines and favoring incumbents with existing toxicology databases over new entrants.
- Alum Price Competitiveness:Legacy aluminum sulfate retains cost advantage in bulk municipal applications across price-sensitive Southeast Asian utilities, limiting organic flocculant penetration in primary clarification.
Strategic Opportunities
- Indonesia Municipal Expansion:Jakarta and Surabaya wastewater treatment upgrades are creating procurement windows for anionic and cationic polymer suppliers as urbanization intensifies discharge compliance pressure.
- EU Green Deal Procurement Incentives:Public tender scoring that rewards bio-based content and carbon footprint disclosure is opening preference margins for biopolymer flocculants in Nordic and German municipal systems.
- Digital Dosing Convergence:Real-time turbidity sensors and automated polymer feed systems are converging with flocculant supply contracts to create performance-guaranteed service models in pulp and paper mills.
Industry Challenges
- Polymer Chemist Talent Scarcity:Formulation expertise in high-molecular-weight polyacrylamide synthesis and charge-density tailoring is concentrating at a handful of regional technical centers, constraining R&D scaling.
- Legacy Dosing Infrastructure Retrofit:Municipal plants designed for alum or ferric salt feed systems face capital-intensive conversion to polymer-compatible make-down and injection equipment.
- Residual Monomer Certification Delays:Food-contact and potable-water approvals for acrylamide-based polymers require extended migration testing timelines that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flocculants Market |
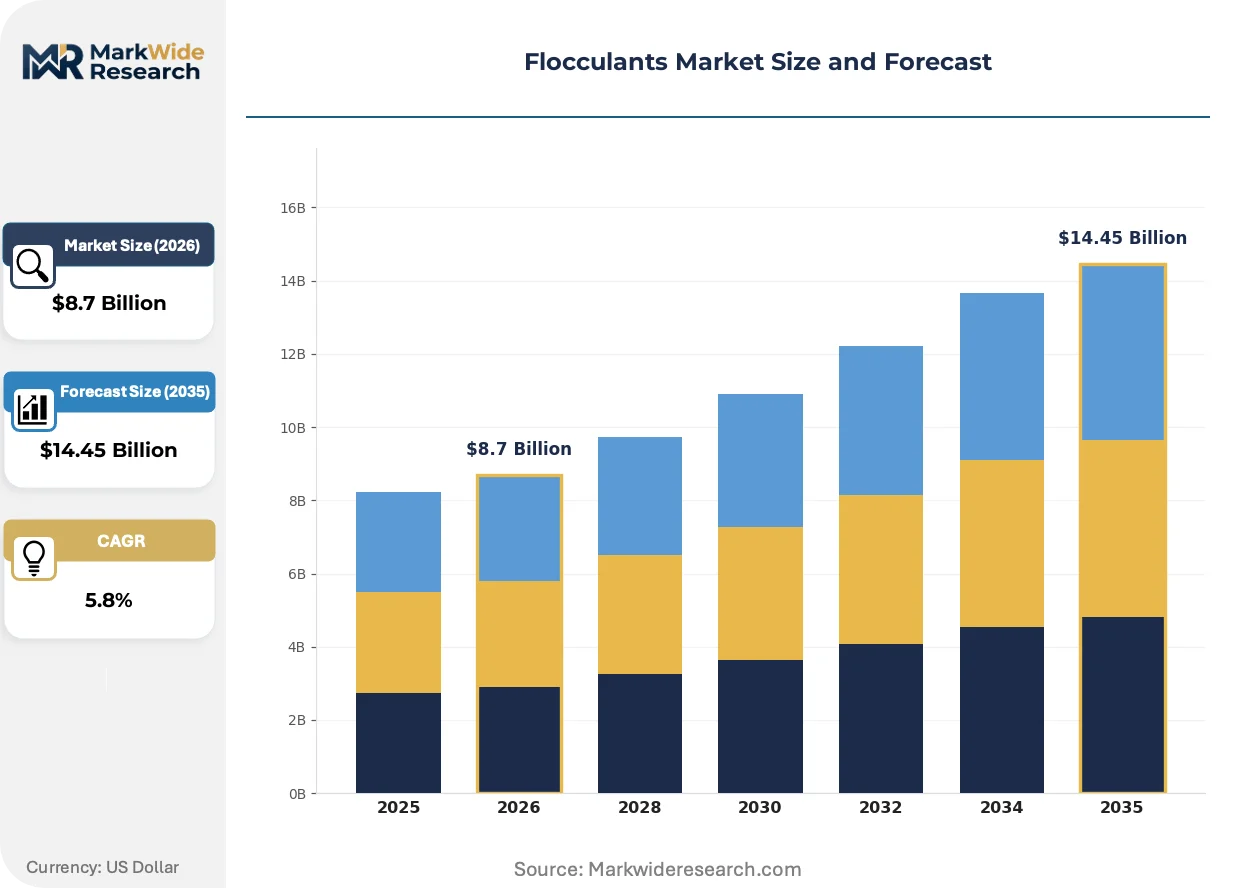
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Flocculants, Inorganic Flocculants, Synthetic Polymers, Biopolymer Flocculants End User: Water Treatment, Mining, Pulp & Paper, Oil & Gas Packaging Type: Bag, Drum, Bulk, Sachet Application: Clarification, Dewatering, Thickeners, Wastewater Treatment |
| Companies Covered | SNF, Kemira Oyj, BASF SE, Ecolab Inc., Solenis LLC, Solvay SA, Feralco AB, Kurita Water Industries Ltd., Ixom Operations Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flocculants Market Emerging Trajectories
Active polymer architectures are converging with sensor-driven process control to displace fixed-dose protocols, while regulatory chemistry restrictions and biopolymer maturation are reshaping raw material sourcing strategies across industrial water treatment.
Hybrid organic-inorganic flocculant systems are converging with zwitterionic polymer designs to bridge colloidal particles across broader pH ranges than single-charge alternatives. Mining operators in Western Australia and Chilean copper belts are piloting these architectures for high-salinity process water where conventional polyacrylamides lose efficacy. The technology is converging with vendor technical service capabilities to create site-specific formulation partnerships that lock out commodity suppliers.
China's MEE discharge standards for industrial wastewater are tightening total suspended solids and heavy metals limits ahead of prior compliance timelines. Chemical parks around Shanghai and Ningbo are retrofitting secondary and tertiary treatment trains with high-molecular-weight cationic flocculants to meet permit conditions. The policy shift is compressing substitution curves for metal salts in electronics manufacturing and textile dyeing clusters.
Performance-guaranteed supply contracts are displacing volume-based procurement in Nordic pulp mills and German automotive coating operations. Technical service bundling—encompassing jar testing, dosing optimization, and sludge characterization—is replacing spot polymer purchases in segments with high penalty costs for out-of-spec effluent. Finland and Sweden host the most advanced contract structures, with penalty-clause pricing tied to filtrate quality rather than kilograms delivered.
Flocculants Market Segmentation
Flocculant procurement decisions hinge on compatibility with legacy dosing infrastructure and the regulatory compliance trajectory of end-use facilities. Upgrade cycles vary sharply across municipal utilities, mining operations, and industrial clusters, reshaping how suppliers structure product portfolios and technical service bundles.
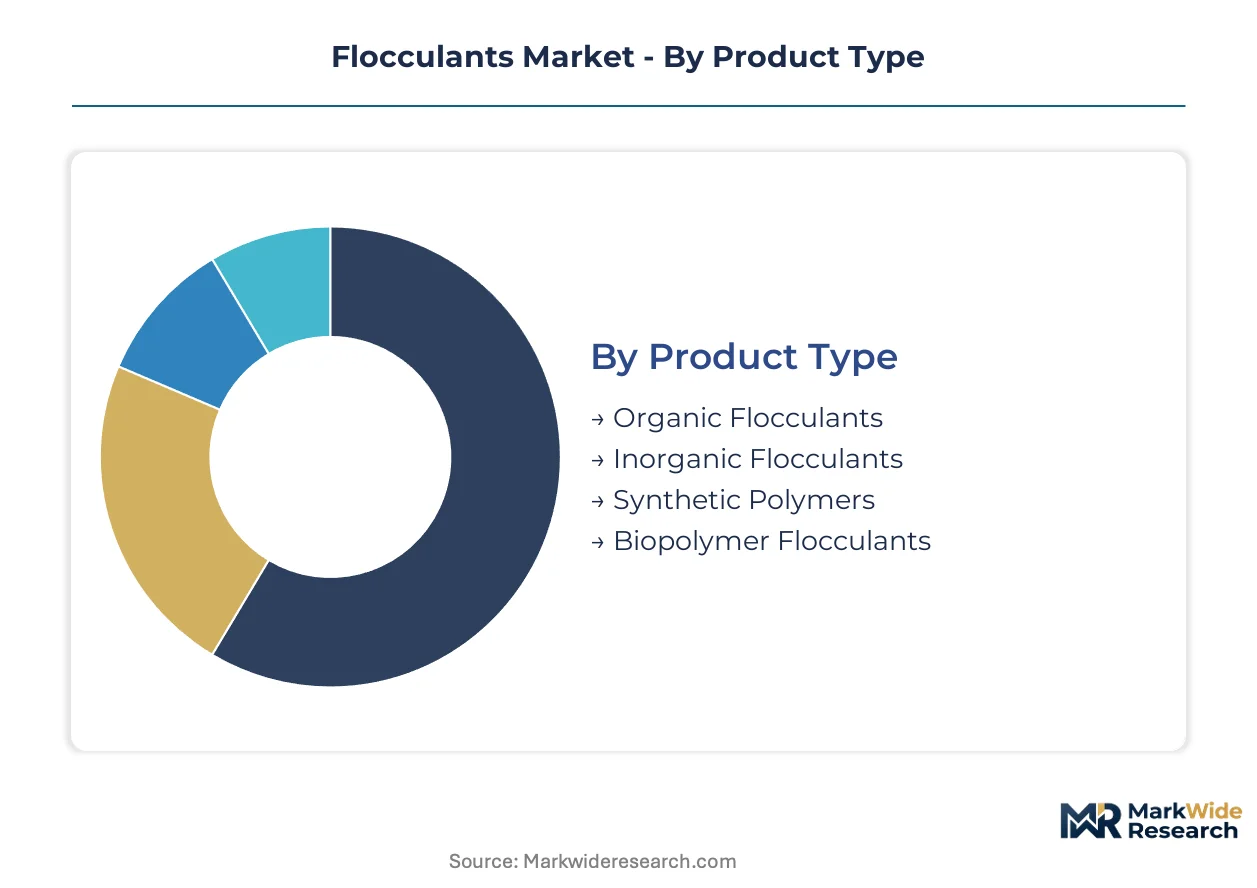
Product Type:
Replacement cycles for flocculant chemistries accelerate where REACH and MEE discharge standards force reformulation away from higher-toxicity polymer architectures.
- Organic Flocculants:Polyacrylamide and polyDADMAC chains with molecular weights spanning 10^5 to 10^7 g/mol dominate value capture through tailored charge densities. Mining tailings dewatering in Chile and municipal wastewater upgrades across Indonesia's Java corridor concentrate volume pull for high-molecular-weight anionic grades.
- Biopolymer Flocculants:Chitosan and starch-derivative architectures are displacing synthetic alternatives in food-grade and aquaculture applications where marine-sourced chemistries gain regulatory acceptance. Nordic pulp mills and German municipal systems award tender preference margins based on bio-based content scoring under EU Green Deal procurement frameworks.
- Inorganic Flocculants:Alum and ferric sulfate formulations retain cost advantage in bulk Southeast Asian municipal clarifiers despite compressing substitution timelines.
- Synthetic Polymers:Engineered copolymers with zwitterionic functionality serve high-salinity process water in Western Australian iron ore belts where conventional single-charge polymers degrade.
Organic flocculants sit at the top of the volume ranking, with biopolymer flocculants climbing the fastest.
End User:
Capital intensity and penalty structures for out-of-spec effluent reshape how end-user segments prioritize performance-guaranteed supply contracts over spot purchasing.
- Water Treatment:Municipal utilities across China's Yangtze River Delta and Indonesia's Surabaya corridor are retrofitting secondary treatment trains with cationic polymer systems to meet tightened suspended solids limits. Jar testing and dosing optimization services bundle with supply contracts where EPA and MEE discharge standards impose steep non-compliance penalties.
- Mining:Copper and iron ore operators in Chile and Australia scale polymer volumes for dry-stack tailings compliance and process water recycling mandates. Site-specific formulation partnerships with technical service capabilities lock out commodity suppliers in high-salinity process water applications.
- Pulp & Paper:Nordic mills in Finland and Sweden operate the most advanced performance-guaranteed contract structures, with penalty-clause pricing tied to filtrate quality rather than kilograms delivered.
- Oil & Gas:Produced water treatment and refinery effluent clarification drive demand for thermally stable polymer grades in high-TDS environments.
Water treatment commands the largest installed base, with mining expanding most quickly on tailings dewatering mandates.
Packaging Type:
Automation readiness and labor cost structures at receiving facilities determine packaging format selection and supplier logistics configurations.
- Bulk:Rail and pneumatic offloading systems serve high-volume mining operations and large municipal utilities with dedicated polymer make-down infrastructure.
- Drum:Steel and plastic drum formats dominate mid-scale industrial applications where batch processing and limited storage capacity constrain delivery economics.
- Bag:Multi-wall paper and woven polypropylene bags address smaller municipal plants and food processing facilities with manual handling protocols.
- Sachet:Pre-measured unit doses support remote mining camps and decentralized aquaculture operations lacking precision dosing equipment.
Bulk formats lead on tonnage throughput, with sachet gaining share fastest in decentralized treatment applications.
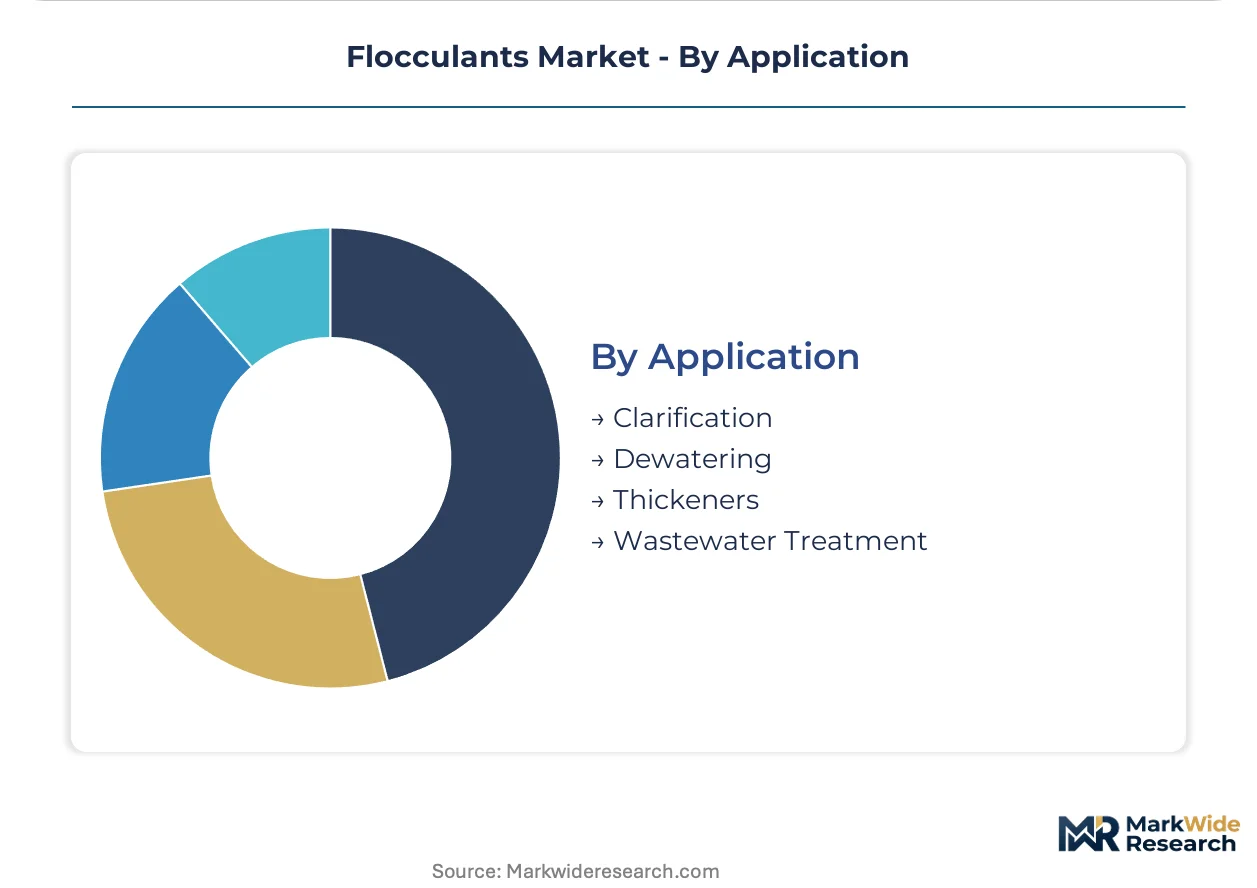
Application:
Process stage positioning and solids loading characteristics dictate polymer charge density, molecular weight, and dosing strategy specifications.
- Wastewater Treatment:Secondary and tertiary clarifier upgrades across China's electronics manufacturing clusters deploy high-molecular-weight cationic flocculants to meet MEE discharge standards for total suspended solids and heavy metals.
- Dewatering:Centrifuge and belt press optimization in pulp mills and mining operations demands rapid floc formation kinetics and high shear resistance to maximize cake solids content.
- Clarification:Primary settling and coagulation-aid applications in Southeast Asian utilities balance polymer cost against alum price competitiveness in bulk turbidity removal.
- Thickeners:High-rate thickener operations in mineral processing and tailings management require ultra-high molecular weight anionic polymers for rapid settling velocity.
Wastewater treatment anchors volume demand, with dewatering posting the steepest expansion trajectory on sludge disposal cost pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer formulation expertise concentrates in technical centers near major industrial water treatment corridors, with regulatory chemistry restrictions reshaping regional manufacturing footprints and raw material sourcing strategies.
China
Chemical parks around Shanghai and Ningbo retrofit secondary treatment trains with high-molecular-weight cationic flocculants to meet MEE discharge standards for total suspended solids. MEE tightened heavy metals limits ahead of prior compliance timelines. Electronics manufacturing clusters in the Yangtze River Delta compress substitution curves for metal salts in textile dyeing operations.
United States
EPA effluent guidelines accelerate flocculant substitution for alum and ferric salts in metal finishing and food processing facilities. The EPA tightened suspended solids limits for industrial wastewater discharge. Municipal utilities in the Great Lakes region upgrade clarifier infrastructure to accommodate polymer-compatible dosing systems.
Germany
REACH toxicity dossier requirements extend product launch timelines and favor incumbents with existing toxicology databases. ECHA mandates extensive dossiers for polymer chemistries under REACH compliance. Municipal systems in North Rhine-Westphalia award tender preference margins based on bio-based content scoring under EU Green Deal procurement frameworks.
Indonesia
Jakarta and Surabaya wastewater treatment upgrades create procurement windows for anionic and cationic polymer suppliers. Urbanization intensifies discharge compliance pressure across Java. Municipal utilities in Surabaya retrofit primary clarification infrastructure as alum price competitiveness limits organic flocculant penetration in bulk applications.
Australia
Iron ore operations in Western Australia pilot zwitterionic polymer designs for high-salinity process water where conventional polyacrylamides lose efficacy. Water recycling mandates drive dry-stack tailings compliance requirements. Mining camps in the Pilbara region test sachet-format pre-measured unit doses for decentralized treatment applications lacking precision dosing equipment.
Flocculants Market Vendor Landscape
The competitive structure tilts toward integrated polymer producers with captive acrylamide supply and regional formulation laboratories. Three archetypes dominate: backward-integrated petrochemical majors controlling specialty monomer supply chains; water treatment specialists bundling technical service with performance-guaranteed supply contracts; and regional formulators serving price-sensitive municipal segments with standard-grade polymers. Capacity expansion and site-specific formulation partnerships represent the dominant competitive moves, with M&A activity concentrating in biopolymer technology access.
Within the integrated producer tier, SNF leverages in-house acrylamide production to absorb REACH compliance costs without outsourcing raw material supply. Kemira Oyj anchors its competitive position through technical service capabilities and R&D partnerships with Nordic pulp mills. BASF SE exemplifies the petrochemical major archetype through control of specialty monomer supply chains feeding high-molecular-weight flocculant grades.
| Leading Market Players |
|---|
| SNF |
| Kemira Oyj |
| BASF SE |
| Ecolab Inc. |
| Solenis LLC |
| Solvay SA |
| Feralco AB |
| Kurita Water Industries Ltd. |
| Ixom Operations Pty Ltd. |
| Others |
Supply Flow & Price Mechanics
Performance-guaranteed procurement contracts in Nordic pulp mills and German automotive coating operations are forcing suppliers to bundle technical services with polymer volumes, compressing spot-market pricing for commodity-grade flocculants while elevating value-capture for integrated producers with jar-testing and dosing optimization capabilities.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the flocculant market. Three-tier pricing structure across premium, standard, and economy levels separates performance-guaranteed supply contracts with penalty-clause pricing from volume-based spot purchases and bulk alum alternatives. Price differentiation hinges on certification grade for food-contact and potable-water approvals and on after-sales technical service intensity. Pricing pressure stems from acrylamide monomer volatility transmitting propylene cost swings directly to non-integrated formulators. Municipal utilities across Southeast Asia exhibit highest price sensitivity, while mining operators with dry-stack tailings compliance mandates show lowest sensitivity due to penalty cost exposure.
Supply Chain Analysis
Freight cost differentials between bulk rail offloading and bagged manual handling reshape regional supplier competitiveness across decentralized treatment applications. Manufacturing concentration centers on China, the United States, and Germany, with formulation expertise clustering near the Yangtze River Delta, the Great Lakes region, and North Rhine-Westphalia. Raw material sourcing draws from acrylonitrile and propylene feedstocks for polyacrylamide synthesis, chitosan from marine processing byproducts, and starch derivatives from agricultural supply chains. Single-source vulnerability concentrates in acrylamide monomer supply where integrated producers hold structural advantage. Distribution runs through direct technical service partnerships for large mining and pulp accounts, with distributor networks serving fragmented municipal segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flocculant market functions as a regulatory compounder where successive tightening of EPA effluent guidelines, REACH toxicity dossier requirements, and China's MEE discharge standards accelerates substitution timelines and rewards suppliers with pre-existing compliance infrastructure.
For Market Incumbents: Lock in site-specific formulation partnerships with Chilean copper operators and Western Australian iron ore belts to preempt commodity substitution in high-salinity process water applications. Deepen captive acrylamide production to absorb REACH compliance costs without margin erosion from outsourced raw material exposure. Prioritize R&D investment in zwitterionic polymer architectures to defend technical service moats against emerging biopolymer competitors. For New Entrants and Emerging Players: Chitosan-based biopolymer maturation offers a technology-first wedge into Nordic municipal systems and German procurement frameworks where EU Green Deal bio-based content scoring creates tender preference margins. Target Indonesia's Surabaya and Jakarta wastewater upgrade corridors where urbanization intensifies discharge compliance pressure faster than incumbent technical service capacity can expand. Lead with pre-measured sachet formats for decentralized aquaculture and remote mining camps lacking precision dosing infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with biopolymer technology specialists possessing marine-sourced chemistry IP and existing food-contact approval pathways. The five-to-ten-year viability window favors acquisition targets with integrated formulation laboratories in the Yangtze River Delta or Nordic pulp mill partnerships rather than pure-play distributors. Monitor acrylamide monomer residue limit tightening as the inflection signal that would accelerate consolidation toward backward-integrated producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Monomer | Captive supply absorption of REACH compliance costs protects margin structures against propylene volatility. |
| Biopolymer Technology Acquisition | Marine-sourced chemistry IP unlocks EU Green Deal procurement preference margins in Nordic municipal systems. |
| Site-Specific Formulation Partnership | Technical service bundling with Chilean copper operators locks out commodity suppliers in high-salinity applications. |
| Digital Dosing Convergence Investment | Real-time turbidity sensor integration creates performance-guaranteed contract structures in pulp and paper mills. |
| Regional Formulation Laboratory Expansion | Proximity to Yangtze River Delta electronics clusters compresses response times for MEE compliance retrofit cycles. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with water treatment procurement managers, mining tailings engineers, pulp mill technical directors, and polymer formulation chemists were validated against secondary sources including EPA effluent guideline filings, ECHA REACH registration databases, MEE discharge standard notifications, and customs trade data for acrylamide and polyacrylamide imports. The approach triangulates consumption estimates across municipal utilities, mining operations, and industrial clusters against production capacity declarations from integrated manufacturers.
Historical trendline analysis across organic, biopolymer, inorganic, and synthetic polymer product categories established baseline growth patterns. The projection framework models demand across water treatment, mining, pulp and paper, and oil and gas end-use segments, with packaging format and application-stage dimensions layered in. CAGRs were derived from regression analysis of regulatory compliance timelines and substitution curve acceleration in electronics manufacturing and textile dyeing clusters. Forecast inputs include MEE enforcement intensity trajectories and EU Green Deal procurement scoring implementation pace.
The model holds under steady regulatory enforcement and acrylamide supply continuity; deviation in monomer price volatility spikes or sudden REACH restriction expansion would shift volume projections toward biopolymer alternatives. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Process Water Treatment Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Market