
 Automotive Regenerative Braking System Market | 2026-2036
Automotive Regenerative Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Regenerative Braking System Market Intelligence
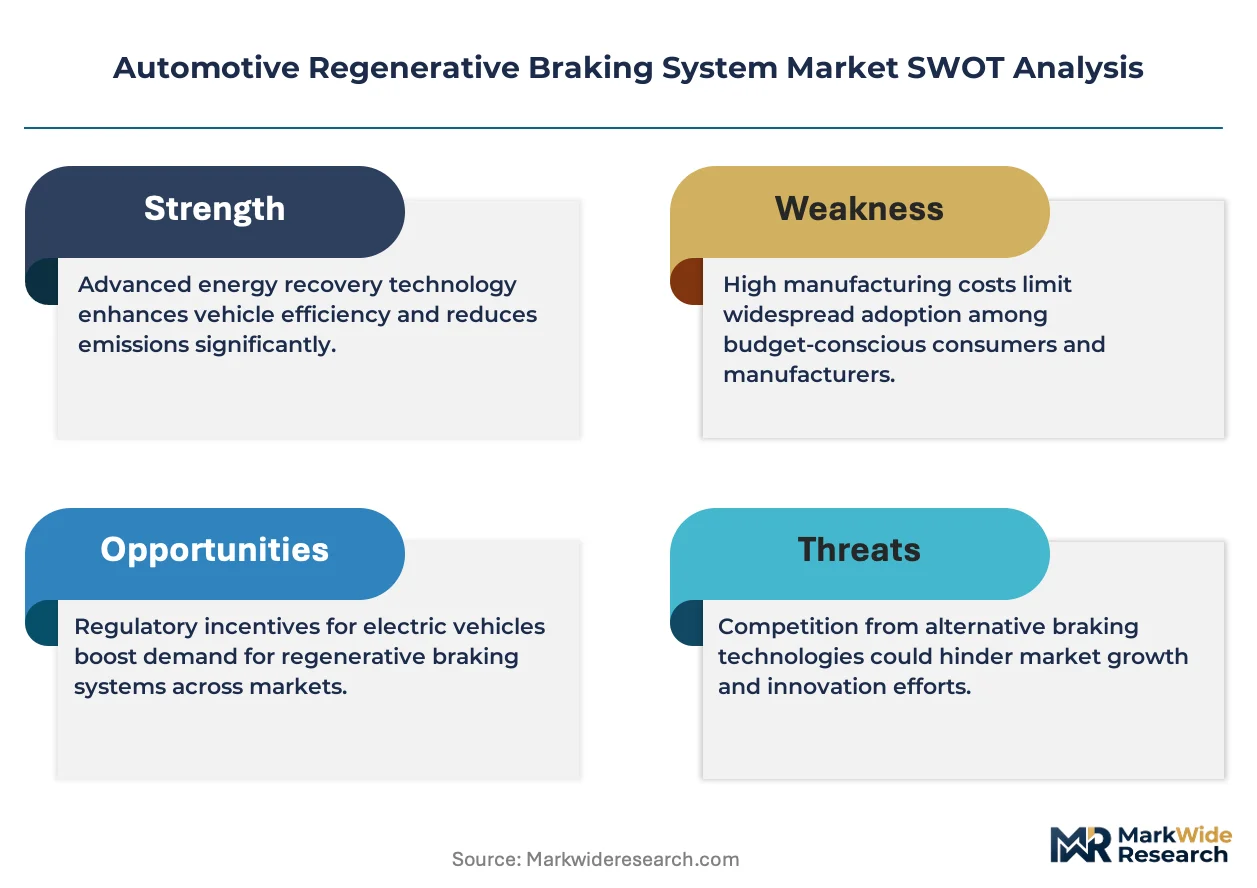
Project finance for battery-electric vehicle platforms is tilting procurement power toward fleet operators and shared-mobility providers rather than traditional retail buyers. Robert Bosch GmbH leverages its integrated powertrain division to bundle braking systems with e-axle modules. ZF Friedrichshafen AG anchors European supply through captive rotor manufacturing in Germany. Continental AG competes on brake-by-wire software stacks that merge regenerative and friction control.
An automotive regenerative braking system recaptures kinetic energy during deceleration and converts it into electrical energy through motor-generator units, typically achieving recovery efficiencies between sixty and seventy percent depending on duty cycle and battery state of charge. The technology primarily extends electric range and reduces mechanical brake wear in electrified vehicles. Electric product types dominate volume as full-electric architectures eliminate vacuum-dependent components, while plug-in hybrid applications represent the fastest-expanding category as transitional powertrains proliferate. Multi-stage energy recovery systems command premium positioning by optimizing capture across varied speed profiles.
The EPA enforces fleet-average emissions standards that effectively mandate regenerative braking adoption for compliance in light-duty segments. NHTSA safety protocols govern brake-system failure modes and pedal-feel consistency during blended regenerative-friction events. The EU Green Deal and F-Gas Regulation indirectly strengthen demand by accelerating phase-out of internal-combustion platforms where conventional vacuum assist remains standard. Stakeholders must monitor how battery chemistry improvements alter energy-recovery rate specifications and whether aftermarket retrofit regulations open parallel channel opportunities.
Market Dynamics
Fleet electrification mandates from California's Advanced Clean Trucks regulation and China's MIIT dual carbon targets are compressing OEM integration timelines, forcing regenerative braking hardware into platform architectures before full powertrain validation cycles complete.
Growth Catalysts
- EPA Fleet-Average Standards:Light-duty emissions ceilings functionally require regenerative energy recovery for compliance, embedding the technology in mass-market vehicle architectures.
- Brake-by-Wire Convergence:Electronic pedal interfaces eliminate vacuum dependency and enable seamless blending between recuperative and friction braking modes.
- China Production Scaling:Domestic electrified platform output concentrates regenerative braking procurement volumes around tier-one motor-generator suppliers.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings in motor-generator units compress supplier margins and destabilize long-term contracting.
- Single-Source Rotor Supply:Captive German manufacturing for high-speed rotor assemblies creates geographic concentration risk for European OEMs.
- Battery State-of-Charge Limitations:Near-full battery conditions disable energy recovery, forcing friction-only braking and accelerating pad wear.
Strategic Opportunities
- Aftermarket Retrofit Channels:California Air Resources Board certification pathways for hybrid conversion kits could open parallel revenue streams outside OEM supply.
- Multi-Speed Recovery Optimization:Variable-speed motor-generator architectures capture kinetic energy across urban stop-and-go and highway deceleration profiles.
- EU Green Deal Acceleration:Fleet CO2 mandates strengthen demand for plug-in hybrid transitional powertrains with integrated recuperative systems.
Industry Challenges
- Embedded Software Talent Scarcity:Brake-by-wire control algorithm development requires rare cross-functional expertise spanning functional safety and motor control.
- ISO 26262 Certification Timelines:ASIL-D validation for safety-critical braking software extends development cycles and delays platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Regenerative Braking System Market |
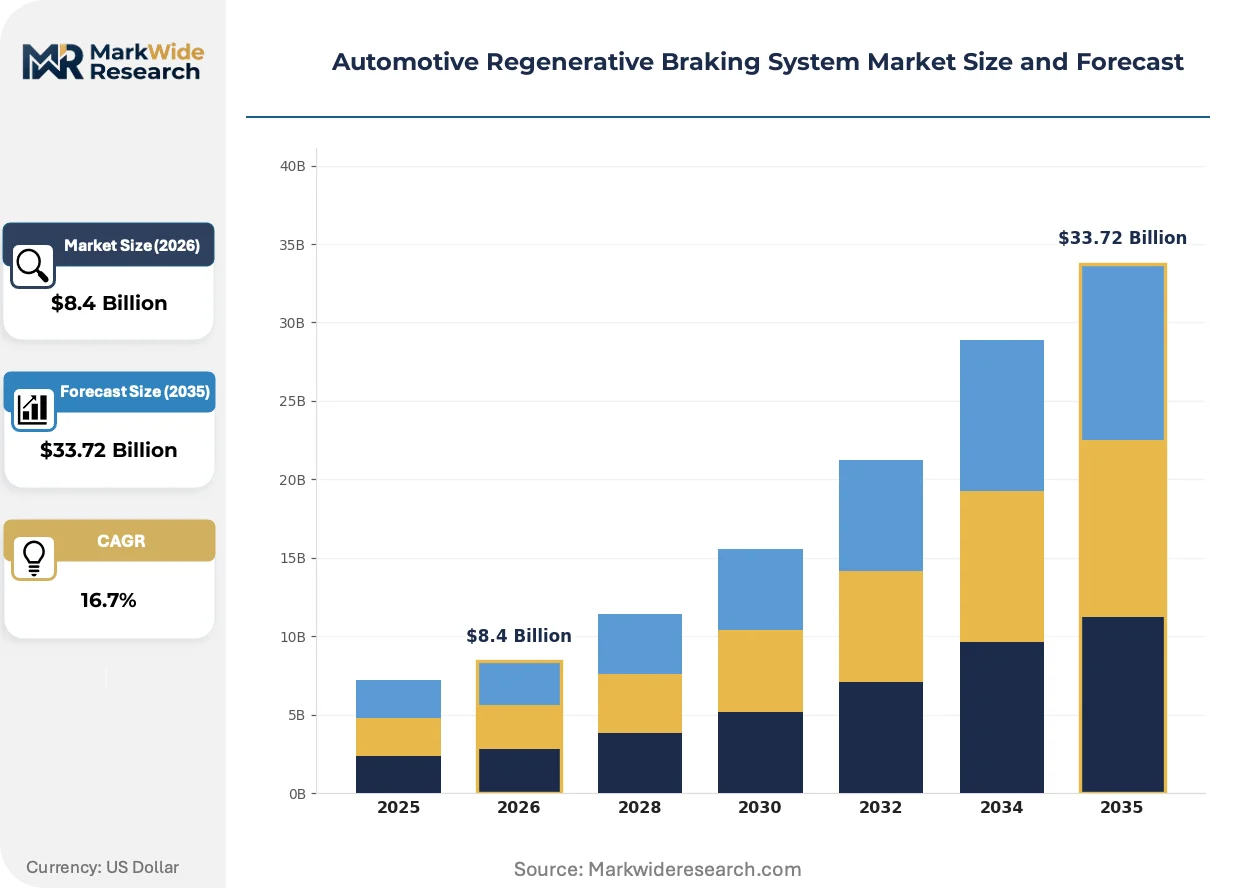
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electro-Hydraulic, Electric, Electro-Mechanical, Vacuum-Assisted Application: Electric Vehicles, Hybrid Electric Vehicles, Plug-in Hybrid Vehicles, Light Commercial Vehicles End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers Technology: Single-Stage, Multi-Stage, Brake Energy Recovery, Kinetic Energy Recovery |
| Companies Covered | Denso Corporation, Eaton Corporation, Robert Bosch GmbH, Hyundai Mobis, Aisin Seiki Co., Ltd., ZF Friedrichshafen AG, BorgWarner Inc., Mazda Motor Corporation, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Regenerative Braking System Market Strategic Shifts & Innovations
Software-defined braking architectures are displacing mechanical linkages as the primary value layer, with code-intensive control systems commanding larger procurement budgets than hardware assemblies.
Brake-by-wire platforms are virtualizing the traditional hydraulic circuit, replacing fluid pressure modulation with electromechanical actuators and sensor fusion algorithms. Full-electric OEMs are adopting these architectures at scale for weight reduction and packaging flexibility. The technology is virtualizing supplier value capture toward software stacks and away from foundry and casting operations.
The EU F-Gas Regulation is accelerating phase-out of internal-combustion platforms where vacuum-assisted braking remains standard, indirectly mandating electrified brake systems. OEMs are responding by pre-integrating regenerative hardware into modular skateboard architectures. Plug-in hybrid segments face the steepest compliance compression as transitional powertrains must satisfy dual efficiency and emissions frameworks.
Fleet operators are consolidating procurement decisions away from retail channel influence, centralizing regenerative braking specifications through multi-year platform agreements. Shared-mobility providers and logistics aggregators now dictate brake-system duty cycle requirements based on utilization intensity data. This concentration is most visible in California and Germany where electrified commercial fleet deployment leads consumer adoption curves.
Automotive Regenerative Braking System Market Segmentation
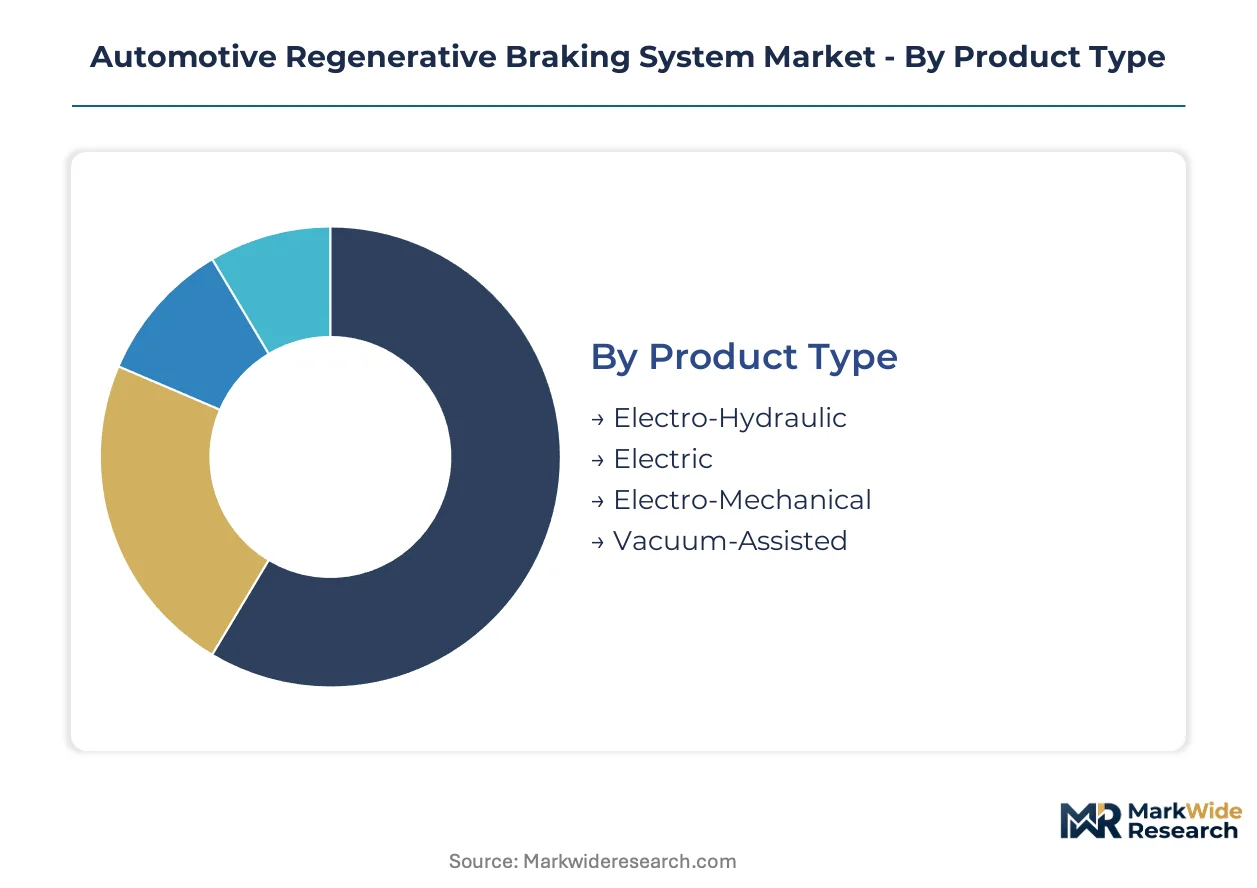
Segmentation in automotive regenerative braking systems reveals how hardware specifications, software architectures, and service lifecycle requirements diverge across electrified powertrain platforms. Procurement patterns vary sharply between OEM captive production and aftermarket retrofit channels, with brake-by-wire integration creating new margin pools in embedded control systems.
Product Type:
After-sales service intensity varies dramatically across product architectures, with fully electric systems requiring minimal friction brake maintenance while electro-hydraulic hybrids demand dual-system servicing protocols.
- Electric:Eliminates vacuum-dependent components entirely through motor-generator torque modulation, achieving the highest energy recovery efficiency in full-electric architectures. Demand concentrates in China where domestic OEMs scale skateboard platforms with integrated e-axle modules, driven by MIIT dual carbon compliance deadlines compressing development cycles.
- Electro-Hydraulic:Blends hydraulic friction braking with electric motor-generator recovery, preserving familiar pedal feel during transitional powertrain adoption. Procurement clusters around German premium OEMs navigating EU CO2 fleet mandates while maintaining driver experience consistency across hybrid lineups.
- Electro-Mechanical:Deploys electromechanical actuators replacing hydraulic circuits entirely, reducing weight and packaging constraints. ZF Friedrichshafen AG anchors European supply through captive rotor manufacturing.
- Vacuum-Assisted:Relies on internal combustion engine vacuum for brake boost, limiting applicability to conventional hybrid architectures. F-Gas Regulation phase-out timelines are compressing residual demand.
Electric holds the largest share; momentum sits with electro-hydraulic as plug-in hybrid volumes climb fastest.
Application:
Cost tier stratification separates premium full-electric platforms from mass-market transitional powertrains, with brake system specifications tracking battery capacity and duty cycle intensity.
- Plug-in Hybrid Vehicles:Transitional architectures must satisfy dual efficiency and emissions frameworks, creating complex blended braking calibration requirements. California fleet operators specify these systems for Advanced Clean Trucks compliance, with shared-mobility providers centralizing procurement through multi-year platform agreements.
- Electric Vehicles:Native high-voltage architectures enable maximum recuperative energy capture without friction brake dependency for routine deceleration. Production scaling in China concentrates procurement volumes around tier-one motor-generator suppliers.
- Hybrid Electric Vehicles:Conventional hybrid systems with limited electric range require conservative regenerative braking strategies to preserve battery longevity.
- Light Commercial Vehicles:Duty cycle intensity from urban delivery routes accelerates brake wear, intensifying demand for recuperative systems that extend service intervals.
Electric vehicles command premium positioning; plug-in hybrids are expanding most quickly as OEMs bridge compliance gaps.
End User:
Customer type determines specification authority, with fleet operators increasingly dictating brake-system duty cycle requirements based on utilization intensity data rather than retail channel preferences.
- OEMs:Captive integration teams specify regenerative braking hardware during platform architecture definition, locking suppliers into multi-year e-axle bundling arrangements. EPA fleet-average standards functionally mandate regenerative energy recovery for light-duty compliance, embedding technology in mass-market architectures.
- Tier-1 Suppliers:Modular subsystem providers compete on brake-by-wire software stacks that merge regenerative and friction control, with Robert Bosch GmbH leveraging integrated powertrain divisions.
- Vehicle Assemblers:Contract manufacturers rely on supplier-designed braking modules with limited customization scope.
- Aftermarket Providers:California Air Resources Board certification pathways for hybrid conversion kits could open parallel revenue streams outside OEM supply chains.
OEMs dominate procurement volume; aftermarket providers hold emerging channel potential.
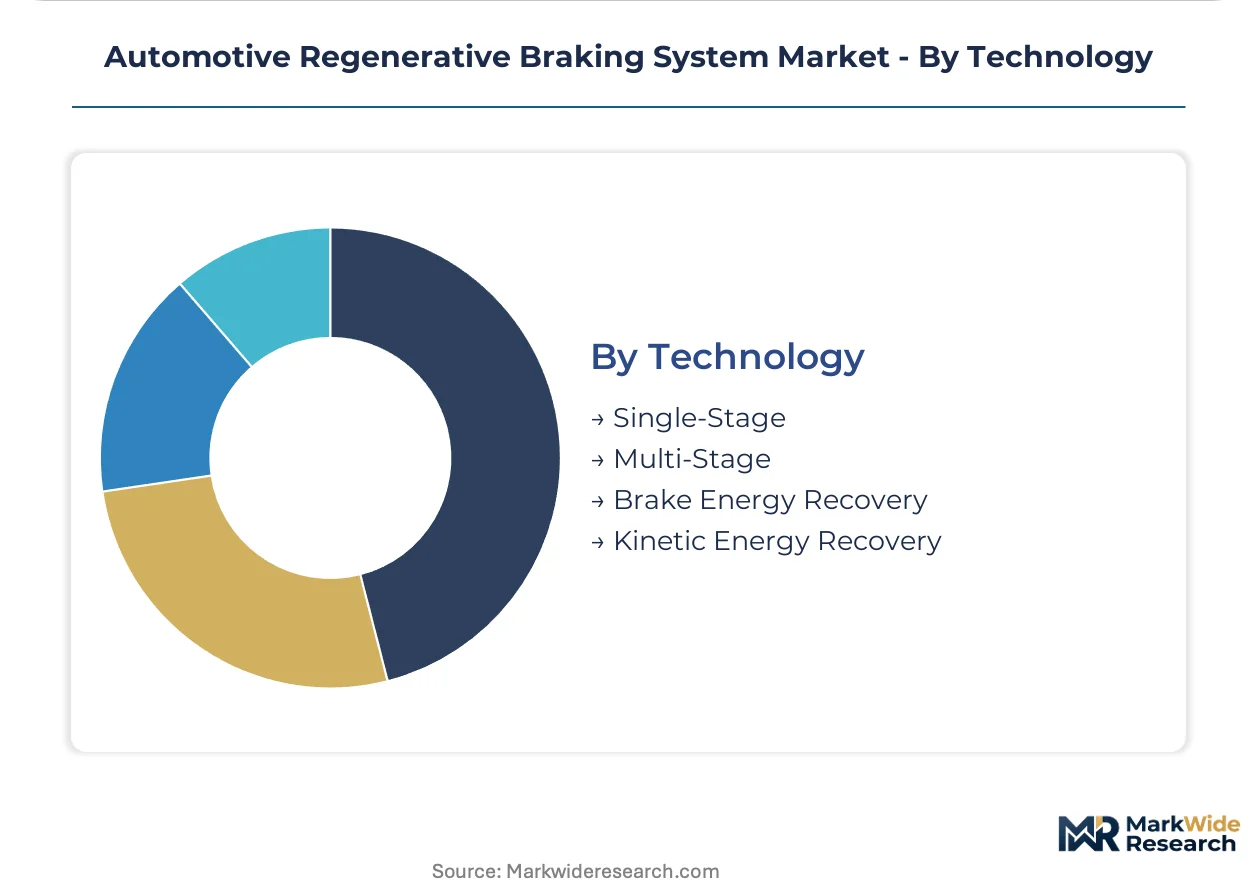
Technology:
Supply concentration in motor-generator manufacturing and embedded software development creates divergent margin structures across technology tiers.
- Multi-Stage:Variable-speed motor-generator architectures optimize energy capture across urban stop-and-go and highway deceleration profiles through dynamic switching between recovery modes. German engineering centers lead development, with KBA certification requirements extending validation timelines.
- Brake Energy Recovery:Software-intensive control systems virtualize traditional hydraulic circuits, replacing fluid pressure modulation with sensor fusion algorithms. ISO 26262 ASIL-D validation requirements compress supplier margins while extending development cycles.
- Single-Stage:Fixed-ratio recovery systems dominate economy segments with limited speed-range optimization.
- Kinetic Energy Recovery:Flywheel-based mechanical storage alternatives serve niche motorsport and heavy-duty applications outside mainstream electrification.
Multi-stage systems capture premium positioning; brake energy recovery is gaining share fastest as software-defined architectures displace mechanical value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where OEM captive manufacturing commands premium positioning, while Chinese suppliers compete on motor-generator volume scale with compressed margins. This asymmetry shapes procurement negotiations across electrified platform development cycles.
China
Domestic OEMs scale skateboard architectures with integrated e-axle modules, compressing supplier qualification timelines. MIIT dual carbon targets mandate fleet electrification percentages that embed regenerative braking in mass-market vehicles. Production clusters in the Yangtze River Delta around Shanghai concentrate tier-one motor-generator procurement volumes.
Germany
Premium OEMs navigate EU CO2 fleet mandates while maintaining driver experience consistency across hybrid lineups. KBA certification requirements extend validation timelines for brake-by-wire software stacks. Engineering centers in Stuttgart and Munich anchor development of multi-stage energy recovery systems.
United States
California fleet operators specify regenerative braking systems for Advanced Clean Trucks compliance, with shared-mobility providers centralizing procurement decisions. EPA fleet-average emissions standards functionally mandate energy recovery technology in light-duty segments. The San Francisco Bay Area hosts development clusters for brake-by-wire control algorithms.
Japan
Established hybrid architectures from domestic OEMs create conservative regenerative braking strategies prioritizing battery longevity over maximum recovery. METI carbon neutrality roadmaps accelerate full-electric platform transitions. Manufacturing clusters in Aichi Prefecture around Toyota City maintain electro-hydraulic system production.
South Korea
Battery-electric platform investments from domestic conglomerates drive integrated powertrain bundling arrangements. MFDS automotive safety standards govern brake-system failure mode validation for export markets. The Seoul Capital Area concentrates R&D facilities for motor-generator control software.
Automotive Regenerative Braking System Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in rotor manufacturing and magnetic materials. The vendor base organizes around three strategic archetypes: diversified automotive suppliers with powertrain integration capabilities, pure-play braking system specialists, and captive OEM in-house divisions. Consolidation pressure intensifies as brake-by-wire architectures virtualize hardware value toward software stacks. Dominant competitive moves include strategic partnerships for e-axle bundling and geographic expansion into Chinese production clusters.
Within the diversified supplier tier, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify platform integrators leveraging powertrain divisions for system-level positioning. Continental AG occupies a position among braking specialists competing on software-defined architectures. These three European-based entities anchor competitive dynamics as brake-by-wire convergence displaces mechanical value capture toward embedded control systems.
| Leading Market Players |
|---|
| Denso Corporation |
| Eaton Corporation |
| Robert Bosch GmbH |
| Hyundai Mobis |
| Aisin Seiki Co., Ltd. |
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| Mazda Motor Corporation |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese motor-generator manufacturing is compressing supplier margins while concentrating procurement leverage with domestic OEMs scaling skateboard platforms. This utilization imbalance forces tier-one suppliers to absorb rare earth magnet volatility and extend payment terms to defend volume positions.
Pricing Analysis
Configured-to-order pricing for multi-stage energy recovery systems commands a substantial premium over standard single-stage configurations, with brake-by-wire software stacks adding further differentiation. Pricing stratifies across premium, standard, and economy tiers based on ASIL-D certification status and e-axle bundling arrangements. Cost compression in electro-hydraulic systems is intensifying because German captive rotor manufacturing limits alternative sourcing. Fleet operators exhibit the lowest price sensitivity due to total-cost-of-ownership framing, while aftermarket retrofit channels remain highly elastic.
Supply Chain Analysis
Neodymium and dysprosium feedstock from Chinese rare earth processors anchors motor-generator cost structures, with German high-speed rotor machining and South Korean control software completing the value chain. The supply chain draws from magnet alloy foundries in Inner Mongolia, precision manufacturing clusters in Baden-Württemberg, and semiconductor packaging facilities in Gyeonggi Province. Single-source vulnerability in German rotor assemblies creates geographic concentration risk for European OEMs. Distribution runs through tier-one subsystem bundling directly to OEM platform integration teams, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by fleet electrification mandate acceleration, with California's Advanced Clean Trucks regulation and China's MIIT dual carbon targets compressing OEM integration timelines.
For Market Incumbents: Insulate margin positions by deepening captive rotor manufacturing in Germany and securing long-term rare earth offtake agreements with Chinese processors. Brake-by-wire software talent scarcity threatens competitive positioning; prioritize ASIL-D certification pipeline investment to accelerate platform launch timelines.
For New Entrants and Emerging Players: Southeast Asian aftermarket retrofit channels offer underpenetrated white-space opportunity as California Air Resources Board certification pathways mature. Target hybrid conversion kit segments with modular electro-hydraulic architectures that preserve familiar pedal feel. Establish direct fleet operator relationships through utilization-intensity data partnerships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among brake-by-wire software specialists with embedded control algorithm portfolios. Long-term viability centers on platform standardization across multiple OEM customers rather than single-source dependencies. Monitor battery chemistry improvements as the critical inflection signal for energy-recovery rate specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces validation overhead for OEMs integrating regenerative braking across multiple vehicle architectures. |
| Battery Supply Agreement | Secures cell capacity for motor-generator system testing and calibration under varied state-of-charge conditions. |
| Software-Defined Vehicle Investment | Positions suppliers to capture value migration from hydraulic hardware toward brake-by-wire control algorithms. |
| Geographic Manufacturing Footprint | Expands rotor machining capacity in China to offset German single-source concentration risk. |
| Charging Infrastructure Partnership | Aligns regenerative braking duty cycle optimization with DC fast-charging network utilization patterns. |
Research Approach
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement directors, aftermarket distributors, and fleet operations managers anchored the qualitative base. Primary interviews combined with secondary validation from EPA fleet compliance filings, MIIT production authorization databases, vehicle registration data, and customs trade records. Bottom-up unit economics triangulated against top-down market sizing across propulsion architectures.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from fitted growth curves applied to electrification penetration trajectories. Forecast inputs incorporated brake-by-wire adoption curves and rare earth price elasticity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese motor-generator specialists would shift outcomes. Material shifts in EU F-Gas Regulation phase-out timelines or NHTSA brake-system safety protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Automotive Glass Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Automotive Braking Component Market
Automotive Components
Global Automotive Gears Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Automotive Ignition Box Market
Automotive Components
Automotive Carbon Fiber Components Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market