
 Germany Automotive Carbon Fiber Composites Market | 2026-2036
Germany Automotive Carbon Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Carbon Fiber Composites Market Foresight
High-pressure resin transfer molding automation is reshaping how German automakers integrate carbon fiber into series production. SGL Carbon SE leverages its vertical integration from precursor to finished component to dominate supply to premium OEM programs. Toray Industries, Inc. anchors its position through sustained R&D partnerships with German engineering centers. BMW AG differentiates by operating one of Europe's most advanced carbon fiber pilot lines for electric vehicle architectures.
Automotive carbon fiber composites are fiber-reinforced polymer systems typically comprising polyacrylonitrile-derived carbon fibers embedded in thermoset epoxy or thermoplastic matrices, engineered to achieve specific strength-to-weight ratios exceeding steel by factors of four to five while reducing mass sixty to seventy percent. Their primary commercial purpose centers on structural load-bearing and crash-energy management applications where every kilogram removed extends electric vehicle range or improves internal combustion efficiency. Prepreg formats currently lead value capture due to controlled resin content and handling consistency demanded by German OEM qualification protocols, while chopped fiber compounds represent the fastest-growing format as automakers seek lower-cost entry points for non-structural interior and semi-structural reinforcement applications. Body panel components concentrate margin pools because Class-A surface finish requirements and paint-line compatibility demand specialized tooling and process control that few suppliers master.
KBA type-approval procedures enforce crash-performance and material-traceability standards that filter out non-compliant composite suppliers from German vehicle programs. REACH chemical registration through ECHA governs resin system formulations and workplace exposure limits across production facilities. The EU Green Deal carbon-border adjustment mechanism and national end-of-life vehicle directives are forcing recyclability planning into composite design specifications from concept phase forward. Stakeholders must monitor how thermoplastic matrix advances and pyrolysis recycling scale-up alter qualification timelines and supplier qualification criteria.
Market Dynamics
High-pressure resin transfer molding automation is compressing cycle times and forcing tier-one suppliers to retool or exit German automotive carbon fiber programs. The EU Green Deal's carbon-border adjustment mechanism is embedding recyclability requirements into every new composite specification from concept phase.
Growth Catalysts
- EU Green Deal carbon-border mechanism:German OEMs now specify end-of-life recyclability in RFQs, accelerating thermoplastic matrix adoption for easier reprocessing.
- Electric vehicle architecture redesign:Battery pack enclosures and structural battery housings demand mass reduction that only carbon fiber delivers at scale.
- Bavaria manufacturing corridor concentration:Munich-Ingolstadt supplier clustering reduces logistics costs and enables just-in-sequence delivery to Audi and BMW assembly plants.
Market Restraints
- Polyacrylonitrile precursor cost volatility:Oil-indexed acrylonitrile prices swing composite raw material costs by double-digit percentages quarterly.
- Single-source supply concentration:Japanese and German precursor producers control over eighty percent of aerospace-grade carbon fiber feedstock.
- Thermoset recycling technical limitation:Pyrolysis energy intensity and fiber length degradation prevent closed-loop material recovery at commercial scale.
Strategic Opportunities
- Lower Saxony wind energy crossover:Blade manufacturing expertise in rotor blade preforming transfers directly to automotive structural member production.
- Chopped fiber thermoplastic compounds:Non-structural interior panels and seat frames offer volume entry points below Class-A surface finish cost barriers.
- KBA type-approval streamlining:Harmonized crash-test protocols for composite-intensive vehicle architectures reduce duplicate certification costs.
Industry Challenges
- Autoclave technician scarcity:German vocational programs graduate fewer than two hundred qualified composite process engineers annually.
- REACH chemical re-registration:ECHA's 2023 substance evaluation wave forces reformulation of legacy epoxy hardener systems mid-program.
- Paint-line integration complexity:Carbon fiber's coefficient of thermal expansion mismatch with steel requires dedicated oven profiling and robotic path reprogramming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Carbon Fiber Composites Market |
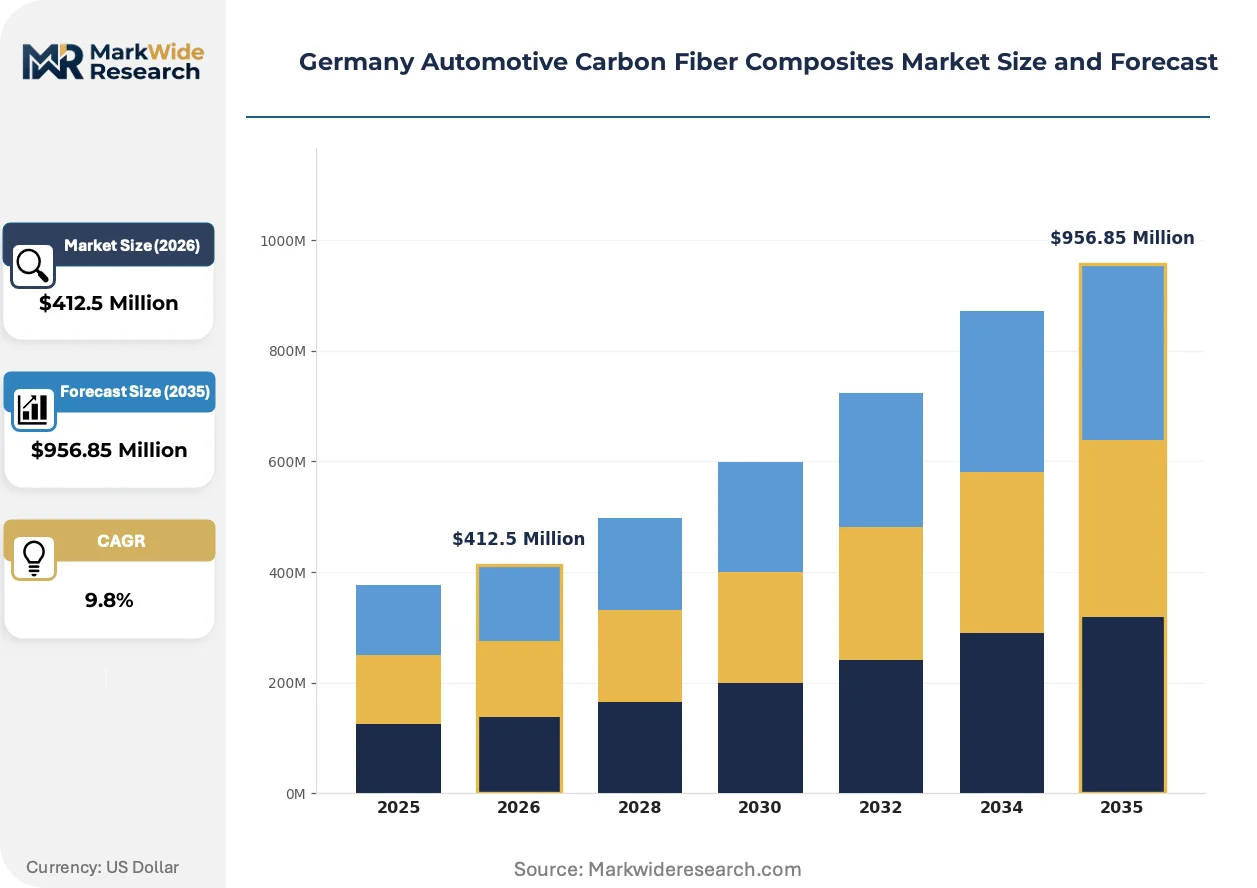
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $956.85 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepreg, Chopped Fiber, Woven Fabric, Pultruded Rod Component: Body Panels, Structural Frames, Interior Panels, Reinforcements Application: Lightweight Structures, Crash Impact Parts, Thermal Management, Aerodynamic Enhancements End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | SGL Carbon SE, Toray Industries, Inc., Teijin Limited, Hexcel Corporation, Solvay Group, BASF SE, BMW AG, Voith GmbH & Co. KGaA, Muhr und Bender KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Carbon Fiber Composites Market Shifts & Advancements
Digital thread technologies are collapsing the design-to-production timeline for composite components. Virtual qualification and simulation-first engineering are displacing physical prototype iterations.
Digital twin platforms for autoclave cure cycle optimization are virtualizing thermal management and residual stress prediction. BMW and Porsche engineering centers deploy these tools to reduce first-article qualification from eighteen months to under six. The technology is virtualizing capital allocation decisions by enabling remote supplier qualification without physical tool transfer.
REACH chemical registration through ECHA is forcing systematic substitution of bisphenol-A based epoxy systems. German compounders now reformulate with bio-based alternatives to maintain market access. Prepreg suppliers serving Munich-area OEMs face the steepest compliance timelines as 2025 substance restriction deadlines approach.
Automakers now unbundle composite component supply from system integrator contracts. Direct sourcing from SGL Carbon and Toray eliminates tier-one markup but transfers inventory risk to OEM balance sheets. Bavaria-based procurement teams lead this restructuring, consolidating spend across electric vehicle skateboard platforms.
Germany Automotive Carbon Fiber Composites Market Segmentation
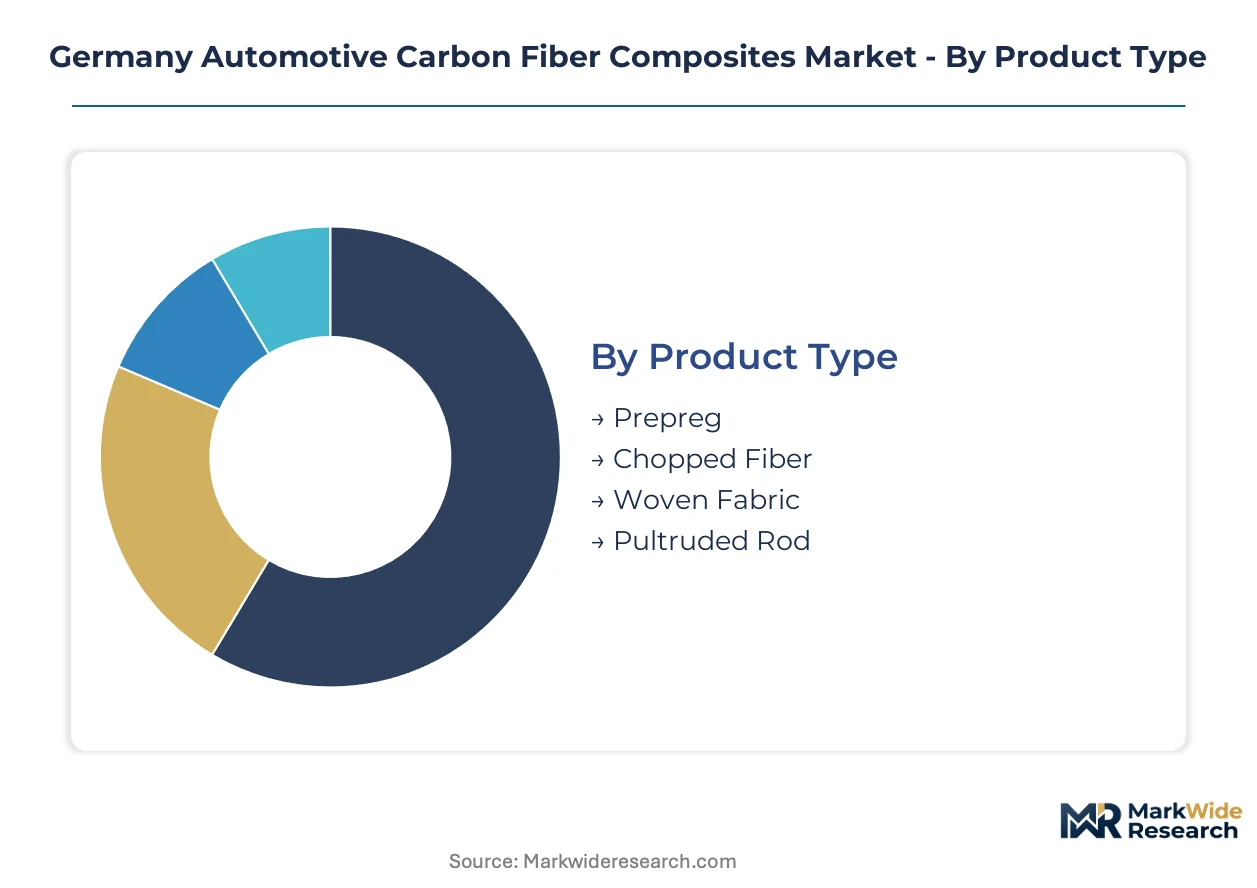
German OEM qualification protocols fragment the carbon fiber supply base by format compatibility and process certification. Each segment carries distinct margin profiles and technical barriers that shape supplier selection for electric vehicle platforms.
Product Type:
Mature formats dominate current qualification pipelines while emerging formats unlock cost-down pathways for volume segments.
- Prepreg:Resin-impregnated carbon fiber sheets with controlled fiber volume fraction enable precise layup automation for Class-A body panels. Audi and BMW specify prepreg for roof structures and hood assemblies where paint-line compatibility demands thermal expansion matching.
- Chopped Fiber:Short-cut carbon fibers dispersed in thermoplastic matrices suit injection molding of complex geometries. Bavarian Tier-1 suppliers deploy chopped fiber compounds for seat frames and battery module brackets where cycle time compression outweighs modulus requirements.
- Woven Fabric:Bidirectional and multiaxial weaves provide balanced in-plane properties for structural members.
- Pultruded Rod:Continuous profiles with unidirectional fiber alignment serve beam and stiffener applications.
Prepreg handles the majority of throughput; chopped fiber is the fastest mover on share.
Component:
Cost tier stratification separates premium surface-critical parts from hidden structural reinforcements.
- Body Panels:Exterior closures demand Class-A surface finish, dimensional stability through electrocoat bake cycles, and robotic paint-line compatibility. Munich-area OEMs concentrate body panel procurement among three qualified suppliers due to tooling amortization requirements.
- Structural Frames:Load-bearing chassis members and battery enclosures require crush-energy management certification under KBA protocols. Ingolstadt engineering centers validate structural frames through physical crash corridors before series release.
- Interior Panels:Decorative and functional cabin surfaces prioritize acoustic damping and thermal insulation over mechanical loading.
- Reinforcements:Localized stiffness inserts and patch reinforcements address stress concentration points without full component replacement.
Body panels capture the steepest margin premiums; structural frames are expanding most quickly as electric vehicle skateboard architectures proliferate.
Application:
Volume concentration clusters where mass reduction translates directly to range extension or emissions compliance.
- Lightweight Structures:Primary load paths including roof bows, floor pans, and suspension cradles achieve fifty to seventy percent mass reduction versus steel stampings. BMW's Leipzig and Dingolfing plants specify lightweight structures for electric sedan platforms.
- Crash Impact Parts:Front rails, bumper beams, and side intrusion bars absorb kinetic energy through controlled fiber fracture and delamination. KBA type-approval for crash impact parts requires full-vehicle sled testing and material traceability documentation.
- Thermal Management:Battery pack enclosures and motor housings combine heat dissipation with electrical isolation.
- Aerodynamic Enhancements:Spoilers, diffusers, and underbody panels reduce drag coefficients with minimal mass penalty.
Lightweight structures anchor procurement volumes; crash impact parts are gaining share fastest as safety ratings intensify platform redesigns.
End User:
Customer type determines contract structure, inventory liability allocation, and technical collaboration depth.
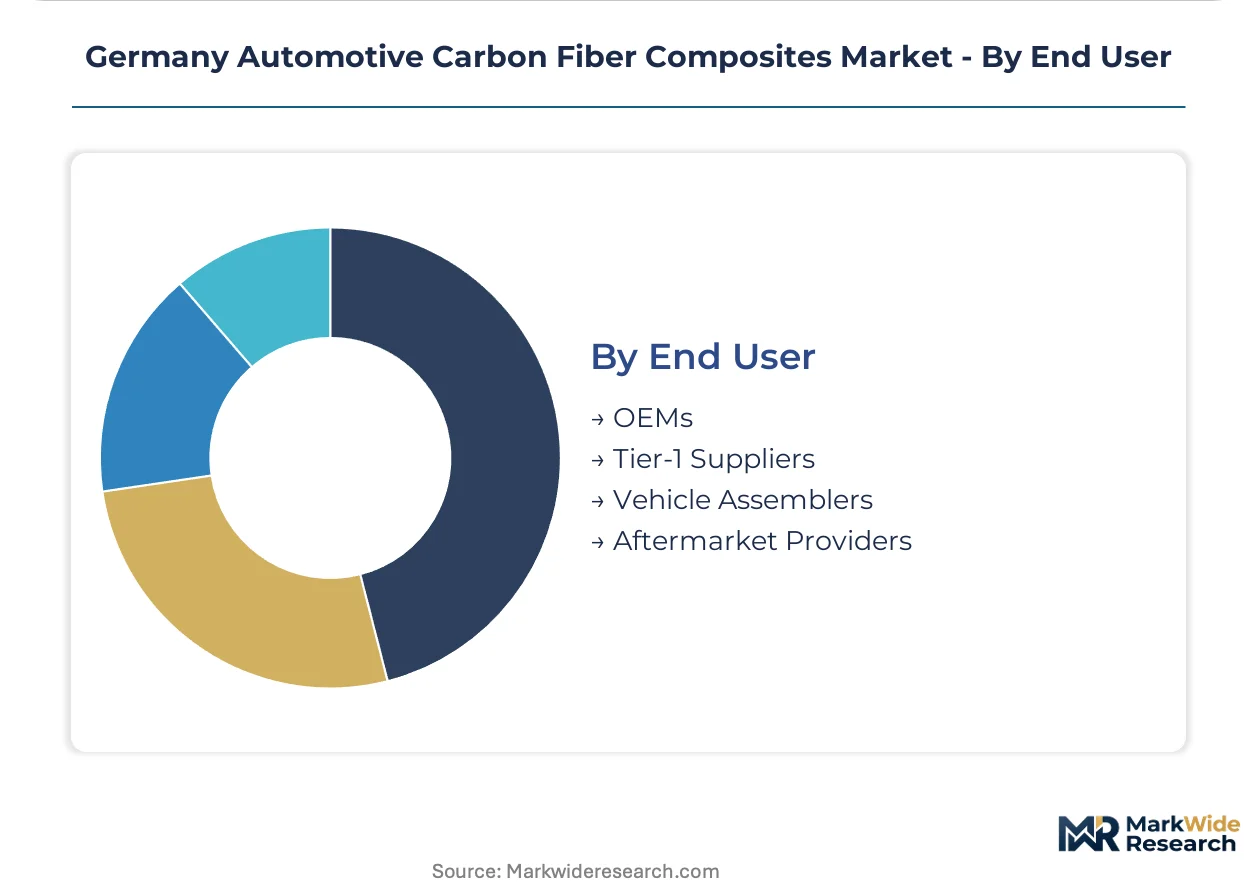
- OEMs:German vehicle manufacturers including BMW, Mercedes-Benz, and Volkswagen Group directly source strategic composite components for electric vehicle flagship programs. OEM procurement teams in Munich and Stuttgart negotiate multi-year prepreg supply agreements with volume commitments.
- Tier-1 Suppliers:System integrators including roof module and seating specialists composite-source at markup while managing assembly sequencing. Tier-1 relationships concentrate in Lower Saxony and Baden-Württemberg supplier parks.
- Vehicle Assemblers:Contract manufacturing and specialty vehicle producers access composite components through distributor networks.
- Aftermarket Providers:Performance tuning and collision repair segments serve niche demand for cosmetic and functional upgrades.
OEMs control the majority of qualified supply capacity; Tier-1 suppliers are climbing the fastest as platform consolidation concentrates spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive carbon fiber composites sector runs a structural trade surplus in precursor chemicals while importing finished aerospace-grade fiber from Japanese suppliers. The country's export strength concentrates in processed composite components bound for European OEM assembly plants.
Bavaria
Audi and BMW electric vehicle programs in Ingolstadt and Munich drive prepreg consumption for battery enclosures and roof structures. KBA type-approval protocols filter supplier qualification to three dominant compounders. The Munich-Ingolstadt corridor anchors just-in-sequence delivery networks that compress logistics costs below three percent of component value.
Baden-Württemberg
Mercedes-Benz engineering centers in Stuttgart specify carbon fiber for luxury sedan lightweighting under EU fleet emissions compliance pressure. REACH chemical re-registration through ECHA forces systematic reformulation of legacy epoxy hardeners before 2025 deadlines. The Stuttgart-Tübingen supplier cluster specializes in Class-A body panel tooling with paint-line thermal expansion matching.
Lower Saxony
Wind turbine blade manufacturing expertise in rotor blade preforming transfers directly to automotive structural member production. Volkswagen Group's Wolfsburg engineering campus validates crash-energy management for composite-intensive vehicle architectures. The Hanover-Braunschweig region hosts Tier-1 seating specialists deploying chopped fiber thermoplastic compounds for mass reduction.
North Rhine-Westphalia
Chemical precursor production at Leverkusen and Dormagen supplies domestic polyacrylonitrile feedstock for carbon fiber conversion. The EU Green Deal carbon-border adjustment mechanism embeds recyclability requirements into every new composite specification from concept phase. Cologne-Düsseldorf logistics hubs enable 48-hour delivery windows to Belgian and Dutch assembly plants.
Hesse
Frankfurt-Rhine-Main procurement centers consolidate multi-year prepreg supply agreements across BMW and Mercedes-Benz electric vehicle platforms. Autoclave technician scarcity limits capacity expansion despite qualified labor graduating fewer than two hundred composite process engineers annually from German vocational programs. The region's financial infrastructure supports supplier tooling amortization through asset-backed lending structures.
Germany Automotive Carbon Fiber Composites Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: vertically integrated carbon fiber producers controlling precursor-to-component pipelines, specialized prepreg compounders serving qualified OEM programs, and diversified chemical conglomerates leveraging resin formulation expertise. Competitive moves center on backward integration into precursor production and strategic partnerships for recycling technology scale-up.
Among German-headquartered specialists, SGL Carbon SE exemplifies the integrated producer archetype through captive supply of polyacrylonitrile conversion and finished component manufacturing. Toray Industries, Inc. anchors the foreign-dominant tier through sustained R&D partnerships with Munich and Stuttgart engineering centers. BASF SE occupies a position within the diversified chemical conglomerate vector, leveraging epoxy and thermoplastic resin portfolios to supply multiple composite formats. These three entities represent distinct competitive positioning strategies without overlapping core capabilities.
| Leading Market Players |
|---|
| SGL Carbon SE |
| Toray Industries, Inc. |
| Teijin Limited |
| Hexcel Corporation |
| Solvay Group |
| BASF SE |
| BMW AG |
| Voith GmbH & Co. KGaA |
| Muhr und Bender KG |
| Others |
Supply & Pricing Matrix
The Munich-Ingolstadt corridor's prepreg capacity concentration grants Bavarian compounders outsized leverage in contract negotiations with Stuttgart and Wolfsburg procurement teams. KBA qualification protocols lock buyers into approved supplier lists, insulating qualified producers from spot-price erosion even as raw material costs fluctuate.
Pricing Analysis
Current-generation autoclave-cured prepreg commands substantial premiums over prior-generation vacuum-infused formats, while next-generation thermoplastic stampable compounds are compressing entry-level pricing. Three-tier pricing structure across aerospace-grade, automotive-qualified, and industrial-grade certification levels segments buyer access. Cost compression in chopped fiber compounds is intensifying because Bavarian Tier-1s are consolidating volume commitments. Aftermarket repair segments exhibit highest price sensitivity; OEM direct-sourcing programs show lowest.
Supply Chain Analysis
Polyacrylonitrile precursor production concentrates in Japan, Germany, and the United States, with carbon fiber conversion capacity clustering in these same markets. German automotive programs draw from aerospace-grade fiber feedstock, epoxy resin systems, and specialized tooling equipment. Single-source vulnerability pervades precursor supply, with Japanese producers controlling premium-grade output. Distribution runs through just-in-sequence networks anchored to Munich, Stuttgart, and Wolfsburg assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity abounds as electric vehicle platform diversification splinters procurement specifications across battery enclosures, structural housings, and crash-management systems. Each architecture demands distinct qualification protocols, creating defendable niches for specialized compounders.
For Market Incumbents: Harden supply security through captive precursor arrangements or long-term offtake agreements with Mitsui Chemicals and Dralon. Accelerate thermoplastic matrix R&D to preempt REACH-driven epoxy reformulation disruption. Consolidate tooling ownership in Lower Saxony to capture wind-energy crossover talent pools.
For New Entrants and Emerging Players: Pursue chopped fiber thermoplastic compounds for seat frames and battery module brackets, where Class-A surface finish barriers exclude established prepreg suppliers. Target Hanover-Braunschweig supplier parks for co-location with Volkswagen Group validation centers. Lead with pyrolysis recycling partnerships to meet EU Green Deal procurement mandates.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with thermoplastic qualification progress and KBA crash-test documentation. Five-to-ten-year viability hinges on recycling technology integration rather than fiber production scale. Monitor ECHA substance restriction announcements as inflection signals for resin system obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Matrix Qualification | Unlocks recyclability compliance under EU Green Deal carbon-border mechanisms. |
| Backward Integration into Precursor | Secures polyacrylonitrile supply against Japanese producer concentration risk. |
| Pyrolysis Recycling Scale-Up | Enables closed-loop material recovery for KBA end-of-life vehicle directives. |
| Digital Twin Platform Deployment | Compresses BMW and Porsche first-article qualification timelines from eighteen months to six. |
| Lower Saxony Manufacturing Footprint | Captures wind blade preforming expertise transferable to automotive structural members. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 procurement directors, autoclave process technicians, and ECHA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from KBA type-approval databases, EU Green Deal implementation guidance, REACH substance restriction timelines, and automotive production registration data. Bottom-up segment sizing triangulated against top-down spending estimates from Bavarian and Baden-Württemberg procurement centers.
Scenario bracketing anchored volume projections across conservative, baseline, and accelerated electric vehicle penetration assumptions. Segmentation dimensions modeled include fiber format, component type, application function, and OEM versus Tier-1 sourcing channel. CAGRs derived from elasticity-adjusted demand curves incorporating battery pack mass-reduction requirements and KBA emissions compliance trajectories. Input sensitivity tested oil-indexed acrylonitrile price volatility and thermoplastic adoption speed.
Sensitivities concentrate around ECHA substance evaluation waves, pyrolysis recycling cost curves, and Japanese precursor export licensing shifts. Forecasts reflect documented assumptions regarding electric vehicle platform rollout timing and composite content per vehicle trajectories. Cross-checking against IHS Markit vehicle production forecasts and SGL Carbon segment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Automotive Pressure Plate Market
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Automotive Braking Component Market
Automotive Components
Automotive Key Market
Automotive Components
Auto Fender Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Polyamide in E-Mobility Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Automotive Actuators Market