
 North America Automotive Exhaust Aftertreatment Systems Market | 2026-2036
North America Automotive Exhaust Aftertreatment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Exhaust Aftertreatment Systems Market Analytics
Buyer concentration among heavy-duty fleet operators is realigning procurement leverage toward integrated aftertreatment platforms. Cummins Inc. anchors engine-integrated system architectures across North American truck OEM channels. Tenneco Inc. competes through exhaust component specialization that spans catalytic converter substrates and complete aftertreatment modules. BorgWarner differentiates via thermal management technologies that optimize regeneration cycles in variable-duty applications.
Automotive exhaust aftertreatment systems combine catalytic substrates, particulate filtration media, and reagent injection hardware to convert NOx, CO, and hydrocarbon emissions into nitrogen, carbon dioxide, and water vapor before tailpipe release. Selective catalytic reduction dominates value capture due to urea infrastructure maturity and EPA compliance stringency, while diesel particulate filter replacement cycles sustain aftermarket revenue pools. Active regeneration technology leads installation rates in cold-climate commercial applications where passive thermal profiles prove insufficient.
EPA tailpipe standards, California Air Resources Board waivers, and US Department of Transportation fuel economy mandates collectively dictate aftertreatment system complexity and sensor density requirements. NHTSA enforcement timelines pressure OEMs to validate integrated emission control architectures ahead of certification deadlines. Stakeholders must monitor state-level zero-emission vehicle mandates for divergence risks that could strand diesel aftertreatment investments.
Market Dynamics
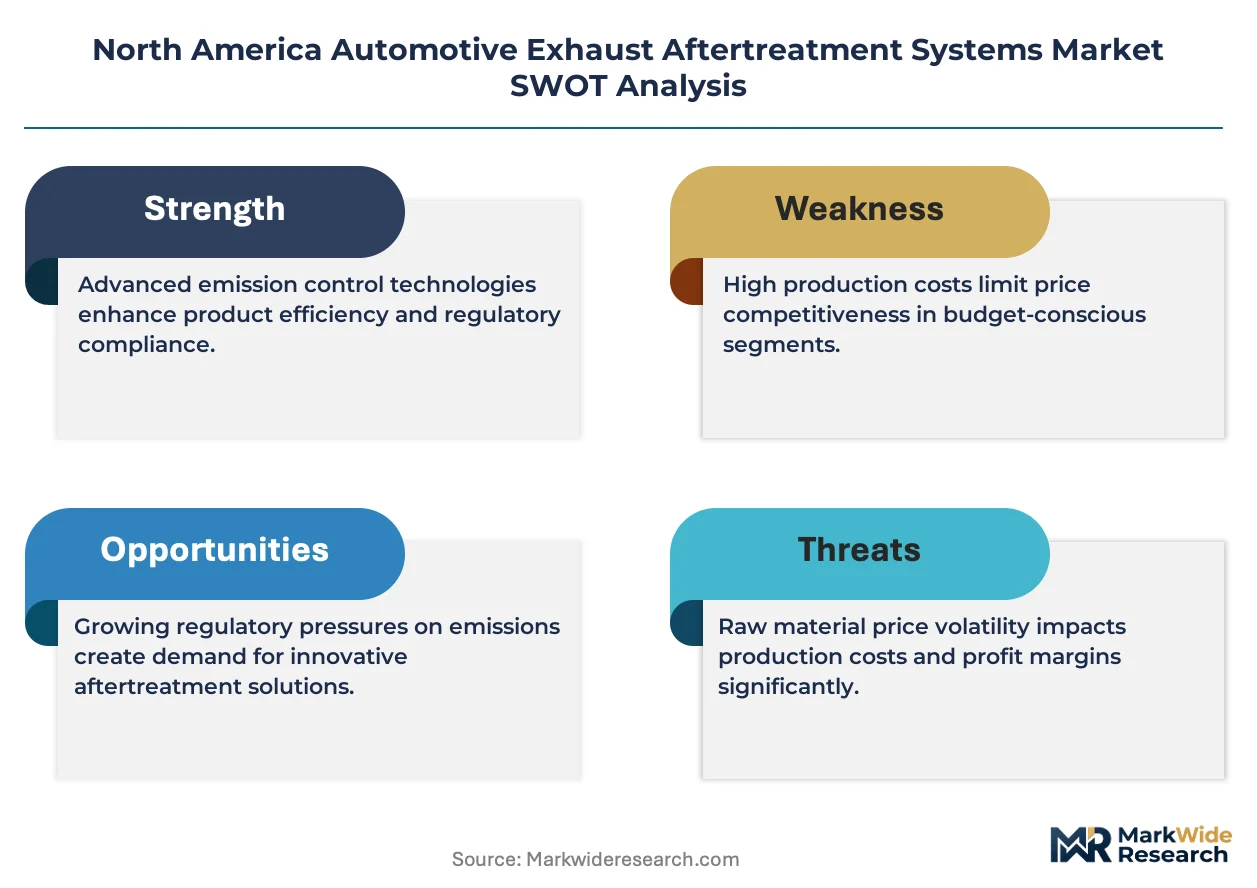
EPA Phase 2 greenhouse gas standards are compressing development cycles for heavy-duty fleet operators, forcing simultaneous upgrades to engine calibrations and aftertreatment architectures.
Growth Catalysts
- EPA Phase 2 Standards:Heavy-duty commercial truck fleets face escalating compliance deadlines that mandate selective catalytic reduction integration across Class 8 vehicle platforms.
- Midwest Manufacturing Corridor:Diesel particulate filter demand concentrates in Michigan, Ohio, and Indiana where heavy-duty vehicle production clusters sustain component procurement volumes.
- Urea Infrastructure Maturity:Selective catalytic reduction systems leverage established DEF distribution networks that reduce fleet operator adoption friction.
Market Restraints
- Platinum Group Metal Volatility:Catalytic converter substrates depend on palladium and rhodium supply concentrated in South African and Russian mining operations.
- DPF Regeneration Thermal Limitations:Passive thermal profiles prove insufficient in cold-climate commercial applications, constraining deployment geography.
- Zero-Emission Vehicle Mandate Divergence:California Air Resources Board waivers and state-level ZEV mandates threaten to strand diesel aftertreatment investments before full depreciation.
Strategic Opportunities
- Active Regeneration Technology:Cold-climate commercial applications in Canada and northern US states create white space for thermal management solutions that optimize regeneration cycles.
- Aftermarket Replacement Cycles:Diesel particulate filter replacement intervals sustain recurring revenue pools independent of new vehicle production volatility.
- Sensor Density Requirements:NHTSA enforcement timelines pressure OEMs to validate integrated emission control architectures, expanding demand for NOx and particulate matter sensors.
Industry Challenges
- Certification Timeline Compression:NHTSA enforcement deadlines force simultaneous validation of engine-integrated aftertreatment systems ahead of model year launches.
- Integrated Architecture Complexity:Combined selective catalytic reduction and diesel particulate filter modules require specialized thermal engineering talent scarce in traditional exhaust component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Exhaust Aftertreatment Systems Market |
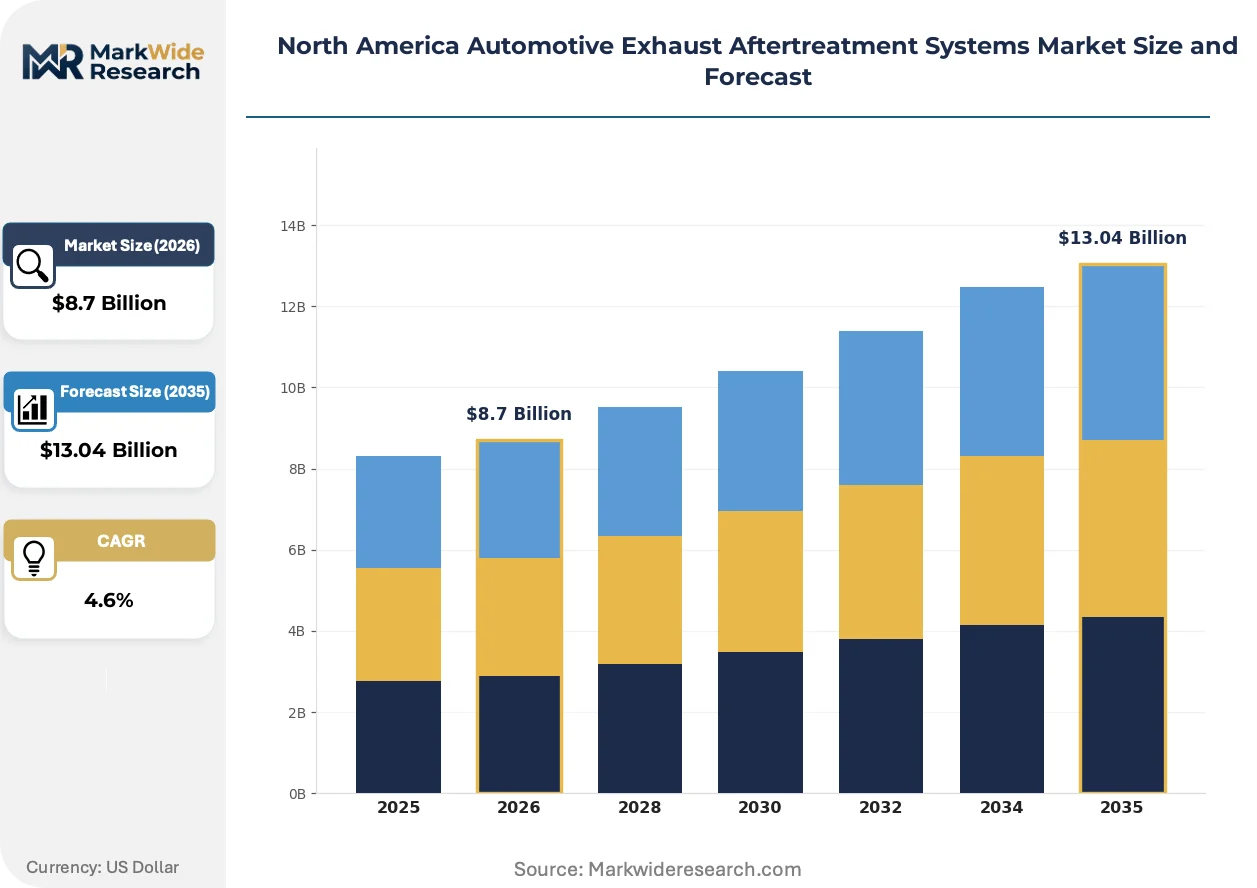
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective Catalytic Reduction, Diesel Particulate Filter, Exhaust Gas Recirculation, Lean NOx Trap Technology: Active Regeneration, Passive Regeneration, Hybrid Systems, Aftertreatment Control Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Light Duty Vehicles, Heavy Duty Vehicles, Commercial Trucks, Buses |
| Companies Covered | Tenneco Inc., Delphi Technologies, Cummins Inc., Continental, Faurecia, Donaldson Company, Robert Bosch GmbH, BorgWarner, Bosal Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Exhaust Aftertreatment Systems Market Evolving Landscape
Aftertreatment system architectures are converging toward engine-integrated platforms that compress packaging volume while expanding sensor density for real-time emissions monitoring.
Combined selective catalytic reduction and diesel particulate filter modules are overtaking discrete component installations in heavy-duty commercial applications. Fleet operators adopting integrated platforms reduce underhood complexity and service interval frequency. This consolidation is overtaking standalone system procurement as the default specification for Class 8 truck OEM channels.
California Air Resources Board waiver provisions are tightening enforcement timelines for nitrogen oxide emissions in heavy-duty segments. Manufacturers must validate dual-catalyst architectures that satisfy both federal EPA standards and state-level requirements. The heavy-duty commercial segment bears primary compliance burden, with fleet operators accelerating procurement of CARB-certified configurations.
Buyer concentration among national fleet operators is consolidating procurement leverage toward multi-year platform contracts. Traditional component distributors face disintermediation as direct OEM-supplier relationships replace aftermarket channel purchases. This consolidation is most visible across US Midwest manufacturing corridors where large fleet operators anchor regional demand patterns.
North America Automotive Exhaust Aftertreatment Systems Market Segmentation
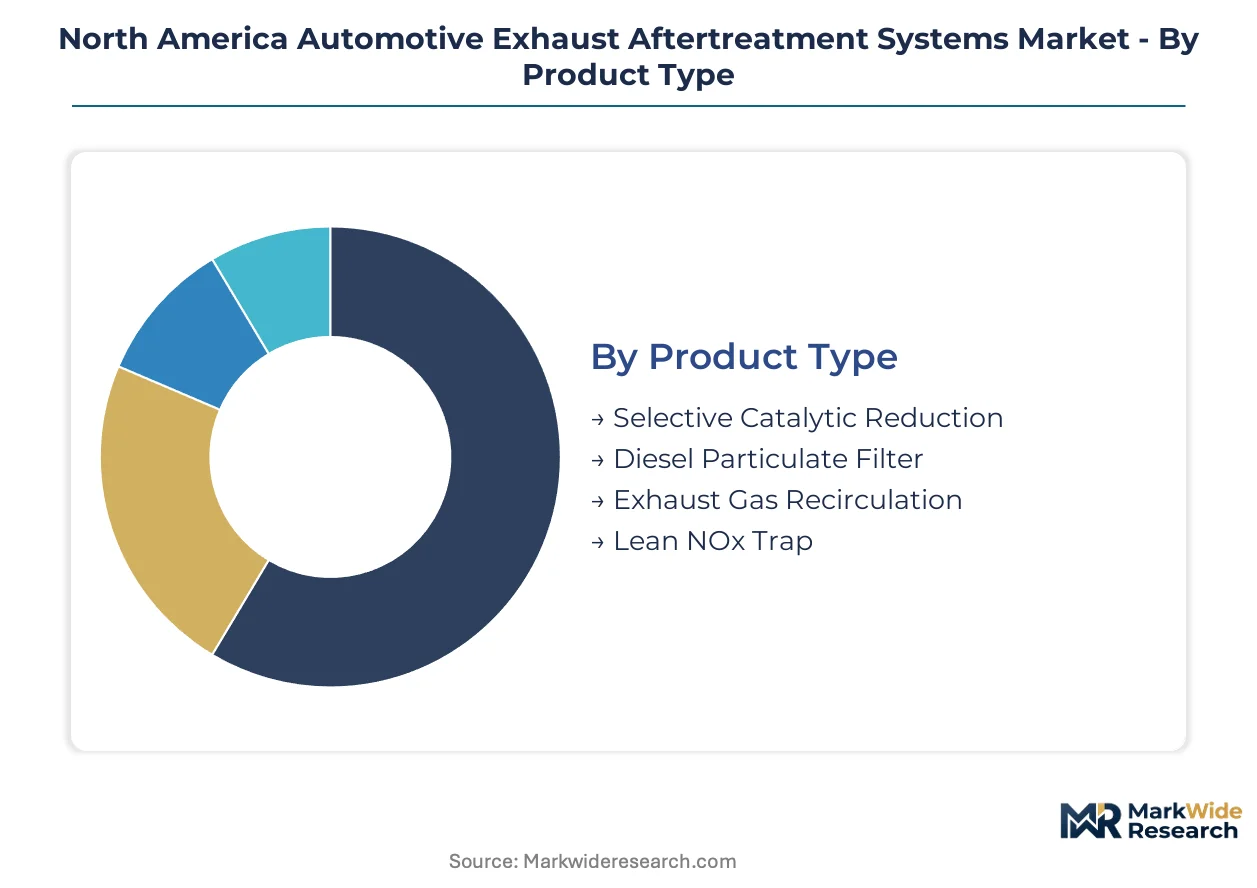
Aftertreatment system segmentation reveals divergent procurement patterns across vehicle duty cycles and regulatory exposure. Product architecture choices cascade through technology adoption, end-user channel selection, and application-specific thermal management requirements.
Product Type:
Buyer differentiation hinges on emission reduction chemistry and reagent infrastructure requirements rather than upfront hardware cost alone.
- Selective Catalytic Reduction:Urea-based aqueous solution injection converts nitrogen oxides into nitrogen and water vapor across ceramic honeycomb substrates. Heavy-duty commercial truck fleets in the US Midwest manufacturing corridor anchor demand as EPA Phase 2 greenhouse gas standards tighten compliance deadlines.
- Diesel Particulate Filter:Wall-flow ceramic substrates trap soot particles for subsequent thermal oxidation during regeneration cycles. Cold-climate commercial applications in Canada and northern US states drive active regeneration adoption where passive thermal profiles prove insufficient.
- Exhaust Gas Recirculation:Cooled exhaust stream recirculation reduces combustion temperatures to suppress nitrogen oxide formation.
- Lean NOx Trap:Adsorbs nitrogen oxides during lean-burn operation for periodic rich-burn desorption and reduction.
Selective catalytic reduction leads volumes today; diesel particulate filter replacement cycles sustain aftermarket revenue pools independent of new vehicle production volatility.
Technology:
Cost tier stratification separates premium active thermal management from economy passive configurations.
- Active Regeneration:Fuel injection or electric heating elements initiate soot oxidation independent of exhaust temperature. Cold-climate commercial applications in Michigan, Ohio, and Indiana create white space for thermal management solutions that optimize regeneration cycles.
- Passive Regeneration:Relies on sustained high exhaust temperatures during highway operation to oxidize trapped particulate matter.
- Hybrid Systems:Combines passive thermal profiles with active backup for variable-duty cycle assurance.
- Aftertreatment Control Systems:Sensor-integrated electronic modules manage reagent dosing and regeneration timing.
Active regeneration commands premium pricing; hybrid configurations are climbing the fastest as fleet operators seek operational flexibility across route profiles.
End User:
Volume concentration varies dramatically between captive OEM production and fragmented aftermarket replacement demand.
- OEMs:Original equipment manufacturers specify integrated engine-aftertreatment architectures for new vehicle certification.
- Tier-1 Suppliers:Component specialists manufacture catalytic substrates, filtration media, and injection hardware for system integrators.
- Aftermarket Providers:Independent distributors and service networks handle diesel particulate filter replacement intervals.
- Vehicle Assemblers:Final assembly operations integrate complete aftertreatment modules into vehicle chassis.
OEM channels dominate new system procurement; aftermarket providers are expanding fastest as replacement cycles compress under severe-duty applications.
Application:
Margin profiles diverge sharply between light-duty consumer vehicles and heavy-duty commercial platforms with extended operational lifecycles.
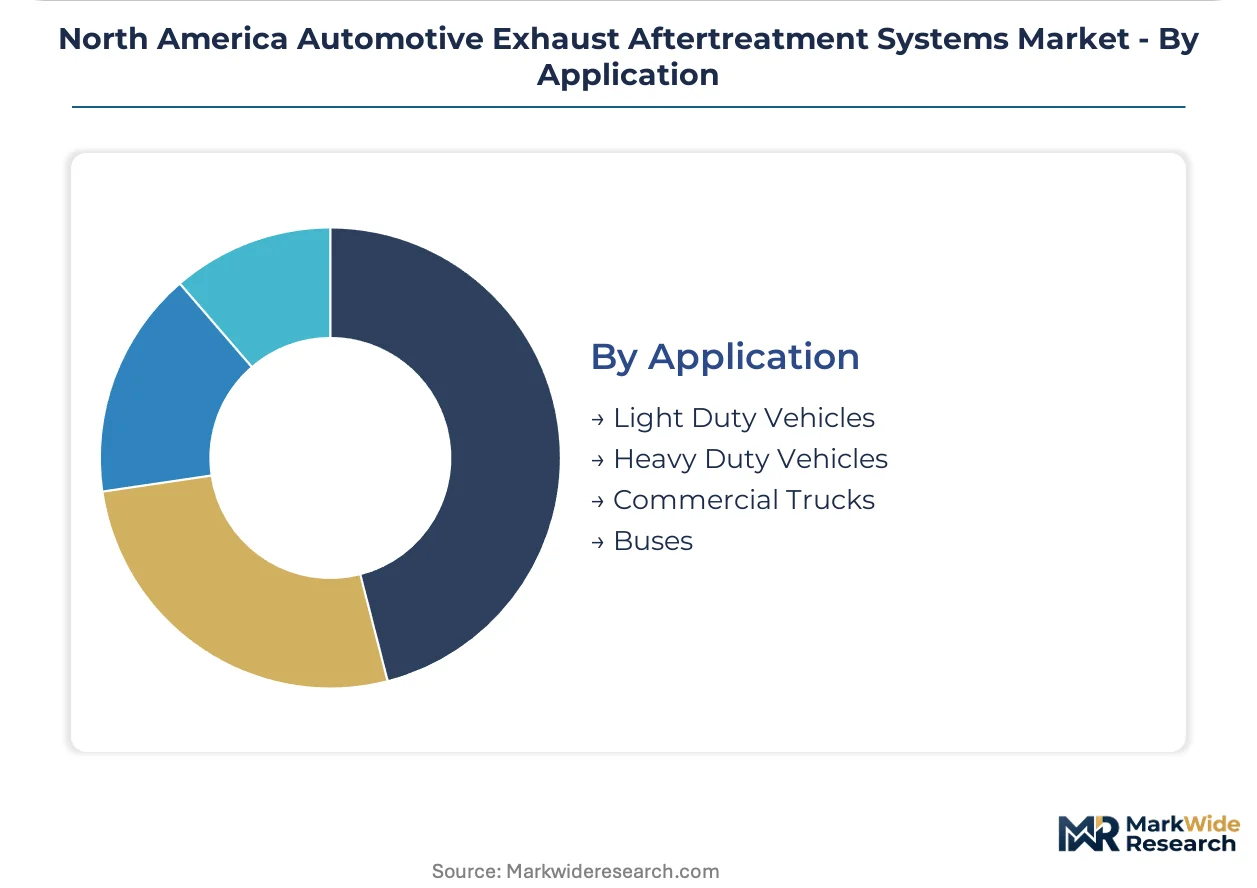
- Heavy Duty Vehicles:Class 8 commercial trucks require combined selective catalytic reduction and diesel particulate filter modules for EPA compliance.
- Commercial Trucks:Fleet operators prioritize total cost of ownership metrics including reagent consumption and service interval frequency.
- Buses:Urban transit duty cycles with frequent stops complicate passive regeneration thermal profiles.
- Light Duty Vehicles:Consumer pickup and passenger diesel applications face less stringent aftertreatment complexity.
Heavy duty vehicles anchor revenue concentration; commercial trucks are expanding most quickly as national fleet operators consolidate procurement toward multi-year platform contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Michigan, Ohio, and Indiana anchor North American aftertreatment system development. These Midwest corridors concentrate thermal management expertise and catalytic substrate manufacturing capabilities. Workforce density in exhaust component engineering exceeds other North American regions by substantial margins.
United States
Class 8 commercial truck production in Michigan and Ohio drives selective catalytic reduction procurement volumes. EPA Phase 2 greenhouse gas standards compress OEM validation timelines for integrated aftertreatment architectures. The Indiana-Ohio manufacturing corridor concentrates diesel particulate filter demand from heavy-duty fleet operators.
Canada
Cold-climate commercial applications in Alberta and Ontario create white space for active regeneration technology adoption. Environment and Climate Change Canada tailpipe standards align with EPA stringency while adding northern temperature testing requirements. The Toronto-Windsor manufacturing corridor hosts Tier-1 supplier operations serving cross-border OEM channels.
Mexico
Vehicle assembly expansion in Nuevo León and Puebla generates aftertreatment module integration demand for export markets. Mexican environmental regulator PROFEPA enforces emissions compliance parallel to EPA frameworks for heavy-duty platforms. The Bajío Region concentrates exhaust component stamping and substrate coating operations.
North America Automotive Exhaust Aftertreatment Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. Market structure tilts toward consolidated procurement relationships between national fleet operators and integrated system suppliers. Three strategic archetypes dominate: engine-integrated platform providers, exhaust component specialists, and thermal management technology developers. M&A activity concentrates on catalytic substrate capabilities, while strategic partnerships address sensor-integrated control system gaps.
Among engine-integrated platform providers, Cummins Inc. and BorgWarner occupy positions exemplifying system-level integration archetypes. Tenneco Inc. represents the exhaust component specialization tier with substrate and module manufacturing capabilities. Robert Bosch GmbH anchors sensor-integrated control system supply across North American OEM channels. These three companies illustrate the competitive spectrum from engine-attached architectures through distributed component supply.
| Leading Market Players |
|---|
| Tenneco Inc. |
| Delphi Technologies |
| Cummins Inc. |
| Continental |
| Faurecia |
| Donaldson Company |
| Robert Bosch GmbH |
| BorgWarner |
| Bosal Group |
| Others |
Value Network & Pricing Analysis
Exhaust system thermal engineering talent concentrated in Michigan, Ohio, and Indiana generates labor-cost differentials that widen pricing-tier spreads between premium integrated platforms and economy component supply.
Pricing Analysis
Bundled engine-integrated aftertreatment systems command substantial premiums over unbundled component procurement. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with CARB-certified configurations extracting brand premiums from heavy-duty fleet operators. Cost compression in economy substrates is intensifying because palladium and rhodium volatility squeezes converter manufacturers. National fleet operators with consolidated procurement show lowest price sensitivity; independent aftermarket distributors face acute margin pressure.
Supply Chain Analysis
EPA and CARB certification gating restricts substrate coating and catalyst formulation to qualified suppliers in the United States, Mexico, and Germany. Palladium and rhodium supply draws from South African and Russian mining operations, while ceramic honeycomb substrates source from Japanese and German manufacturers. Single-source vulnerability in platinum group metal supply creates structural exposure to geopolitical disruption. Distribution runs through direct OEM-supplier relationships that disintermediate traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Automotive Exhaust Aftertreatment Systems Market represents a late-cycle quality story as fleet procurement shifts toward CARB-certified integrated platforms with extended service intervals.
For Market Incumbents: Hedge platinum group metal exposure through long-term offtake agreements with South African suppliers before price volatility accelerates. Deepen backward integration into ceramic substrate manufacturing to defend margin position against converter specialists. Secure thermal engineering talent in the Midwest corridor through targeted acquisition of regional engineering firms.
For New Entrants and Emerging Players: Capture active regeneration technology white space in Canadian and northern US cold-climate applications where passive thermal profiles fail. Target aftermarket sensor replacement demand as NHTSA enforcement timelines expand NOx and particulate matter sensor density requirements. Pursue direct fleet operator relationships that bypass disintermediated distributor channels.
For Investors and Strategic Acquirers: Tier 1 automotive suppliers with engine integration capabilities are the most active acquirer in this space, seeking catalytic substrate specialists to fill architecture gaps. Long-term viability hinges on 5-10 year EPA regulatory continuity versus zero-emission vehicle mandate acceleration. Monitor California Air Resources Board waiver provisions as the critical inflection signal for diesel aftertreatment investment horizons.
| Strategic Initiative | Industry Significance |
|---|---|
| Active Regeneration Technology Development | Cold-climate fleet operators in Alberta and Minnesota require thermal management solutions beyond passive profiles. |
| Sensor-Integrated Control System Investment | NHTSA enforcement timelines pressure OEMs to validate denser emission monitoring architectures ahead of certification. |
| Platinum Group Metal Supply Agreement | Long-term offtake contracts with South African miners hedge converter manufacturers against palladium volatility. |
| Aftermarket Channel Direct Access | National fleet operators consolidating procurement leverage seek bypass relationships with system integrators. |
| CARB Dual-Catalyst Certification | Manufacturers must validate architectures satisfying both federal EPA standards and California waiver requirements. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down catalytic substrate supply tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributor operations heads, and fleet maintenance managers combined with secondary validation from EPA certification databases, NHTSA enforcement timelines, vehicle production registries, and platinum group metal trade flow data. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Historical trendline analysis of selective catalytic reduction and diesel particulate filter adoption rates established baseline penetration curves. The projection framework spans vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster segmentation dimensions. CAGRs derive from regression-adjusted trend extrapolation incorporating EPA Phase 2 compliance deadline acceleration and urea infrastructure expansion trajectories.
Regulatory timeline acceleration, platinum group metal supply disruption, and zero-emission vehicle mandate divergence are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding EPA-CARB regulatory continuity and heavy-duty fleet replacement cycle stability. A model refresh is warranted upon material change in California Air Resources Board waiver provisions or federal zero-emission vehicle mandate preemption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
OBD-Linked Predictive Maintenance Diagnostic Platforms Market
Vehicle Maintenance & Aftermarket
Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Duster Market