
 E-Commerce Automotive Aftermarket Market | 2026-2036
E-Commerce Automotive Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Automotive Aftermarket Market Analysis
The premium OEM-certified parts tier is rebalancing against unbranded commodity alternatives as warranty complexity and sensor-integrated components split buyer expectations. Amazon.com, Inc. leverages its fulfillment density to dominate same-day delivery for routine maintenance items. Alibaba Group Holding Limited anchors cross-border supply chains for bulk aftermarket components sourced from East Asian manufacturing clusters. AutoZone, Inc. competes through integrated buy-online-pick-up-in-store infrastructure that bridges digital convenience with physical service touchpoints.
The E-Commerce Automotive Aftermarket encompasses digitally transacted replacement components, accessories, and maintenance supplies for post-warranty vehicles, encompassing brake pads formulated to SAE J661 friction coefficients, catalytic converters meeting EPA Tier 3 emissions thresholds, and telematics-enabled diagnostic tools. The category serves vehicle owners, independent repair facilities, and fleet managers seeking alternatives to franchised dealer networks for cost containment and parts availability. Parts and Accessories categories lead transaction volume, with brake, filtration, and lighting components generating recurring demand cycles tied to wear-based replacement intervals. Online Retailers and Marketplaces capture the fastest-growing sales channel share as platform economics aggregate fragmented supplier bases and reduce search costs for buyers comparing fitment specifications across multiple vehicle platforms.
The EPA enforces emissions compliance for aftermarket catalytic converters and exhaust components sold through digital channels, while the EU F-Gas Regulation restricts refrigerant handling in climate system parts traded across member state borders. NHTSA safety standards govern brake and lighting component performance claims, creating certification barriers that filter low-quality listings from major platforms. Stakeholders must monitor evolving right-to-repair legislation across multiple jurisdictions, as mandated diagnostic data access threatens proprietary service information advantages that currently tether complex repairs to authorized channels.
Market Dynamics
Platform economics are compressing traditional distribution layers as marketplace aggregators capture search traffic and fulfillment scale advantages previously held by specialized distributors with decades of fitment data.
Growth Catalysts
- EU Green Deal circular economy mandates:Remanufacturing requirements for brake calipers and steering racks are creating certified refurbishment channels that extend part lifecycles and open new revenue streams for qualified suppliers.
- DIY enthusiast expansion:Vehicle owners facing elevated labor rates at repair facilities are sourcing diagnostic tools and sensor-integrated components through digital channels, driving transaction frequency in the maintenance category.
- Telematics-enabled predictive maintenance:Connected vehicle data streams are triggering automated parts recommendations before failure events, converting unplanned repairs into scheduled e-commerce purchases.
Market Restraints
- Aluminum and rare earth input volatility:Catalytic converter substrates and electric motor magnets face price swings that compress margins on emission-critical components sold through thin-margin digital channels.
- East Asian manufacturing concentration:Bulk aftermarket production clusters in specific industrial zones create single-point vulnerability for cross-border fulfillment networks serving European and North American demand.
- SAE J661 certification barriers:Friction material testing requirements for brake components filter low-quality listings but extend supplier onboarding timelines for marketplace platforms.
Strategic Opportunities
- Right-to-repair legislative tailwinds:Mandated diagnostic data access in multiple US states and EU member countries threatens proprietary service information advantages, opening complex repair categories to independent digital sellers.
- Same-day fulfillment infrastructure gaps:Dense urban corridors in Germany and the Netherlands remain underserved for emergency replacement parts, creating white space for localized inventory positioning.
- Sensor-integrated component convergence:Advanced driver-assistance system calibration tools paired with replacement cameras and radar units enable bundled digital offerings that capture higher transaction values.
Industry Challenges
- Fitment data standardization delays:Inconsistent vehicle identification number mapping across supplier databases generates return rates that erode platform economics and buyer trust.
- Emissions compliance verification complexity:EPA Tier 3 and CARB certification documentation requirements for catalytic converters create listing审核 bottlenecks that slow inventory velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Automotive Aftermarket Market |
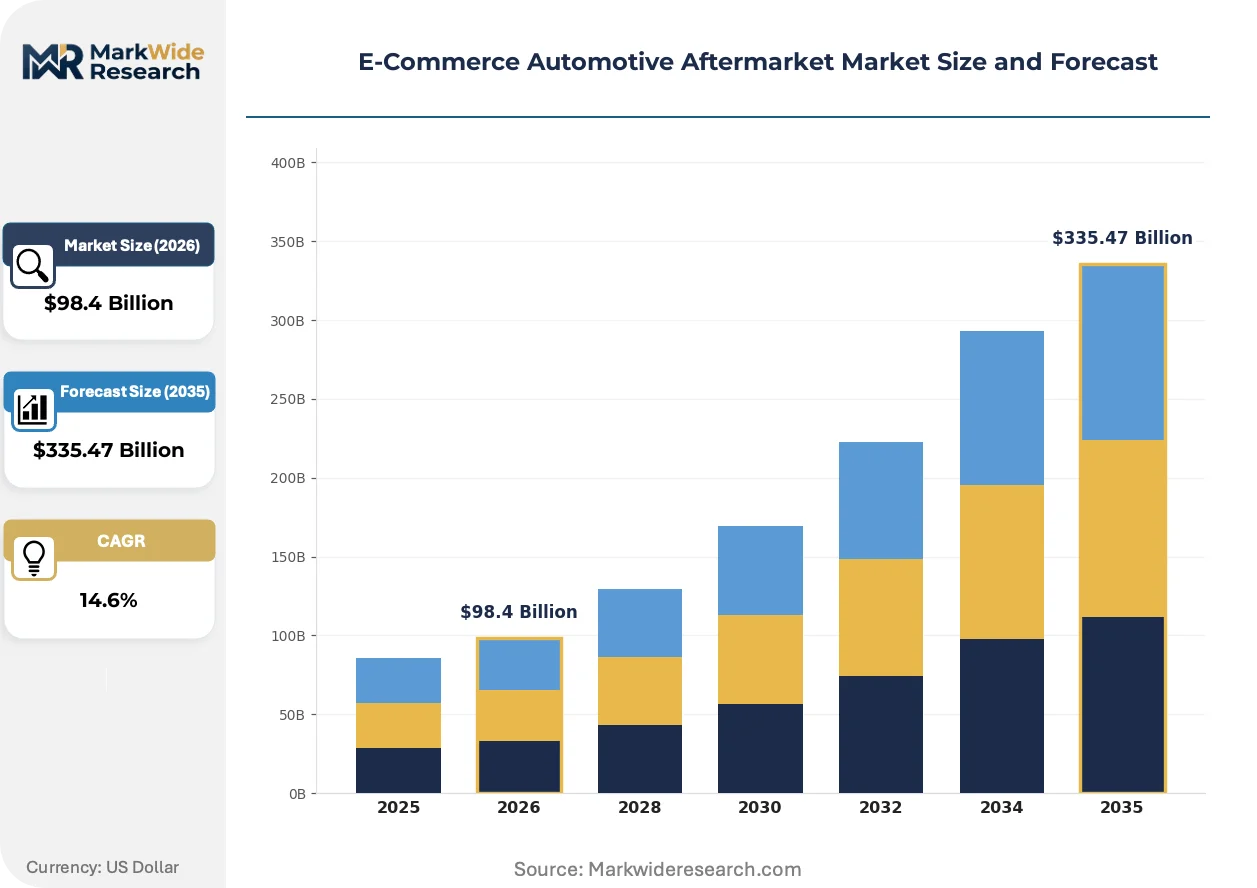
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $335.47 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parts, Accessories, Tools, Fluids Sales Channel: Online Retailers, Marketplaces, Brand Websites, Garage Networks Customer Type: Consumers, DIY Enthusiasts, Mechanics, Fleet Operators Service Type: Installation, Delivery, Warranty, Technical Support |
| Companies Covered | Amazon.com, Inc., Alibaba Group Holding Limited, Advance Auto Parts, Inc., AutoZone, Inc., O'Reilly Auto Parts, eBay Inc., RockAuto, LLC, CARiD, U.S. Auto Parts Network, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Automotive Aftermarket Market Emerging Trajectories
Artificial intelligence applications are rewiring how buyers discover compatible components, replacing keyword search with visual recognition and predictive fitment matching that reduces return friction.
Computer vision-based part identification is overtaking traditional catalog navigation as the primary discovery mechanism for DIY buyers. Smartphone camera applications now match worn brake pads and damaged body panels against manufacturer specifications in real time. This compression of the search-to-purchase cycle is reducing cart abandonment rates and expanding addressable demand among non-technical vehicle owners.
The EU F-Gas Regulation is restricting refrigerant handling in climate system components traded across member state borders, forcing marketplace platforms to verify technician certification before completing transactions. Sellers of air conditioning compressors and recharge kits must now integrate credential validation into checkout flows. This regulatory layer is segmenting the market between professional-grade channels and consumer-restricted listings.
Fleet procurement centralization is consolidating purchasing authority for light commercial vehicle maintenance into specialized procurement platforms that displace individual driver purchasing. Large logistics operators in Germany and Poland are negotiating direct supplier relationships that bypass generalist marketplaces for high-volume consumables. This buyer concentration is compressing margins for sellers dependent on fragmented individual transactions.
E-Commerce Automotive Aftermarket Market Segmentation
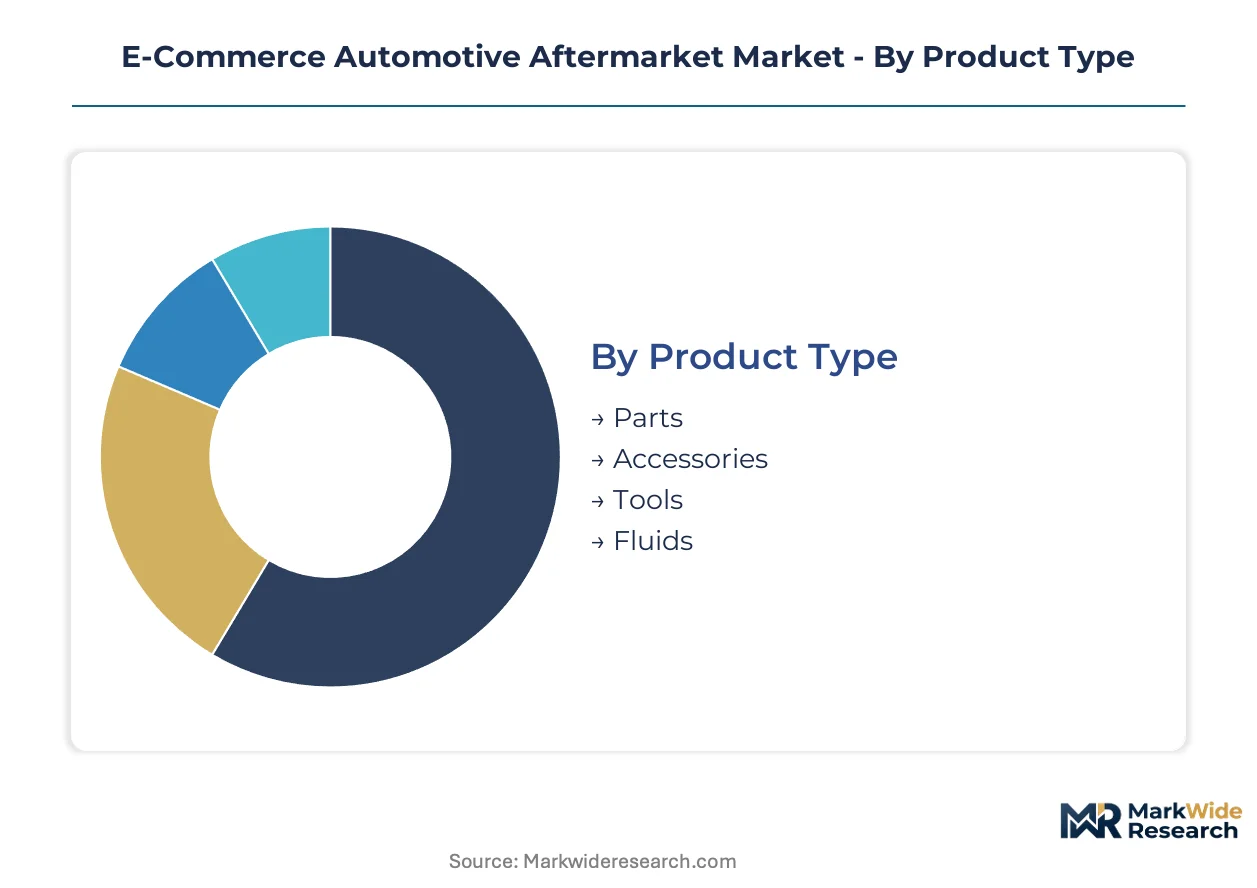
Segmentation in the E-Commerce Automotive Aftermarket reveals how certification burdens, fulfillment complexity, and buyer expertise split demand across incompatible service models. Parts requiring EPA Tier 3 or SAE J661 validation command premium positioning against unbranded alternatives, while same-day delivery feasibility varies sharply by component size and hazard classification.
Product Type:
EPA Tier 3 certification applies to catalytic converters and exhaust substrates, while SAE J661 friction coefficients govern brake materials; accessories and tools face lighter documentation loads but heavier fitment-matching requirements.
- Parts:Brake pads, filtration elements, and lighting assemblies formulated to OEM specifications or aftermarket equivalents. Demand clusters in Germany where dense vehicle ownership and mature logistics infrastructure support rapid replenishment cycles for wear-based replacement intervals.
- Accessories:Interior upgrades, exterior styling components, and telematics hardware including diagnostic interfaces and ADAS calibration tools. DIY enthusiasts in Poland and the Netherlands drive transaction frequency as vehicle owners seek cost-effective personalization options.
- Tools:Professional-grade diagnostic equipment, torque wrenches, and specialized service instruments.
- Fluids:Engine oils, brake fluids, coolants, and refrigerants subject to EU F-Gas Regulation handling restrictions.
Leading the category by volume: Parts. Growing fastest: Accessories.
Sales Channel:
Platform economics favor aggregators with fulfillment density, while brand websites retain margin control at the cost of traffic acquisition; garage networks monetize installation expertise that pure digital channels cannot replicate.
- Online Retailers:Specialized automotive platforms with curated fitment databases and technical support infrastructure. Fleet operators in Germany consolidate procurement through these channels for predictable delivery schedules and consolidated invoicing.
- Marketplaces:Generalist platforms aggregating fragmented supplier bases and reducing search costs through competitive listing density. Cross-border supply chains from East Asian manufacturing clusters anchor inventory depth for bulk aftermarket components.
- Brand Websites:Direct manufacturer channels bypassing platform fees to capture full margin on proprietary components.
- Garage Networks:Integrated buy-online-pick-up-in-store infrastructure bridging digital convenience with physical service touchpoints and installation labor.
Highest transaction velocity: Marketplaces. Steepest margin compression: Online Retailers.
Customer Type:
Procurement authority concentrates differently across segments—individual consumers optimize for price transparency, while fleet operators negotiate volume terms that displace fragmented purchasing.
- DIY Enthusiasts:Vehicle owners sourcing diagnostic tools and sensor-integrated components through digital channels, driving transaction frequency in the maintenance category as elevated labor rates at repair facilities push cost containment strategies.
- Fleet Operators:Large logistics operators in Germany and Poland negotiating direct supplier relationships that bypass generalist marketplaces for high-volume consumables including brake pads, filtration elements, and lighting assemblies.
- Consumers:Individual vehicle owners prioritizing convenience and price comparison across multiple platforms.
- Mechanics:Independent repair facilities requiring technical documentation, warranty support, and rapid availability for unplanned repairs.
Fastest order frequency: DIY Enthusiasts. Largest average order value: Fleet Operators.
Service Type:
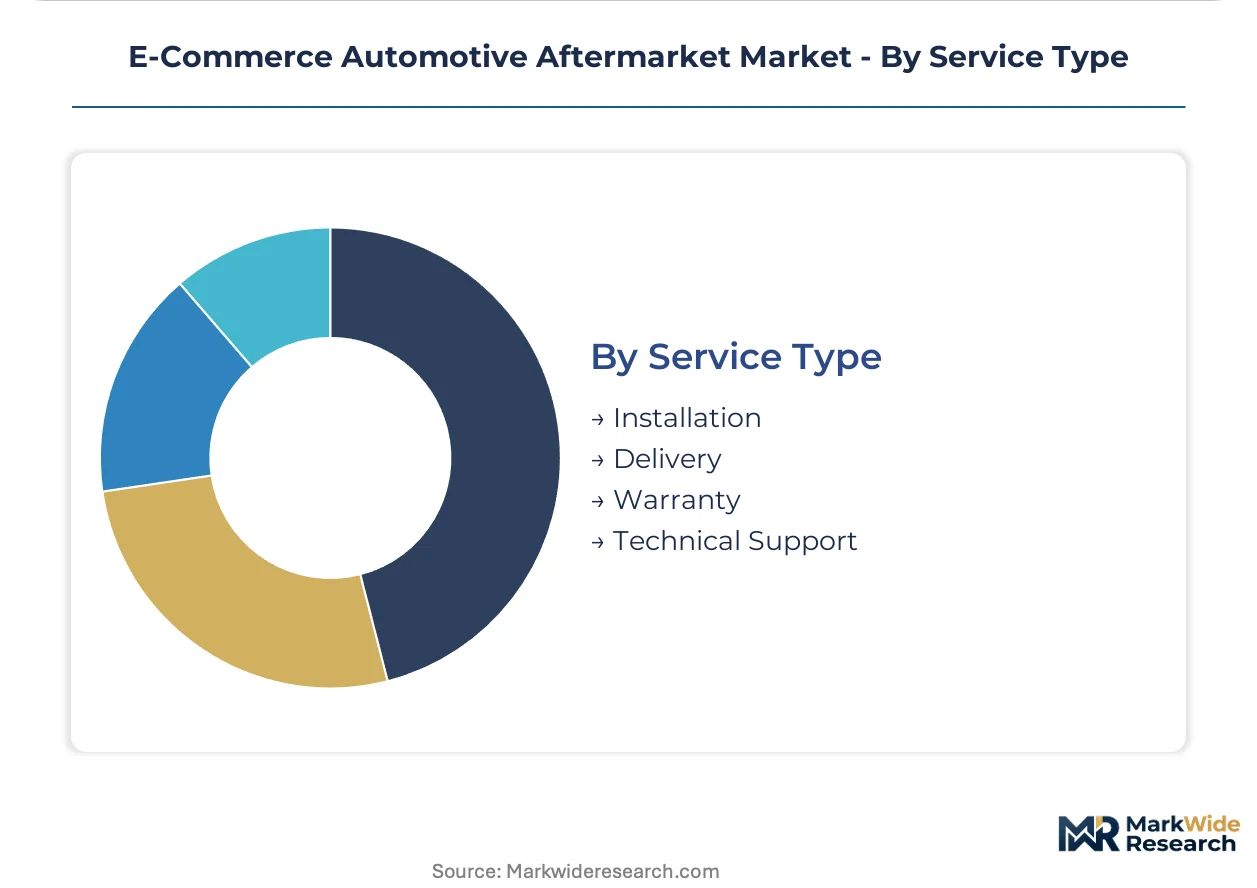
Fulfillment infrastructure gaps in dense urban corridors create white space for localized inventory positioning, while warranty complexity favors channels with direct manufacturer relationships.
- Delivery:Same-day and emergency fulfillment for critical replacement components, with density advantages in German metropolitan corridors where vehicle downtime costs escalate rapidly.
- Installation:Labor bundling that captures service revenue unavailable to pure parts sellers, particularly for ADAS calibration and sensor-integrated components requiring specialized equipment.
- Warranty:OEM-backed coverage terms that reduce perceived risk on high-value purchases including catalytic converters and electronic control modules.
- Technical Support:Fitment verification, diagnostic guidance, and troubleshooting assistance that reduces return rates and builds platform loyalty.
Widest coverage gap: Installation. Expanding most quickly: Technical Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan corridor anchors European e-commerce automotive aftermarket density, where mature logistics infrastructure and dense vehicle ownership create rapid replenishment cycles for wear-based replacement parts.
United States
DIY enthusiast expansion and elevated repair facility labor rates drive transaction frequency for diagnostic tools and sensor-integrated components. NHTSA safety standards govern brake and lighting performance claims, filtering low-quality marketplace listings. The Detroit-Windsor automotive corridor concentrates supplier relationships that feed cross-border fulfillment networks.
Germany
Fleet procurement centralization among logistics operators consolidates purchasing authority for high-volume consumables including brake pads and filtration elements. The EU Green Deal circular economy mandates remanufacturing requirements for brake calipers and steering racks, creating certified refurbishment channels. The Stuttgart industrial region hosts dense supplier networks supporting same-day delivery feasibility for critical replacement components.
China
East Asian manufacturing clusters anchor cross-border supply chains for bulk aftermarket components sourced through generalist marketplaces. MIIT standards govern telematics-enabled diagnostic tools traded through digital channels. The Yangtze River Delta manufacturing belt concentrates production capacity that feeds European and North American demand with compressed lead times.
United Kingdom
Right-to-repair legislative tailwinds threaten proprietary service information advantages, opening complex repair categories to independent digital sellers. The UK Vehicle Certification Agency enforces emissions compliance documentation for catalytic converters sold through online channels. The Midlands automotive cluster supports specialized platforms with curated fitment databases and technical support infrastructure.
Japan
Telematics-enabled predictive maintenance adoption converts unplanned repairs into scheduled e-commerce purchases through connected vehicle data streams. METI standards shape aftermarket component quality expectations for sensor-integrated parts. The Nagoya-Toyota industrial corridor concentrates OEM supplier relationships that influence aftermarket certification tiers.
E-Commerce Automotive Aftermarket Market Vendor Landscape
Premium-margin players sit above commodity-margin players across fulfillment density and certification depth, with platform economics compressing traditional distribution layers previously held by specialized distributors. Marketplace aggregators capture search traffic advantages through competitive listing density, while integrated buy-online-pick-up-in-store operators bridge digital convenience with physical service touchpoints. Three archetypes dominate: fulfillment-scale platforms, fitment-data specialists, and garage-network integrators. Competitive moves concentrate on same-day infrastructure expansion and cross-border supply chain consolidation.
Among North American-based operators, Amazon.com, Inc. and AutoZone, Inc. occupy positions at opposite ends of the fulfillment spectrum—pure platform density versus integrated physical-digital infrastructure. Alibaba Group Holding Limited anchors the cross-border tier, representing the East Asian manufacturing cluster linkage archetype that supplies bulk aftermarket components to European and North American demand centers.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Alibaba Group Holding Limited |
| Advance Auto Parts, Inc. |
| AutoZone, Inc. |
| O'Reilly Auto Parts |
| eBay Inc. |
| RockAuto, LLC |
| CARiD |
| U.S. Auto Parts Network, Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up aftermarket distributors have consolidated fragmented supplier bases across Germany and Poland, tightening working capital discipline that feeds through to pricing power on EPA Tier 3-certified catalytic converters and SAE J661-validated brake components. Their ownership structure demands margin extraction through volume-based procurement leverage, compressing commodity-tier suppliers while premium OEM-certified channels retain pricing autonomy.
Pricing Analysis
Value-based pricing anchored to vehicle uptime and repair facility labor rate avoidance governs the premium tier, with fleet operators accepting 15-40% markups on guaranteed-fitment parts that eliminate diagnostic delays. Price differentiation separates EPA Tier 3-certified emission components from uncertified alternatives, while volume scale and same-day delivery feasibility drive stratification across urban corridors. Pricing pressure stems from aluminum and rare earth input volatility on catalytic converter substrates, eroding margins on thin-margin digital channels. DIY enthusiasts exhibit highest price sensitivity, comparing fitment specifications across multiple platforms; fleet operators show lowest sensitivity, prioritizing predictable delivery schedules and consolidated invoicing.
Supply Chain Analysis
Dual-sourcing requirements from German fleet operators and North American marketplace platforms mandate multi-supplier qualification for brake calipers and steering racks, preventing single-point dependency on East Asian remanufacturing clusters. Geographic supply concentration centers on China's Yangtze River Delta for bulk aftermarket production, Germany's Stuttgart region for precision-machined OEM-equivalent components, and Mexico's border manufacturing belt for North American fulfillment. Raw material dependencies span aluminum alloys for brake rotors, rare earth elements for catalytic converter substrates, and semiconductor-grade sensors for ADAS calibration tools. Tariff exposure on cross-border East Asian supply chains presents structural risk. Distribution runs through marketplace aggregators capturing search traffic, specialized online retailers with curated fitment databases, and integrated garage networks bridging digital convenience with physical installation labor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA Tier 3 and SAE J661 certification barriers create durable moats for incumbent suppliers capable of absorbing documentation and testing overhead that filters low-quality marketplace listings.
For Market Incumbents: Cement certification depth as a defensive barrier by accelerating backward integration into remanufacturing capacity for brake calipers and steering racks under EU Green Deal circular economy mandates. Threat from unbranded commodity sellers on generalist marketplaces demands channel control through exclusive fitment data licensing agreements with platform operators. Investment in same-day fulfillment infrastructure across Germany's Rhine-Ruhr corridor captures fleet procurement centralization trends. For New Entrants and Emerging Players: Direct-to-garage digital channels offer the most penetrable route for bypassing platform fee structures that compress margins on generalist marketplaces. White-space targets cluster in ADAS calibration tool bundling with replacement cameras and radar units, and in localized inventory positioning for emergency replacement parts in underserved Dutch urban corridors. Go-to-market angle should emphasize technician certification integration at checkout to satisfy EU F-Gas Regulation compliance requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor fitment-data specialists with proprietary VIN-mapping databases in Germany and Poland, where consolidation tailwinds and regulatory compliance burdens are forcing sub-scale competitors toward exit. Long-term viability hinges on five-to-ten-year positioning for right-to-repair legislative inflection points that would unlock proprietary diagnostic data currently tethering complex repairs to authorized dealer networks. Signal to watch: state-level right-to-repair bill passage rates in the United States and corresponding EU member country adoption patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Same-Day Fulfillment Infrastructure Expansion | Captures fleet procurement centralization in Germany's dense logistics corridors where vehicle downtime costs escalate rapidly. |
| Backward Integration into Remanufacturing | Positions suppliers to meet EU Green Deal circular economy mandates for brake calipers and steering rack refurbishment. |
| ADAS Calibration Tool Bundling | Enables higher transaction values through sensor-integrated component convergence requiring specialized equipment. |
| Fitment Data Standardization Investment | Reduces return rates that erode platform economics by resolving inconsistent VIN mapping across supplier databases. |
| Technician Certification Integration | Satisfies EU F-Gas Regulation credential validation requirements for climate system components traded across member state borders. |
Methodological Framework
Independent corroboration across primary interviews with aftermarket distributor procurement heads, OEM platform engineers, independent repair facility owners, and fleet logistics managers, combined with secondary validation through EPA certification databases, NHTSA safety standard filings, and EU F-Gas Regulation compliance registries, underwrites the qualitative findings. Bottom-up demand modeling from vehicle parc data and replacement interval analysis triangulates against top-down market sizing from customs trade flows and platform transaction disclosures.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, sales channel architecture, customer procurement authority, and service fulfillment model. CAGRs derive from fitted growth curves calibrated to telematics-enabled predictive maintenance adoption curves and DIY enthusiast expansion patterns. Industry-specific forecast inputs include connected vehicle penetration rates and right-to-repair legislative progression indices.
The model holds under stable regulatory enforcement intensity and cross-border logistics continuity; deviation in aluminum and rare earth price volatility, East Asian manufacturing cluster disruption, or accelerated right-to-repair mandate implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Silicone in Car Care Products Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Vehicle Recycling Market