
 Philippines Freight and Logistics Market | 2026-2036
Philippines Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Freight and Logistics Market Outlook
Outsourced fleet management is consolidating among Philippine enterprises seeking cost predictability across the archipelago's fragmented geography. Royal Cargo anchors inter-island heavy freight through specialized vessel networks. LBC Express Holdings sustains nationwide parcel coverage via franchise-operated last-mile stations. DHL Group leverages international gateway control at Manila and Cebu ports to compete on cross-border express services.
Philippines freight and logistics encompasses the coordinated movement of goods through multimodal networks spanning over 7,600 islands, requiring roll-on/roll-off vessel specifications and temperature-controlled container standards for agricultural and pharmaceutical cargo. Its primary commercial purpose is bridging production zones in Mindanao and Visayas with consumption centers in Luzon while enabling export manufacturing competitiveness. Road logistics dominates volume flows despite chronic congestion on the Pan-Philippine Highway, while warehousing commands margin concentration in Metro Manila's bonded zones. E-commerce end users represent the fastest-expanding demand pool, pressuring service providers to compress fulfillment cycles.
The Department of Transportation enforces vessel safety and port modernization mandates that elevate capital requirements for domestic shipping operators. The Bureau of Customs administers trade facilitation reforms and anti-smuggling protocols that directly affect freight forwarding margins and clearance velocity. Stakeholders must monitor how BIR tax compliance automation and the Anti-Red Tape Authority's regulatory streamlining reshape operational cost structures and competitive differentiation across Luzon, Visayas, and Mindanao corridors.
Market Dynamics
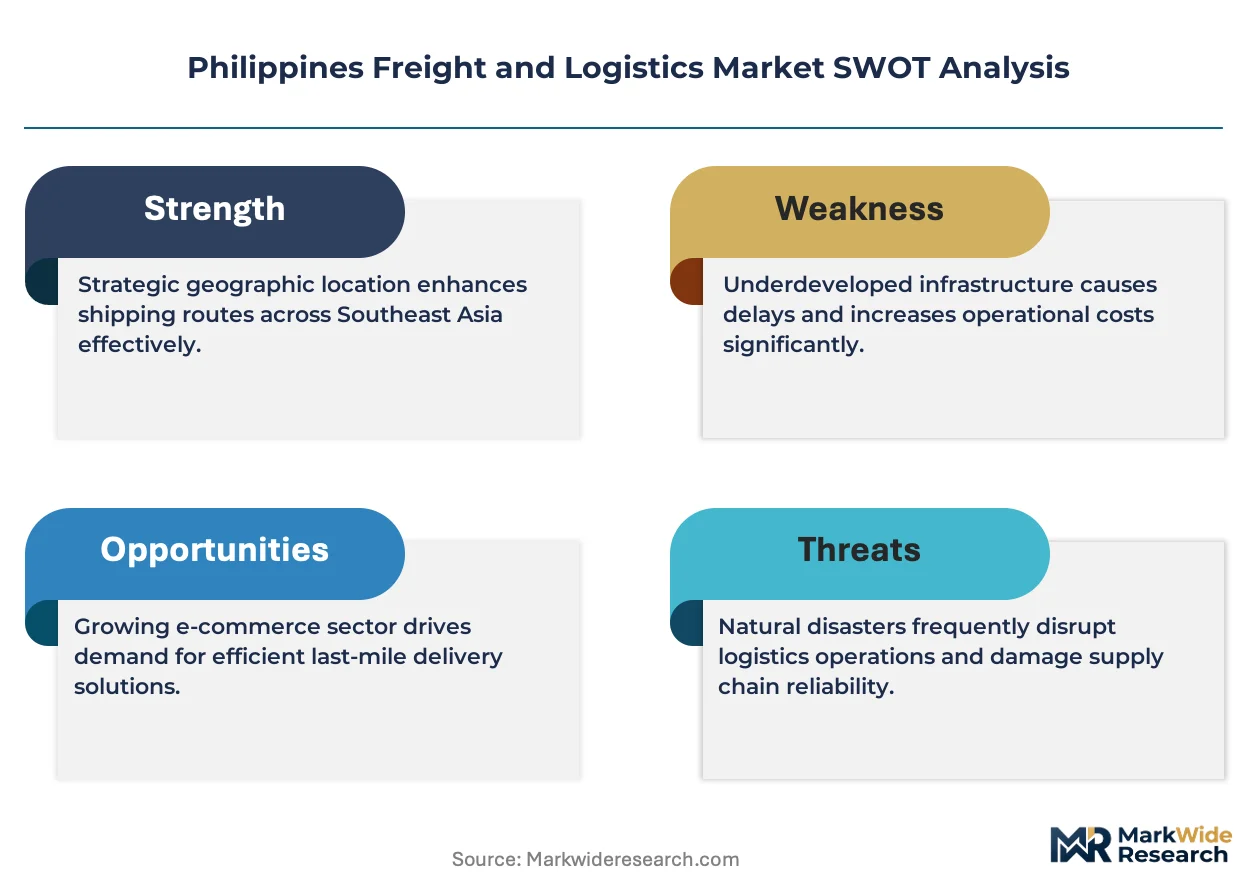
Inter-island connectivity gaps and Department of Transportation vessel modernization mandates are forcing domestic shipping operators to consolidate fleets and upgrade roll-on/roll-off specifications, compressing margins for smaller carriers while advantaging capital-heavy networks.
Growth Catalysts
- E-commerce fulfillment acceleration:Shopee and Lazada marketplace volumes are driving demand for refrigerated last-mile stations across Visayas and Mindanao provinces, requiring temperature-controlled container investments from third-party logistics providers.
- Build! Build! Build! infrastructure program:The Department of Transportation's port modernization and Pan-Philippine Highway widening are reducing transit times between Calabarzon manufacturing zones and Manila export gateways.
- Agricultural cold chain mandates:Bureau of Fisheries and Aquatic Resources regulations on seafood transport are compelling reefers and controlled-atmosphere equipment adoption for tuna and shrimp exporters in General Santos and Zamboanga.
Market Restraints
- Fuel cost volatility:Diesel price swings directly erode road freight margins, with provincial operators lacking fuel surcharge mechanisms that large fleet managers deploy.
- Port concentration risk:Manila and Cebu ports handle over 80% of international container throughput, creating vessel queuing bottlenecks during peak harvest seasons.
- Ro-Ro vessel age limits:Maritime Industry Authority safety inspections are grounding older inter-island ferries faster than shipyard replacement capacity permits.
Strategic Opportunities
- Mindanao logistics corridors:Davao and Cagayan de Oro bonded warehousing zones remain undersupplied relative to emerging banana and pineapple export volumes.
- Digital freight matching platforms:Trucking apps connecting Calabarzon manufacturers with backhaul capacity in Batangas and Laguna are reducing empty-mile ratios for mid-size fleet operators.
- Pharmaceutical GDP compliance:Food and Drug Administration cold chain validation requirements for vaccines and biologics are creating certified logistics service provider niches.
Industry Challenges
- Licensed mariner shortages:Maritime Industry Authority certification backlogs for deck officers and engineers are delaying vessel crewing for domestic shipping lines.
- WMS integration complexity:Provincial warehousing operators struggle to connect legacy inventory systems with e-commerce marketplace APIs for real-time stock visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Freight and Logistics Market |
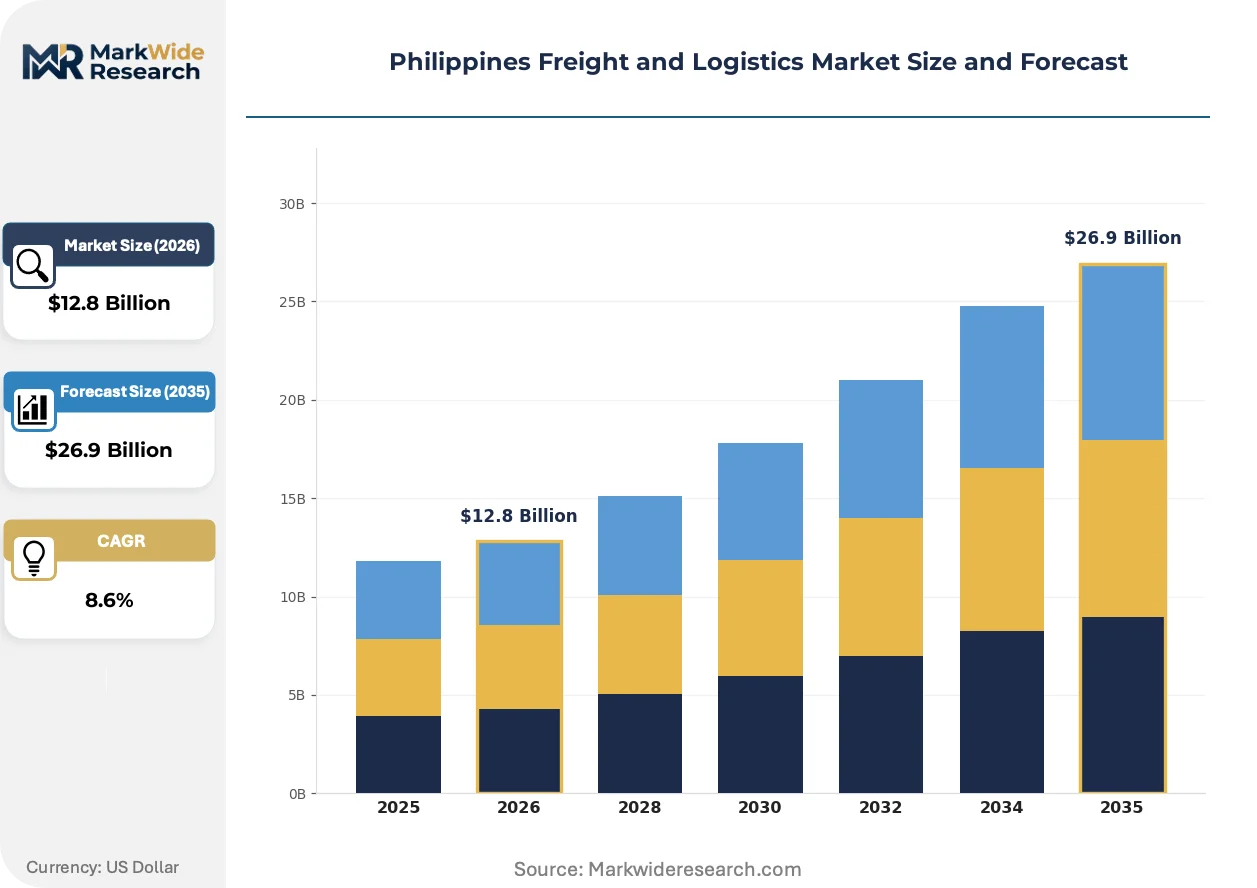
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
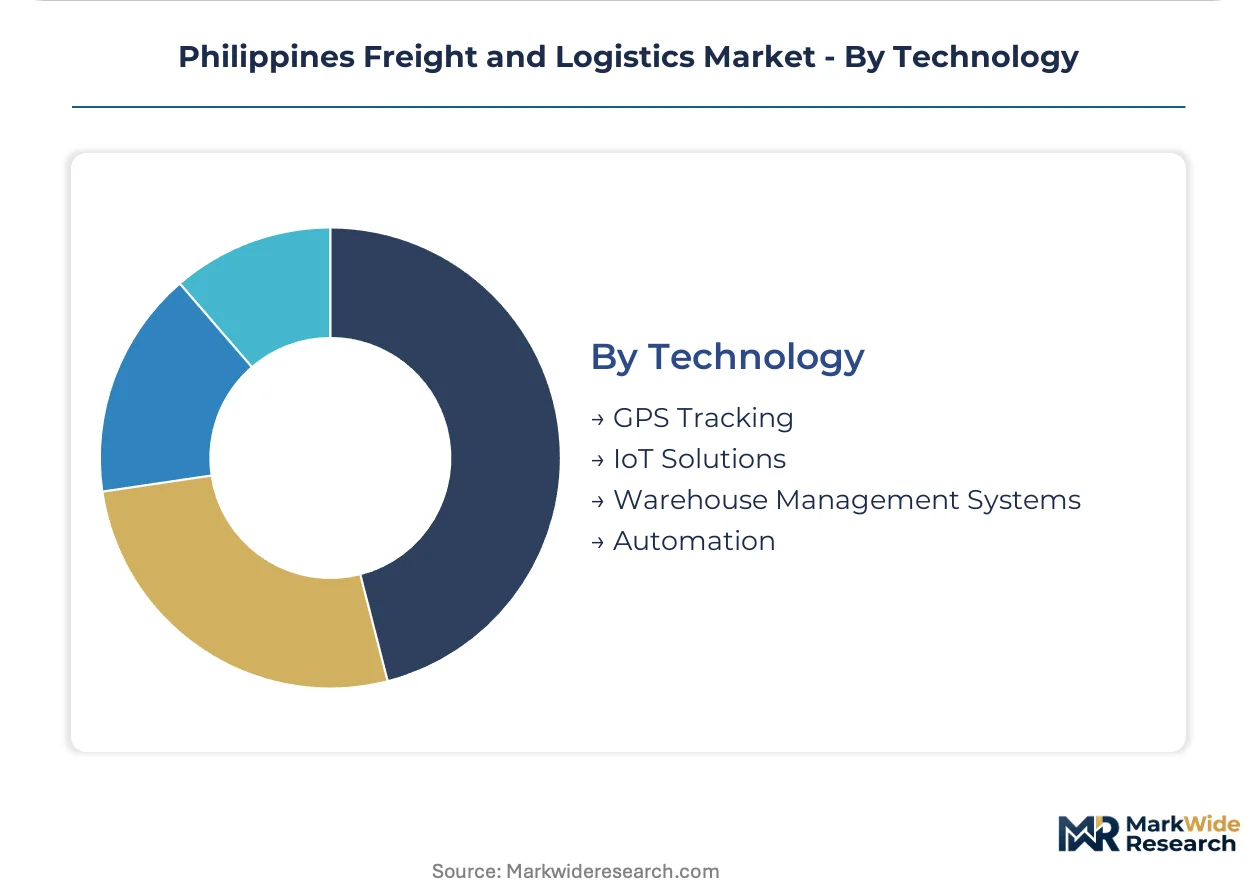
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Custom Brokerage Logistics Mode: Road, Air, Sea, Rail End User: Retail, Manufacturing, E-commerce, Pharmaceuticals Technology: GPS Tracking, IoT Solutions, Warehouse Management Systems, Automation |
| Companies Covered | SM Investments Corp. (including 2GO Group), LBC Express Holdings, Inc., DHL Group, Royal Cargo, DSV A/S (including DB Schenker), FedEx Corporation, United Parcel Service (UPS), JRS Express, Kuehne + Nagel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Freight and Logistics Market Strategic Shifts
Digital freight platforms and automated port systems are compressing quotation-to-delivery cycles across the archipelago, while regulatory pressure on emissions and safety is accelerating fleet replacement decisions.
Blockchain-enabled bill of lading systems are expanding into cross-border documentation workflows between Philippine exporters and ASEAN destination ports. Electronics manufacturers in Calabarzon are piloting these platforms to reduce customs clearance disputes with Bureau of Customs examiners. The technology is expanding into trade finance instruments, enabling faster supplier payment cycles for SMEs lacking traditional banking collateral.
Maritime Industry Authority emissions monitoring rules are mandating exhaust gas cleaning systems for vessels operating the Manila-Cebu-Davao triangle. Domestic shipping operators face dry-dock retrofit deadlines or fleet replacement decisions. The regulation most affects Ro-Ro operators serving Mindanao agricultural exporters, who are consolidating routes to maximize vessel utilization rates.
Shipper consolidation around integrated logistics providers is displacing fragmented broker relationships in Metro Manila import-export corridors. Electronics and automotive parts buyers are bundling freight forwarding, customs brokerage, and warehousing under single-contract arrangements. This pattern is most visible among Korean and Japanese manufacturing affiliates in Cavite and Laguna industrial zones.
Philippines Freight and Logistics Market Segmentation

The Philippines' archipelagic geography fragments freight flows across 7,600 islands, making service type and logistics mode selection critical for cost efficiency. Segmentation reveals where embedded multimodal solutions outperform standalone services in inter-island corridors.
Service Type:
Standalone transportation and warehousing operations dominate provincial markets, while Metro Manila enterprises increasingly bundle forwarding and brokerage into integrated contracts.
- Transportation:Road freight accounts for the majority of domestic tonnage moved, with Pan-Philippine Highway congestion pushing Calabarzon manufacturers toward night-time scheduling. Provincial fleet operators struggle with fuel surcharge mechanisms that larger carriers deploy against diesel volatility.
- Warehousing:Bonded facilities in Metro Manila command premium margins, while temperature-controlled space concentrates near Manila and Cebu ports for pharmaceutical GDP compliance. Cold storage investments lag banana and pineapple export growth from Mindanao.
- Freight Forwarding:Customs clearance velocity differentiates providers, with Bureau of Customs trade facilitation reforms compressing documentation cycles for accredited operators.
- Custom Brokerage:Anti-Red Tape Authority streamlining mandates are automating duty calculations, reducing manual intervention for repeat shippers in electronics corridors.
Volume placements concentrate in Transportation; the faster expansion belongs to Warehousing.
Logistics Mode:
Cost tier stratification separates premium air cargo from economy sea freight, with rail capturing bulk commodities and road serving time-sensitive manufacturing inputs.
- Road:Dominates last-mile delivery to e-commerce fulfillment stations across Luzon, though chronic congestion on the Pan-Philippine Highway erodes transit reliability for just-in-time automotive parts.
- Sea:Roll-on/roll-off vessels bridge the archipelago's inter-island gaps, with Maritime Industry Authority age limits forcing fleet consolidation among Mindanao agricultural exporters.
- Air:Express parcel services concentrate at Manila and Cebu international gateways, serving electronics and pharmaceutical shippers requiring sub-48-hour ASEAN connectivity.
- Rail:Limited to bulk commodity corridors, primarily serving cement and agricultural inputs between Laguna industrial zones and Manila port staging areas.
Sea freight handles the heaviest tonnage; air cargo is climbing the fastest on e-commerce express demand.
End User:
Application intensity varies sharply, with e-commerce and pharmaceuticals demanding real-time visibility while manufacturing prioritizes cost predictability.
- E-commerce:Shopee and Lazada marketplace volumes are driving refrigerated last-mile station deployment across Visayas and Mindanao provinces, requiring third-party logistics providers to invest in temperature-controlled container fleets.
- Manufacturing:Korean and Japanese automotive and electronics affiliates in Cavite and Laguna industrial zones bundle forwarding, brokerage, and warehousing under single-contract arrangements to reduce vendor management overhead.
- Retail:Traditional distribution networks face margin pressure from direct-to-consumer platform alternatives, consolidating procurement around integrated providers with nationwide cold chain coverage.
- Pharmaceuticals:Food and Drug Administration cold chain validation requirements for vaccines and biologics are creating certified logistics service provider niches with GDP-compliant warehousing and transport documentation.
Manufacturing retains the largest contract values; e-commerce is gaining share fastest on fulfillment network expansion.
Technology:
Maturity gaps separate legacy provincial operators from Metro Manila early adopters, with automation investments concentrated in bonded export zones.
- Warehouse Management Systems:Real-time inventory visibility integrates e-commerce marketplace APIs, though provincial operators struggle with legacy system connectivity and staff training costs.
- GPS Tracking:Fleet telematics penetration is highest among Calabarzon manufacturers monitoring subcontractor compliance, with diesel theft detection adding operational security value.
- IoT Solutions:Cold chain monitoring devices track temperature excursions for tuna exporters in General Santos and shrimp shipments from Zamboanga, with Bureau of Fisheries and Aquatic Resources mandates accelerating sensor deployment.
- Automation:Sortation robotics concentrate in Metro Manila parcel hubs serving e-commerce peak volumes, with payback periods limiting adoption among mid-size provincial freight operators.
GPS Tracking commands the widest installation base; automation shows the steepest expansion trajectory in Manila gateway facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper-gold porphyry deposits anchor Luzon's industrial freight corridors. Nickel laterite reserves concentrate in Surigao and Palawan. These mineral localities drive heavy equipment logistics and bulk cargo vessel demand across the archipelago.
Metro Manila
E-commerce fulfillment stations and bonded warehousing zones concentrate container throughput at Manila North Harbor and South Harbor terminals. The Department of Transportation's port modernization program is expanding roll-on/roll-off berthing capacity. Electronics manufacturers in Caloocan and Quezon City industrial parks are compressing supplier delivery windows through integrated forwarding contracts.
Calabarzon
Automotive assembly plants in Santa Rosa and electronics clusters in Cavite and Laguna generate just-in-time road freight demand along the Pan-Philippine Highway. Bureau of Customs trade facilitation reforms are accelerating clearance cycles for repeat shippers in these export zones. Cold storage investments lag behind processed food output from Batangas agro-industrial facilities.
Central Visayas
Cebu City's international gateway status drives air cargo express services for semiconductor and furniture exporters. Maritime Industry Authority vessel age limits are forcing fleet consolidation among inter-island operators serving Bohol and Negros Oriental agricultural shippers. Mactan port expansion is adding refrigerated container yard capacity for tuna transshipment.
Davao Region
Banana and pineapple export volumes from Davao del Norte and Compostela Valley are outpacing bonded cold storage availability. Bureau of Fisheries and Aquatic Resources cold chain mandates are accelerating reefer investments among Mindanao logistics providers. The Davao International Container Terminal is adding vessel calls to reduce Manila port diversion costs.
Western Mindanao
Tuna canneries in General Santos and shrimp aquaculture in Zamboanga drive temperature-controlled container demand through the Celebes Sea corridor. Food and Drug Administration pharmaceutical GDP compliance requirements are creating certified logistics niches for vaccine distribution to Bangsamoro health facilities. Ro-Ro operators are consolidating routes to maximize vessel utilization on aging fleets.
Philippines Freight and Logistics Market Competitive Environment
Capacity expansion dominates the current landscape as operators retrofit roll-on/roll-off fleets and build refrigerated last-mile networks. The market structures around three tiers: integrated multimodal providers with international gateway control, domestic specialists with inter-island vessel networks, and franchise-operated parcel couriers with provincial penetration. Strategic archetypes include capital-heavy shipping consolidators, technology-enabled freight matchers, and compliance-certified cold chain operators. Fleet modernization and strategic partnerships represent the dominant competitive moves, with dry-dock retrofit deadlines forcing replacement decisions and e-commerce platforms seeking dedicated fulfillment alliances.
Among integrated multimodal providers, Royal Cargo anchors inter-island heavy freight through specialized vessel specifications, while DHL Group exemplifies international gateway control at Manila and Cebu ports. LBC Express Holdings occupies a position within the franchise-operated parcel tier, sustaining nationwide last-mile coverage through station-based provincial networks. These three represent distinct archetypes: domestic shipping consolidation, cross-border express integration, and distributed retail logistics.
| Leading Market Players |
|---|
| SM Investments Corp. (including 2GO Group) |
| LBC Express Holdings, Inc. |
| DHL Group |
| Royal Cargo |
| DSV A/S (including DB Schenker) |
| FedEx Corporation |
| United Parcel Service (UPS) |
| JRS Express |
| Kuehne + Nagel |
| Others |
Value Chain & Pricing Dynamics
E-commerce fulfillment compression is forcing third-party logistics providers to unbundle last-mile services from core freight contracts, exposing standalone transportation margins to spot-market volatility while integrated warehousing-forwarding bundles retain pricing power.
Pricing Analysis
Service bundling separates integrated logistics contracts from standalone freight quotes, with temperature-controlled container guarantees and real-time visibility APIs commanding premiums over basic port-to-port arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with GDP-compliant pharmaceutical logistics and Maritime Industry Authority safety-rated vessels anchoring top tiers. Cost compression in provincial road freight is intensifying because diesel volatility outpaces fuel surcharge recovery mechanisms for mid-size fleet operators. E-commerce marketplace sellers exhibit highest price sensitivity, while Korean and Japanese manufacturing affiliates in Cavite and Laguna prioritize reliability over rate minimization.
Supply Chain Analysis
Freight cost stratification across the archipelago's 7,600 islands forces inter-island cargo to flow through Manila and Cebu port chokepoints, with roll-on/roll-off vessel specifications determining access to Mindanao agricultural corridors. Equipment manufacturing draws from China, South Korea, and Japan for reefer container production and vessel engine systems. Single-source vulnerability concentrates in European cold chain monitoring device suppliers serving tuna exporters in General Santos. Distribution runs through bonded warehousing zones in Metro Manila before radiating to provincial last-mile stations via franchise-operated parcel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital freight matching platforms are displacing legacy broker networks across Luzon manufacturing corridors, compressing quotation cycles from days to hours while automated port systems reshape vessel scheduling economics.
For Market Incumbents: Deepen inter-island vessel fleet consolidation to capture Maritime Industry Authority modernization mandates, retrofitting roll-on/roll-off specifications before dry-dock deadlines strand non-compliant assets. Secure backward integration into refrigerated container leasing pools to defend margin position against spot-market reefer shortages during peak harvest seasons.
For New Entrants and Emerging Players: Blockchain-enabled bill of lading systems offer a technology-first wedge into cross-border documentation workflows between Calabarzon electronics exporters and ASEAN destination ports. Target Mindanao bonded warehousing zones in Davao and Cagayan de Oro, where banana and pineapple export growth outpaces certified cold storage availability. Partner with e-commerce marketplace aggregators for dedicated fulfillment station alliances.
For Investors and Strategic Acquirers: The window for entry favors capital-heavy shipping consolidators with fleet replacement balance sheet capacity. Long-term viability hinges on exposure to pharmaceutical GDP compliance certification and agricultural cold chain mandates. Watch Bureau of Fisheries and Aquatic Resources enforcement intensity as inflection indicator for reefer equipment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization Program | Maritime Industry Authority age limits force Ro-Ro replacement decisions ahead of safety inspection deadlines. |
| Integrated Logistics Contracting | Electronics manufacturers in Cavite bundle forwarding, brokerage, and warehousing under single-vendor arrangements. |
| Digital Freight Platform Launch | Trucking apps connecting Calabarzon manufacturers with Batangas backhaul capacity reduce empty-mile ratios. |
| Cold Chain Certification Investment | Food and Drug Administration GDP requirements create defensible niches for vaccine distribution logistics. |
| Strategic Port Alliance | Davao International Container Terminal expansion reduces Manila diversion costs for Mindanao agricultural exporters. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fleet operations managers, port authority planners, customs brokerage principals, and cold chain compliance officers. Bureau of Customs trade facilitation reports, Maritime Industry Authority vessel registration databases, Department of Transportation infrastructure project disclosures, and Bureau of Fisheries and Aquatic Resources cold chain mandate circulars provided quantitative foundations. Bottom-up tonnage estimates from individual carrier networks reconciled with top-down GDP-linked freight intensity models.
Data-stream reconciliation across service type, logistics mode, end-user vertical, and technology adoption dimensions produced volume and value outputs over the projection horizon. Mode-specific CAGRs derived from fleet capacity expansion pipelines, e-commerce fulfillment station deployment schedules, and bonded warehousing construction permits. Forecast inputs incorporated Pan-Philippine Highway widening completion trajectories and refrigerated container import duty structures.
Several conditions sit outside the modeled scope, including Bangsamoro autonomous region security disruptions, fuel subsidy policy reversals, and unforeseen vessel casualty events. Forecasts reflect documented assumptions about regulatory enforcement consistency and infrastructure program continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
Asia Pacific Finished Vehicle Logistics Market
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
Unit Load Device Market
Logistics and Shipping
Food Delivery Logistic Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Global 3PL in Cold Chain Logistics Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
UK Freight Forwarding Market