
 Vehicle Wash System Market | 2026-2036
Vehicle Wash System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Wash System Market Outlook
Multi-source procurement among large-format car wash chains is realigning supplier relationships across the vehicle wash equipment sector. WashTec AG leverages its European manufacturing footprint to sustain long-term service contracts with major operators. Otto Christ AG anchors its position through specialized conveyor systems for high-throughput tunnel applications. Daifuku Co. Ltd. competes in the automated logistics integration space, extending its industrial automation expertise into wash system material handling.
A vehicle wash system comprises mechanical, electrical, and fluid-handling subsystems designed to clean exterior vehicle surfaces through automated or semi-automated processes, typically operating at water pressures between 1,000 and 2,500 PSI and incorporating reclaim systems that filter and reuse up to 80 percent of process water. These systems serve commercial operators seeking throughput optimization, regulatory compliance on effluent discharge, and labor cost reduction. Touchless systems command premium positioning due to their compatibility with advanced vehicle coatings and wrap finishes, while in-bay automatic configurations dominate the installed base across North American gas station and convenience store channels. Water recycling technology represents the fastest-growing technology segment as drought-prone regions tighten usage restrictions and operators face escalating municipal sewer discharge fees.
The EPA administers Clean Water Act provisions governing industrial effluent from commercial wash facilities, while California's State Water Resources Control Board imposes stricter total dissolved solids limits than federal baselines. OSHA standards on chemical handling and slip hazards shape operator training requirements and equipment guarding specifications. Stakeholders must monitor how evolving state-level water scarcity policies and emerging PFAS screening protocols for cleaning chemistries reshape equipment specification and site permitting timelines.
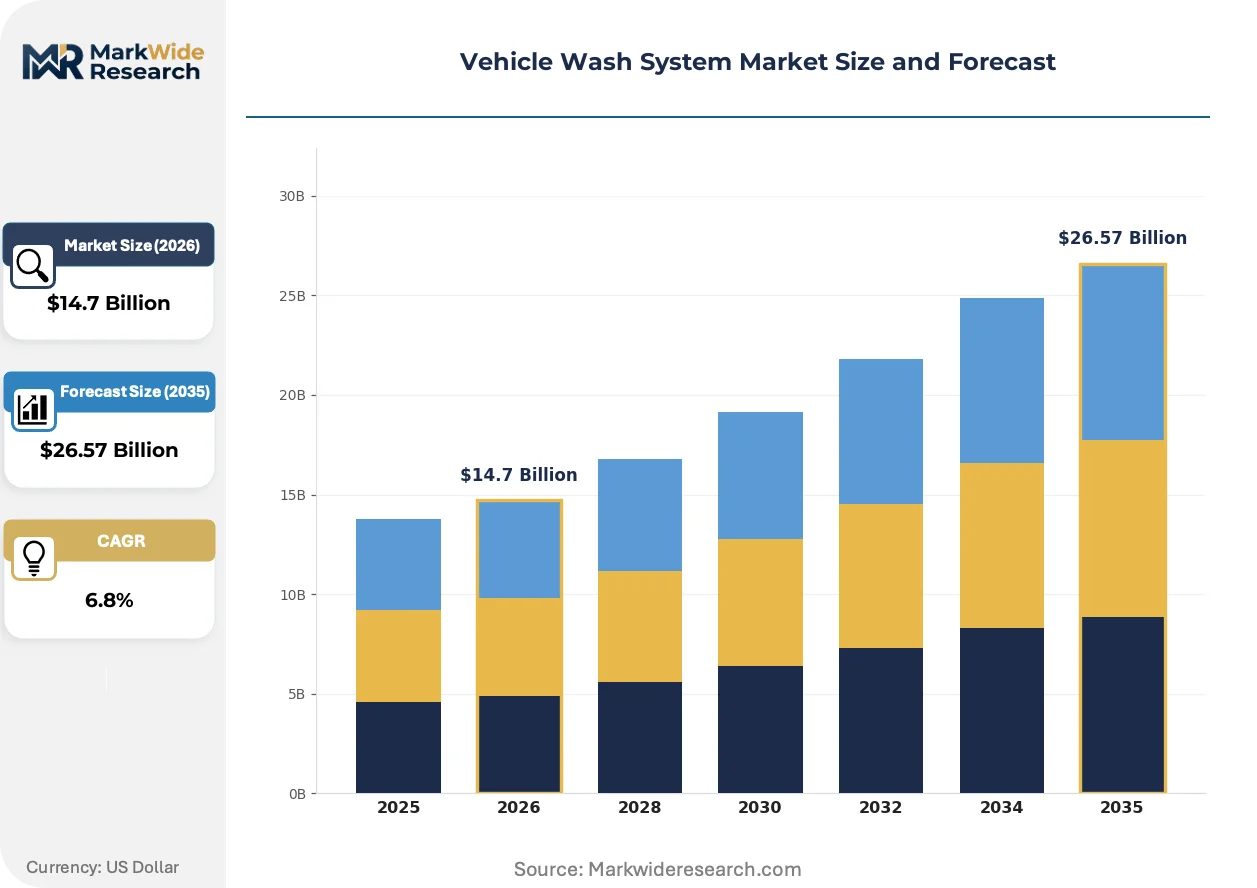
Market Dynamics
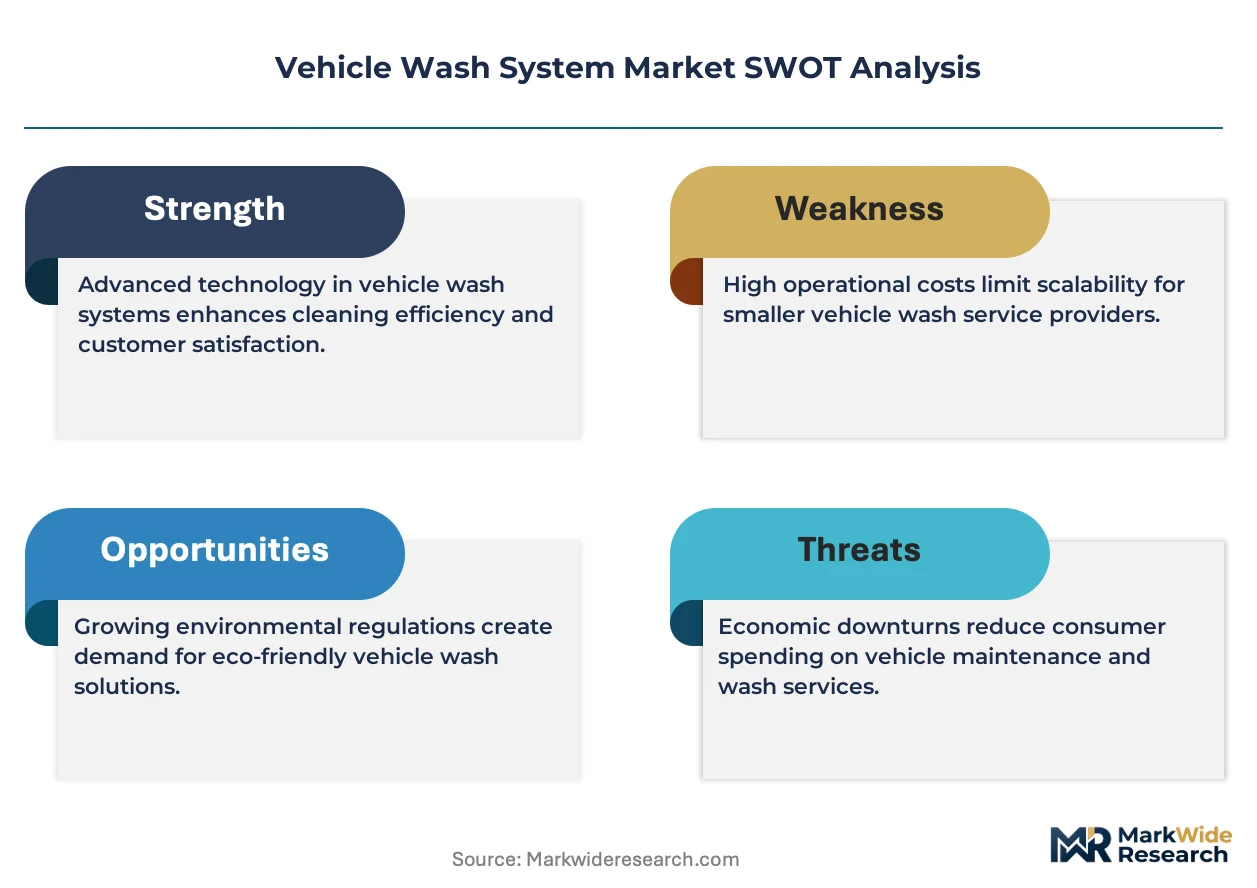
Water reclamation mandates from EPA and state-level regulators are forcing equipment replacement cycles across the installed base, compressing operator capital planning horizons while elevating specification requirements for new system purchases.
Growth Catalysts
- California's Title 22 Water Reuse Standards:Municipal discharge restrictions in drought-prone counties accelerate tunnel system upgrades. Operators face penalties for exceeding total dissolved solids thresholds.
- Fleet electrification programs:Commercial vehicle operators with battery-electric buses and delivery vans require specialized low-pressure wash protocols to protect high-voltage components and sensor arrays.
- Touchless nozzle arrays:Ceramic coating compatibility drives adoption among premium detailing chains serving wrapped and PPF-protected vehicles.
Market Restraints
- Stainless steel input volatility:Conveyor frame and arch fabrication costs fluctuate with nickel pricing, squeezing equipment margins during contract bidding cycles.
- Regional supplier concentration:High-pressure pump assembly clusters in Germany and Italy create exposure to trans-Atlantic shipping disruptions and tariff uncertainty.
- Site footprint requirements:Underground water reclamation tanks demand 15,000+ square foot parcels, excluding urban infill locations from tunnel system deployment.
Strategic Opportunities
- India's Smart Cities Mission:Municipal bus fleet automation creates demand for high-throughput wash infrastructure at depots in Bangalore, Hyderabad, and Pune.
- Subscription membership models:Unlimited wash plans at express exterior tunnels reshape customer lifetime value calculations and equipment utilization rates.
- IoT-enabled predictive maintenance:Sensor-integrated brush motors and chemical dosing systems reduce unplanned downtime through condition-based servicing protocols.
Industry Challenges
- PFAS chemistry screening:Emerging state-level protocols for per- and polyfluoroalkyl substances in surfactant formulations complicate chemical supplier qualification and inventory management.
- Skilled technician scarcity:PLC programming and high-pressure hydraulic troubleshooting expertise concentrates among aging workforces in Midwestern US manufacturing corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Wash System Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Systems, Manual Systems, Touchless Systems, In-Bay Systems Technology: Water Recycling, Foam Technology, Conveyor Belt, High-Pressure Spraying End User: Commercial Car Washes, Gas Stations, Fleet Operators, Residential Users Service Type: Maintenance Services, Installation Services, Cleaning Products, Equipment Rental |
| Companies Covered | WashTec AG, Otto Christ AG, Daifuku Co. Ltd., Istobal S.A., Coleman Hanna Carwash Systems, Ryko Solutions Inc., Autec Inc., Sonny’s Enterprises Inc., Oasis Car Wash Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Wash System Market Strategic Shifts
Digitalization of wash system control architectures is compressing maintenance response times while enabling remote performance optimization. Equipment differentiation now centers on data integration capabilities rather than mechanical throughput specifications alone.
Modular water reclamation skids with integrated membrane bioreactor technology are decentralizing treatment infrastructure away from centralized municipal hookups. Regional express wash chains in Texas and Arizona deploy containerized reclaim units to bypass sewer connection delays. This distributed approach accelerates site activation timelines from 18 months to under 6 months in jurisdictions with constrained utility capacity.
REACH restrictions on perchloroethylene and trichloroethylene in industrial degreasing chemistries are forcing reformulation of presoak and tire cleaning products. European equipment manufacturers face compliance verification costs for exported systems. The regulatory burden falls heaviest on tunnel operators running high-volume commercial programs with chemical-intensive wash packages.
Fleet procurement departments now bundle wash system maintenance into broader vehicle lifecycle management contracts. Third-party service providers displace OEM service networks for chemical supply and preventive maintenance. This consolidation trend is most pronounced among North American grocery and parcel delivery fleets with 500+ vehicle counts and centralized asset management functions.
Vehicle Wash System Market Segmentation
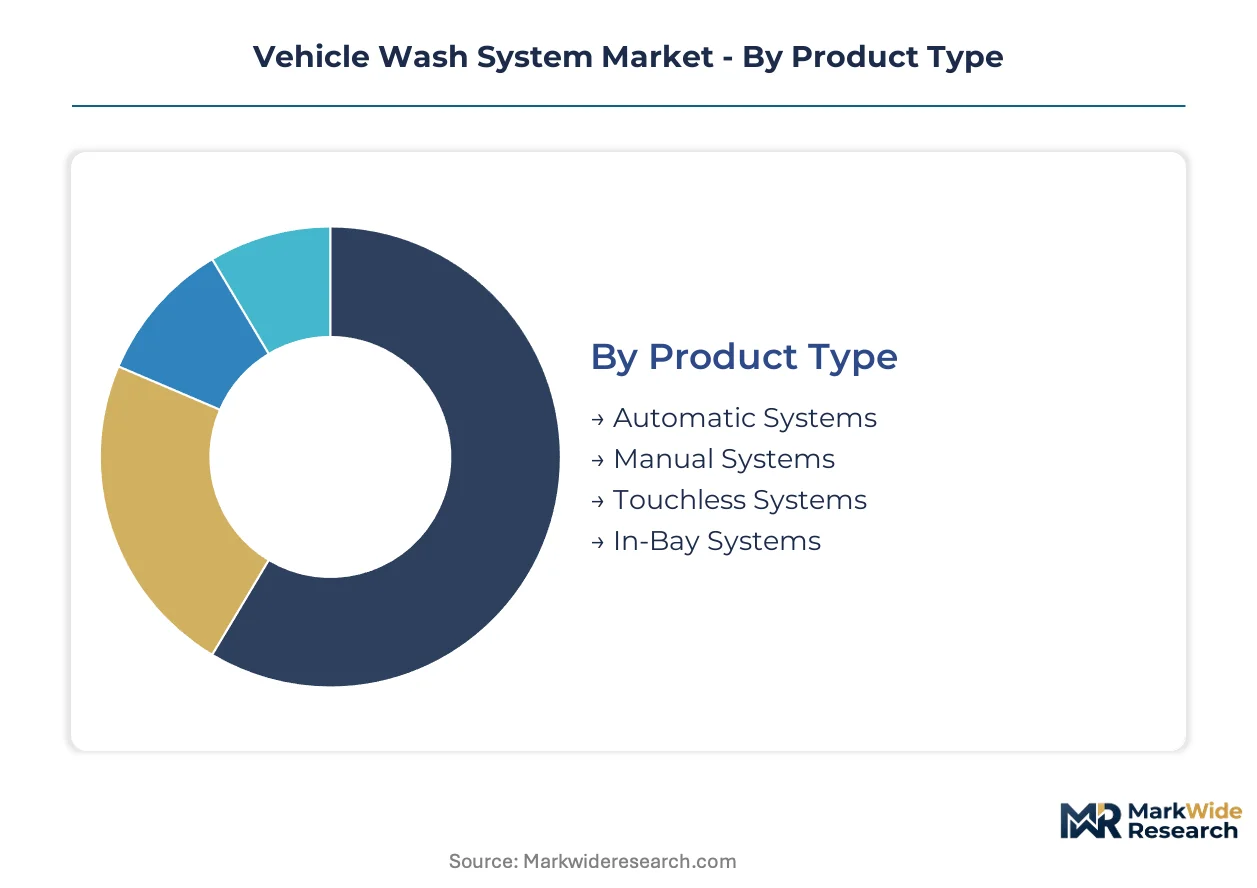
Equipment specification varies sharply across operator scale and regulatory environment. Product architecture, reclamation technology, and service bundling determine capital deployment patterns and margin structures for suppliers.
Product Type:
System architecture pivots on throughput requirements and site constraints.
- Automatic Systems:Tunnel configurations process 60-120 vehicles hourly through integrated conveyor, brush, and drying modules. Fleet operators in Texas and California deploy these at centralized depots to minimize vehicle downtime during maintenance windows.
- Touchless Systems:High-pressure nozzle arrays eliminate physical contact with vehicle surfaces. Premium detailing chains serving wrapped and ceramic-coated vehicles specify these to prevent finish damage, commanding price premiums over friction-based alternatives.
- In-Bay Systems:Self-contained units fit constrained footprints at gas stations and convenience stores.
- Manual Systems:Pressure-wand configurations persist at independent operators with low volume thresholds.
Automatic systems lead on scale; touchless systems lead on momentum.
Technology:
Water stewardship specifications are reshaping equipment procurement priorities.
- Water Recycling:Membrane bioreactor and reverse osmosis skids filter and reuse process water, cutting municipal discharge volumes by up to 80 percent. Drought-prone jurisdictions in Arizona and Nevada mandate these systems for new permits.
- High-Pressure Spraying:Precision nozzle arrays operate between 1,000 and 2,500 PSI, balancing cleaning efficacy with sensor protection on electrified fleet vehicles.
- Foam Technology:Chemical application systems reduce water consumption per wash cycle.
- Conveyor Belt:Material handling subsystems integrate with automated logistics infrastructure at high-volume tunnel installations.
Water recycling technology is gaining share fastest; high-pressure spraying maintains the broadest installed base.
End User:
Customer type dictates specification complexity and contract structure.
- Fleet Operators:Municipal bus authorities and parcel delivery networks require high-throughput infrastructure with specialized low-pressure protocols for battery-electric vehicles. Procurement departments bundle wash maintenance into lifecycle management contracts spanning 500-plus vehicle counts.
- Commercial Car Washes:Express exterior chains deploy subscription membership models that maximize equipment utilization rates through predictable volume flows.
- Gas Stations:Convenience store channels favor compact in-bay configurations with minimal staffing requirements.
- Residential Users:Consumer-grade pressure washer attachments represent a peripheral market segment with limited supplier engagement.
Fleet operators lead on contract value; commercial car washes lead on deployment velocity.
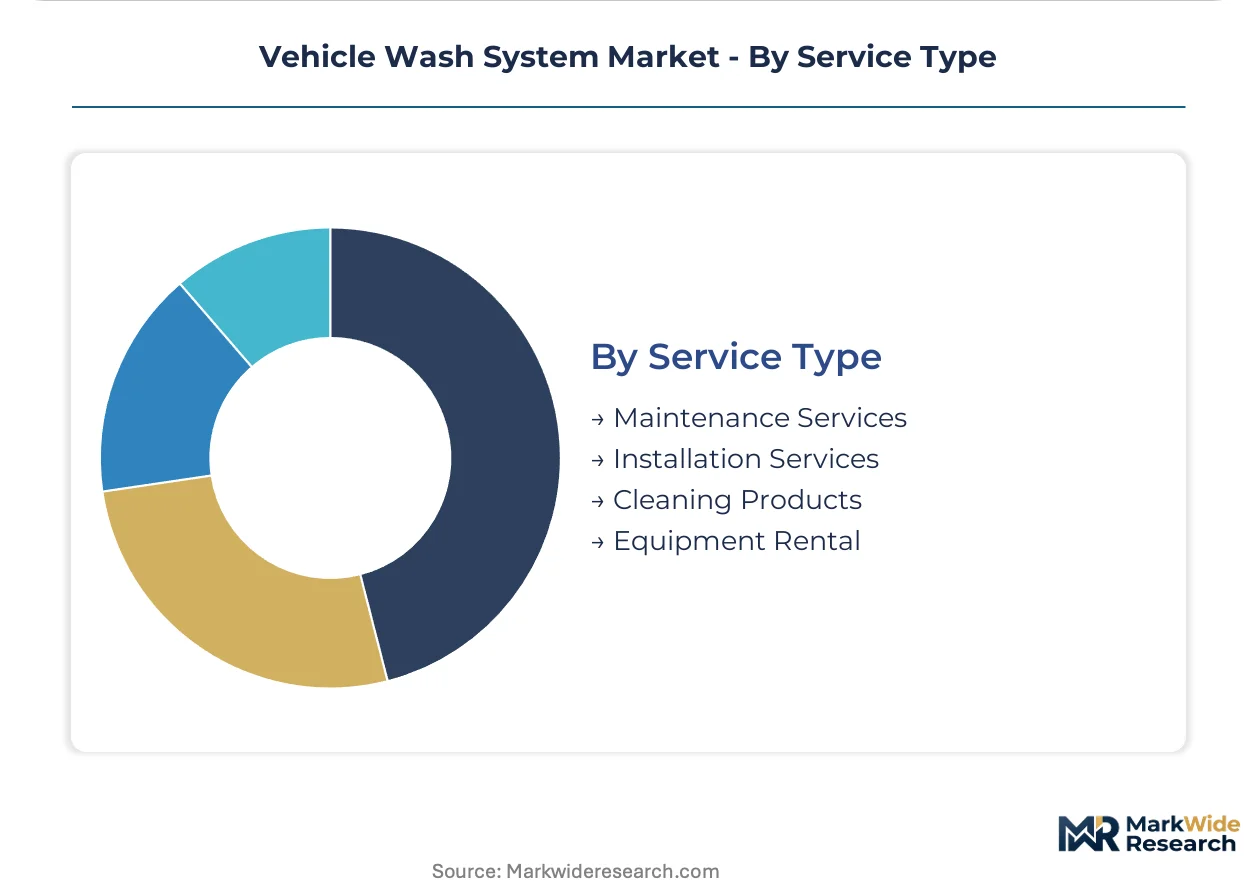
Service Type:
Revenue models are shifting from equipment sale toward recurring service relationships.
- Maintenance Services:Preventive programs covering brush motor replacement, chemical dosing calibration, and PLC troubleshooting reduce unplanned downtime. Third-party providers displace OEM networks for multi-site fleet contracts.
- Cleaning Products:Presoak, detergent, and protectant formulations face emerging PFAS screening protocols from state-level regulators, complicating supplier qualification.
- Installation Services:Site preparation and utility connection work accelerates system activation timelines.
- Equipment Rental:Short-term deployment options serve seasonal operators and construction fleet managers.
Maintenance services lead on margin stability; cleaning products face the steepest regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement patterns diverge sharply across jurisdictions as water scarcity regulations and fleet electrification timelines create compliance-driven arbitrage opportunities. Manufacturers are relocating final assembly capacity toward markets with stable permitting frameworks and concentrated commercial vehicle density.
United States
Express exterior tunnel chains in Texas and Arizona deploy containerized water reclamation units to bypass municipal sewer connection delays. EPA Clean Water Act enforcement elevates total dissolved solids monitoring costs for operators in drought-prone counties. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate fleet depot automation projects for parcel delivery networks.
Germany
Industrial automation expertise from automotive logistics is transferring into high-throughput conveyor system design. REACH restrictions on perchloroethylene and trichloroethylene force reformulation of presoak chemistries for exported equipment. Stuttgart and Munich engineering corridors anchor specialized pump assembly and PLC control module fabrication.
China
Municipal bus fleet electrification programs in Beijing and Shanghai create demand for low-pressure wash protocols protecting battery enclosures and lidar sensors. Dual carbon goals accelerate water recycling mandates for commercial vehicle maintenance facilities. Yangtze River Delta manufacturing clusters supply high-pressure nozzle arrays to domestic and Southeast Asian operators.
India
Smart Cities Mission infrastructure investments in Bangalore, Hyderabad, and Pune prioritize automated depot washing for municipal transit authorities. Central Pollution Control Board effluent guidelines tighten discharge standards for commercial vehicle service facilities. Gujarat and Maharashtra industrial zones attract component assembly investment from European system integrators seeking tariff-advantaged export platforms.
Japan
Premium detailing chains serving ceramic-coated and PPF-protected vehicles specify touchless nozzle configurations to prevent finish damage. METI energy efficiency standards shape equipment specification for automated logistics integration at high-volume facilities. Nagoya and Osaka manufacturing bases supply precision pump assemblies to Asia-Pacific replacement parts channels.
Vehicle Wash System Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue IoT-enabled predictive maintenance and modular water reclamation skids as differentiation vectors. The vendor base organizes around three archetypes: European engineering houses with long-term service contract expertise, Japanese industrial automation specialists leveraging logistics integration capabilities, and North American regional fabricators serving convenience store and gas station channels. Consolidation pressure concentrates among mid-scale operators as fleet procurement departments bundle wash maintenance into centralized lifecycle contracts. Geographic expansion and strategic technology licensing represent the dominant competitive moves as suppliers seek tariff-advantaged manufacturing footprints.
Within the European engineering tier, WashTec AG and Otto Christ AG exemplify established market presence through sustained service relationships with major commercial operators. Daifuku Co. Ltd. occupies a distinct position among industrial automation specialists extending logistics expertise into wash system material handling integration. These three anchors illustrate how competitive positioning stratifies across geographic origin and technical specialization rather than scale alone.
| Leading Market Players |
|---|
| WashTec AG |
| Otto Christ AG |
| Daifuku Co. Ltd. |
| Istobal S.A. |
| Coleman Hanna Carwash Systems |
| Ryko Solutions Inc. |
| Autec Inc. |
| Sonny's Enterprises Inc. |
| Oasis Car Wash Systems |
| Others |
Value Chain & Pricing Dynamics
Fleet procurement departments with centralized lifecycle contracts command volume-based discounts that compress equipment margins while elevating specification requirements for water reclamation integration. This buyer concentration shifts pricing power toward operators bundling 500-plus vehicle maintenance programs across North American parcel delivery networks.
Pricing Analysis
Distributor markups of 15-25 percent separate OEM list pricing from end-user acquisition costs, with direct-to-fleet contracts bypassing this layer entirely. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EPA-compliant water recycling systems command premiums over baseline friction configurations. Pricing pressure stems from stainless steel input volatility tied to nickel commodity markets, squeezing fabrication margins during contract bidding cycles. Gas station and convenience store channels exhibit highest price sensitivity due to constrained capital planning horizons, while municipal bus authorities prioritize compliance over unit cost.
Supply Chain Analysis
India's phased manufacturing program and domestic-content requirements for municipal infrastructure are redirecting component sourcing toward Gujarat and Maharashtra industrial zones. High-pressure pump assembly draws from Germany and Italy, conveyor frame fabrication rests on Chinese and Mexican metalworking capacity, and PLC control modules source from Japanese and German automation specialists. Single-source vulnerability concentrates in European pump component supply, exposing North American fabricators to trans-Atlantic shipping disruptions. Distribution runs through OEM-direct channels for fleet accounts and regional equipment distributors serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water scarcity regulatory divergence between Arizona's municipal discharge restrictions and Texas's utility-connection permitting timelines creates arbitrage opportunities for containerized reclamation system deployment. Operators can exploit six-month activation timelines in Phoenix against eighteen-month sewer-connection delays in Dallas-Fort Worth metro clusters.
For Market Incumbents: Anchor service contract renewal rates through predictive maintenance platform integration, countering third-party chemical suppliers displacing OEM networks. Defend against modular water reclamation skid entrants by deepening backward integration into membrane bioreactor component production. Prioritize PLC programming certification investments to address skilled technician scarcity concentrated in Midwestern US manufacturing corridors. For New Entrants and Emerging Players: Municipal transit authorities in India's Smart Cities Mission represent the most penetrable buyer archetype, with Bangalore and Hyderabad depot automation programs lacking established service relationships. Containerized reclaim units bypassing sewer infrastructure offer white-space entry into Arizona and Nevada drought-prone jurisdictions with constrained utility capacity. Pursue equipment-as-a-service subscription models to displace capital-intensive procurement cycles among mid-scale commercial operators. For Investors and Strategic Acquirers: Industrial automation specialists extending logistics expertise into wash system material handling represent the most active acquirer category in this space. Long-term viability hinges on water stewardship technology ownership as regulatory tightening accelerates across drought-prone jurisdictions. Target acquisition profiles center on IoT-enabled predictive maintenance platforms with proven fleet operator deployments. Monitor PFAS chemistry screening protocol adoption across California and Texas as the critical inflection signal for chemical supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Water Recycling Components | Captures margin from membrane bioreactor skids mandated by Arizona and Nevada regulators. |
| IoT-Enabled Predictive Maintenance Platform Launch | Reduces unplanned downtime for fleet operators through sensor-integrated brush motor monitoring. |
| Containerized Reclamation System Geographic Expansion | Accelerates site activation timelines from eighteen months to six months in Phoenix and Dallas-Fort Worth. |
| PFAS-Compliant Chemistry Formulation Investment | Preempts California State Water Resources Control Board screening protocols affecting presoak suppliers. |
| Strategic Partnership with Fleet Lifecycle Managers | Bundles wash maintenance into centralized contracts spanning 500-plus vehicle counts for parcel delivery networks. |
Study Parameters
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market informing cross-regional pattern identification. The analysis combines structured interviews with fleet maintenance directors, commercial car wash chain operators, municipal procurement officers, equipment OEM sales executives, and water reclamation technology specialists with secondary validation from EPA enforcement databases, state water board discharge filings, SEC equipment manufacturer disclosures, and customs import records for high-pressure pump components. Bottom-up installation base estimates and top-down market sizing triangulate volume and value outputs.
Granularity-level modeling disaggregates revenue across automatic, touchless, in-bay, and manual system architectures; water recycling, high-pressure spraying, foam technology, and conveyor belt technology segments; and fleet operator, commercial car wash, gas station, and residential end-user categories. Regional regulatory cluster differences and fleet electrification penetration rates constitute additional modeling dimensions. CAGRs derive from regression analysis of historical equipment shipment data against regulatory mandate implementation timelines and drought severity indices.
Underlying measurement precision varies by segment; water recycling technology and fleet operator channels carry tighter precision than manual systems and residential categories due to disclosure concentration among publicly traded equipment suppliers and municipal procurement transparency. Forecasts reflect assumptions regarding EPA enforcement continuity, nickel price volatility moderation, and PFAS protocol adoption trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Global Fleet Maintenance Software Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market