
 Asia-Pacific Augmented and Virtual Reality in Manufacturing Market | 2026-2036
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market Analytics
GB/T standard compliance for industrial AR/VR hardware is rotating vendor eligibility across the Asia-Pacific manufacturing base. Lenovo Group leverages its enterprise server infrastructure to anchor large-scale deployment contracts with heavy machinery producers. Samsung Group competes through in-house semiconductor production that sustains supply security for VR headset displays. Sony Corporation specializes in optical component miniaturization that differentiates its industrial headset portfolio from consumer-grade alternatives.
Asia-Pacific augmented and virtual reality in manufacturing encompasses wearable display systems, spatial computing software, and sensor fusion architectures that overlay digital work instructions onto physical production environments with sub-millimeter tracking accuracy. These systems enable real-time remote expert guidance, reduce assembly errors, and compress prototype iteration cycles for capital-intensive production lines. AR Devices currently occupy the largest technology share as factory-floor durability requirements favor monocular and binocular overlays over fully immersive VR enclosures. Training Simulations represents the fastest-growing application segment as aerospace and heavy machinery producers mandate immersive safety certification programs for hazardous equipment operation. Cloud-based deployment is gaining traction among electronics manufacturers seeking centralized content management across multi-site production networks.
China's MIIT enforces GB standards for electromagnetic compatibility and optical safety that condition market access for imported AR/VR hardware. Japan's METI promotes JIS-aligned digital manufacturing roadmaps that subsidize mixed reality adoption among small and medium enterprises. South Korea's MFDS maintains medical-grade optical device standards that upstream into industrial headset certification requirements. Stakeholders must monitor evolving cross-border data localization rules that will determine whether cloud-based AR content delivery remains viable across fragmented national regulatory regimes.
Market Dynamics
China's MIIT enforcement of GB/T electromagnetic compatibility standards is rotating vendor eligibility across the Asia-Pacific manufacturing base, forcing hardware recertification cycles that compress procurement timelines for industrial AR/VR deployments.
Growth Catalysts
- Automotive OEM immersive training mandates:Heavy machinery and aerospace producers across Japan and South Korea now require VR-based safety certification for hazardous equipment operation, expanding addressable demand.
- Cloud-based deployment architectures:Electronics manufacturers in Taiwan and Vietnam seek centralized content management across multi-site production networks, reducing per-facility software licensing overhead.
- GB standards harmonization:China's MIIT alignment of electromagnetic compatibility testing with industrial equipment interoperability protocols accelerates hardware certification timelines for qualified suppliers.
Market Restraints
- Optical component supply concentration:High-resolution micro-OLED and pancake lens production clusters in South Korea and Taiwan create single-source vulnerability for headset manufacturers.
- GB/T certification cost structure:Imported AR/VR hardware faces mandatory electromagnetic compatibility and optical safety testing that adds eighteen to twenty-four months to market entry timelines.
- Technical limitation in outdoor tracking:Direct sunlight interference with optical tracking systems restricts deployment to indoor factory environments, excluding yard logistics and port operations.
Strategic Opportunities
- Vietnam electronics manufacturing corridors:Samsung and Foxconn expansion around Bac Ninh and Hai Phong creates greenfield demand for AR-guided assembly without legacy system integration burden.
- Japan METI SME digital manufacturing subsidies:Mixed reality adoption incentives for small and medium enterprises lower effective acquisition costs for domestic system integrators.
- 5G private network convergence:Ultra-reliable low-latency connectivity enables real-time remote expert guidance applications previously constrained by Wi-Fi coverage gaps in steel and chemical plants.
Industry Challenges
- Spatial computing talent scarcity:Factory-floor deployment of AR/VR systems requires technicians skilled in both industrial engineering and Unity/Unreal engine content creation, a combination rarely found in regional labor pools.
- Cross-border data localization friction:Divergent national rules on cloud-based AR content storage and transmission complicate centralized deployment models for multi-national manufacturers operating across China, Japan, and South Korea.
- Legacy MES integration complexity:Proprietary manufacturing execution systems in established automotive and heavy machinery plants resist API-based connectivity with modern spatial computing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Augmented and Virtual Reality in Manufacturing Market |
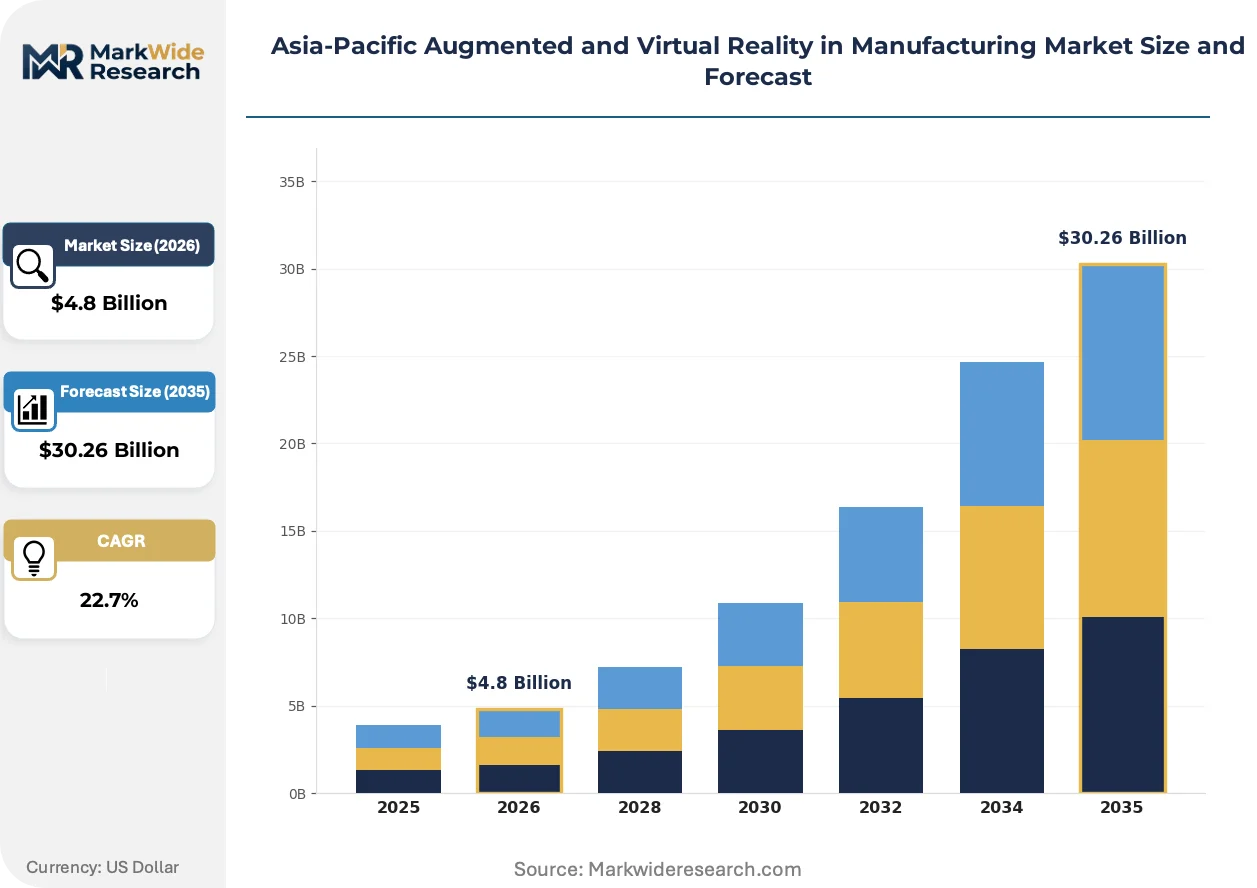
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AR Devices, VR Headsets, Mixed Reality Solutions, Software Platforms End User: Aerospace, Automotive OEMs, Electronics, Heavy Machinery Application: Training Simulations, Remote Assistance, Design Visualization, Quality Control Deployment: On-premises, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | Lenovo Group, Xiaomi Corporation, Sony Corporation, DPVR, Epson, HTC Corporation, Huawei Technologies, Kaon Interactive Inc., Samsung Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market Evolving Landscape
Industrial AR/VR hardware is fragmenting into distinct performance tiers as factory-floor durability requirements diverge from pilot-program specifications. Three technology and demand shifts are compressing vendor margins while expanding application breadth.
Optical see-through displays are bifurcating the device landscape. Waveguide-based monocular overlays deliver sub-millimeter tracking accuracy for assembly line work instructions, while binocular passthrough headsets enable immersive training simulations. Automotive OEMs in Japan and South Korea adopt the former at scale for technician guidance, whereas aerospace producers in Australia favor the latter for safety certification programs. This split is forcing component suppliers to maintain dual optical engine roadmaps without volume consolidation.
South Korea's MFDS medical-grade optical device standards are upstreaming into industrial headset certification requirements. The regulation mandates specific luminance thresholds and eye-tracking accuracy metrics that previously applied only to surgical visualization systems. Electronics manufacturers around Seoul and Suwon now face extended validation timelines as industrial hardware must satisfy medical-equivalent optical safety protocols. Domestic vendors with existing healthcare certifications capture accelerated approval pathways.
Subscription-based software licensing is displacing perpetual purchase models among mid-cap electronics manufacturers. Tier-one contract manufacturers in Taiwan and Vietnam negotiate enterprise agreements covering content creation tools, remote expert platforms, and fleet management dashboards under unified annual contracts. This shift concentrates procurement authority at regional headquarters in Singapore and Shanghai, reducing vendor direct sales touchpoints. The model is most visible in semiconductor packaging facilities seeking predictable operational expenditure structures.
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market Segmentation
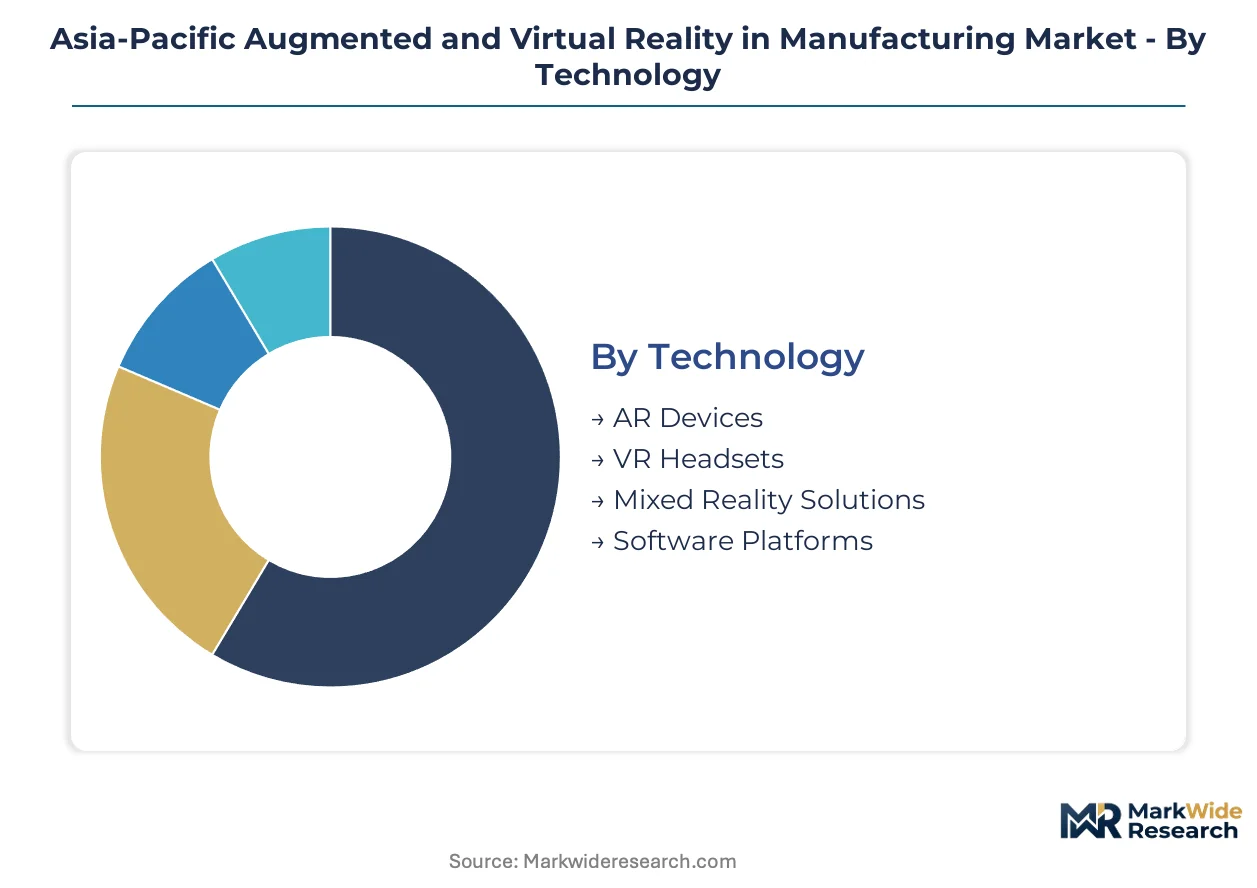
Technology choices in Asia-Pacific manufacturing AR/VR determine capital intensity and integration complexity. End-user concentration in automotive and electronics corridors shapes regional deployment patterns.
Technology:
Margin pools concentrate in optical component miniaturization and sensor fusion architectures that enable sub-millimeter tracking accuracy.
- AR Devices:Monocular and binocular overlays deliver digital work instructions onto factory floors with factory-grade durability ratings. Automotive OEMs in Japan and South Korea deploy these at scale for assembly line technician guidance, favoring waveguide-based optical see-through displays over bulkier alternatives. The dominant share belongs to AR Devices, while Mixed Reality Solutions is closing the gap fastest.
- VR Headsets:Fully immersive enclosures enable hazardous equipment training simulations with complete environmental isolation. Heavy machinery producers across Australia mandate these for safety certification programs where spatial presence reduces accident rates during procedural rehearsal.
- Mixed Reality Solutions:Passthrough headsets blend physical and digital environments for design review applications.
- Software Platforms:Spatial computing engines power content creation, fleet management, and remote expert connectivity.
AR Devices commands the installed base, though Mixed Reality Solutions gains traction where training and guidance applications converge.
End User:
Procurement authority clusters around electronics contract manufacturers seeking centralized multi-site deployment.
- Electronics:Semiconductor packaging and final assembly facilities in Taiwan and Vietnam drive volume demand for AR-guided precision work. Foxconn and Samsung expansion around Bac Ninh and Hai Phong creates greenfield deployment without legacy system integration burden. Electronics holds the largest addressable base, while Heavy Machinery shows the steepest expansion trajectory.
- Automotive OEMs:Assembly plants across Japan and South Korea mandate immersive training programs for hazardous equipment operation. METI subsidies lower effective acquisition costs for domestic system integrators serving tier-one suppliers.
- Aerospace:Australian and Japanese producers prioritize VR-based safety certification for maintenance technician qualification.
- Heavy Machinery:Capital-intensive production lines compress prototype iteration cycles through design visualization applications.
Electronics manufacturers dominate procurement volumes, with Heavy Machinery producers accelerating adoption for safety-critical operations.
Application:
Revenue concentration follows subscription licensing models that consolidate content creation and remote expert platforms.
- Training Simulations:Immersive safety certification programs for hazardous equipment operation span aerospace and heavy machinery verticals. Japan and South Korea now mandate VR-based qualification for crane operation and chemical plant maintenance, expanding addressable demand. Training Simulations leads adoption velocity, while Remote Assistance scales fastest.
- Remote Assistance:Real-time expert guidance overlays reduce assembly errors and compress troubleshooting timelines. 5G private network convergence in steel and chemical plants enables ultra-reliable low-latency connectivity previously constrained by Wi-Fi coverage gaps.
- Design Visualization:Digital twin integration accelerates prototype iteration for capital-intensive production lines.
- Quality Control:AR-guided inspection protocols standardize defect detection across multi-site manufacturing networks.
Training Simulations captures the fastest-climbing share as regulatory mandates expand, with Remote Assistance scaling through 5G infrastructure buildout.
Deployment:
Operational expenditure preferences among mid-cap manufacturers favor predictable annual licensing over capital-intensive perpetual purchases.
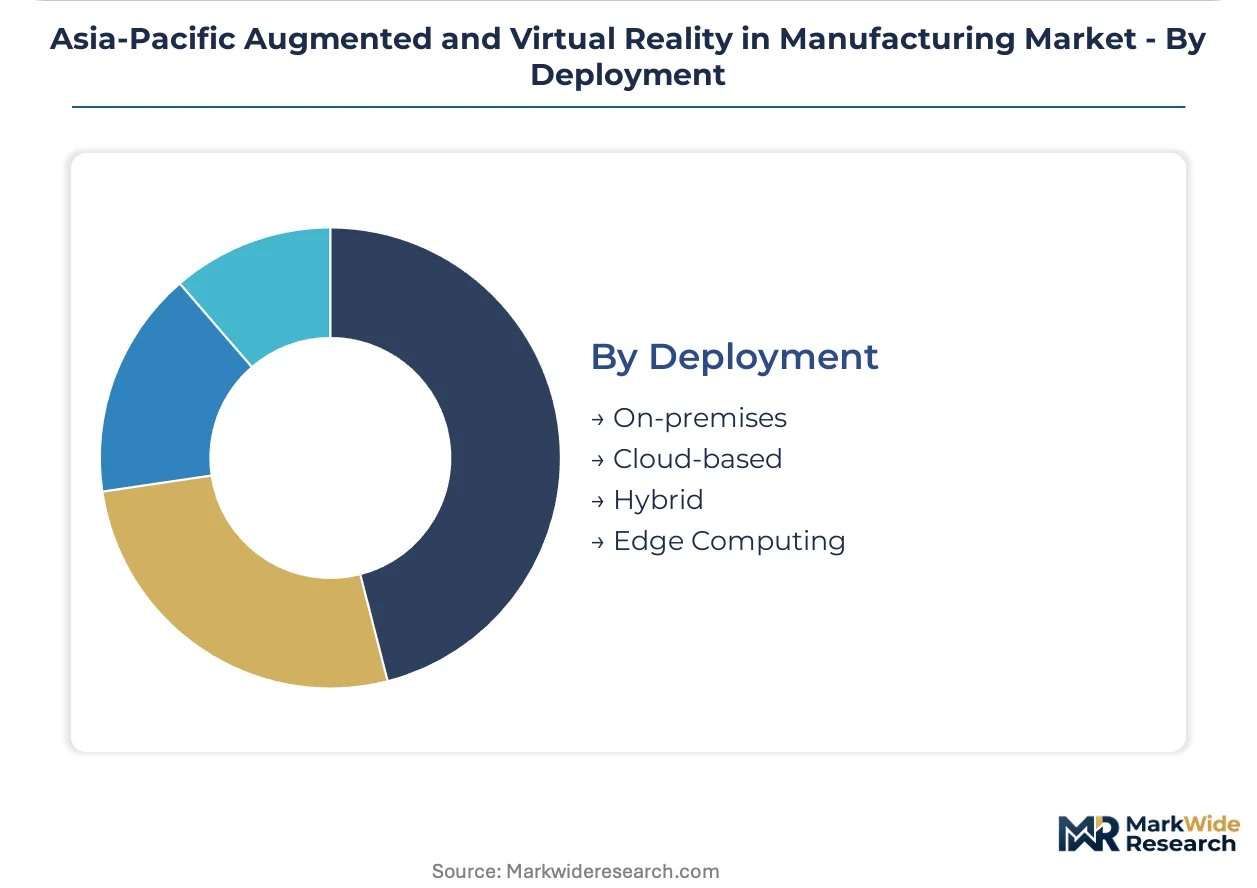
- Cloud-based:Centralized content management across multi-site production networks reduces per-facility software licensing overhead. Electronics manufacturers in Taiwan and Vietnam negotiate enterprise agreements covering fleet management dashboards under unified contracts with regional headquarters in Singapore and Shanghai. Cloud-based deployment leads new installations, though Hybrid architectures gain share fastest.
- On-premises:Air-gapped installations serve defense and critical infrastructure manufacturers with stringent data sovereignty requirements.
- Hybrid:Mixed architectures balance sensitive design data on local servers with collaborative tools in cloud environments.
- Edge Computing:Distributed processing enables real-time tracking without latency to centralized data centers.
Cloud-based deployment dominates greenfield electronics facilities, while Hybrid models penetrate established automotive plants with mixed sensitivity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The China-Laos Railway and expanding 5G private networks across ASEAN manufacturing corridors are underwriting Asia-Pacific's industrial AR/VR deployment capacity. Dense fiber backbones in South Korea and Japan enable ultra-reliable low-latency connectivity for real-time remote expert guidance applications.
China
Heavy machinery producers in Jiangsu and Shandong provinces are mandating VR-based safety certification for crane operators and chemical plant technicians. MIIT's GB/T electromagnetic compatibility standards condition market access for imported AR hardware, compressing procurement timelines for qualified domestic suppliers. The Yangtze River Delta manufacturing cluster around Shanghai anchors large-scale deployment contracts with automotive OEMs seeking factory-floor durability ratings.
Japan
Aerospace maintenance facilities in Aichi Prefecture prioritize immersive training simulations for technician qualification programs. METI subsidizes mixed reality adoption among Nagoya-based SMEs through JIS-aligned digital manufacturing roadmaps. The Chubu region's precision equipment producers integrate AR-guided assembly protocols to reduce defect rates in semiconductor packaging operations.
South Korea
Electronics contract manufacturers around Seoul and Suwon drive volume demand for waveguide-based optical see-through displays. MFDS medical-grade optical device standards upstream into industrial headset certification, extending validation timelines for imported hardware. Samsung and LG Display production clusters in Gyeonggi Province sustain captive supply security for micro-OLED panels.
Vietnam
Foxconn and Samsung expansion around Bac Ninh and Hai Phong creates greenfield demand for AR-guided precision assembly without legacy MES integration burden. The country's national telecommunications regulator accelerates 5G spectrum allocation for industrial private networks. Northern electronics manufacturing corridors are negotiating enterprise software agreements with regional headquarters in Singapore.
Australia
Mining equipment producers in Western Australia deploy VR enclosures for hazardous machinery operation training in isolated site conditions. The Therapeutic Goods Administration maintains optical safety standards that condition industrial headset import approvals. Perth-based resources technology clusters are piloting remote expert guidance applications across Pilbara iron ore operations.
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market Competitive Landscape
Listed leaders compete with private specialists across hardware certification pathways, creating tiered procurement dynamics. The vendor base concentrates around three strategic archetypes: diversified technology conglomerates with captive semiconductor supply, optical component specialists leveraging healthcare certification pathways, and enterprise software integrators anchoring cloud-based deployment contracts. Competitive moves center on electromagnetic compatibility pre-certification investments and strategic partnerships with regional system integrators.
Within the diversified technology tier, Lenovo Group and Samsung Group exemplify scale-driven players with in-house production of critical components. Sony Corporation occupies a position among optical specialists whose healthcare device certifications accelerate industrial headset approvals. Xiaomi Corporation represents the emerging hardware challenger segment competing on cost-optimized deployment packages for mid-cap electronics manufacturers.
| Leading Market Players |
|---|
| Lenovo Group |
| Xiaomi Corporation |
| Sony Corporation |
| DPVR |
| Epson |
| HTC Corporation |
| Huawei Technologies |
| Kaon Interactive Inc. |
| Samsung Group |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four-month GB/T certification lead times compress procurement windows for industrial AR/VR hardware, concentrating pricing power among domestic vendors with pre-cleared electromagnetic compatibility pathways while forcing importers to absorb extended inventory carrying costs or cede share to qualified suppliers.
Pricing Analysis
Three-tier pricing structure across medical-grade, industrial-certified, and uncertified hardware levels separates Samsung and Sony offerings from mid-tier Lenovo deployments and cost-optimized Xiaomi alternatives. Subscription-based software licensing now generates recurring revenue streams that offset hardware margin compression, with cloud-based fleet management commanding premium attach rates. Cost compression in uncertified headset tiers intensifies because Foxconn and contract manufacturers negotiate enterprise volume agreements that reset baseline pricing annually. Mid-cap electronics manufacturers in Vietnam exhibit highest price sensitivity, whereas Japanese automotive OEMs prioritize optical safety certification over unit economics.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and Taiwan Strait container availability constraints extend component delivery timelines for waveguide optical engines and micro-OLED panels. High-resolution display production clusters in South Korea and Taiwan draw from single-source lithography equipment and specialty glass substrates, creating concentrated supply vulnerability. Tariff exposure on semiconductor-grade components imported into Vietnam disrupts just-in-time assembly for Bac Ninh electronics corridors. Distribution runs through regional headquarters in Singapore and Shanghai that negotiate consolidated procurement across multi-site manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial AR/VR hardware margins are compressing toward commodity levels, yet software subscription attach rates and remote expert platform recurring revenue are expanding faster than device sales across Asia-Pacific manufacturing deployments.
For Market Incumbents: Secure GB/T electromagnetic compatibility pre-certification for next-generation optical engines to defend procurement eligibility against emerging domestic challengers. Lock long-term waveguide supply agreements with Samsung Display and LG Display before capacity allocation tightens further. Reinforce cloud-based deployment architecture leadership through API integration with legacy MES systems that resist connectivity standardization. For New Entrants and Emerging Players: Cloud-to-edge content synchronization gaps in heavy machinery safety training create immediate white-space opportunity where incumbents under-serve offline-capable VR certification programs. Target Australian mining equipment producers and Japanese SME precision manufacturers as most penetrable segments given limited incumbent field service presence. Pursue system integrator partnerships with Nagoya-based automation specialists rather than direct OEM sales approaches. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-only spatial computing platforms while hardware-dependent vendors face rising certification and component inventory burdens. Long-term viability favors acquisition targets with healthcare-derived optical safety certifications that accelerate industrial headset approvals. Monitor MFDS regulatory alignment announcements as inflection indicator for which certification pathways will dominate cross-border hardware deployment.| Strategic Initiative | Industry Significance |
|---|---|
| GB/T Pre-Certification Investment | MIIT electromagnetic compatibility clearance compresses procurement timelines for qualified suppliers against eighteen-month import delays. |
| Healthcare Certification Leverage | MFDS optical safety pathways accelerate industrial headset approvals for vendors with existing surgical visualization credentials. |
| Cloud Platform Integration | API connectivity with proprietary MES systems differentiates software vendors serving established automotive assembly plants. |
| 5G Private Network Partnership | Ultra-reliable low-latency infrastructure enables real-time remote expert guidance previously constrained by steel plant Wi-Fi gaps. |
| Optical Component Backward Integration | In-house micro-OLED and waveguide production insulates margins against South Korean and Taiwanese supply concentration risks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, METI subsidy disbursement records, and ASEAN telecommunications infrastructure databases. Primary interviews conducted with industrial automation procurement directors, plant engineers at Foxconn and Samsung facilities, and optical component sourcing managers. Secondary validation drew from customs trade data for AR/VR hardware imports, SEC 10-K disclosures from listed technology conglomerates, and GB standards publication timelines. Bottom-up facility deployment estimates triangulate against top-down market sizing from regional manufacturing output data.
Segmentation dimensions modeled include technology tier, end-use vertical, application type, and deployment architecture across the analysis window. CAGRs derive from installed base growth trajectories, replacement cycle compression, and software attach rate expansion. Forecast inputs incorporate 5G private network rollout schedules and evolving cross-border data localization enforcement patterns.
Forecasts assume regulatory continuity in China's GB/T electromagnetic compatibility regime, Japan's METI digital manufacturing subsidies, and South Korea's MFDS optical device standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Location Based VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market