
 VR Box Market | 2026-2036
VR Box Market Size, Share, and Industry Trends Forecast 2026-2036
VR Box Market Insights
CE marking under the EU Radio Equipment Directive is redrawing competitive boundaries for VR box manufacturers seeking European market access. Meta Platforms leverages its captive content ecosystem to sustain hardware attach rates, while Sony Corporation anchors its position through optical engineering specialization in display panels. HTC Corporation competes on enterprise channel depth, particularly in corporate training and simulation verticals where its Vive product line dominates installed bases.
A VR box is a head-mounted enclosure housing stereoscopic displays, motion sensors, and Fresnel or pancake lenses that map user head movements to rendered virtual environments, typically operating at refresh rates of 90 Hz or higher to minimize motion sickness. Standalone VR headsets with integrated application processors and wireless connectivity are capturing the fastest growth trajectory as they eliminate tethering to external PCs or consoles. PC-based VR headsets retain the premium tier for simulation and real estate visualization applications where GPU-rendered fidelity is non-negotiable, while mobile VR headsets have contracted to near-commodity status in emerging markets.
The FCC in the United States enforces radio frequency emissions limits that constrain transmitter power and antenna configurations in wireless VR boxes, directly shaping product architecture decisions. China's MIIT mandates network access licenses for cellular-enabled standalone headsets, creating a dual-track compliance burden for global manufacturers. Ecodesign requirements under the EU Green Deal are beginning to pressure material selection and end-of-life recycling protocols. Stakeholders must monitor how fragmented national certification timelines alter launch sequencing and inventory allocation across regional warehouses.
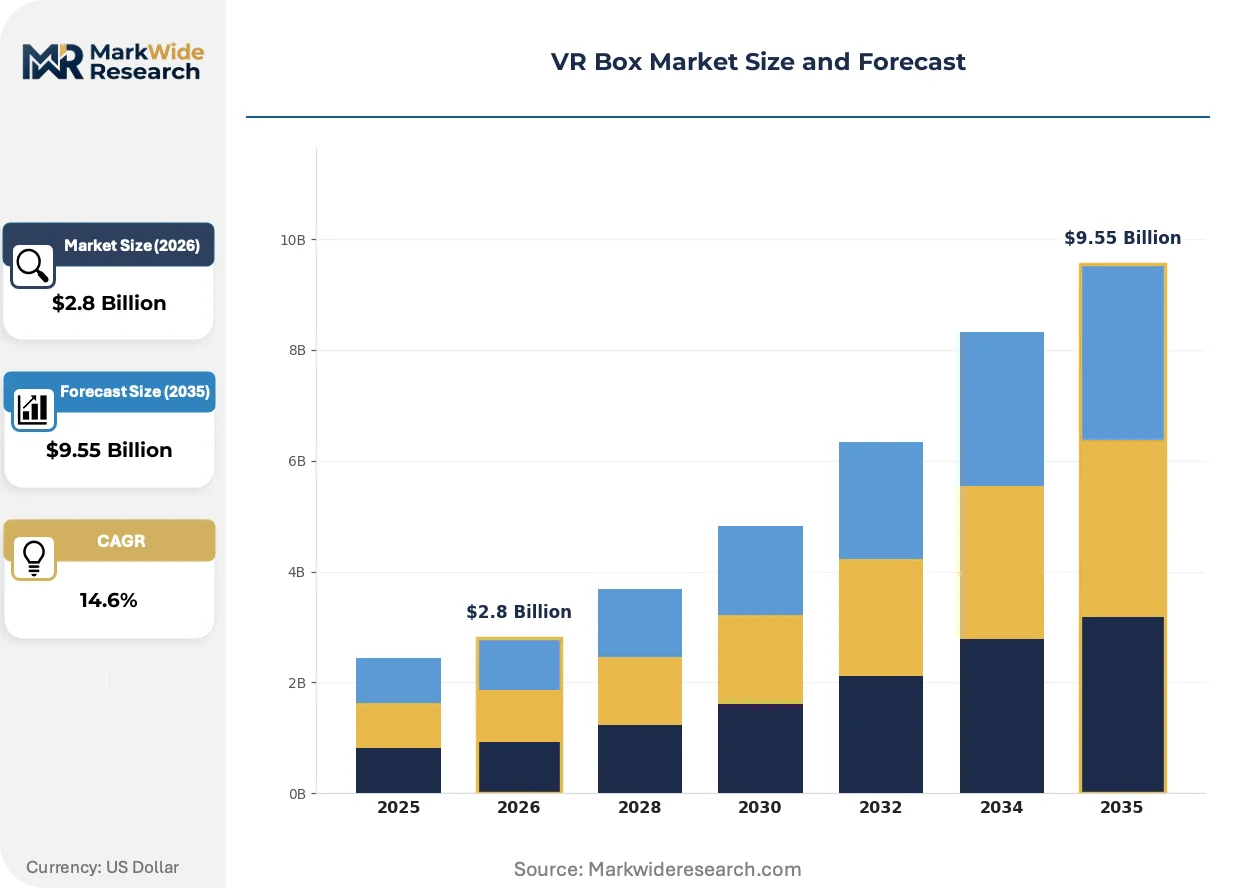
Market Dynamics
Standalone VR headsets with integrated processors are cannibalizing tethered systems as wireless fidelity reaches parity, while electromagnetic compliance costs in China and the EU are filtering out undercapitalized hardware entrants.
Growth Catalysts
- Entertainment venue deployment:Theme park operators in the United States and Japan are installing location-based VR boxes for immersive attractions, driving bulk procurement cycles.
- MIIT network access mandates:China's cellular-enabled standalone headset licensing creates captive demand for compliant domestic supply chains.
- Pancake lens diffusion:Thinner optical stacks are reducing headset weight and enabling extended wear sessions in corporate training environments.
Market Restraints
- Display panel supply concentration:High-resolution OLED and micro-OLED sources cluster in South Korean and Taiwanese fabs, creating single-source vulnerability.
- FCC RF emissions limits:Transmitter power caps constrain wireless range and antenna design flexibility for US-bound hardware.
- Smartphone-based VR substitution:Phone-docked viewers in emerging markets compete on sub-$50 price points against dedicated headsets.
Strategic Opportunities
- EU Green Deal ecodesign pressure:Material recycling mandates favor modular headset architectures with replaceable components.
- Military simulation procurement:Defense contractors in the United States are scaling VR box purchases for tactical training and mission rehearsal.
- Enterprise channel bypass:Direct sales to corporate training departments reduce margin extraction by retail intermediaries.
Industry Challenges
- Optical engineering talent scarcity:Fresnel and pancake lens design expertise concentrates in Japanese and German precision optics firms.
- Dual-track certification timelines:Parallel FCC and MIIT approval processes delay synchronized product launches across North American and Chinese markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Box Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile VR Headsets, PC-based VR Headsets, Standalone VR Headsets, Console-based VR Headsets End User: Entertainment, Education, Healthcare, Corporate Training Distribution Channel: Online Retail, Offline Retail, Third-party Distributors, Direct Sales Application: Gaming, Real Estate, Virtual Tourism, Simulation |
| Companies Covered | Meta Platforms, Sony Corporation, Samsung Electronics, HTC Corporation, Google, Microsoft, Valve Corporation, Lenovo, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Box Market Trends and Innovations
Display technology roadmaps and regulatory fragmentation are forcing hardware architects into parallel design tracks, while buyer procurement patterns are compressing product refresh cycles.
Pancake optical systems are fragmenting the premium headset tier by enabling sub-250g form factors previously unattainable with Fresnel lens stacks. Location-based entertainment operators in Dubai and Singapore are adopting these lightweight configurations for four-hour operational shifts. The technology is fragmenting vendor portfolios into ultra-portable and performance-optimized branches with incompatible supply chains.
CE marking under the EU Radio Equipment Directive is tightening electromagnetic compatibility documentation requirements for head-mounted displays with wireless transmitters. Manufacturers must submit expanded test reports covering 2.4 GHz and 5 GHz band coexistence. European distributors are demanding six-month certification buffers, forcing Asian ODMs to front-load compliance spending.
Corporate training departments are unbundling hardware procurement from content licensing, reversing the bundled subscription model that dominated early enterprise VR adoption. Industrial safety trainers in Germany and automotive manufacturers in South Korea now negotiate hardware and software contracts separately. This bifurcation pressures hardware margins while elevating content platform switching costs.
VR Box Market Segmentation
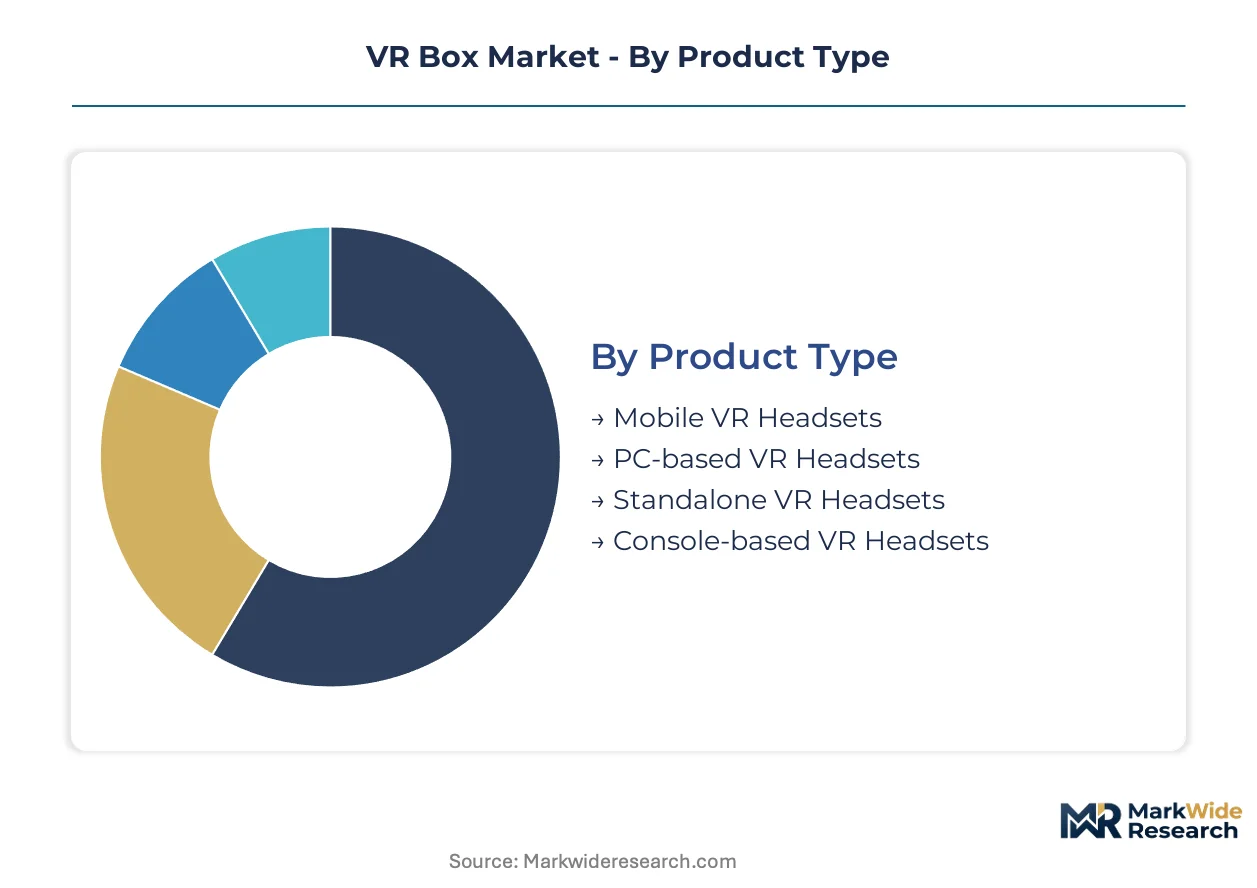
VR box segmentation reveals divergent margin architectures across hardware form factors and procurement channels. Product type stratification separates integrated-system premiums from accessory-tier commoditization, while end-user concentration in defense and enterprise verticals sustains price inelasticity absent in consumer entertainment.
Product Type:
Margin pools concentrate in self-contained systems that eliminate external compute dependencies and recurring licensing obligations.
- Standalone VR Headsets:Integrated application processors and wireless modems enable cord-free operation with on-device rendering. Procurement from United States military simulation contractors and Japanese location-based entertainment operators drives premium pricing for thermal-managed enclosures. Qualcomm Snapdragon XR platforms dominate the compute layer, creating captive silicon dependencies for hardware architects.
- PC-based VR Headsets:Tethered designs leverage external GPU horsepower for sub-20ms motion-to-photon latency and foveated rendering precision. Demand clusters in German automotive design studios and United States architectural visualization firms where render fidelity overrides mobility requirements. DisplayPort and USB-C cable standards constrain industrial design flexibility.
- Mobile VR Headsets:Smartphone-docked enclosures with Fresnel lens pairs operate at sub-$50 price points in Indian and Indonesian consumer markets. Supply chains align with handset accessory economics rather than dedicated computing hardware.
- Console-based VR Headsets:Proprietary connectors and SDK lock-in tie hardware to Sony PlayStation and Microsoft Xbox ecosystems. Japanese and United States gaming demographics sustain attach rates through exclusive content licensing.
The dominant share belongs to PC-based VR Headsets, while Standalone VR Headsets is closing the gap fastest.
End User:
Application depth and procurement cycle length vary sharply across user categories, with enterprise verticals commanding multi-year contracts against consumer transactional patterns.
- Corporate Training:Industrial safety modules and equipment simulation deployments in German manufacturing and South Korean shipbuilding require EN 60950-1 electrical safety certification and IP54 ingress protection. Hardware procurement separates from content licensing, compressing device margins while elevating platform switching costs.
- Entertainment:Theme park operators in United States and United Arab Emirates deploy location-based VR boxes for four-hour operational shifts, prioritizing pancake lens weight reduction and swappable hygiene interfaces.
- Healthcare:Surgical planning and phobia exposure therapy applications in United States academic medical centers demand FDA 510(k) clearance for diagnostic display accuracy. Sterilizable face interfaces and antimicrobial coatings add material cost premiums.
- Education:K-12 and university deployments in United States and United Kingdom favor mobile VR headsets for cost scalability, with bulk procurement constrained by COPPA and GDPR-K data protection compliance.
Corporate Training commands the highest average selling prices, while Healthcare is expanding most quickly through regulatory-cleared therapeutic applications.
Distribution Channel:
Channel selection directly determines margin retention and customer relationship duration, with direct engagement capturing enterprise lifetime value against retail velocity.
- Direct Sales:Corporate training departments and defense contractors in United States negotiate hardware and service contracts through vendor field organizations, eliminating retail intermediary extraction. Account-based pricing reflects volume commitments and integration service bundling.
- Online Retail:Amazon and specialized VR commerce platforms serve United States and European consumer segments with 15-30 day return windows that elevate reverse logistics costs for hardware vendors.
- Third-party Distributors:Value-added resellers in Germany and France provide local language support and CE marking documentation for enterprise procurement compliance.
- Offline Retail:Electronics superstores in Japan and United Arab Emirates offer hands-on demonstration environments that reduce return rates for premium standalone headsets.
Direct Sales generates the highest margin per unit, while Online Retail is climbing the fastest through pandemic-accelerated procurement habit formation.
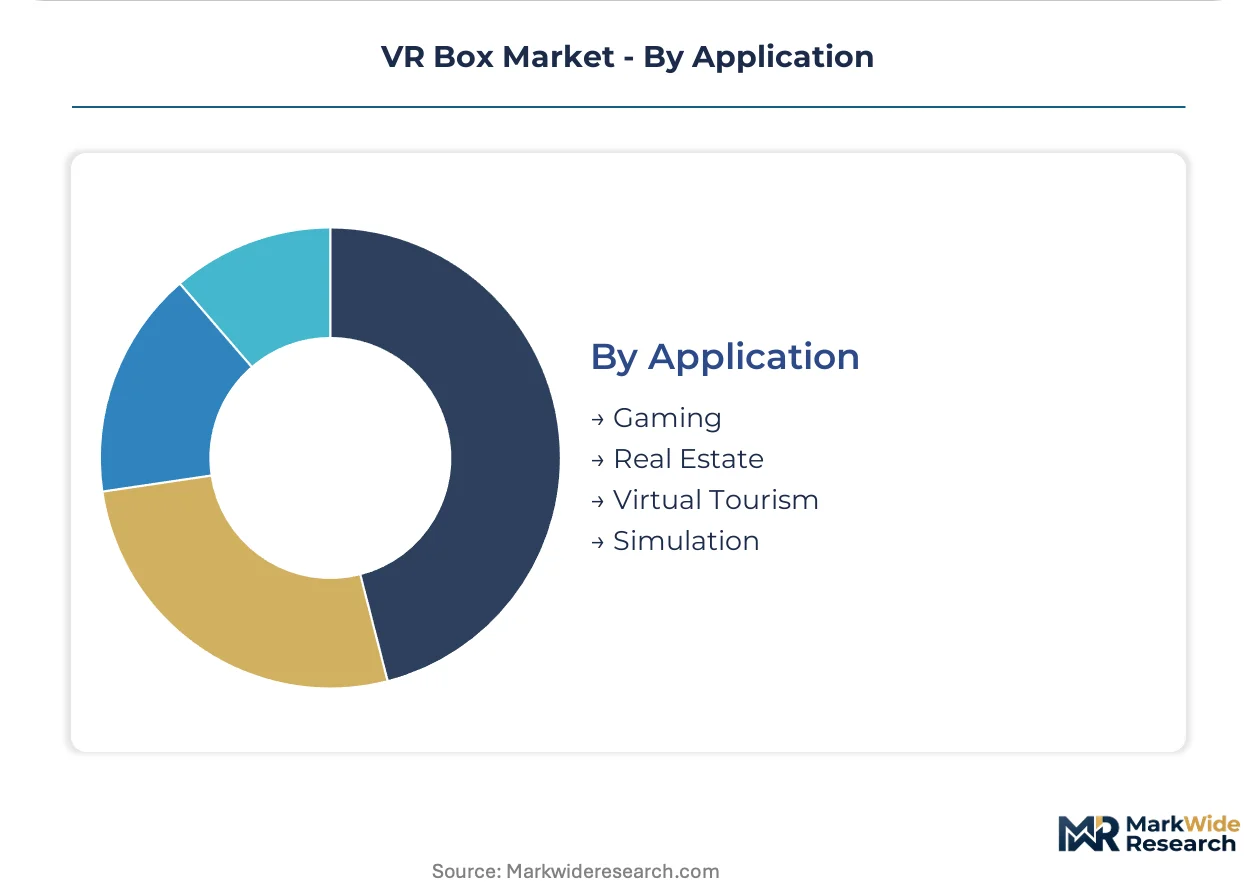
Application:
Use case technical requirements fragment hardware specifications across rendering load, tracking precision, and session duration parameters.
- Gaming:Competitive esports and narrative experiences in United States and South Korea demand 90-120 Hz refresh rates and sub-20ms motion-to-photon latency. Haptic feedback integration and inside-out tracking standardization differentiate premium tiers.
- Simulation:Flight training and tactical rehearsal for United States defense contractors requires FAA and DoD certification for motion platform synchronization and electromagnetic interference resilience.
- Real Estate:Property visualization studios in United States and Australia utilize PC-based headsets for photorealistic architectural walkthroughs with real-time lighting simulation.
- Virtual Tourism:Museum and heritage site digitization in Italy and Egypt deploys standalone headsets for untethered visitor circulation with 2-4 hour battery endurance requirements.
Gaming retains the largest installed base, while Simulation is gaining share fastest through defense procurement scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT network access mandates for cellular-enabled headsets are reshaping procurement patterns across Asia-Pacific, while FCC emissions protocols in the United States and CE marking expansions in the European Union are fragmenting certification timelines for hardware architects.
United States
Defense contractors and theme park operators drive bulk procurement of standalone headsets for tactical simulation and location-based entertainment. FCC radio frequency emissions limits constrain transmitter power and antenna configurations for wireless devices. Military simulation clusters in Orlando and defense technology corridors in California sustain premium pricing for thermally managed enclosures.
China
Domestic supply chains capture captive demand from MIIT licensing requirements for cellular-enabled standalone headsets. GB standards and electromagnetic compatibility protocols raise compliance costs for new hardware entrants. Shenzhen and Dongguan manufacturing hubs concentrate optical module assembly and Fresnel lens fabrication for regional distribution.
Germany
Automotive design studios and industrial safety trainers anchor demand for PC-based headsets with sub-20ms motion-to-photon latency. EU Green Deal ecodesign requirements pressure material recycling protocols and modular architectures. Bavarian precision optics firms and Stuttgart engineering clusters dominate pancake lens engineering for enterprise deployments.
Japan
Location-based entertainment operators and gaming demographics sustain attach rates through exclusive content licensing. METI industrial standards and JIS certification protocols govern electrical safety for extended wear sessions. Tokyo and Osaka metropolitan areas concentrate arcade deployment and optical engineering talent for Fresnel stack optimization.
South Korea
Display panel fabrication clusters supply high-resolution OLED and micro-OLED sources for premium headset tiers. MFDS regulatory frameworks and corporate training procurement from shipbuilding conglomerates drive hardware standardization. Seoul Capital Area and Busan-Ulsan industrial zones anchor semiconductor integration for wireless fidelity systems.
VR Box Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with captive content ecosystems and specialized optical engineering houses. Market structure concentrates around three archetypes: platform-integrated hardware vendors leveraging software attach rates, display technology specialists controlling critical component supply, and enterprise channel operators dominating corporate training verticals. Competitive moves center on strategic partnerships for content licensing and backward integration into optical module production.
Within the platform-integrated tier, Meta Platforms and Sony Corporation exemplify divergent approaches to ecosystem lock-in, while HTC Corporation occupies a position in enterprise channel depth. Meta Platforms represents the content-captive archetype through its hardware-software bundling strategy. Sony Corporation anchors the optical engineering specialization vector through display panel integration. HTC Corporation exemplifies the vertical market penetration model with its installed base concentration in simulation and training environments.
| Leading Market Players |
|---|
| Meta Platforms |
| Sony Corporation |
| Samsung Electronics |
| HTC Corporation |
| Microsoft |
| Valve Corporation |
| Lenovo |
| Apple |
| Others |
Pricing and Supply Chain Analysis
Ninety-day certification buffers for CE marking and FCC approvals concentrate working capital requirements among Asian ODMs, compressing pricing power for non-compliant entrants while rewarding vertically integrated incumbents with synchronized launch capabilities across regulatory zones.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers, with FDA 510(k)-cleared headsets for surgical planning commanding substantial premiums over uncertified consumer units. Three-tier pricing structure across enterprise-grade, prosumer, and mobile-docked economy levels reflects electromagnetic compliance investment and optical module sourcing depth. Cost compression in the mobile VR tier intensifies because smartphone accessory economics displace dedicated compute margins. Corporate training departments exhibit lowest price sensitivity due to unbundled procurement separating hardware from content licensing.
Supply Chain Analysis
Six-month inventory cycles for micro-OLED display panels from South Korean fabs tether headset production schedules to semiconductor foundry allocation windows. Optical module assembly concentrates in Shenzhen and Dongguan, while precision pancake lens engineering anchors in Bavarian and Tokyo precision optics houses. Single-source vulnerability in high-resolution OLED supply creates exposure to foundry capacity reallocation toward smartphone markets. Distribution runs through direct enterprise field organizations for defense and training verticals, with online retail capturing consumer velocity through Amazon and specialized VR commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where MIIT network access licenses and FDA diagnostic clearance create multi-year certification barriers that compound switching costs for enterprise buyers.
For Market Incumbents: Secure captive supply agreements for micro-OLED display capacity from South Korean fabs before foundry allocation shifts toward smartphone demand surges. Deepen backward integration into pancake lens module production through partnerships with Bavarian precision optics firms to defend margin position against optical engineering talent scarcity.
For New Entrants and Emerging Players: CE marking fast-track through European notified bodies offers the most penetrable regulatory pathway for hardware startups lacking MIIT domestic supply chain relationships. Target German automotive design studios and industrial safety trainers with modular headset architectures that satisfy EU Green Deal ecodesign recycling mandates, bypassing retail intermediary extraction through direct enterprise sales.
For Investors and Strategic Acquirers: Long-term, this sits as a vertical-integration play because optical engineering expertise concentrates in Japanese and German precision houses with irreplaceable Fresnel and pancake lens design capabilities. Acquisition targets should display enterprise channel depth in corporate training or defense simulation verticals where multi-year procurement contracts sustain price inelasticity. Watch for MIIT licensing timeline compression as inflection signal indicating regulatory barrier erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Pancake Lens Module Backward Integration | Captures optical engineering scarcity from Bavarian and Tokyo precision houses. |
| MIIT Network Access License Acquisition | Unlocks cellular-enabled standalone headset distribution within Chinese domestic supply chains. |
| Direct Enterprise Channel Expansion | Eliminates retail margin extraction from corporate training and defense procurement verticals. |
| EU Green Deal Ecodesign Certification | Positions modular architectures for material recycling mandates in German automotive and industrial safety markets. |
| FDA 510(k) Diagnostic Clearance Pathway | Enters surgical planning and phobia exposure therapy segments with sterilizable face interface premiums. |
Research Methodology
A standing panel of hardware product managers, optical engineering directors, enterprise procurement officers, and FCC compliance specialists provided ongoing calibration against secondary validation from MIIT filing databases, FDA 510(k) clearance records, and EU CE marking documentation. Bottom-up shipment estimates from ODM production records triangulated with top-down demand aggregation from theme park operators and defense simulation contractors.
Consistency checks against hyperscaler VR capex disclosures and Qualcomm Snapdragon XR platform shipment data validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, end-user vertical, distribution channel, and application-specific rendering load requirements. CAGRs derived from installed base growth rates and replacement cycle compression in location-based entertainment deployments.
Decision-makers should treat outputs as directional under assumptions of sustained FCC emissions limits and MIIT licensing timelines; material deviation in regulatory processing speed or display panel foundry allocation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market