
 Global Augmented Reality (AR) and Mixed Reality (MR) Market | 2026-2036
Global Augmented Reality (AR) and Mixed Reality (MR) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Augmented Reality (AR) and Mixed Reality (MR) Market Foresight
Asset-light leasing models for enterprise AR hardware are reshaping competitive dynamics by lowering capital barriers for mid-sized manufacturing buyers. Microsoft Corporation leverages its Azure cloud backbone to anchor mixed-reality deployments across industrial clients. Meta Platforms Inc. competes through vertical integration of its Quest hardware with proprietary spatial software stacks. Magic Leap Inc. specializes in premium optics for defense and medical segments where precision demands justify higher subscription fees.
Augmented Reality and Mixed Reality denote spatial computing systems that overlay or embed digital information within physical environments through optical waveguides, depth sensors, and real-time rendering engines operating at sub-20-millisecond motion-to-photon latency. These systems serve industrial and commercial purposes ranging from remote expert guidance to immersive product prototyping. Head-Mounted Displays dominate procurement volumes among defense and aerospace contractors seeking situational awareness overlays. Training and Simulation applications are expanding fastest in manufacturing and education as enterprises seek scalable workforce upskilling without physical equipment downtime. Hardware offerings capture the largest margin pools today, though Platforms and Content Creation Tools are attracting recurring-revenue-focused vendors.
The EU AI Act, GDPR, and FDA device classification standards collectively shape product roadmaps by mandating algorithmic transparency, biometric data consent frameworks, and clinical validation for medical AR applications. FCC spectrum allocations in the United States and MIIT certification requirements in China further constrain which depth-sensing and wireless transmission modules gain market access. Stakeholders must monitor evolving national security review thresholds for foreign hardware components while building compliance architectures that span multiple jurisdiction-specific certification tracks.
Market Dynamics
Enterprise procurement of spatial computing hardware is consolidating around defense and aerospace contractors seeking sub-20-millisecond motion-to-photon latency for situational awareness overlays, compressing vendor qualification timelines and favoring integrated hardware-software bundles over component sourcing.
Growth Catalysts
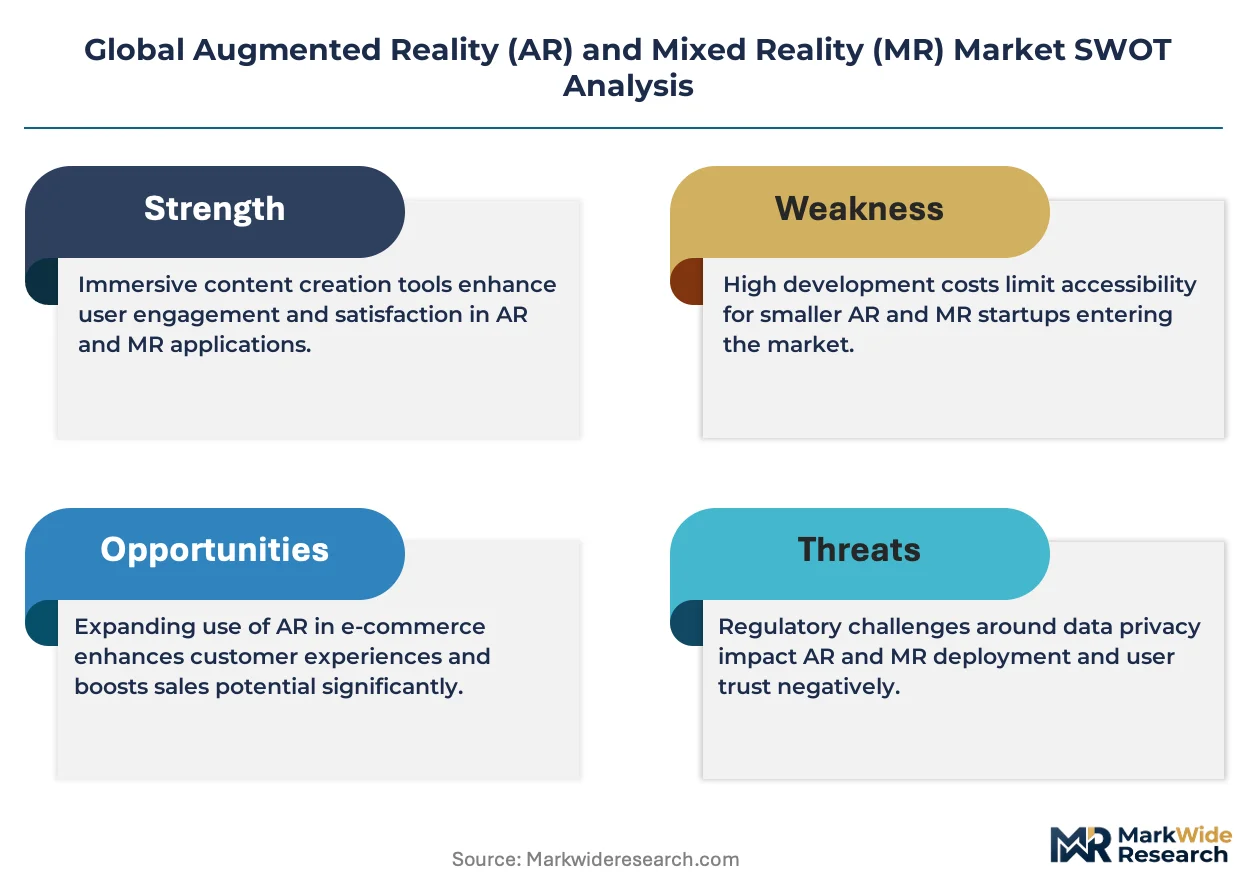
- EU AI Act compliance mandates:Privacy-by-design architectures embedded from the chipset layer upward are accelerating replacement cycles for legacy AR hardware in European manufacturing facilities.
- Waveguide optics advancement:Optical waveguides with improved field-of-view are enabling precision medical visualization applications that justify premium subscription pricing in surgical planning.
- United States defense procurement concentration:Pentagon contracts for Head-Mounted Displays are creating concentrated demand pools that anchor production scale for spatial computing vendors.
Market Restraints
- Custom silicon dependency:Depth-sensing module fabrication concentrates among a limited set of foundries, exposing lead time volatility for real-time rendering chipsets.
- GDPR biometric consent friction:Retinal and gaze-tracking data collection triggers complex consent frameworks that lengthen enterprise sales cycles in European healthcare deployments.
- Display panel input cost concentration:Micro-OLED substrate supply tightens periodically, compressing hardware margins for premium optics manufacturers.
Strategic Opportunities
- India manufacturing upskilling gap:CDSCO and BIS certification pathways for medical AR devices remain underdeveloped, creating first-mover advantage for training module vendors.
- 5G edge convergence with spatial computing:Low-latency rendering offload to distributed edge nodes is virtualizing heavy computational workloads previously tethered to local hardware.
- Japan METI digital manufacturing incentives:Subsidies for smart factory deployments are accelerating MR training module adoption among automotive suppliers in Nagoya and Toyota City clusters.
Industry Challenges
- Optical engineer talent scarcity:Waveguide design and photonics simulation expertise concentrates among defense contractors, constraining vendor R&D scaling.
- Multi-jurisdiction certification sequencing:FDA device classification, EU MDR, and MIIT certification requirements operate on non-aligned timelines, delaying product launches.
- Legacy ERP integration complexity:Spatial computing platforms require custom API development to synchronize with incumbent manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Augmented Reality (AR) and Mixed Reality (MR) Market |
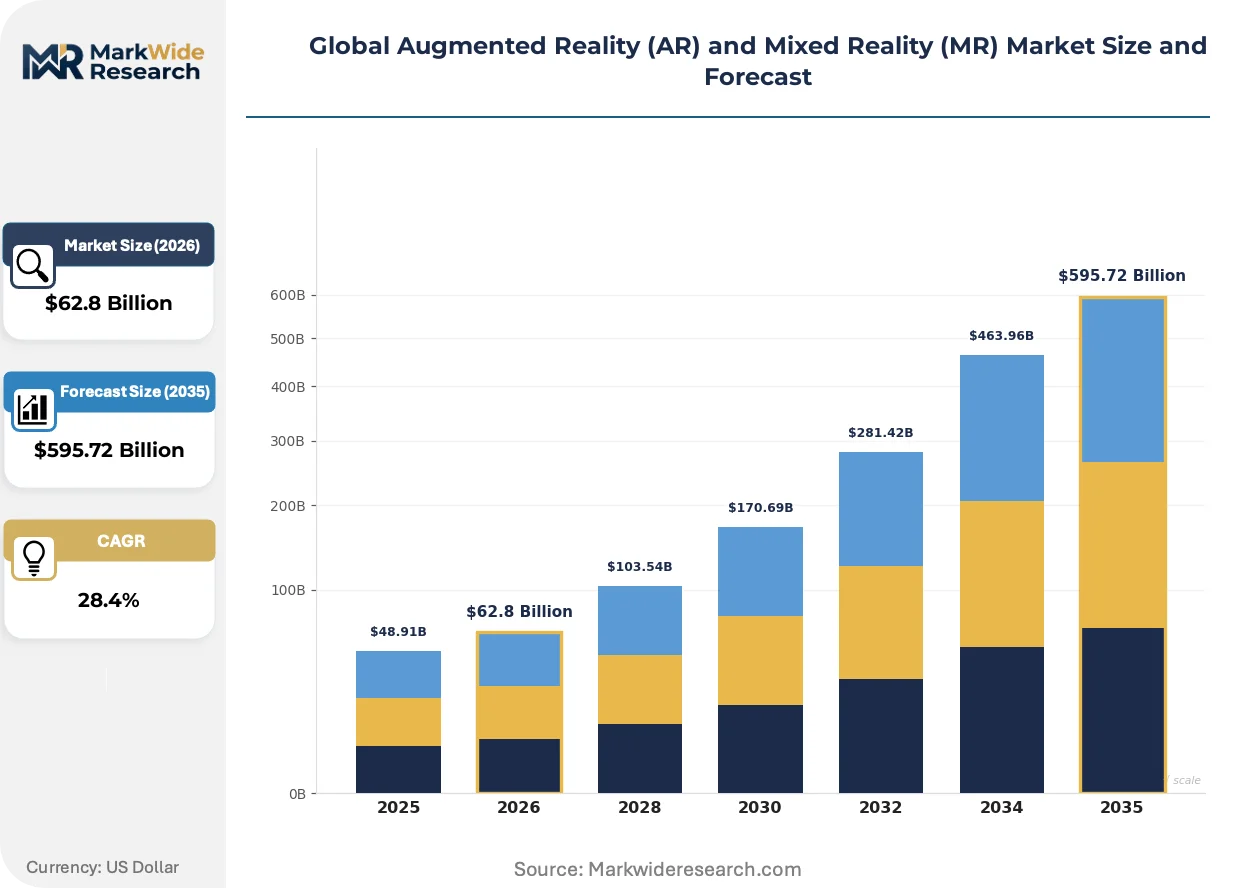
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $595.72 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AR Glasses, Head-Mounted Displays, Spatial Computing, Depth Sensing, Gesture Recognition Application: Training & Simulation, Product Design, Remote Assistance, Interactive Entertainment, Real Estate Visualization Offering: Hardware, Software, Services, Platforms, Content Creation Tools End User Industry: Manufacturing, Defense & Aerospace, Education, Architecture & Construction, Entertainment |
| Companies Covered | Microsoft Corporation, Apple Inc., Meta Platforms Inc., Google LLC, Samsung Electronics Co. Ltd., Magic Leap Inc., Vuzix Corporation, Sony Group Corporation, PTC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Augmented Reality (AR) and Mixed Reality (MR) Market Shifts & Advancements
Spatial computing architectures are converging around real-time cloud rendering pipelines that decouple display hardware from computational heavy lifting, redistributing value capture toward platform operators and edge infrastructure providers.
Optical waveguides employing surface-relief gratings and holographic optical elements are virtualizing traditional refractive lens assemblies in enterprise Head-Mounted Displays. Automotive design studios and surgical planning departments are adopting these systems at accelerated procurement cycles. The technology is virtualizing the physical prototyping workflow, compressing iteration timelines from weeks to hours while reducing material waste.
EU AI Act algorithmic transparency requirements and GDPR biometric data governance frameworks are mandating explainable AI overlays for diagnostic AR applications. Industrial equipment manufacturers must now document decision pathways for spatial guidance systems. Medical device segments in Germany and France are responding by embedding audit trails directly into rendering pipelines, extending development timelines but creating compliance moats against unqualified entrants.
Asset-light leasing structures are displacing capital purchase models for mid-sized manufacturing buyers seeking AR-guided assembly tools. Industrial distributors and systems integrators are capturing margin pools previously held by hardware OEMs through managed service bundles. This rotation is most visible in United States Midwest manufacturing corridors, where tooling budgets face pressure from cyclical order volatility.
Global Augmented Reality (AR) and Mixed Reality (MR) Market Segmentation
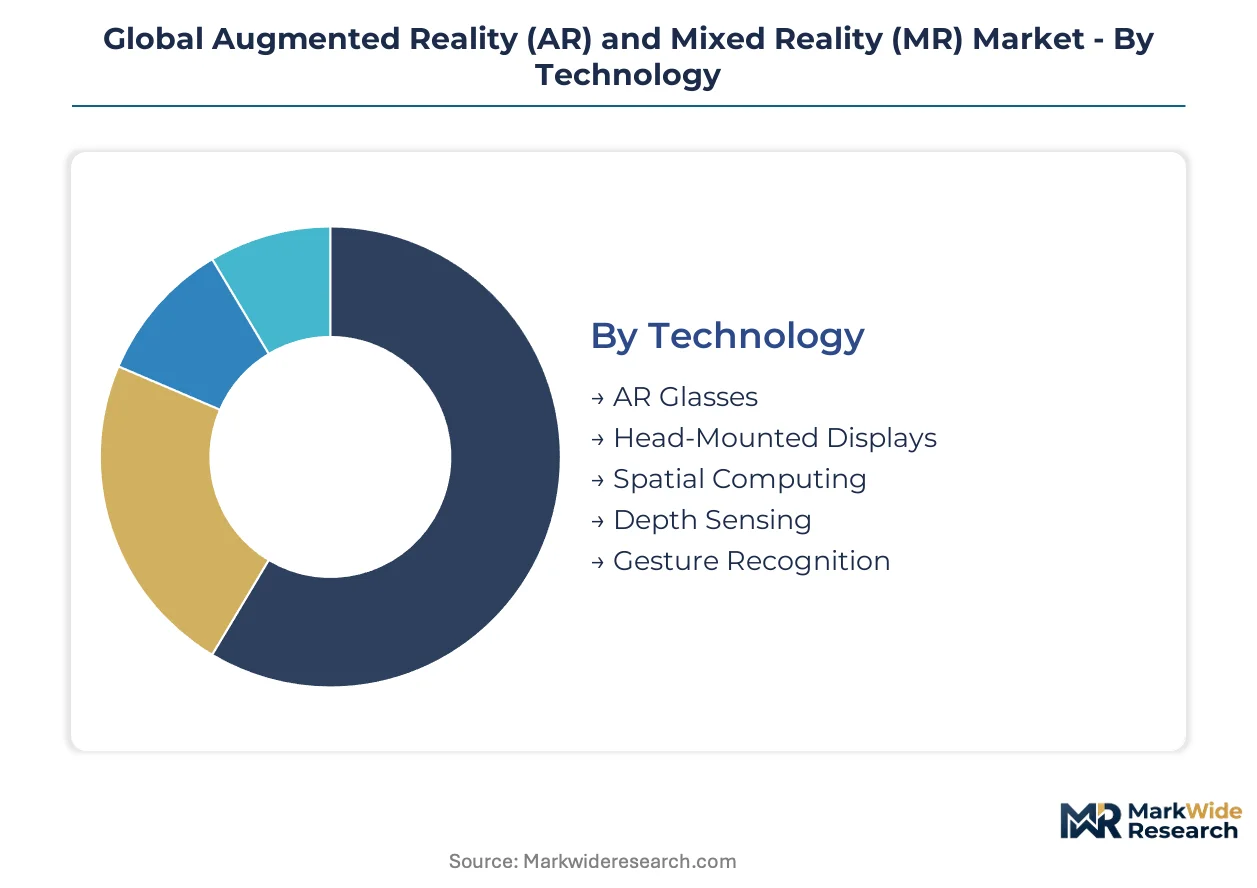
Segmentation in spatial computing reveals how procurement cycles diverge across technical architectures and use cases. Cycle times compress for hardware refresh while software subscriptions extend recurring revenue horizons.
Technology:
Head-Mounted Displays turn over every 18-24 months as defense contractors chase latency improvements, while depth-sensing modules persist across multiple hardware generations.
- Head-Mounted Displays:Optical waveguide assemblies with sub-20-millisecond motion-to-photon latency anchor Pentagon procurement pools. United States defense contractors concentrate demand for situational awareness overlays, compressing vendor qualification timelines.
- AR Glasses:Lightweight optical see-through designs prioritize field-of-view expansion over immersive occlusion. German automotive design studios in Stuttgart and Munich drive enterprise adoption for virtual prototyping workflows.
- Spatial Computing:Cloud-rendered pipelines decouple display hardware from computational workloads.
- Depth Sensing:Time-of-flight and structured-light modules enable real-time environmental meshing.
- Gesture Recognition:Computer vision-based hand tracking reduces controller dependency in surgical planning.
Head-Mounted Displays anchors the volume base while AR Glasses gains share at the steepest rate.
Application:
Cost tiers separate capital-intensive deployment from subscription-based scaling, with physical equipment downtime avoidance commanding premium pricing.
- Training & Simulation:MR modules compress skill development cycles without halting production lines. Manufacturing facilities in Japan's Nagoya automotive cluster deploy these systems under METI subsidy programs.
- Remote Assistance:Expert guidance overlays reduce travel costs for equipment maintenance. United States Midwest tooling corridors favor asset-light leasing for mid-sized buyers facing cyclical order pressure.
- Product Design:Virtual prototyping eliminates physical iteration waste.
- Interactive Entertainment:Consumer-facing experiences drive hardware volume at lower margins.
- Real Estate Visualization:Pre-construction walkthroughs accelerate buyer decision cycles.
Training & Simulation commands the premium tier while Remote Assistance expands most quickly across mid-market manufacturing.
Offering:
Margin pools concentrate in hardware today, though platform operators capture recurring revenue through cloud-rendered spatial computing pipelines.
- Hardware:Micro-OLED displays and custom silicon dominate bill-of-materials costs. Supply tightness in substrate fabrication periodically compresses margins for premium optics manufacturers.
- Platforms:Cloud backbone integrations anchor enterprise deployments across industrial clients.
- Software:Spatial operating systems manage sensor fusion and rendering pipelines.
- Services:Systems integrators capture margin pools through managed deployment bundles.
- Content Creation Tools:Authoring environments for 3D asset preparation and scenario scripting.
Hardware dominates current revenue capture while Platforms climbs fastest as rendering offloads to distributed edge infrastructure.
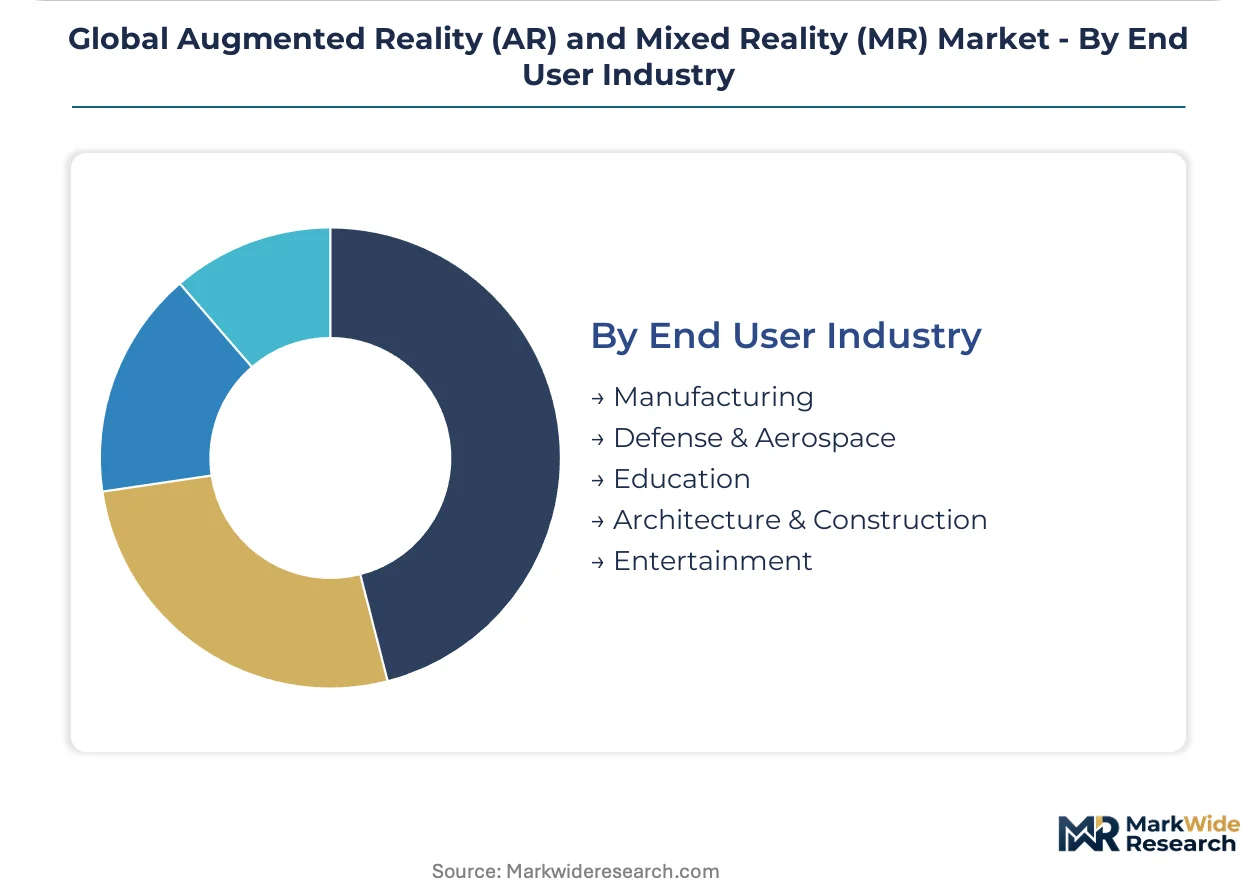
End User Industry:
Maturity gradients separate defense procurement with decade-long qualification cycles from education pilots with rapid pilot-to-scale transitions.
- Defense & Aerospace:Situational awareness overlays demand sub-20-millisecond latency for mission-critical applications. United States Pentagon contracts create concentrated demand pools that anchor production scale.
- Manufacturing:AR-guided assembly and MR training modules compress workforce upskilling timelines. EU AI Act compliance mandates accelerate replacement cycles for legacy hardware in European facilities.
- Education:Scalable immersive learning environments reduce physical equipment requirements.
- Architecture & Construction:Pre-visualization tools coordinate complex project stakeholders.
- Entertainment:Location-based experiences and consumer content drive volume at commoditized pricing.
Defense & Aerospace sustains the longest procurement cycles while Manufacturing demonstrates the steepest adoption trajectory across automotive and industrial verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net spatial computing hardware exports flow predominantly from United States and China toward European and Asian manufacturing importers. Germany and Japan maintain trade surpluses in precision optical components. India's emerging assembly capacity draws component imports from Taiwan and South Korea.
United States
Pentagon procurement pools for Head-Mounted Displays anchor concentrated demand from defense contractors. FCC spectrum allocations constrain depth-sensing module certification timelines. Midwest manufacturing corridors in Michigan and Ohio deploy asset-light AR leasing for automotive supplier tooling.
China
MIIT certification requirements govern market access for wireless transmission modules in enterprise headsets. Domestic cloud operators build edge rendering infrastructure for spatial computing pipelines. Yangtze River Delta clusters around Shanghai integrate AR-guided assembly for electronics contract manufacturers.
Germany
EU AI Act compliance mandates accelerate replacement cycles for legacy hardware in Stuttgart automotive plants. GDPR biometric consent frameworks lengthen sales cycles for healthcare AR deployments. Bavarian industrial zones adopt MR training modules under factory digitalization incentives.
Japan
METI subsidies for smart factory deployments drive MR adoption among Nagoya automotive suppliers. JIS standards govern optical component specifications for precision manufacturing applications. Kansai region medical device clusters pilot surgical planning AR under PMDA guidance frameworks.
India
CDSCO certification pathways for medical AR devices remain underdeveloped, creating first-mover positioning for training module vendors. BIS standards for electronics hardware constrain import timelines for depth-sensing components. Karnataka and Maharashtra industrial zones pilot workforce upskilling programs with leased AR hardware.
Global Augmented Reality (AR) and Mixed Reality (MR) Market Competitive Landscape
On the supply side, the industry is consolidating around integrated hardware-software bundles as defense and aerospace procurement compresses vendor qualification timelines. Tiered competitive positioning separates cloud-backed platform operators from specialized optics fabricators and component module suppliers. Strategic archetypes include vertically integrated technology conglomerates, premium optics specialists, and enterprise software integrators. Dominant competitive moves encompass strategic cloud partnerships and portfolio diversification into edge rendering infrastructure.
Among United States-based technology conglomerates, Microsoft Corporation and Meta Platforms Inc. occupy positions anchoring enterprise platform ecosystems, while Magic Leap Inc. exemplifies the premium optics specialist archetype serving defense and medical segments where precision requirements justify elevated subscription pricing. These three entities represent the primary competitive anchors around which mid-tier hardware vendors and regional systems integrators cluster.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Apple Inc. |
| Meta Platforms Inc. |
| Google LLC |
| Samsung Electronics Co. Ltd. |
| Magic Leap Inc. |
| Vuzix Corporation |
| Sony Group Corporation |
| PTC Inc. |
| Others |
Supply & Pricing Matrix
Single-source dependency on Taiwan-based micro-OLED substrate foundries determines both pricing tier spreads and supply chain shape in spatial computing hardware, compressing margins for premium optics manufacturers while forcing buyers toward longer-term contract structures.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing structures for AR-guided assembly tools, with three-tier pricing structure across premium, standard, and economy levels differentiated by motion-to-photon latency performance and EU AI Act certification grade. Cost compression in the economy tier is intensifying because Micro-OLED supply tightness periodically spikes input costs, while defense contractors show least price sensitivity due to decade-long procurement cycles and mission-critical latency requirements.
Supply Chain Analysis
Micro-OLED substrates and custom silicon for depth-sensing modules draw from Taiwan, South Korea, and Japan, with optical waveguide assemblies resting on precision photonics expertise concentrated in German and Japanese defense contractors. Single-source vulnerability in time-of-flight sensor fabrication creates exposure to foundry allocation shocks, while distribution runs through systems integrators capturing margin pools via managed service bundles for mid-sized manufacturing buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spatial computing hardware demand follows defense procurement cycles and manufacturing capital expenditure waves, with current positioning reflecting recovery from trough conditions as Pentagon Head-Mounted Display contracts accelerate and METI subsidies unlock Japanese automotive deployment.
For Market Incumbents: Build compliance moats through embedded privacy-by-design architectures that satisfy EU AI Act algorithmic transparency mandates from the chipset layer upward. Deepen backward integration into optical waveguide fabrication to reduce dependency on German and Japanese photonics specialists, while anchoring cloud-rendered platform ecosystems through Azure backbone integrations that lock in industrial client switching costs. For New Entrants and Emerging Players: Establish a beachhead in India's underdeveloped CDSCO certification pathways for medical AR devices, where first-mover positioning in workforce upskilling modules offers protected growth before regulatory frameworks mature. Target Karnataka and Maharashtra industrial zones with leased hardware bundles that circumvent BIS import timeline constraints for depth-sensing components, leveraging asset-light structures to bypass capital barriers facing domestic buyers. For Investors and Strategic Acquirers: The market sits at a defense procurement upswing phase that favors premium optics specialists with established Pentagon qualification timelines and medical segment subscription pricing power. Acquisition targets should demonstrate embedded FDA device classification expertise or EU MDR certification progress as defensive positioning against multi-jurisdiction approval delays. Watch for MIIT certification accelerations in China as signal of edge infrastructure buildout maturity that would validate cloud-rendered spatial computing platform bets.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-by-Design Architecture Integration | EU AI Act compliance mandates accelerate replacement cycles for legacy hardware in European manufacturing facilities. |
| Optical Waveguide Backward Integration | German and Japanese photonics specialist concentration creates supply risk for vendors lacking captive fabrication capacity. |
| Cloud-Rendered Platform Ecosystem | Microsoft Azure backbone anchors enterprise deployments through distributed edge node infrastructure partnerships. |
| Defense Contract Qualification Acceleration | Pentagon Head-Mounted Display procurement pools compress vendor timelines and favor integrated hardware-software bundles. |
| Medical Device Certification Pathway Investment | FDA device classification and EU MDR requirements create compliance moats against unqualified entrants in surgical planning segments. |
Research Methodology
Initial hypotheses were tested against primary input from defense procurement officers, automotive manufacturing engineers, medical device regulatory affairs leads, and spatial computing platform architects and refined through secondary validation against SEC filings from cloud infrastructure providers, FDA 510(k) submission databases, EU MDR notified body approval records, and hyperscaler capital expenditure disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators across the analysis window.
Demand-supply balance modeling incorporated technology segmentation across Head-Mounted Displays, AR Glasses, and spatial computing platforms; application dimensions spanning Training & Simulation, Remote Assistance, and Product Design; and end-user industry splits including Defense & Aerospace, Manufacturing, and Healthcare. CAGRs derived from fitted growth curves applied to base-year sizing, with optical waveguide yield rates and defense contract award velocity serving as industry-specific sensitivity inputs.
Sensitivities concentrate around Pentagon procurement timeline shifts, Micro-OLED substrate supply disruptions, and EU AI Act enforcement intensity variations. Forecasts reflect documented assumptions regarding edge infrastructure deployment rates and manufacturing capital expenditure recovery trajectories. Material shifts in FCC spectrum allocation decisions or MIIT certification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
US Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Solutions Market