
 Location Based VR Market | 2026-2036
Location Based VR Market Size, Share, and Industry Trends Forecast 2026-2036
Location Based VR Market Outlook
Corporate training is realigning the end-use mix for location based VR as enterprises seek experiential learning environments. Sandbox VR leverages its proprietary motion capture arenas to dominate social entertainment venues across North American cities. Zero Latency sustains technology leadership through warehouse-scale free-roam systems that occupy premium retail spaces. HTC Corporation anchors professional deployment with tethered headset ecosystems designed for high-throughput commercial installations.
Location based VR denotes commercially operated immersive entertainment systems utilizing head-mounted displays, positional tracking sensors, and spatial computing infrastructure to deliver shared virtual experiences in dedicated physical venues. Hardware configurations typically integrate sub-millimeter lighthouse tracking or inside-out camera arrays with refresh rates exceeding 90 Hz to minimize motion sickness during extended sessions. Arcade service types currently generate the strongest revenue concentration due to low capital barriers and rapid consumer throughput, while theme park integrations command superior per-capita spending through narrative depth and custom physical set pieces. Tethered platform architectures lead in fidelity-critical deployments, though standalone headsets are gaining traction in mobile pop-up formats where installation speed outweighs graphical intensity.
The FCC governs wireless spectrum allocation for untethered VR transmission equipment in the United States, directly constraining available bandwidth for multiplayer synchronization in dense venue environments. China's SAMR enforces national standard GB/T specifications for head-mounted display safety, including optical radiation limits and structural durability testing that manufacturers must clear for commercial distribution. Stakeholders must monitor evolving biometric data classification rules across jurisdictions, as pupil tracking and gait analysis capabilities trigger privacy compliance obligations that reshape hardware architecture and venue operating procedures.
Market Dynamics
Motion tracking latency reduction below 20 milliseconds is compressing hardware refresh cycles and forcing venue operators to upgrade lighthouse systems or lose throughput to competitors with superior haptic fidelity.
Growth Catalysts
- MIIT Equipment Standards:China's mandatory GB/T optical radiation and structural durability testing is accelerating commercial-grade headset certification pipelines, reducing time-to-deployment for domestic venue chains.
- Haptic Feedback Maturation:Force-feedback vests and full-body tracking suits are expanding session duration tolerance, driving repeat visitation rates at entertainment centers.
- Corporate Training Pivot:Enterprises in aviation, healthcare, and energy are commissioning custom arena installations for hazardous procedure simulation, diversifying revenue beyond consumer entertainment.
Market Restraints
- GPU Supply Concentration:Taiwan-based foundry capacity constraints for high-refresh display drivers are extending lead times for tethered headset orders beyond 16 weeks.
- GDPR Biometric Friction:The EU's pupil tracking and gait analysis classification as sensitive personal data is forcing hardware architecture redesigns and consent workflow complexity.
- Real Estate Cost Escalation:Premium urban retail space absorption in Tokyo, New York, and Shanghai is compressing venue operating margins below sustainable thresholds for independent operators.
Strategic Opportunities
- India Urban Entertainment Infrastructure:Bangalore and Mumbai shopping mall expansions are creating greenfield deployment opportunities before domestic regulatory frameworks mature.
- Healthcare Rehabilitation Applications:Physical therapy clinics are piloting balance and motor-skill recovery protocols using warehouse-scale free-roam systems.
- FCC Spectrum Allocation:Pending 6 GHz band expansion for unlicensed Wi-Fi 6E operation will enable denser multiplayer synchronization in compact venue footprints.
Industry Challenges
- Motion Sickness Mitigation Expertise:Venue staffing shortages in perceptual psychology and human factors engineering are limiting safe session duration optimization.
- Multi-Jurisdiction Certification Lag:Divergent optical safety testing requirements between SAMR, FDA, and PMDA are fragmenting hardware SKUs and inflating inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Location Based VR Market |
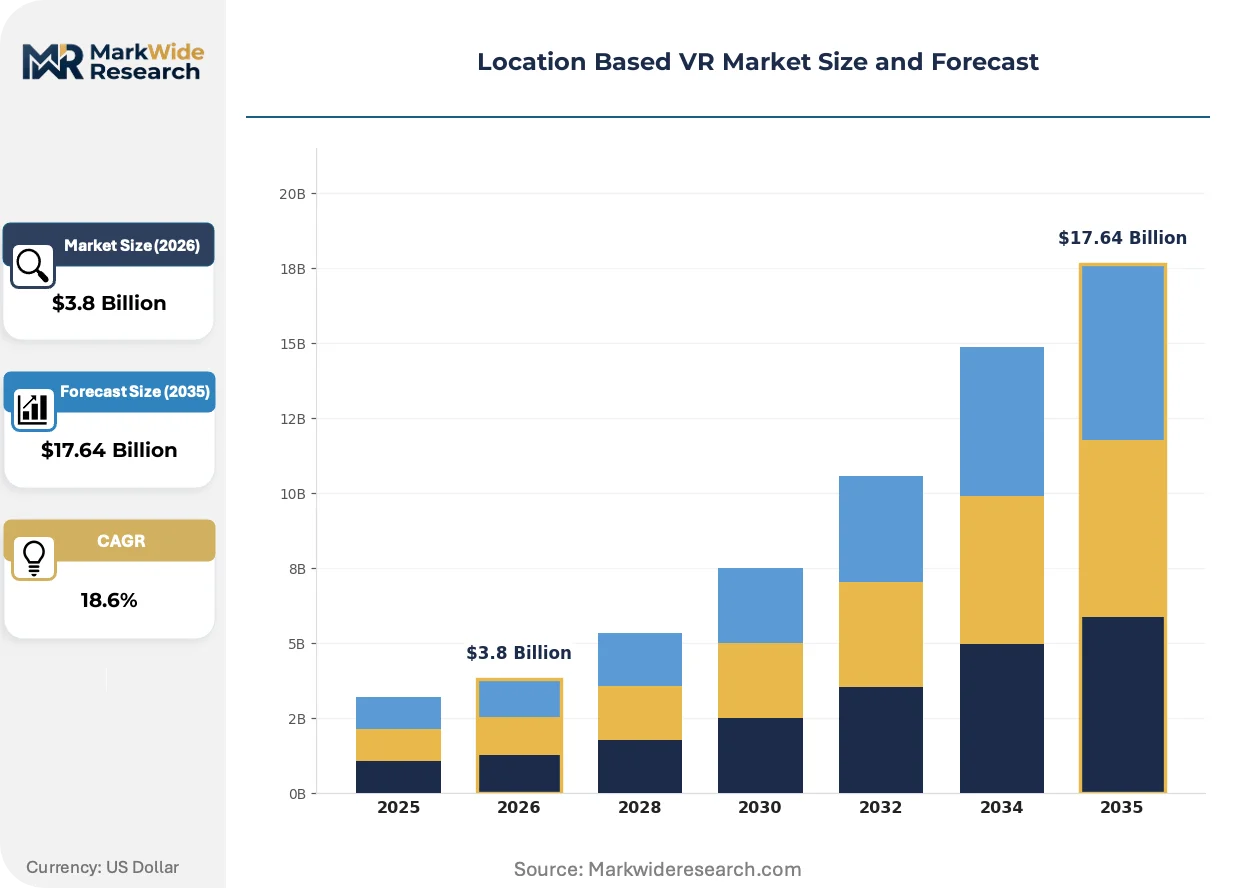
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Arcade, Theme Parks, Gaming Zones, Event Venues Technology: Motion Tracking, Haptic Feedback, 3D Audio, Gesture Recognition End User: Entertainment Centers, Educational Institutions, Healthcare Facilities, Corporate Training Platform: Standalone, Tethered, Mobile, Cloud-Based |
| Companies Covered | Sandbox VR, Zero Latency, Hologate, Dreamscape Immersive, VRstudios, HTC Corporation, Meta, Survios, The VOID, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Location Based VR Market Strategic Shifts
Spatial computing infrastructure is migrating from proprietary tethered stacks toward modular, standards-based architectures that reduce vendor lock-in and accelerate venue technology refresh decisions.
Inside-out camera arrays with sub-millimeter precision are converging with AI-driven predictive tracking algorithms to eliminate external lighthouse installation requirements. Mobile pop-up operators in festival and event circuits are adopting these self-contained systems to reduce setup time from days to hours. This convergence is compressing the addressable market for premium external tracking hardware and redirecting R&D investment toward on-device processing.
The EU AI Act's risk classification framework for biometric inference systems is reclassifying pupil-tracking-enabled headsets as high-risk AI. Hardware manufacturers serving European venues are stripping gaze-monitoring capabilities or implementing on-device anonymization to avoid conformity assessment obligations. This regulatory pressure is bifurcating product lines between privacy-preserving EU configurations and feature-rich variants for less restrictive jurisdictions.
Enterprise buyers are consolidating vendor relationships through multi-year immersive training facility contracts rather than per-session arcade purchasing. Oil & gas operators in the US Gulf Coast and North Sea clusters are commissioning dedicated simulation arenas with custom content pipelines. This procurement compression is squeezing standalone entertainment venues out of premium commercial real estate in Houston and Aberdeen.
Location Based VR Market Segmentation
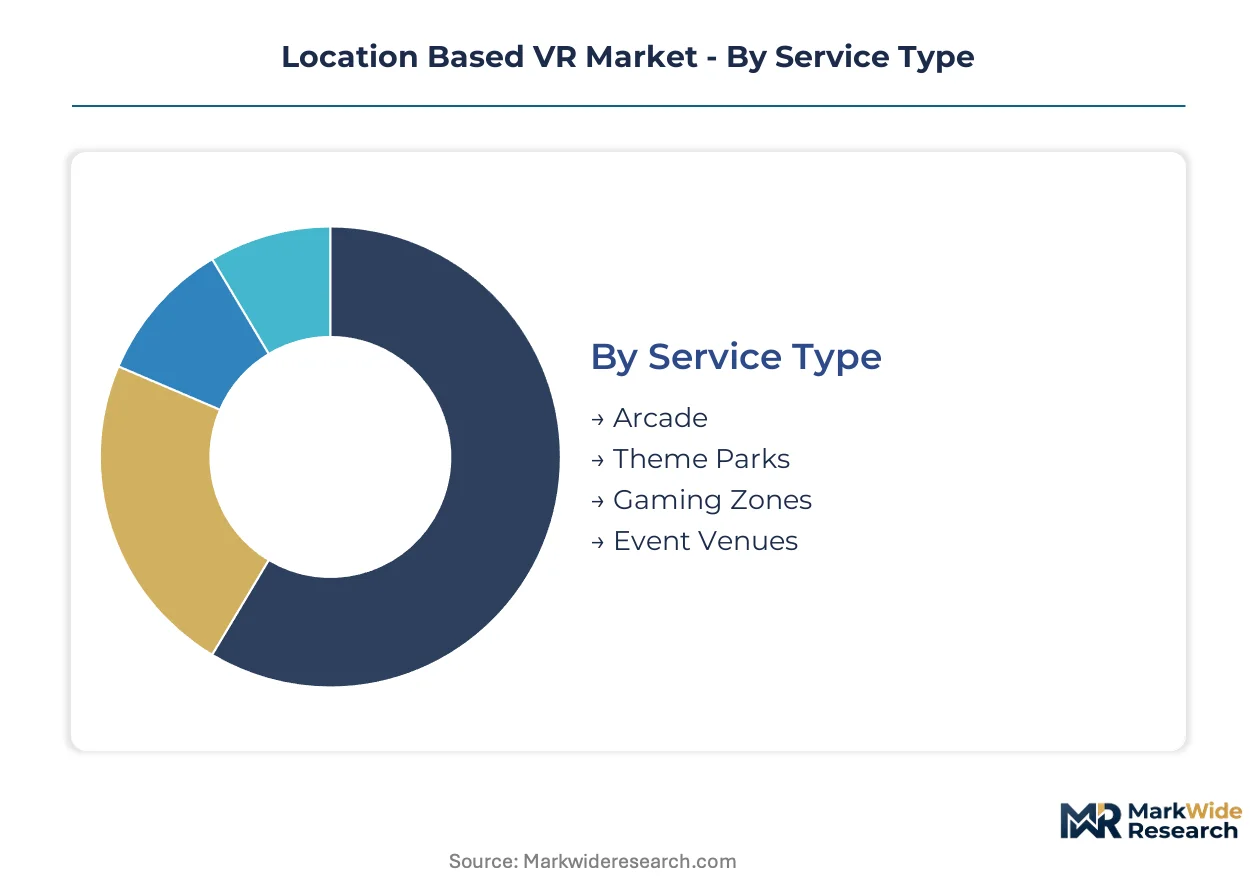
Segmentation in location based VR reveals how hardware architectures and service delivery models align with venue economics. Operators select configurations based on throughput requirements, installation permanence, and regulatory constraints governing biometric data collection.
Service Type:
Arcade deployments function as standalone entertainment modules requiring minimal integration with surrounding infrastructure, while theme park installations embed deeply into narrative environments with custom physical set pieces.
- Arcade:Compact booth configurations with 15-30 minute session formats maximize hourly throughput in shopping mall footprints. United States operators favor these for rapid ROI in secondary urban markets where real estate costs strain independent venues.
- Theme Parks:Warehouse-scale arenas integrate motion platforms, environmental effects, and physical props with synchronized VR content. Japan's Universal Studios and Shanghai Disney clusters command premium per-capita spending through narrative depth unavailable in modular formats.
- Gaming Zones:Multiplayer competitive formats in dedicated esports venues.
- Event Venues:Temporary pop-up installations at festivals and corporate activations.
Arcade leads volumes today; theme park is gaining share fastest.
Technology:
Technology selection separates premium venues investing in full-body immersion from cost-optimized operators prioritizing rapid deployment.
- Motion Tracking:Sub-20 millisecond latency systems using lighthouse arrays or inside-out camera clusters enable free-roam multiplayer synchronization. China's MIIT GB/T standards for optical radiation safety are accelerating certification of domestic tracking hardware manufacturers.
- Haptic Feedback:Force-feedback vests and full-body suits extend session duration tolerance by 40-60% through proprioceptive grounding. Corporate training facilities in aviation and energy sectors commission custom haptic configurations for hazardous procedure simulation.
- 3D Audio:Spatial audio arrays with head-related transfer function calibration.
- Gesture Recognition:Computer vision-based hand tracking eliminating controller dependency.
Motion tracking dominates installed base; haptic feedback is expanding most quickly.
End User:
End user segmentation maps directly to procurement cycles, with enterprise buyers consolidating multi-year contracts while entertainment venues operate on per-session economics.
- Entertainment Centers:Consumer-facing arcades and family entertainment centers with high throughput requirements.
- Educational Institutions:University laboratories and K-12 STEM programs deploying VR for immersive history and science modules.
- Healthcare Facilities:Physical therapy clinics in Germany and the United States pilot balance recovery protocols using warehouse-scale free-roam systems with fall-detection safety protocols.
- Corporate Training:Oil and gas operators in Houston and Aberdeen commission dedicated simulation arenas with custom content pipelines, squeezing standalone venues from premium commercial real estate.
Entertainment centers anchor volume; corporate training shows steepest expansion trajectory.
Platform:
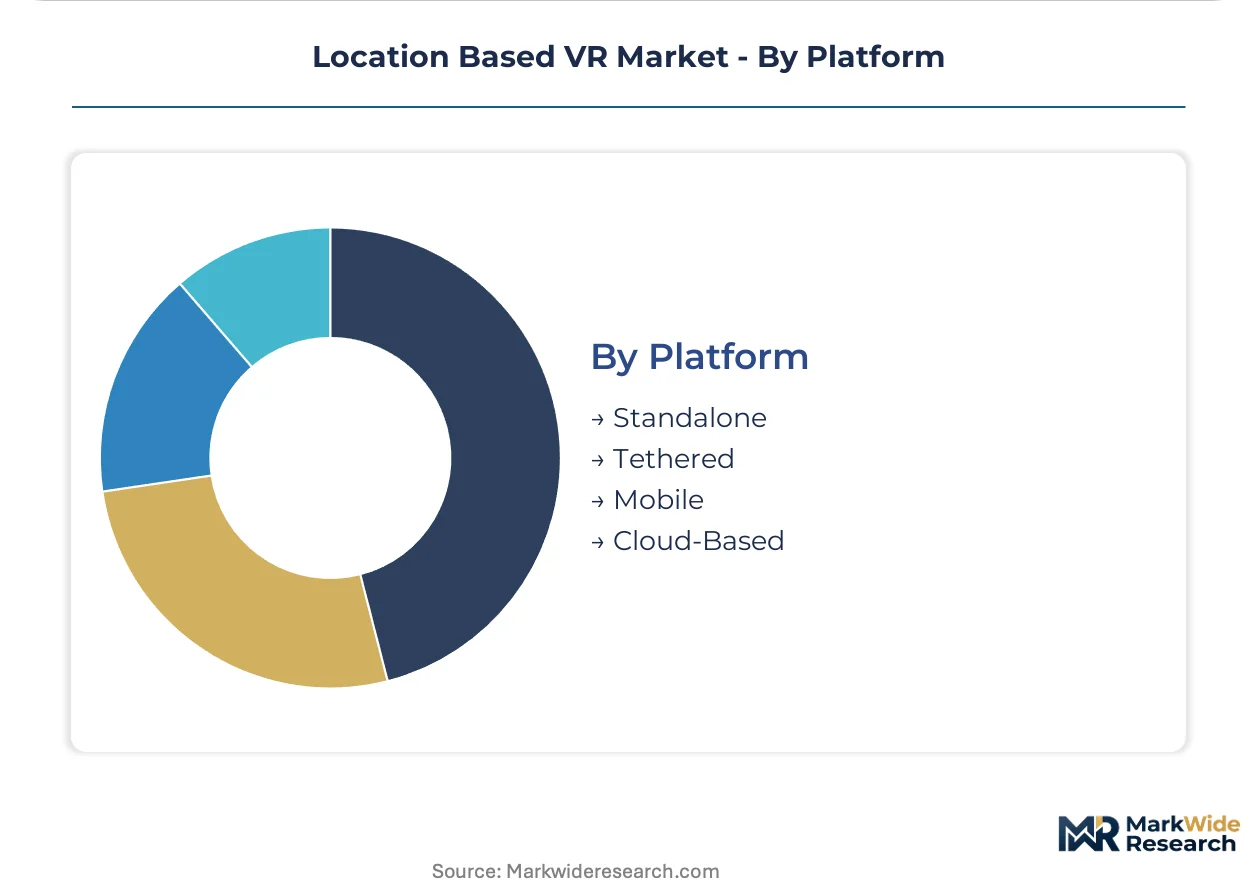
Platform architecture determines installation complexity, with tethered systems requiring fixed infrastructure and standalone configurations enabling rapid redeployment.
- Standalone:Self-contained headsets with on-device processing eliminate external tracking hardware. Mobile pop-up operators in festival circuits adopt these to compress setup from days to hours.
- Tethered:PC-connected headsets with external lighthouse tracking deliver highest visual fidelity. HTC Corporation anchors professional deployment with these configurations designed for high-throughput commercial installations.
- Mobile:Smartphone-powered viewers for low-cost entry experiences.
- Cloud-Based:Edge-rendered streaming to lightweight headsets, dependent on venue bandwidth infrastructure.
Tethered platforms lead fidelity-critical deployments; standalone is climbing the fastest in pop-up formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting venue deployment capital toward jurisdictions with streamlined equipment certification and lower biometric compliance burdens. Operators migrate installation spend away from markets where GDPR-class consent workflows inflate customer onboarding friction.
United States
Entertainment center rollouts concentrate in secondary urban markets where real estate costs permit sustainable operating margins. The FCC governs wireless spectrum allocation for untethered VR transmission equipment, constraining available bandwidth for multiplayer synchronization in dense venue environments. Houston anchors corporate training demand as oil and gas operators commission dedicated simulation arenas with custom content pipelines.
China
Domestic venue chains accelerate expansion as MIIT mandatory GB/T standards for optical radiation and structural durability testing compress headset certification timelines. SAMR enforces national standard specifications for head-mounted display safety that manufacturers must clear for commercial distribution. Shanghai's premium urban retail space absorption is compressing margins for independent operators while state-backed entertainment infrastructure receives preferential leasing terms.
Japan
Theme park integrations at Universal Studios and Disney clusters command premium per-capita spending through narrative depth unavailable in modular arcade formats. METI oversees industrial standards coordination while PMDA maintains jurisdiction over medical device classifications affecting rehabilitation VR deployments. Tokyo's escalating commercial real estate costs are forcing independent venues toward suburban mall footprints with lower throughput potential.
Germany
Physical therapy clinics in Munich and Hamburg pilot balance and motor-skill recovery protocols using warehouse-scale free-roam systems with fall-detection safety protocols. The EU AI Act's risk classification framework for biometric inference systems reclassifies pupil-tracking-enabled headsets as high-risk AI, forcing hardware architecture redesigns. Berlin's startup ecosystem is incubating privacy-preserving tracking alternatives to circumvent GDPR consent workflow complexity.
India
Bangalore and Mumbai shopping mall expansions are creating greenfield deployment opportunities before domestic regulatory frameworks for biometric data collection mature. BIS standards for electronic equipment safety remain less prescriptive than GB/T or CE marking requirements, reducing certification overhead for imported hardware. Hyderabad's entertainment infrastructure investments are attracting venue operators seeking first-mover positioning in underpenetrated metropolitan markets.
Location Based VR Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with proprietary content studios capturing premium positioning in theme park integrations while hardware OEMs supply standardized configurations to high-throughput arcade operators. The vendor base organizes around three strategic archetypes: motion-capture arena developers, warehouse-scale free-roam system integrators, and tethered headset ecosystem providers. Competitive maneuvering concentrates on multi-year enterprise training contracts and rapid-setup pop-up formats for festival circuits.
Within the motion-capture arena tier, Sandbox VR and Zero Latency occupy positions exemplifying divergent geographic and format strategies, with the former representing social entertainment venue concentration across North American cities and the latter anchoring technology leadership through warehouse-scale free-roam systems in premium retail spaces. HTC Corporation sits within the professional deployment archetype, its tethered headset configurations designed for high-throughput commercial installations. These three entities collectively illustrate how hardware-software integration depth separates premium-tier competitors from modular equipment suppliers.
| Leading Market Players |
|---|
| Sandbox VR |
| Zero Latency |
| Hologate |
| Dreamscape Immersive |
| VRstudios |
| HTC Corporation |
| Meta |
| Survios |
| The VOID |
| Others |
Value Chain & Pricing Dynamics
Display driver foundry capacity in Taiwan flows through tiered hardware configurations that separate premium tethered installations from economy standalone pop-up formats, with venue operators absorbing cost compression through extended refresh cycles or reduced haptic integration.
Pricing Analysis
Distributor margins on tethered headset bundles compress pricing flexibility for independent venue operators while direct-to-OEM volume discounts concentrate procurement power with enterprise training buyers. Three-tier pricing structure across premium, standard, and economy levels separates full-body motion capture arenas from compact arcade booths and mobile festival configurations. Pricing pressure stems from GPU supply concentration extending hardware lead times beyond sustainable operating windows. Corporate training facilities exhibit lowest price sensitivity due to multi-year contract consolidation, while independent entertainment centers face acute margin compression from real estate cost escalation.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Taipei, and Los Angeles anchor hub-and-spoke patterns that feed venue hardware into North American, Chinese, and Japanese markets. Taiwan and South Korea concentrate high-refresh display driver production while China dominates haptic feedback component manufacturing and final headset assembly. Raw material dependencies include rare earth magnets for lighthouse tracking motors, gallium nitride substrates for wireless transmission modules, and specialized polymers for force-feedback vest housings. Single-source vulnerability around Taiwan-based foundry capacity creates systemic risk for tethered platform availability. Distribution runs through authorized equipment distributors serving venue chains and direct manufacturer relationships for enterprise training deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's biometric risk classification functions as a regulatory compounder, forcing hardware architecture redesigns that create compliance-driven demand for privacy-preserving tracking alternatives.
For Market Incumbents: Anchor market position through backward integration into proprietary motion capture content pipelines that lock enterprise training buyers into multi-year renewal cycles. Defend against standalone headset displacement by accelerating lighthouse system latency reduction below competitor thresholds. Certification investment in MIIT GB/T compliance creates barrier against emerging Chinese hardware OEMs. For New Entrants and Emerging Players: The mid-tier price gap between Sandbox VR premium arenas and economy mobile pop-ups offers white-space entry for modular haptic configurations targeting secondary US urban markets. India's greenfield mall expansions in Bangalore and Mumbai present lowest regulatory friction for first-mover venue establishment. Go-to-market through festival circuit operators seeking rapid-setup inside-out tracking systems bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where venue operating margins fall below sustainable thresholds in Tokyo, New York, and Shanghai premium retail corridors. Long-term viability favors vertically integrated content-hardware platforms with captive enterprise training pipelines over pure equipment suppliers. Signal to watch: FCC 6 GHz spectrum expansion enabling denser multiplayer synchronization in compact footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Motion Capture Content Pipeline | Locks enterprise aviation and energy buyers into renewable training contracts with custom hazard simulation modules. |
| MIIT GB/T Certification Acceleration | Compresses domestic Chinese venue deployment timelines against slower FDA and PMDA approval pathways. |
| Inside-Out Tracking Modularization | Enables mobile pop-up operators to reduce festival setup from days to hours without external lighthouse installation. |
| Privacy-Preserving Hardware Architecture | Circumvents EU AI Act high-risk classification for pupil-tracking systems in German rehabilitation clinic deployments. |
| Corporate Training Arena Consolidation | Squeezes independent entertainment venues from premium Houston and Aberdeen commercial real estate through dedicated simulation facilities. |
Study Parameters
Bottom-up venue deployment modeling reconciled against top-down hardware shipment tracking forms the analytical core of this study. Primary interviews with venue operations directors, haptic hardware procurement leads, corporate training facility managers, and MIIT certification specialists combined with secondary validation against FCC spectrum allocation filings, SAMR GB/T standard documentation, EU AI Act regulatory texts, and venue chain expansion announcements. Triangulation across these sources calibrated installation forecasts against tethered and standalone platform production data.
Input-output matrices mapped hardware component flows through Taiwan foundries, Chinese assembly facilities, and regional distribution hubs to venue deployment across the analysis window. Segmentation dimensions modeled include service type permanence, platform architecture, end-use procurement cycle, and regulatory compliance tier. CAGRs derived from unit economics of arcade throughput versus theme park per-capita spending trajectories, with forecast inputs incorporating motion tracking latency reduction curves and haptic feedback adoption rates in corporate training verticals.
The model assumes a particular technology adoption path; alternative pathways for inside-out camera arrays displacing lighthouse tracking would alter the outlook for premium external hardware vendors. Forecasts reflect documented assumptions around MIIT certification timeline compression and GDPR biometric consent workflow standardization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Industrial Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality in Therapy Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market