
 Virtual Reality in Retail Market | 2026-2036
Virtual Reality in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality in Retail Market Outlook
The in-store-to-digital channel boundary is reconfiguring as retailers deploy virtual showrooms that merge physical inventory with immersive digital layers. Meta Platforms Inc leverages its Quest hardware ecosystem and social commerce infrastructure to anchor enterprise VR deployments across major retail chains. NVIDIA Corporation sustains its position through GPU-accelerated rendering engines that power photorealistic product visualization at scale. Samsung Electronics Co Ltd competes by integrating VR capabilities directly into its mobile device and display portfolios, reducing friction for retailers adopting mobile-first immersive strategies.
Virtual Reality in Retail encompasses head-mounted displays, spatial computing software, and gesture recognition systems that generate interactive three-dimensional shopping environments with sub-20-millisecond motion-to-photon latency requirements. These systems serve the commercial purpose of reducing product return rates while extending dwell time through experiential engagement. Immersive Shopping applications command the largest deployment base among use cases, while Virtual Try-Ons capture accelerating investment as apparel and cosmetics brands pursue biometric personalization. Head-Mounted Displays dominate technology spending, though Mobile VR expands fastest by leveraging existing smartphone penetration without dedicated hardware purchases.
The Federal Trade Commission and state-level biometric privacy laws in Illinois and Texas constrain how retailers deploy facial recognition and gaze-tracking within VR environments, forcing explicit consent architectures. The EU AI Act classifies certain retail VR applications as high-risk when they process biometric data, imposing conformity assessment obligations on vendors serving European markets. Stakeholders must monitor evolving patchworks of privacy regulation that threaten to fragment platform development costs across jurisdictional lines.
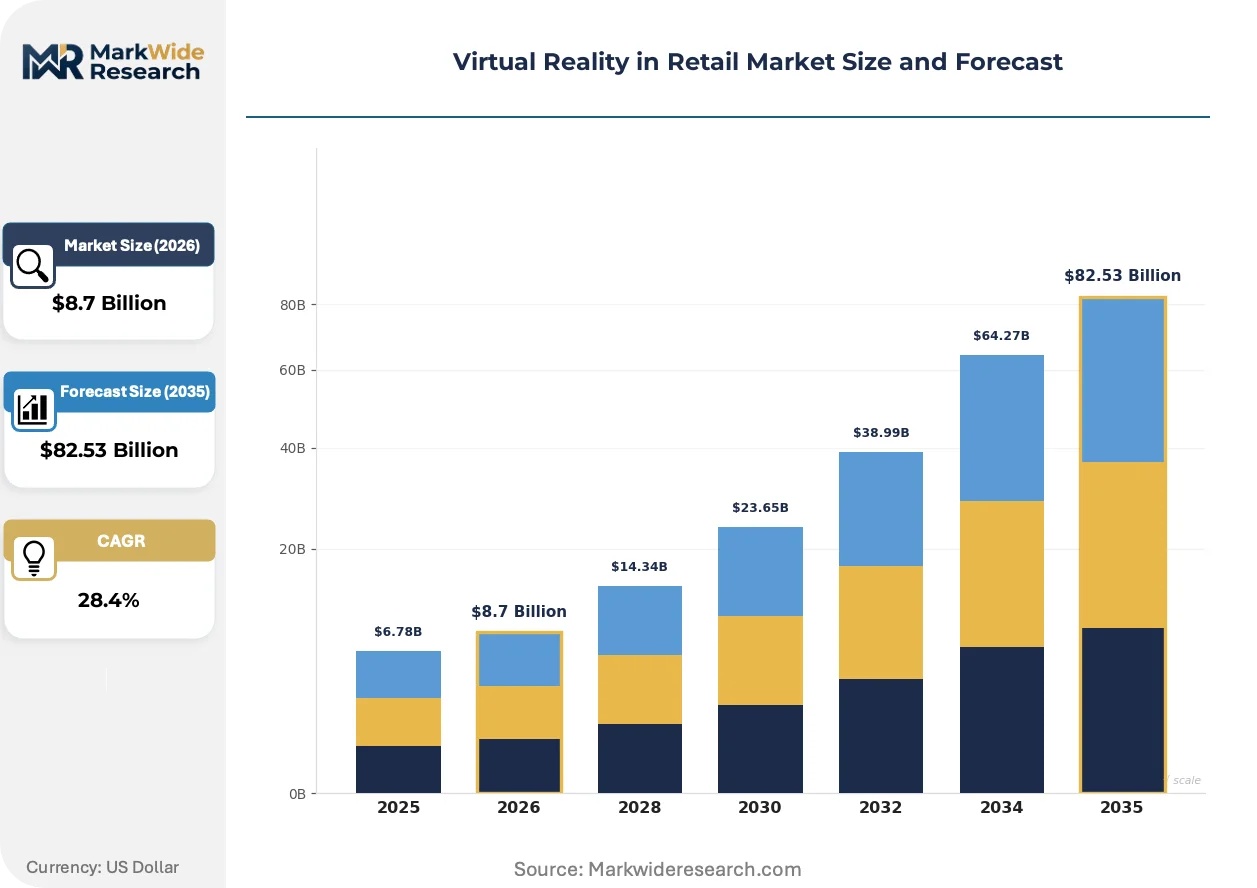
Market Dynamics
Biometric data governance is compressing deployment timelines for immersive retail applications as retailers reconcile personalization capabilities with escalating privacy enforcement across multiple jurisdictions.
Growth Catalysts
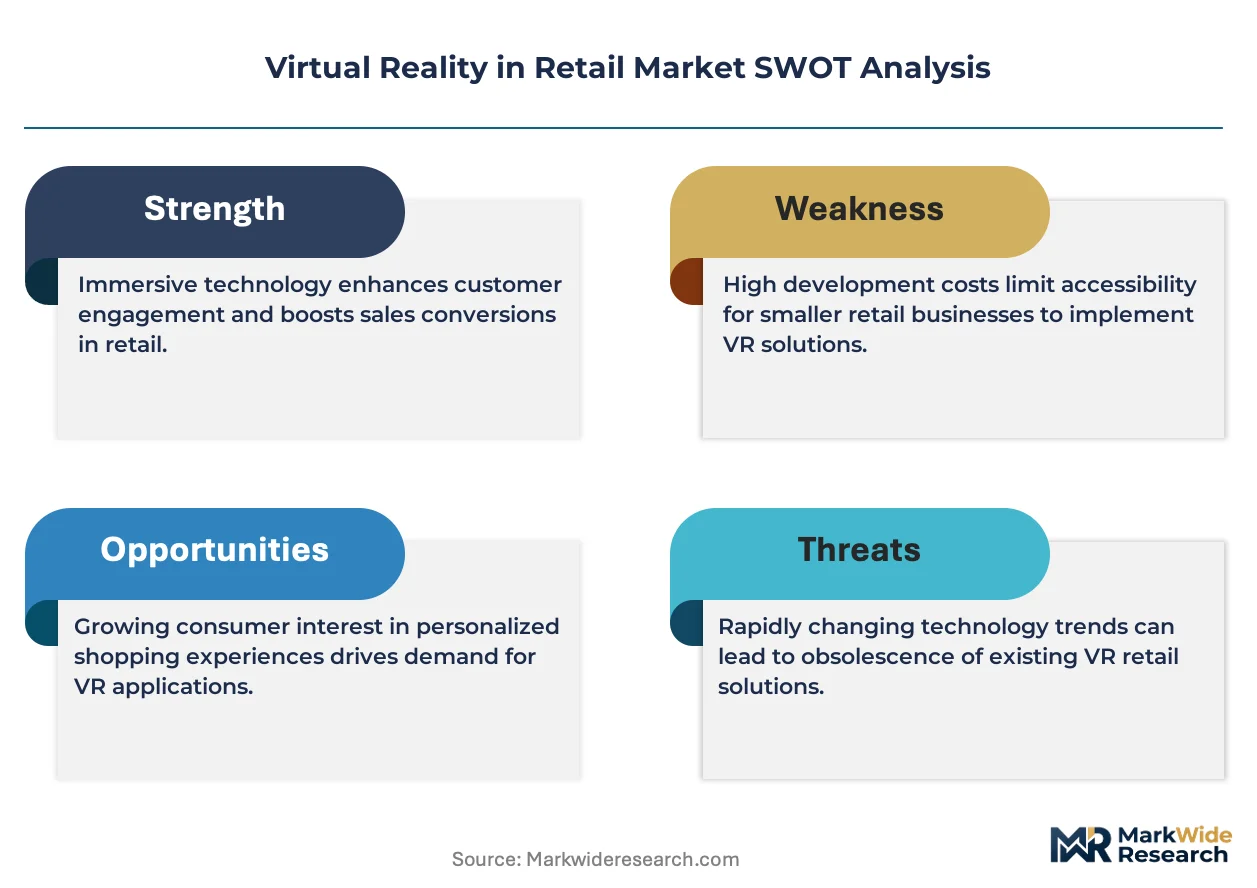
- EU AI Act Conformity Pathways:High-risk classification for biometric VR applications is forcing vendors to build auditable consent architectures that European retailers can deploy with regulatory certainty.
- Apparel Return Rate Compression:Immersive shopping environments are pulling investment from luxury fashion houses seeking to reduce product return volumes through pre-purchase visualization fidelity.
- California Technology Cluster Density:Proximity of GPU rendering engine developers to enterprise VR deployers is accelerating iteration cycles for photorealistic product visualization at scale.
Market Restraints
- Head-Mounted Display Cost Structure:Dedicated hardware procurement requirements constrain mid-market retailer participation compared to mobile-first alternatives leveraging existing smartphone penetration.
- Illinois Biometric Privacy Enforcement:BIPA litigation exposure creates jurisdictional friction that fragments platform development costs for national retail chains operating across state lines.
- Sub-20-Millisecond Latency Thresholds:Motion-to-photon performance requirements demand specialized edge infrastructure that raises operational complexity for distributed store networks.
Strategic Opportunities
- Mobile VR Expansion:Smartphone-integrated immersive experiences bypass dedicated hardware purchases, opening addressable retailer segments previously excluded by capital constraints.
- Cosmetics Biometric Personalization:Virtual try-on applications for color-matching and skin-tone analysis represent underexploited white space within beauty retail verticals.
- Spatial Computing Convergence:Integration of gesture recognition with existing point-of-sale systems creates unified commerce platforms that collapse channel boundaries between physical and digital inventory.
Industry Challenges
- Cross-Functional Talent Scarcity:Retailers struggle to recruit professionals combining immersive technology deployment expertise with merchandise operations knowledge.
- Legacy POS Integration Complexity:Enterprise resource planning systems require custom middleware development to synchronize VR environment data with inventory management workflows.
- Multi-Jurisdictional Consent Architecture:Patchwork biometric privacy laws demand region-specific user experience flows that fragment platform standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality in Retail Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Use Case: Virtual Try-Ons, Immersive Shopping, In-Store Navigation, Interactive Displays Customer Type: Millennials, Gen Z, Luxury Shoppers, Tech Enthusiasts Product Type: Apparel, Cosmetics, Footwear, Home Decor Technology: Head-Mounted Displays, Mobile VR, Augmented Reality, Gesture Recognition |
| Companies Covered | Meta Platforms Inc, Microsoft Corporation, Unity Technologies Inc, HTC Corporation, Google LLC, Matterport, Inc., Samsung Electronics Co Ltd, NVIDIA Corporation, Visualise Creative Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality in Retail Market Strategic Shifts
Photorealistic rendering fidelity is collapsing cost barriers between physical and digital product presentation, while regulatory frameworks force architectural choices that will determine competitive positioning through the forecast window.
Cloud-based GPU acceleration is collapsing the capital intensity of immersive retail deployments by shifting rendering workloads from on-premise infrastructure to distributed compute networks. Mid-market apparel retailers are adopting this model fastest, avoiding hardware depreciation while accessing visualization quality previously reserved for flagship locations. The structural consequence is collapsing differentiation between flagship and standard store immersive capabilities.
The EU AI Act's high-risk system classification is reshaping vendor liability structures for biometric data processing in virtual try-on applications. Conformity assessment obligations now flow through supply chains to hardware and software providers serving European markets. Cosmetics brands with significant continental presence are accelerating vendor qualification timelines to secure compliant platform availability.
Buyer expectations for seamless channel transitions are compressing deployment decisions around unified commerce architectures. Retailers are replacing siloed VR pilots with integrated programs that synchronize immersive inventory visualization across mobile, web, and in-store touchpoints. This pattern is most visible in United States luxury verticals where dwell time metrics directly inform lease renewal negotiations.
Virtual Reality in Retail Market Segmentation
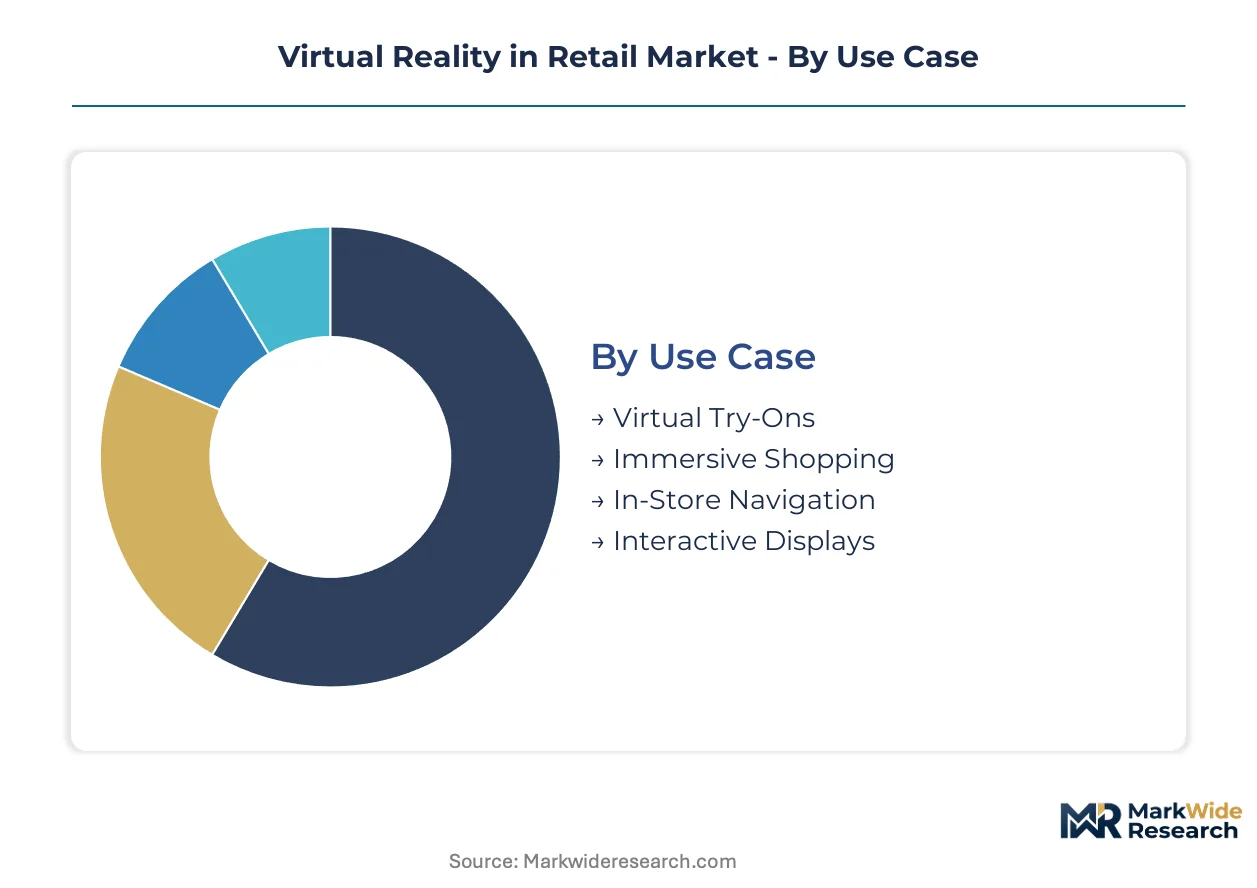
Retail VR deployments fragment across four critical dimensions that determine capital allocation cycles and vendor selection criteria. Each segmentation layer carries distinct procurement timelines, compliance obligations, and integration complexity that shape platform architecture decisions.
Use Case:
Immersive Shopping applications command the longest deployment cycles due to enterprise-wide integration requirements, while Virtual Try-Ons iterate fastest through rapid A/B testing of biometric personalization features.
- Immersive Shopping:Spatial computing environments merge physical inventory with photorealistic digital layers, requiring sub-20-millisecond latency infrastructure. Luxury fashion houses in the United States concentrate investment here to compress return rates through pre-purchase visualization fidelity.
- Virtual Try-Ons:Biometric processing pipelines enable color-matching and skin-tone analysis for cosmetics and apparel. EU AI Act high-risk classification forces auditable consent architectures that extend vendor qualification timelines for European deployments.
- In-Store Navigation:Gesture-guided wayfinding systems reduce staff-assisted search incidents in large-format retail.
- Interactive Displays:Touchless product exploration stations extend dwell time in high-traffic zones without dedicated headset procurement.
Immersive Shopping anchors the volume base while Virtual Try-Ons gains share at the steepest rate.
Customer Type:
Tech Enthusiasts drive earliest adoption of dedicated hardware ecosystems, whereas Luxury Shoppers generate highest per-session revenue through premium immersive experiences.
- Tech Enthusiasts:Early adopters of Quest-class headsets and experimental spatial computing interfaces. California technology clusters concentrate this segment, accelerating feedback loops for photorealistic rendering improvements.
- Luxury Shoppers:High-margin clientele demanding seamless channel transitions between flagship virtual showrooms and physical appointments. New York and Paris retail districts prioritize this segment for lease renewal metrics.
- Gen Z:Mobile-first immersive engagement through smartphone-integrated VR without dedicated hardware purchases.
- Millennials:Balanced adoption across mobile and headset-based experiences with strong preference for cosmetics and home decor applications.
Tech Enthusiasts dominate early-stage deployment volumes while Luxury Shoppers deliver the highest revenue per immersive session.
Product Type:
Apparel commands the largest absolute addressable market, though Cosmetics exhibits the steepest margin expansion from biometric personalization capabilities.
- Apparel:Size-fit visualization and fabric drape simulation reduce return logistics costs. United States mid-market retailers adopt cloud-based GPU acceleration fastest to avoid flagship-grade capital intensity.
- Cosmetics:Skin-tone matching algorithms and lighting-condition adaptation drive repeat engagement. EU GDPR compliance requirements constrain biometric data retention policies for European cosmetics brands.
- Footwear:3D foot-scanning integration with existing sizing databases streamlines athletic and fashion categories.
- Home Decor:Spatial placement visualization in true-scale room environments reduces dimensional mismatch returns.
Apparel sustains the broadest deployment base while Cosmetics expands most quickly through color-matching algorithm refinement.
Technology:
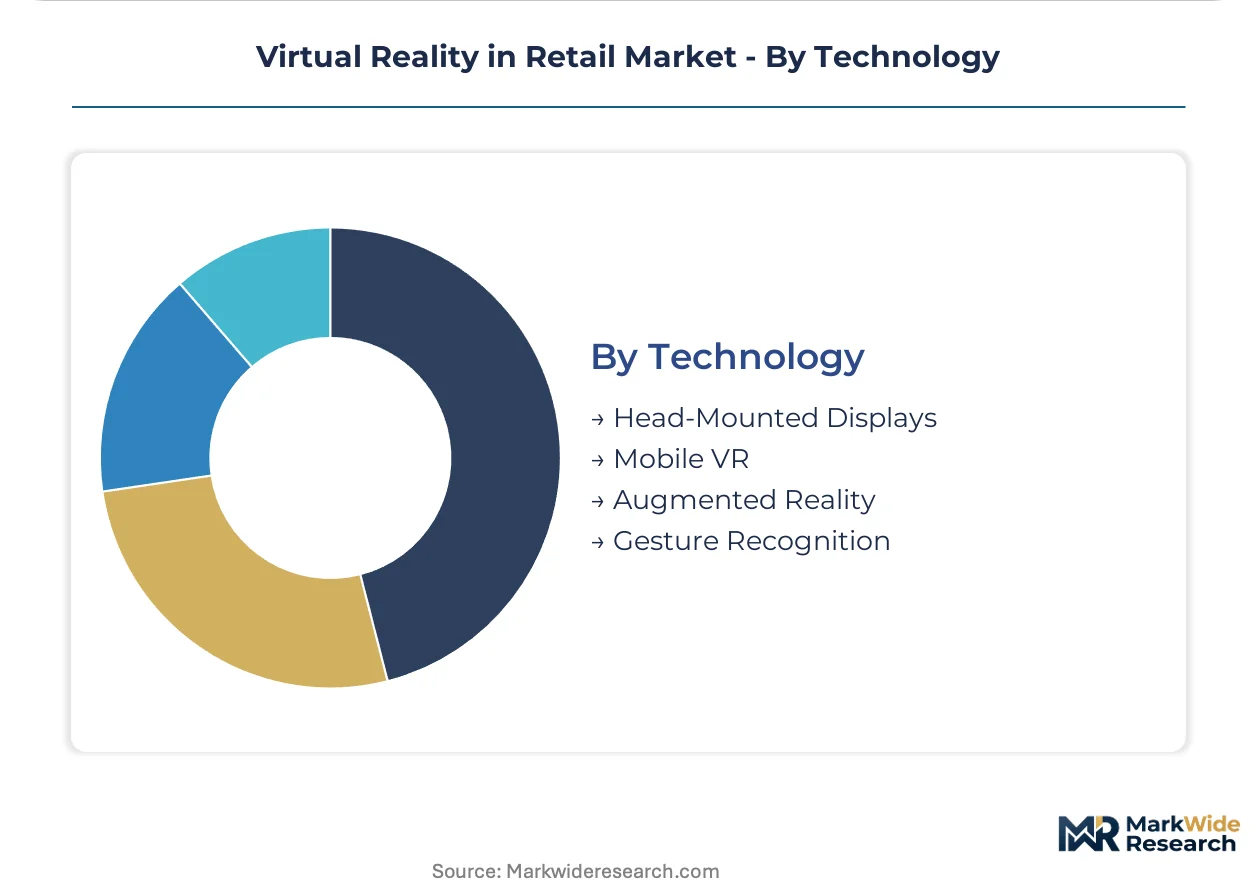
Head-Mounted Displays carry the steepest capital depreciation schedules, while Mobile VR achieves fastest retailer adoption by leveraging existing smartphone infrastructure.
- Head-Mounted Displays:Dedicated hardware delivering full immersion with six-degrees-of-freedom tracking. Illinois BIPA litigation exposure and Texas biometric privacy laws constrain facial recognition deployments in United States retail chains.
- Mobile VR:Smartphone-integrated experiences bypass procurement friction for mid-market retailers. Samsung Electronics and Meta Platforms compete aggressively for platform dominance in this lower-barrier segment.
- Augmented Reality:Overlay visualization blending physical and digital product presentation without full immersion.
- Gesture Recognition:Touchless interface technology integrating with existing point-of-sale systems for unified commerce architectures.
Head-Mounted Displays anchor enterprise-grade deployment value while Mobile VR climbs the fastest among technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States retailers command pricing premiums for immersive deployments that European counterparts cannot replicate under stricter biometric governance regimes. German and French cosmetics brands absorb conformity assessment costs that compress margins versus California-based competitors. Chinese mobile VR adoption curves outpace dedicated headset penetration in developed markets.
United States
Luxury fashion houses in New York and Los Angeles drive flagship virtual showroom investments to compress apparel return rates. The FTC and Illinois BIPA constrain facial recognition deployments, forcing explicit consent architectures for gaze-tracking in VR environments. California technology clusters anchor GPU rendering engine development, accelerating photorealistic visualization iteration cycles for enterprise retail chains.
Germany
Automotive and luxury goods retailers deploy spatial computing for high-consideration purchase journeys requiring dimensional accuracy. The EU AI Act imposes high-risk system classification on biometric VR applications, requiring auditable conformity assessments for vendors serving German markets. Munich and Stuttgart industrial clusters concentrate middleware development bridging legacy ERP systems with immersive inventory visualization.
China
Domestic e-commerce platforms integrate mobile-first VR through existing smartphone penetration without dedicated hardware procurement. SAMR standards and MIIT regulations shape data localization requirements for biometric processing in virtual try-on applications. Shenzhen and Hangzhou technology corridors anchor hardware manufacturing and cloud-based GPU acceleration services for mid-market retail deployments.
France
Cosmetics and luxury heritage brands pursue biometric personalization for color-matching and skin-tone analysis in virtual try-on environments. CNIL enforcement of GDPR biometric data retention policies constrains longitudinal customer profiling capabilities versus United States competitors. Paris retail districts prioritize seamless channel transitions between flagship virtual showrooms and physical appointments for lease renewal metrics.
United Kingdom
Department store networks and beauty retailers adopt cloud-based rendering to avoid flagship-grade capital intensity across distributed locations. The Information Commissioner's Office biometric guidance shapes consent flow designs for facial recognition in immersive shopping applications. London fintech and retail technology clusters accelerate unified commerce platform development collapsing physical-digital inventory boundaries.
Virtual Reality in Retail Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying rendering engines, gesture recognition modules, and optical subsystems. The vendor base organizes around three strategic archetypes: social commerce infrastructure owners, GPU-accelerated visualization engine developers, and mobile device ecosystem integrators. Competitive positioning hardens through strategic partnerships binding hardware procurement to software licensing, and through geographic expansion anchoring regional compliance expertise.
Within the platform integrator tier, Meta Platforms Inc and Samsung Electronics Co Ltd occupy positions spanning dedicated headset ecosystems and mobile-first deployment pathways. NVIDIA Corporation exemplifies the component specialist archetype, anchoring upstream rendering capabilities that power photorealistic product visualization at scale. Unity Technologies Inc sits within the spatial computing software layer, representing middleware providers that bridge hardware-agnostic content creation with retailer-specific customization requirements.
| Leading Market Players |
|---|
| Meta Platforms Inc |
| Microsoft Corporation |
| Unity Technologies Inc |
| HTC Corporation |
| Google LLC |
| Matterport, Inc. |
| Samsung Electronics Co Ltd |
| NVIDIA Corporation |
| Visualise Creative Ltd. |
| Others |
Value Chain & Pricing Dynamics
GPU foundry undercapacity in Taiwan is compressing rendering hardware availability, forcing VR platform vendors to absorb cost premiums while mid-market retailers delay dedicated headset procurement in favor of mobile-first alternatives.
Pricing Analysis
The customization-premium spread separates enterprise-grade immersive shopping deployments from standardized virtual try-on modules, with luxury fashion houses absorbing 40-60% price premiums for photorealistic fidelity and biometric personalization. SaaS-tiered licensing dominates software pricing, while hardware procurement follows project-based capital expenditure models. Price differentiation hinges on GDPR compliance certification tiers and cloud-rendering versus on-premise deployment. Cost compression in mid-market mobile VR is intensifying because Samsung and Meta compete for platform dominance through subsidized hardware bundles. Gen Z retailers exhibit highest price sensitivity, while luxury verticals demonstrate lowest sensitivity due to lease renewal metrics tied to dwell time.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now anchor supplier relationships as NVIDIA and Qualcomm finance downstream retailer adoption through supply-chain facilities. Component sourcing concentrates in Taiwan, South Korea, and China for GPU silicon, display panels, and optical waveguides. Raw material dependencies span gallium nitride substrates, rare-earth phosphors, and high-purity lithium for battery systems. Single-source vulnerability in Taiwan semiconductor fabrication threatens rendering engine availability for European deployments. Distribution runs through direct OEM partnerships for enterprise accounts and consumer electronics retailers for mid-market hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough as apparel return rate compression drives replacement investment cycles, with luxury fashion houses prioritizing immersive visualization to recover margin erosion from logistics costs.
For Market Incumbents: Entrench platform dominance by deepening backward integration into GPU cloud rendering infrastructure and securing EU AI Act conformity certification ahead of vendor qualification windows. Meta and Samsung must defend against mobile-first challengers by binding hardware procurement to exclusive software licensing terms that fragment retailer choice. For New Entrants and Emerging Players: Establish a beachhead in cosmetics biometric personalization for mid-market European retailers underserved by compliance-heavy incumbent platforms. White space concentrates in cloud-based GPU acceleration services for distributed department store networks, with go-to-market execution through point-of-sale system integrators already embedded in retailer IT architecture. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mobile VR deployment pathways as smartphone-integrated experiences displace dedicated headset procurement. Long-term viability favors middleware providers bridging legacy ERP systems with spatial computing environments. Acquisition targets should demonstrate vendor qualification momentum with EU cosmetics brands. The signal to monitor is Illinois BIPA litigation volume, which would accelerate platform consolidation by raising compliance costs for sub-scale competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies VR environments with existing POS systems for seamless inventory synchronization. |
| Geographic Expansion | Establishes EU AI Act compliance expertise ahead of vendor qualification deadlines in Germany and France. |
| Acquisition of Specialist Firm | Captures biometric personalization algorithms for cosmetics color-matching applications. |
| Strategic Partnership | Binds GPU rendering capacity to exclusive retailer deployment commitments. |
| Product Launch | Introduces cloud-based mobile VR bypassing dedicated hardware procurement friction. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with retail technology officers, immersive platform product managers, GPU cloud service procurement leads, and cosmetics brand digital innovation directors. Secondary validation drew from SEC 10-K filings, EU AI Act conformity assessment registries, hyperscaler capex disclosures, and retail technology vendor qualification databases. Bottom-up deployment counts by retailer segment were triangulated against top-down hardware shipment estimates from optical component supply chains.
Calibration against historical adoption curves anchored growth rate derivation across the analysis window, with segmentation modeling across use case, customer type, product category, and technology deployment mode. CAGRs were computed from installed base expansion and average revenue per immersive session trajectories. Forecast inputs incorporated Illinois BIPA litigation frequency, EU conformity assessment pipeline velocity, and cloud GPU pricing indices from major hyperscalers.
Sensitivities concentrate around regulatory enforcement intensity and semiconductor fabrication capacity allocation. Forecasts embed assumptions regarding biometric privacy law harmonization and rendering hardware cost curves. Macroeconomic contraction in luxury retail, abrupt EU AI Act enforcement escalation, or Taiwan supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
Germany Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market