
 VR Headsets Market | 2026-2036
VR Headsets Market Size, Share, and Industry Trends Forecast 2026-2036
VR Headsets Market Insights
Aftermarket service revenue from enterprise VR fleet management is narrowing as vendors bundle extended support into initial hardware contracts. Meta Platforms leverages its social platform ecosystem to sustain consumer attachment rates. Sony Group Corporation anchors premium tethered systems through exclusive content licensing with major game studios. HTC Corporation specializes in location-based entertainment hardware, competing against lower-cost Asian manufacturers through modular tracking architectures.
A virtual reality headset comprises a head-mounted display with stereoscopic lenses, inertial measurement units, and spatial audio transducers engineered to render immersive three-dimensional environments at refresh rates exceeding 90 Hz to prevent motion sickness. Standalone headsets now dominate unit shipments by eliminating PC dependency, while eye-tracking modules represent the fastest-growing technology segment as foveated rendering reduces GPU load. Enterprise training use cases command the highest per-unit margins, whereas consumer gaming generates volume scale across tethered and standalone product types.
The FDA regulates VR therapeutic devices under software-as-medical-device pathways, while the EU AI Act imposes risk-classification requirements on biometric data processing including gaze tracking. FCC electromagnetic emissions standards and CE marking directives govern radio frequency and safety compliance for headset distribution. Stakeholders must monitor evolving interoperability mandates between hardware platforms and content ecosystems as regulatory fragmentation threatens scale economics.
Market Dynamics
Foveated rendering architectures are collapsing GPU requirements for standalone headsets, enabling medical-grade visual fidelity without tethered workstations. This technical inflection redistributes value capture from discrete graphics suppliers toward integrated SoC vendors and eye-tracking module specialists.
Growth Catalysts
- FDA Software-as-Medical-Device Pathway:Therapeutic VR deployments for pain management and psychiatric intervention now access accelerated clearance timelines, expanding reimbursable indications beyond surgical training.
- Healthcare Cadaver Lab Replacement:Academic medical centers in the United States and Germany are retiring physical anatomy facilities in favor of haptic-enabled immersive simulation, creating durable hardware refresh cycles.
- EU AI Act Biometric Compliance:Risk-classification frameworks for gaze-tracking data processing are forcing standardization of privacy-preserving eye-data architectures, reducing vendor fragmentation in enterprise therapeutic segments.
Market Restraints
- Display Panel Concentration:High-resolution micro-OLED supply concentrates among Korean and Japanese foundries, creating allocation bottlenecks for premium headset SKUs during demand surges.
- Motion Sickness Latency Floor:Sub-20ms motion-to-photon thresholds require specialized display controllers and predictive tracking algorithms that remain costly at volume price points.
- Content Ecosystem Fragmentation:Exclusive licensing arrangements between hardware OEMs and AAA studios lock therapeutic and enterprise buyers into single-vendor procurement, inflating total cost of ownership.
Strategic Opportunities
- India Clinical Training Infrastructure:National medical council accreditation reforms are mandating simulation-based competency verification, opening procurement channels for mid-tier standalone hardware.
- Convergence of Haptics and Force Feedback:Integration of exoskeleton gloves with spatial computing headsets is enabling remote surgical telementoring applications previously confined to physical co-presence.
- Defense Contracting Bundles:United States military pilot training programs are consolidating VR hardware, software, and sustainment into multi-year indefinite-delivery vehicles, favoring vendors with security clearance infrastructure.
Industry Challenges
- Optical Engineer Scarcity:Pancake lens design and waveguide fabrication require specialized talent pools concentrated among Asian camera module suppliers, constraining Western OEM roadmap velocity.
- Interoperability Certification Delays:OpenXR conformance testing for multi-vendor tracking systems extends platform integration timelines by 8-14 months, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Headsets Market |
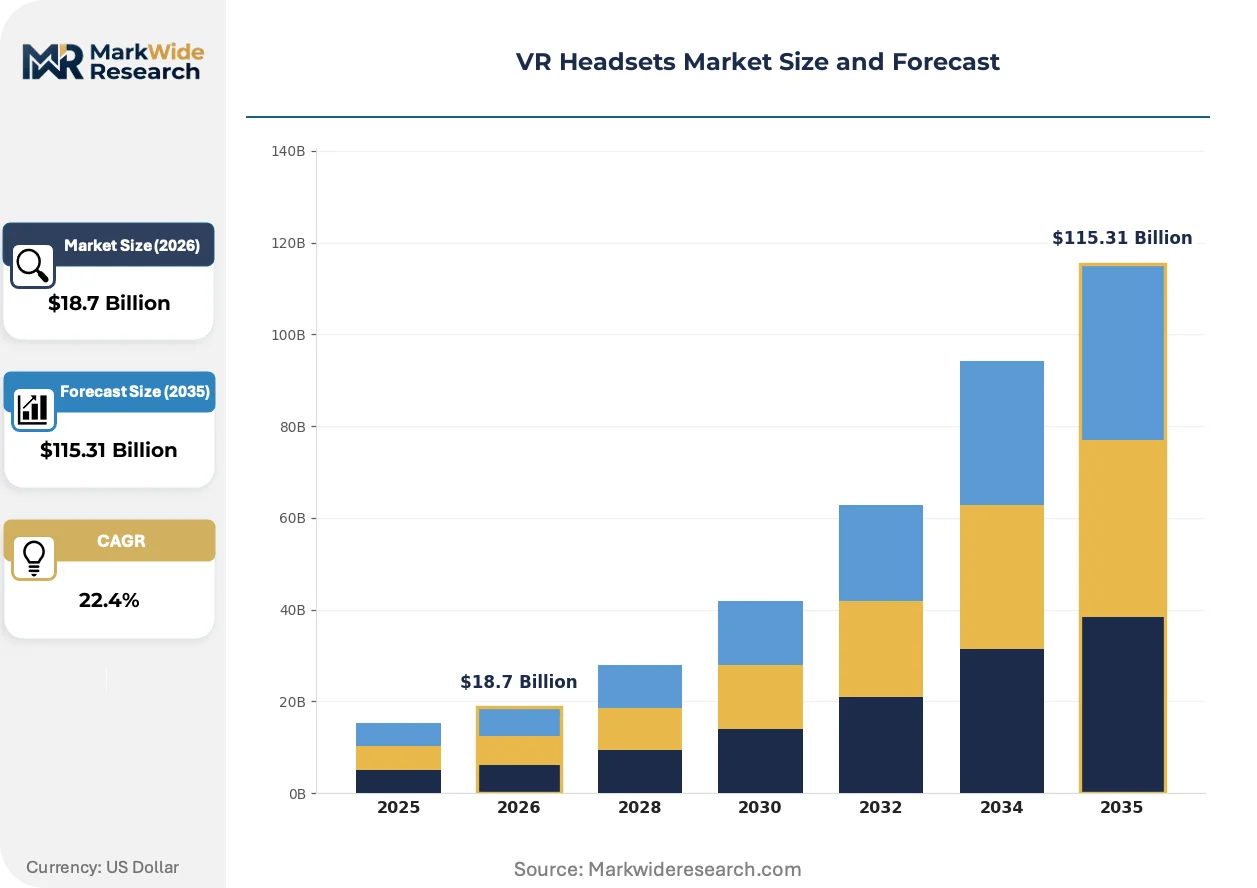
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Tethered, Mobile, PC-Based Use Case: Gaming, Training, Healthcare, Entertainment End User: Consumers, Enterprises, Educational Institutions, Developers Technology: OLED, LCD, 3D Audio, Eye Tracking |
| Companies Covered | Meta Platforms, Sony Group Corporation, HTC Corporation, Pico Interactive, Samsung Electronics, Microsoft Corporation, Apple, ByteDance, DPVR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Headsets Market Trends and Innovations
Spatial computing architectures are dissolving the boundary between physical and digital interaction modalities. Three convergent developments are compressing hardware refresh cycles and redefining competitive moats across therapeutic, enterprise, and defense verticals.
Pancake optical stacks are collapsing the physical volume required for high-resolution immersion, enabling headset form factors compatible with extended clinical wear. Hospital systems in the United States and Germany are adopting these slim-profile devices for bedside pain distraction protocols. The structural consequence is a shift from PC-tethered cart systems toward battery-powered patient-worn hardware that follows care delivery workflows.
The EU AI Act's risk-tiering for biometric inference systems is forcing gaze-data localization within headset processing units rather than cloud transmission. European therapeutic VR developers are rearchitecting software pipelines to satisfy CNIL and national data protection authority precedents. Medical device OEMs targeting EU reimbursement are prioritizing edge-AI silicon with deterministic inference latency over raw compute throughput.
Enterprise buyers are unbundling hardware procurement from content licensing, reversing the integrated-stack model that dominated early commercial VR adoption. Defense training commands and clinical research institutions now issue separate RFPs for headsets, software platforms, and integration services. This purchasing pattern is most pronounced in United States federal contracting and German university hospital consortia, where compliance documentation requirements favor vendor specialization over single-source relationships.
VR Headsets Market Segmentation
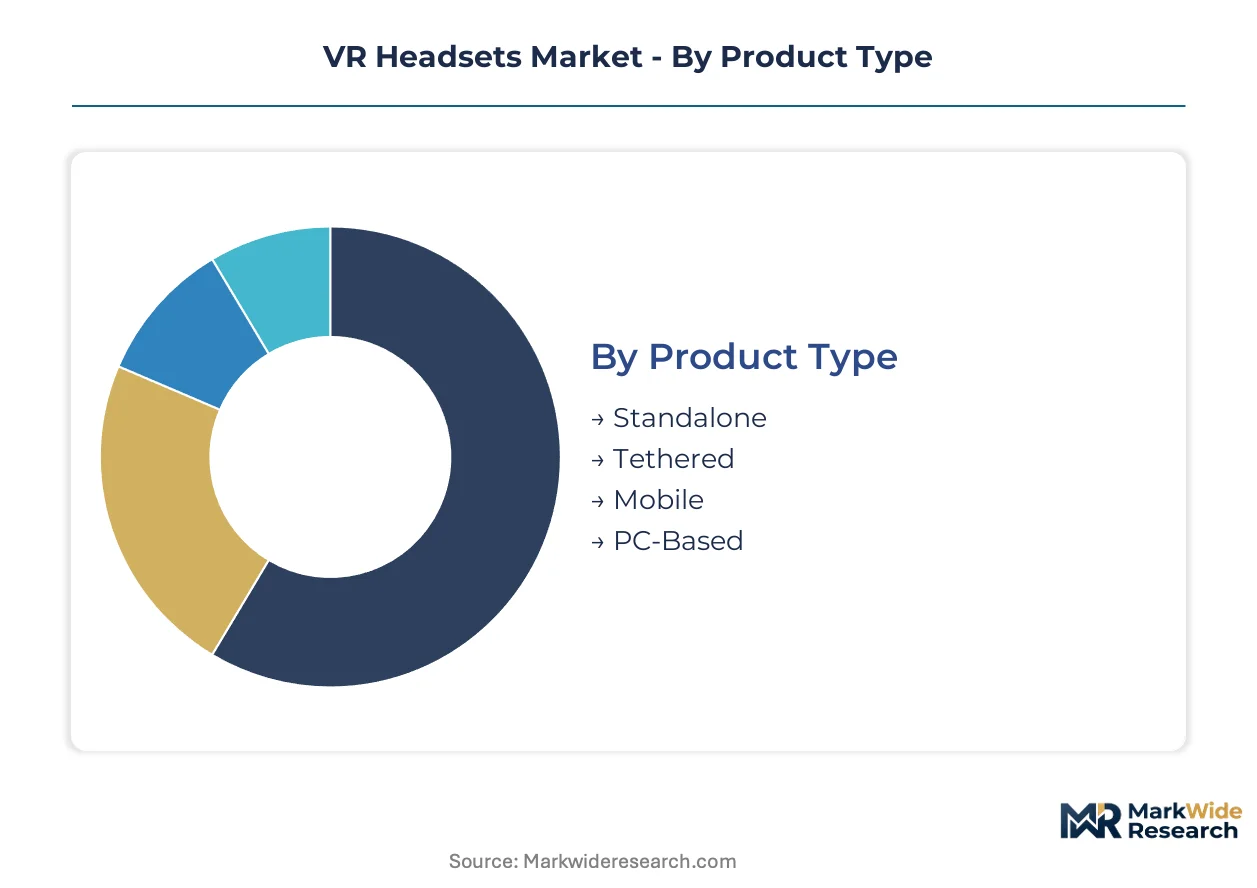
VR headset segmentation reveals divergent hardware requirements across therapeutic precision, enterprise durability, and consumer entertainment use cases. Each dimension—product architecture, application intensity, buyer sophistication, and display fidelity—creates distinct procurement criteria and margin structures that vendors must address through specialized SKU strategies.
Product Type:
The use-case spectrum spans fully autonomous operation for clinical mobility through workstation-dependent rendering for surgical simulation fidelity.
- Standalone:Integrated SoC architectures with onboard rendering eliminate PC dependency, enabling bedside patient distraction protocols in United States hospital systems and mobile training deployments in Indian medical colleges. Battery thermal management and foveated rendering efficiency determine competitive positioning as eye-tracking modules become standard.
- Tethered:External GPU access delivers medical-grade visual fidelity for German anatomy simulation labs and defense pilot training programs requiring sub-20ms motion-to-photon latency. Cable management constraints limit adoption to fixed-installation environments despite superior raw performance.
- Mobile:Smartphone-dependent displays leverage existing device penetration for low-cost consumer entry, though processing limitations exclude therapeutic and enterprise applications.
- PC-Based:External compute dependency with specialized tracking base stations persists in AAA game studio development pipelines and high-fidelity research applications.
The dominant share belongs to Standalone, while Tethered is closing the gap fastest in reimbursable healthcare segments.
Use Case:
Application intensity separates entertainment consumption from regulated therapeutic interventions with distinct compliance burdens.
- Gaming:Consumer entertainment drives volume scale through exclusive content licensing and social platform integration, though per-unit margins compress against mid-tier standalone hardware.
- Training:Enterprise and defense simulation commands premium pricing with multi-year sustainment contracts; United States military indefinite-delivery vehicles bundle hardware, software, and security-cleared support infrastructure.
- Healthcare:FDA software-as-medical-device clearance and EU AI Act biometric compliance create regulatory moats for pain management and psychiatric intervention deployments, with German university hospitals and United States academic medical centers leading procurement.
- Entertainment:Location-based venues and cinematic experiences compete on throughput economics against home-based alternatives.
Healthcare commands the steepest expansion trajectory as cadaver lab replacement accelerates across accredited institutions.
End User:
Buyer sophistication determines procurement complexity from individual transaction through federal contracting compliance.
- Consumers:Price-sensitive individual purchasers respond to content library depth and social platform network effects.
- Enterprises:Fleet management requirements favor vendors bundling extended support into initial hardware contracts, reversing standalone aftermarket revenue models.
- Educational Institutions:Indian national medical council accreditation reforms mandating simulation-based competency verification are opening procurement channels for mid-tier hardware with haptic integration.
- Developers:OpenXR conformance and multi-vendor tracking interoperability requirements extend platform integration timelines, compressing independent studio product launch windows.
Enterprises concentrate the highest per-unit margins, while Educational Institutions are expanding procurement fastest under regulatory mandate.
Technology:
Display and sensor architectures determine visual fidelity thresholds and GPU load efficiency across price tiers.
- OLED:Korean and Japanese foundry supply concentration creates allocation bottlenecks for premium micro-OLED SKUs during demand surges, particularly affecting healthcare and defense procurement.
- LCD:Cost-optimized panels dominate consumer volume segments with acceptable fidelity for non-clinical applications.
- 3D Audio:Spatial audio transducers engineered for immersive three-dimensional environments enhance presence in training and entertainment use cases.
- Eye Tracking:Biometric inference systems for foveated rendering are gaining share fastest as edge-AI silicon satisfies EU AI Act risk-tiering requirements for gaze-data localization.
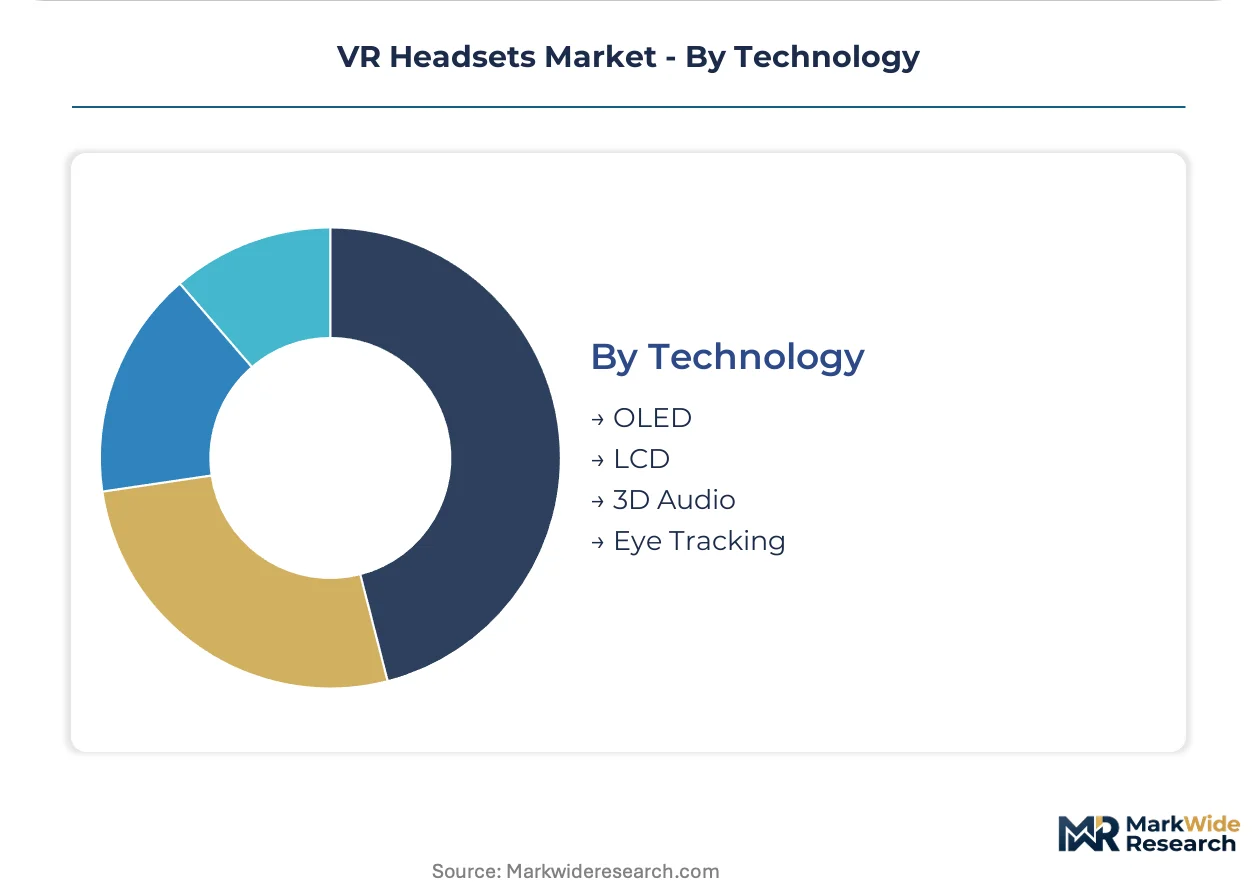
OLED retains the dominant share in premium segments, while Eye Tracking is climbing the fastest as privacy-preserving architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Korean and Japanese foundries control micro-OLED supply for premium headsets, while FDA and EU AI Act pathways concentrate therapeutic demand in the United States and Germany. Defense contracting, clinical research institutions, and AAA game studios drive hardware procurement across distinct national ecosystems.
United States
Defense pilot training programs and academic medical centers anchor demand for tethered systems with sub-20ms latency. The FDA software-as-medical-device pathway accelerates clearance for pain management and psychiatric interventions. Boston and San Francisco clusters host surgical simulation startups replacing cadaver labs with haptic-enabled immersive training.
Germany
University hospital consortia are retiring physical anatomy facilities in favor of simulation-based competency verification. The EU AI Act's risk-tiering for biometric data processing mandates gaze-data localization within headset processing units. Munich and Heidelberg industrial clusters specialize in pancake lens design for slim-profile clinical wear devices.
China
Domestic OEMs compete on cost-optimized standalone architectures for consumer volume segments. MIIT radio frequency standards and GB safety compliance govern headset distribution for location-based entertainment venues. Shenzhen and Beijing hardware ecosystems concentrate pancake optical stack and waveguide fabrication capabilities.
India
National medical council accreditation reforms mandate simulation-based competency verification for clinical training. CDSCO medical device regulations and BIS safety standards shape procurement requirements for mid-tier standalone hardware. Karnataka and Maharashtra medical colleges are opening procurement channels for haptic-integrated training systems.
Japan
METI industrial policy supports spatial computing R&D for enterprise training and remote collaboration applications. JIS standards and PMDA consultation pathways influence therapeutic device development timelines. Tokyo-Osaka industrial corridors concentrate specialized optical engineering talent for camera module suppliers serving Western OEMs.
VR Headsets Market Competitive Landscape
Platform-integrated technology conglomerates and specialized hardware fabricators split the market across consumer, enterprise, and therapeutic verticals. The vendor base concentrates among entities with captive content ecosystems, defense security clearances, or modular tracking architectures. Three archetypes dominate: social-platform-integrated hardware OEMs, premium tethered system specialists, and location-based entertainment equipment suppliers. Competitive moves center on exclusive content licensing arrangements and multi-year indefinite-delivery vehicle consolidation.
Within the platform-integrated tier, Meta Platforms and ByteDance exemplify social-ecosystem attachment strategies. Sony Group Corporation occupies a position among premium tethered specialists leveraging exclusive AAA studio relationships. HTC Corporation anchors the location-based entertainment equipment segment through modular tracking architectures.
| Leading Market Players |
|---|
| Meta Platforms |
| Sony Group Corporation |
| HTC Corporation |
| Pico Interactive |
| Samsung Electronics |
| Microsoft Corporation |
| Apple |
| ByteDance |
| DPVR |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's optical stack fabrication clusters dictate downstream pricing power for slim-profile clinical headsets, with waveguide module throughput constraints feeding premium tier scarcity across German and United States hospital procurement cycles. Korean and Japanese micro-OLED foundry allocation bottlenecks amplify this dynamic during defense and healthcare demand surges, compressing margins for mid-tier standalone vendors unable to secure display panel commitments.
Pricing Analysis
Extended support and sustainment contracts now capture the majority of lifetime value in enterprise and defense segments, displacing transactional hardware margins. Three-tier pricing structure across premium tethered systems, standard standalone devices, and economy mobile-dependent headsets separates FDA-cleared therapeutic SKUs from consumer entertainment hardware. Pricing pressure stems from exclusive content licensing inflation as single-vendor procurement locks elevate total cost of ownership for clinical buyers. Educational institutions in India exhibit highest price sensitivity, while United States military indefinite-delivery vehicles demonstrate lowest sensitivity due to bundled security-cleared support requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for Western OEMs dependent on Shenzhen waveguide and pancake lens module sourcing. Display panel supply concentrates in South Korea and Japan, while edge-AI silicon for gaze-data localization feeds from Taiwan and United States foundries. Single-source vulnerability persists for specialized optical engineering talent concentrated among Asian camera module suppliers. Distribution runs through direct enterprise fleet contracts and defense procurement channels, bypassing retail intermediaries for therapeutic and training segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from multi-year sustainment and security-cleared support contracts is expanding faster than hardware unit economics, restructuring vendor profitability toward recurring-revenue models. This shift rewards entities with defense clearance infrastructure and clinical integration capabilities over pure hardware fabricators.
For Market Incumbents: Insulate premium positioning by deepening backward integration into eye-tracking module supply and securing Korean micro-OLED allocation through long-term offtake commitments. Exclusive content licensing arrangements from emerging AAA studios threaten hardware commoditization; counter by bundling FDA software-as-medical-device clearance pathways into hardware contracts to elevate switching costs for clinical buyers.
For New Entrants and Emerging Players: Indian medical college simulation labs offer the most penetrable procurement channel under national accreditation reform mandates mandating haptic-enabled competency verification. Mid-tier standalone hardware with integrated thermal management for extended clinical wear addresses this white space. Target defense subcontractor status through security clearance infrastructure investment rather than direct prime contracting competition.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because FDA and EU AI Act compliance pathways create durable barriers against consumer-electronics entrants lacking medical device certification infrastructure. Acquisition target archetypes include eye-tracking module specialists with deterministic edge-AI latency and haptic glove integrators serving remote surgical telementoring applications. Watch for OpenXR conformance acceleration as signal of platform consolidation enabling multi-vendor procurement unbundling.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerated clearance timelines expand reimbursable therapeutic indications beyond surgical training applications. |
| EU AI Act Biometric Compliance Certification | Gaze-data localization architectures satisfy CNIL precedents and unlock German university hospital procurement. |
| Defense Security Clearance Infrastructure Investment | Multi-year indefinite-delivery vehicles consolidate hardware, software, and sustainment into single-source relationships. |
| Haptic-Exoskeleton Glove Integration Partnership | Remote surgical telementoring applications previously confined to physical co-presence become technically viable. |
| Korean Micro-OLED Long-term Supply Agreement | Allocation security during demand surges protects premium SKU roadmaps for healthcare and defense segments. |
Research Methodology
A spread of perspectives from VR hardware engineering leads, clinical simulation directors at German university hospitals, United States defense training command procurement officers, and eye-tracking module specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation, SEC disclosures from platform-integrated technology conglomerates, and Indian CDSCO medical device registration databases. Bottom-up unit economics from component bill-of-materials analysis triangulated against top-down addressable market sizing across therapeutic, enterprise, and defense verticals.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions spanning product architecture, application intensity, buyer sophistication tier, and display fidelity grade. CAGRs derived from hardware refresh cycle analysis, regulatory approval velocity, and content ecosystem development timelines. Foveated rendering adoption curves and edge-AI silicon cost trajectories supplied industry-specific forecast inputs for standalone versus tethered system mix shifts.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Asian optical module suppliers or accelerated OpenXR conformance by modular tracking vendors would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality in Therapy Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality Display Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market