
 Smart Augmented Reality Glasses for B2B Market | 2026-2036
Smart Augmented Reality Glasses for B2B Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Augmented Reality Glasses for B2B Market Insights
The EU Green Deal is recalibrating energy-efficiency mandates for industrial electronics, pushing B2B AR glass makers toward lower-power optical engines. Microsoft Corporation leverages its Azure cloud backbone to anchor enterprise deployments across regulated European manufacturing sites. Vuzix Corporation specializes in waveguide optics for ruggedized environments, while RealWear Inc. dominates voice-controlled monocular designs for noisy factory floors.
Smart augmented reality glasses for B2B are wearable display systems combining micro-projectors, waveguide lenses, and onboard sensors to overlay digital information onto physical workspaces, typically operating at 40–60 degree fields of view with IP67-rated dust and moisture sealing for industrial durability. Their primary commercial purpose is to deliver hands-free visual guidance that reduces procedural error rates and accelerates technician training cycles. Enterprise Solutions currently occupies the largest revenue pool as consolidated platform contracts replace point-product purchases, while Remote Assistance is the fastest-expanding segment as distributed technical support models displace on-site specialist travel. Gesture Recognition technology leads in precision assembly environments where voice commands face acoustic interference, though Cloud Integration is widening its margin profile through recurring software attach rates.
FDA oversight of AR-based surgical visualization is tightening clinical validation requirements for healthcare-oriented B2B deployments, while FCC equipment authorization rules govern radio-frequency emissions from untethered smart glasses operating in US logistics hubs. OSHA workplace safety standards are beginning to address optical ergonomics and situational awareness risks for employees wearing see-through displays near heavy machinery. Stakeholders must monitor how divergent regional compliance timelines fragment product certification roadmaps and shape go-to-market sequencing.
Market Dynamics
Hands-free AR guidance systems are compressing technician training cycles on automotive assembly floors, with Germany's precision manufacturing corridors setting procurement benchmarks for industrial durability specifications.
Growth Catalysts
- EU AI Act compliance mandates:European industrial sites now require auditable data governance for connected eyewear, creating upgrade cycles for legacy deployments lacking embedded privacy architectures.
- Waveguide optics maturation:Micro-projector brightness thresholds now satisfy outdoor field-service visibility requirements, expanding addressable use cases beyond controlled factory environments.
- Automotive maintenance protocols:Stuttgart and Wolfsburg engineering clusters specify AR-enabled torque guidance for electric powertrain assembly, normalizing enterprise platform contracts over point-product purchases.
Market Restraints
- Optical engine supply concentration:High-brightness micro-OLED fabrication capacity clusters in East Asian foundries, exposing lead-time vulnerability for European and North American OEMs.
- OSHA optical ergonomics uncertainty:Pending workplace safety standards for see-through displays near heavy machinery create procurement hesitation until compliance thresholds clarify.
- LiDAR-based spatial mapping:Alternative hands-free guidance systems using depth sensors without wearable displays threaten niche applications in structured warehouse environments.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Contract assembly incentives attract AR glass final-assembly investment to serve South Asian industrial automation demand.
- FDA surgical visualization pathway:Healthcare-oriented B2B variants face tightened clinical validation requirements, creating first-mover advantage for pre-certified optical architectures.
- 5G private network integration:Ultra-reliable low-latency connectivity converges with edge-compute eyewear to enable real-time remote expert annotation in mining and oil-field operations.
Industry Challenges
- Optomechanical engineering talent scarcity:Waveguide design and precision assembly expertise concentrates in specialized photonics programs, constraining R&D scaling for mid-tier hardware vendors.
- Multi-regional certification sequencing:Divergent FCC equipment authorization and CE marking timelines fragment product launch roadmaps, delaying revenue recognition across transatlantic deployments.
- Legacy ERP integration complexity:Enterprise customers demand seamless data exchange between AR workflow platforms and incumbent manufacturing execution systems, extending implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Augmented Reality Glasses for B2B Market |
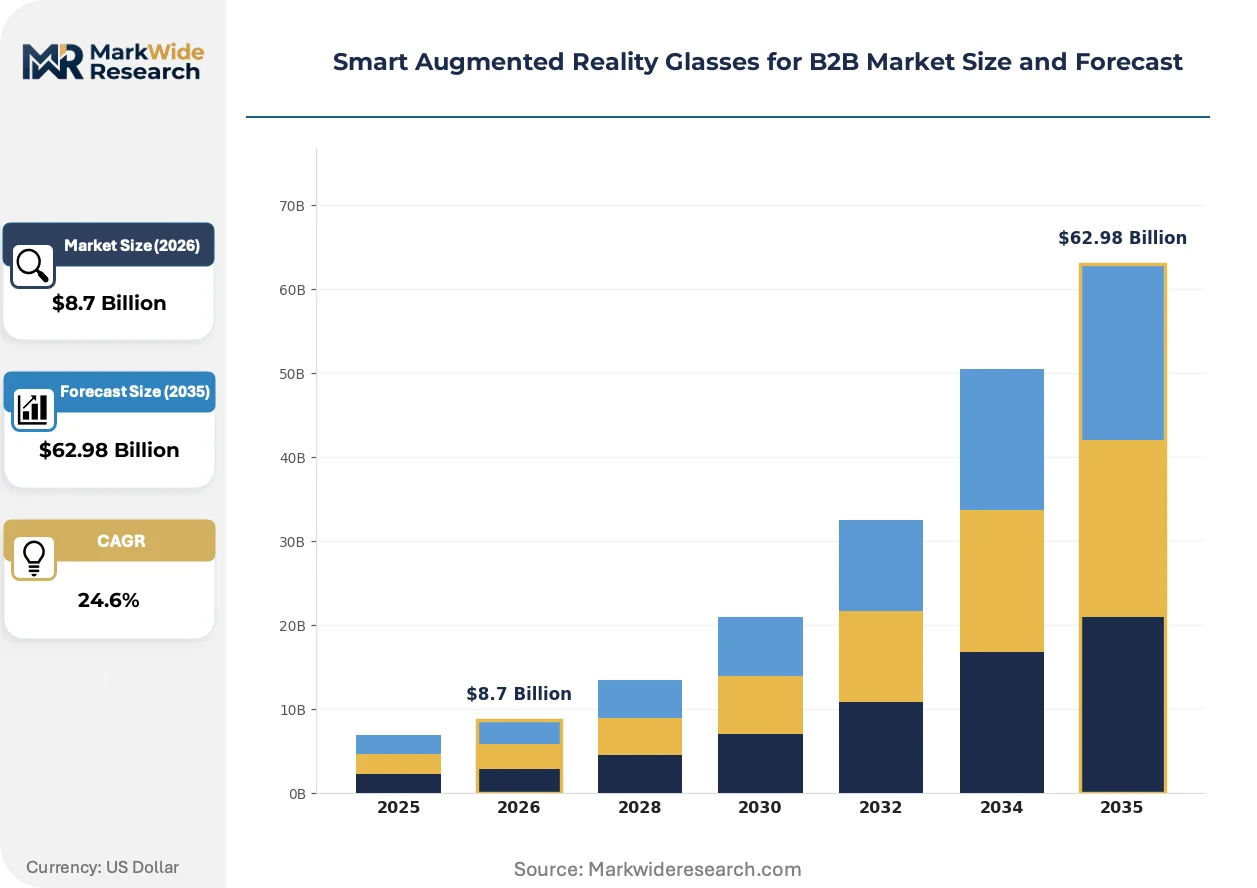
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise Solutions, Industrial Applications, Remote Assistance, Training Tools End User: Manufacturers, Healthcare Providers, Logistics Companies, Retailers Technology: Gesture Recognition, Voice Recognition, Cloud Integration, Spatial Mapping Use Case: Product Design, Maintenance Support, Workflow Optimization, Customer Engagement |
| Companies Covered | RealWear Inc., Vuzix Corporation, XREAL Inc., Microsoft Corporation, Seiko Epson Corporation, Kopin Corporation, Rokid Corporation Ltd., ThirdEye Gen Inc., Lenovo Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Augmented Reality Glasses for B2B Market Trends and Innovations
Optical engine architectures and connectivity protocols are undergoing simultaneous compression, with enterprise buyers prioritizing platforms that unify hardware durability with recurring software attach rates.
Waveguide-based display systems are consolidating technical specifications across industrial AR eyewear. These optical engines project digital overlays through etched glass substrates, eliminating bulky prism optics. Automotive assembly technicians in Bavaria and Baden-Württemberg now specify 40-degree field-of-view minimums as standard procurement language. The technology is consolidating vendor differentiation around brightness efficiency and dust-sealing reliability rather than raw display specifications.
REACH substance restrictions and EU Green Deal energy-efficiency mandates are recalibrating material selection for industrial electronics. RoHS-compliant solder formulations and lower-power optical engines now dominate hardware roadmaps. German automotive OEMs demand documentation of conflict-mineral-free supply chains for AR glass components, compressing supplier qualification timelines for non-compliant vendors.
Platform subscription models are displacing perpetual licensing for AR workflow software. Enterprise procurement teams now prioritize vendors offering predictive maintenance analytics and usage-based pricing tiers. This shift concentrates contract value in consolidated platform relationships rather than fragmented point-product purchases, with Stuttgart-based manufacturing conglomerates leading contract restructuring negotiations.
Smart Augmented Reality Glasses for B2B Market Segmentation
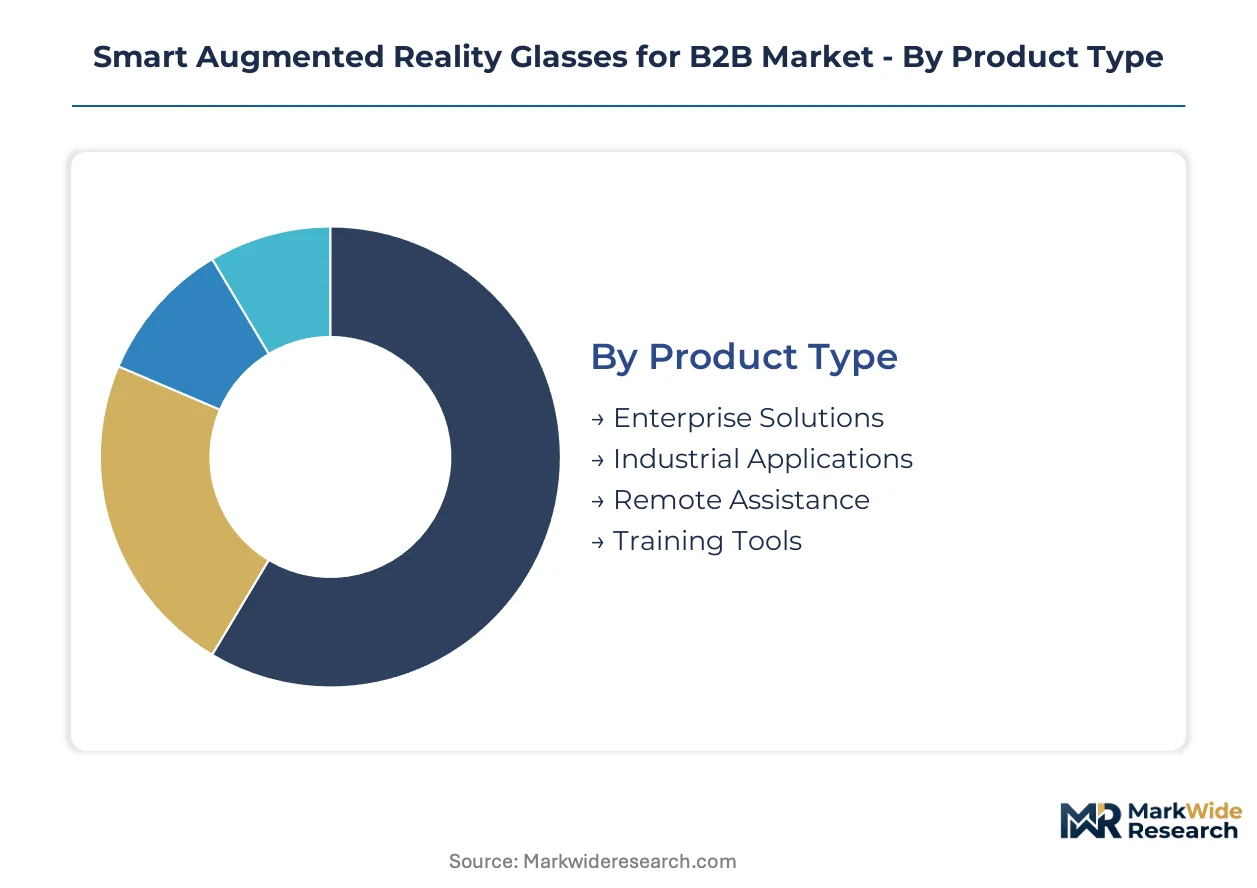
Segmentation in B2B AR eyewear reveals how procurement priorities diverge across industrial workflows. Buyers select hardware-software bundles based on environmental durability requirements and integration complexity with incumbent enterprise systems.
Product Type:
Supply concentration in waveguide optics fabrication favors vendors with captive optical engine production, compressing margins for assembly-only competitors.
- Enterprise Solutions:Consolidated platform contracts bundle hardware, software licenses, and predictive maintenance analytics into multi-year agreements. Stuttgart automotive OEMs now mandate unified procurement to reduce vendor management overhead.
- Remote Assistance:Real-time expert annotation capabilities reduce specialist travel requirements for distributed technical support. Bavarian engineering clusters are normalizing this segment through 5G private network integration in assembly facilities.
- Industrial Applications:Ruggedized hardware with IP67 sealing for dust and moisture exposure.
- Training Tools:Accelerated technician onboarding through immersive procedural guidance.
Enterprise Solutions absorbs the bulk of installed capacity; Remote Assistance is expanding most quickly.
End User:
Cost tier stratification separates premium certified deployments from economy hardware without enterprise software attach rates.
- Manufacturers:Precision assembly floors in Germany's automotive corridors specify torque-guidance overlays and gesture-controlled interfaces for high-noise environments. Procurement teams prioritize optical durability and ERP integration.
- Healthcare Providers:Surgical visualization and clinical training applications face tightened FDA validation requirements. Pre-certified optical architectures gain first-mover advantage in hospital procurement cycles.
- Logistics Companies:Warehouse picking optimization and hands-free inventory verification.
- Retailers:In-store customer service and visual merchandising support.
Manufacturers command the deepest deployment footprints; Healthcare Providers are climbing the fastest as clinical validation pathways mature.
Technology:
Application-specific performance demands dictate interface modality selection for acoustic and environmental constraints.
- Gesture Recognition:Camera arrays and depth sensors enable touchless control in high-noise factory floors where voice commands face interference. Precision assembly technicians in Baden-Württemberg specify this modality for electric powertrain workflows.
- Cloud Integration:Edge-to-cloud data pipelines support predictive maintenance analytics and usage-based pricing tiers. Recurring software attach rates widen vendor margin profiles beyond hardware sales.
- Voice Recognition:Noise-canceling microphone arrays for controlled environment operation.
- Spatial Mapping:LiDAR-based depth sensing for environmental anchoring of digital overlays.
Gesture Recognition dominates precision manufacturing deployments; Cloud Integration is gaining share fastest through subscription revenue expansion.
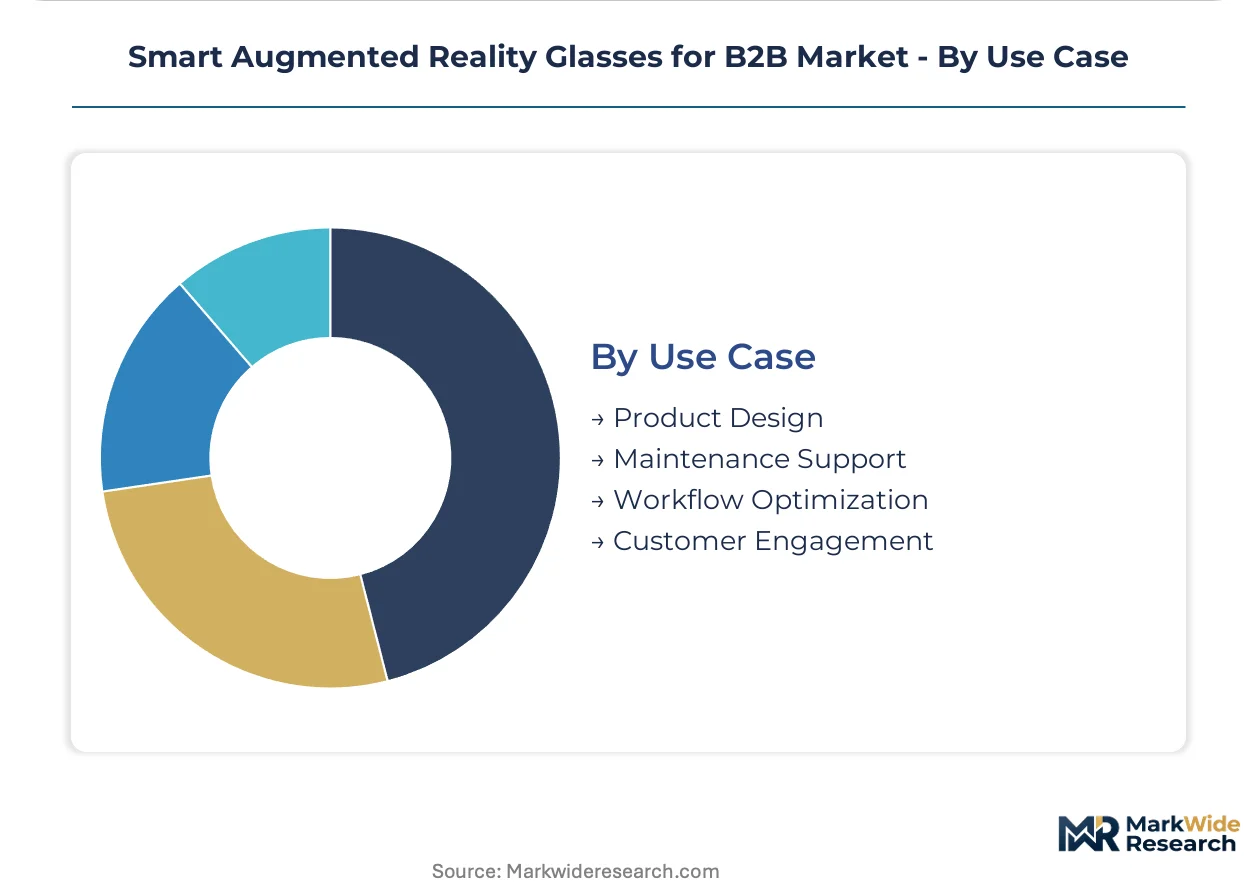
Use Case:
Customer type segmentation separates heavy-asset maintenance workflows from design-phase prototyping applications.
- Maintenance Support:Step-by-step repair guidance with hands-free documentation capture. Field service technicians in oil-field and mining operations specify untethered hardware with extended battery endurance.
- Workflow Optimization:Real-time performance metrics and quality checkpoints overlay production lines. German automotive OEMs integrate these systems with manufacturing execution systems for closed-loop process control.
- Product Design:Collaborative 3D model review and ergonomic prototyping.
- Customer Engagement:Remote product demonstration and technical sales support.
Maintenance Support holds the largest active deployment base; Workflow Optimization is accelerating most rapidly through ERP integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors industrial AR glass procurement through its precision automotive engineering corridors, where torque-guidance workflows normalize enterprise platform contracts.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria specify IP67-sealed waveguide optics for electric powertrain assembly. The EU AI Act mandates auditable data governance for connected eyewear deployed in European industrial settings. Wolfsburg engineering clusters integrate AR-enabled maintenance protocols with manufacturing execution systems.
United States
OSHA workplace safety standards address optical ergonomics for see-through displays near heavy machinery, creating compliance-driven upgrade cycles. FDA oversight tightens clinical validation for healthcare-oriented surgical visualization deployments. Detroit automotive corridors and Houston oil-field operations drive demand for untethered hardware with extended battery endurance.
China
MIIT standards govern radio-frequency emissions from untethered smart glasses in logistics hubs. Shenzhen and Shanghai manufacturing zones concentrate micro-OLED fabrication capacity for optical engines. The country's dual carbon goals recalibrate energy-efficiency mandates for industrial electronics supply chains.
Japan
METI industrial policy supports precision optomechanical engineering programs that concentrate waveguide design expertise. Toyota City and Nagoya manufacturing clusters specify gesture-controlled interfaces for high-noise assembly environments. JIS standards shape durability specifications for ruggedized enterprise deployments.
India
The PLI scheme for electronics manufacturing attracts AR glass final-assembly investment to serve South Asian industrial automation demand. BIS certification requirements structure product qualification timelines for enterprise procurement. Maharashtra and Tamil Nadu automotive corridors pilot hands-free guidance systems for component assembly workflows.
Smart Augmented Reality Glasses for B2B Market Competitive Landscape
Premium-margin players sit above commodity-margin players across optical engine architecture and enterprise software attach rates. The vendor base stratifies between consolidated platform providers and specialized hardware fabricators. Three archetypes dominate: cloud-anchored enterprise platforms, waveguide optics specialists, and voice-controlled monocular designers. Competitive moves concentrate on strategic partnerships for ERP integration and captive optical engine production.
Within the cloud-anchored platform tier, Microsoft Corporation exemplifies enterprise-scale deployment architecture. Vuzix Corporation and RealWear Inc. occupy distinct specialization positions in optical hardware design. These three entities represent the primary competitive anchors across the enterprise solutions and remote assistance segments.
| Leading Market Players |
|---|
| RealWear Inc. |
| Vuzix Corporation |
| XREAL Inc. |
| Microsoft Corporation |
| Seiko Epson Corporation |
| Kopin Corporation |
| Rokid Corporation Ltd. |
| ThirdEye Gen Inc. |
| Lenovo Group Limited |
| Others |
Pricing and Supply Chain Analysis
Waveguide optics maturation is compressing unit economics while concentrating production know-how in East Asian fabrication centers, simultaneously lowering per-unit display costs and tightening vendor margins for assembly-only competitors lacking captive optical engine capacity.
Pricing Analysis
Outcome-linked subscription pricing anchors enterprise AR glass contracts, with Stuttgart automotive OEMs tying fees to technician throughput gains rather than hardware shipment volumes. Price differentiation separates FDA-pre-certified healthcare variants from industrial durability tiers lacking clinical validation documentation. Cost compression in economy hardware runs through Shenzhen assembly houses as micro-OLED oversupply intensifies. Procurement teams in Baden-Württemberg exhibit lowest price sensitivity given ERP integration requirements, while Indian PLI-scheme entrants face acute margin pressure from BIS certification timelines.
Supply Chain Analysis
India's PLI domestic-content mandates are reshaping sourcing patterns for final assembly, pushing contract manufacturers toward Maharashtra and Tamil Nadu production zones. Micro-OLED wafers and high-brightness micro-projectors draw from South Korean and Taiwanese foundry capacity, while waveguide substrates hinge on Japanese and German precision glass suppliers. Single-source vulnerability concentrates in East Asian optical engine fabrication, exposing European and North American OEMs to lead-time volatility. Distribution runs through direct enterprise platform contracts rather than channel intermediaries, with consolidated procurement teams in Wolfsburg and Detroit negotiating multi-year bundled agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical engine fabrication capacity constraints prop pricing power for vendors with captive waveguide production, insulating premium tiers from margin erosion affecting assembly-only competitors.
For Market Incumbents: Anchor defensive positioning through backward integration into waveguide design expertise and captive micro-OLED sourcing from South Korean foundries. LiDAR-based spatial mapping systems threaten niche warehouse applications; counter through deeper ERP integration with Siemens and SAP manufacturing execution systems. Certification investment in FDA surgical visualization pathways creates switching costs against emerging healthcare entrants. For New Entrants and Emerging Players: Cloud-native software platforms offer the lowest-friction entry vector, bypassing capital-intensive optical hardware fabrication. India's PLI-scheme electronics corridors present the most penetrable geography given nascent industrial automation demand and limited incumbent platform entrenchment. Target voice-controlled monocular designs for noisy factory floors where RealWear's dominance remains unchallenged in price-sensitive tiers. For Investors and Strategic Acquirers: Re-rating potential sits with waveguide optics specialists given EU AI Act compliance mandates accelerating upgrade cycles for privacy-architecture-deficient legacy deployments. Long-term viability favors vendors controlling both optical engine production and recurring software attach rates. Monitor 5G private network deployment velocity in mining and oil-field operations as inflection indicator for remote assistance segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Waveguide Production | In-house optical engine fabrication insulates margins from East Asian foundry concentration. |
| FDA Pre-Certification Investment | Clinical validation pathways create first-mover advantage in hospital procurement cycles. |
| ERP Platform Integration | Siemens and SAP manufacturing execution system connectors extend contract durations. |
| 5G Private Network Partnerships | Ultra-reliable low-latency connectivity enables real-time remote expert annotation in mining operations. |
| India PLI Final-Assembly Investment | Domestic-content incentives attract contract manufacturing to serve South Asian industrial demand. |
Research Methodology
Independent corroboration across plant engineers at Stuttgart automotive OEMs, procurement leads at Bavarian manufacturing conglomerates, and optical R&D directors at waveguide specialists underwrites the qualitative findings. Primary interviews with maintenance directors, enterprise IT integration specialists, and aftermarket service heads combined with secondary validation from SEC filings, EU AI Act regulatory texts, and PLI scheme disclosure documents. Bottom-up unit deployment estimates and top-down platform contract value analysis triangulate market sizing.
Comparable-period anchoring to historical enterprise software attach rate trajectories shaped the projection horizon across product type, end user, technology modality, and regional adoption pattern dimensions. CAGRs were derived from segment-specific growth drivers including EU regulatory compliance cycles and 5G infrastructure deployment curves. Forecast inputs incorporated waveguide optics yield improvement trajectories and automotive electric powertrain assembly automation rates.
Inputs from OEM procurement committees and optical component suppliers were available through the study window; gaps in private 5G network deployment timelines introduce uncertainty bands around remote assistance segment velocity. Forecasts reflect documented assumptions regarding ERP integration complexity and regional certification sequencing divergence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality (AR) and Mixed Reality (MR) Market