
 Europe Metaverse Market | 2026-2036
Europe Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metaverse Market Insights
A shift from single-source engine licensing toward multi-source content creation toolchains is rebalancing procurement patterns across European metaverse deployments. Epic Games leverages its Unreal Engine ecosystem to anchor high-fidelity industrial visualization contracts with automotive and aerospace manufacturers. Siemens AG sustains competitive differentiation through its Xcelerator platform, which integrates digital twin capabilities with immersive simulation environments. Microsoft Corporation competes by extending Azure cloud infrastructure across enterprise metaverse workloads, particularly in Nordic manufacturing hubs.
The Europe Metaverse comprises persistent, immersive digital environments rendered through real-time 3D engines, spatial computing hardware, and distributed networking protocols operating at sub-20 millisecond latency thresholds for presence retention. These systems enable synchronous multi-user interaction for commercial training, product design validation, and virtual commerce applications. VR Platforms and AR Platforms currently dominate deployment volumes, though Blockchain-Based Platforms are capturing margin pools in digital asset verification and cross-border virtual goods transactions. Enterprise users represent the fastest-expanding user category, diverging from the gamer-centric installations that defined earlier platform generations.
GDPR and the EU AI Act impose strict data residency and algorithmic transparency obligations on metaverse operators processing biometric or behavioral data within European jurisdictions. EMA and national data protection authorities in Germany, France, and the Netherlands are coordinating enforcement frameworks that condition market access on privacy-by-design architecture. The F-Gas Regulation indirectly shapes hardware deployment through cooling and energy efficiency standards applied to edge data centers powering regional metaverse infrastructure. Stakeholders must monitor evolving CE marking requirements for head-mounted displays and haptic peripherals entering European distribution channels.
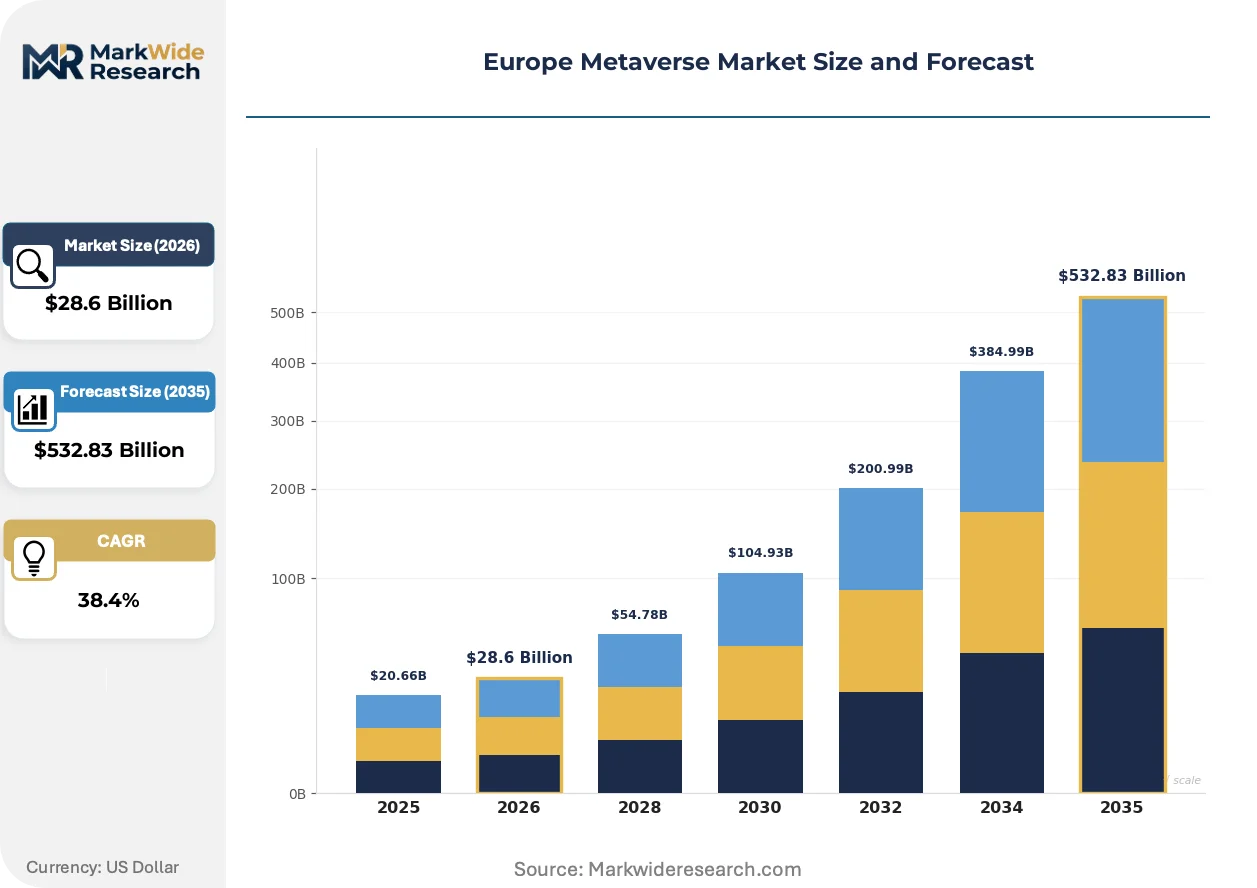
Market Dynamics
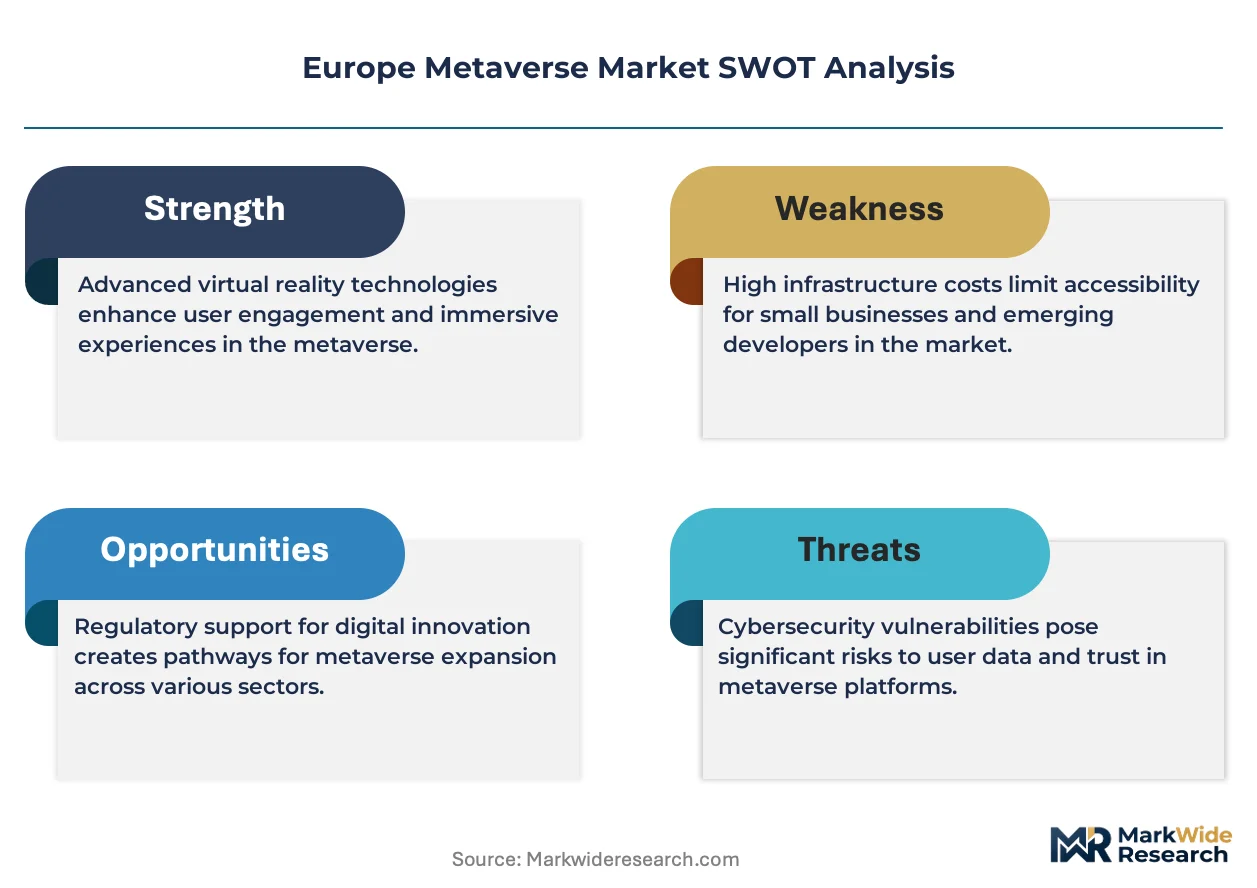
GDPR and the EU AI Act are compressing deployment timelines for metaverse operators while simultaneously creating competitive moats for privacy-by-design architectures. These regulatory frameworks now function as structural gatekeepers that determine which platforms can process biometric behavioral data at scale.
Growth Catalysts
- Industrial Digital Twin Adoption:Aerospace and automotive manufacturers in France deploy metaverse platforms for supply chain visualization, creating pull-through demand for high-fidelity rendering infrastructure.
- GDPR Compliance Investment:Privacy-preserving virtual environments attract enterprise procurement as data residency requirements harden across German and Dutch jurisdictions.
- Enterprise Training Expansion:German corporations accelerate immersive collaboration tool procurement to reduce physical facility dependency for workforce development programs.
Market Restraints
- Edge Infrastructure Cost Concentration:Cooling and energy efficiency standards under the F-Gas Regulation inflate capital requirements for regional data center buildouts powering sub-20 millisecond latency thresholds.
- Biometric Data Processing Friction:EMA coordination with national data protection authorities creates enforcement variance that complicates cross-border platform operations.
- Spatial Computing Hardware Supply Bottleneck:CE marking requirements for head-mounted displays and haptic peripherals extend certification timelines for peripheral manufacturers.
Strategic Opportunities
- Nordic Manufacturing Hub Penetration:Azure cloud infrastructure extension into Scandinavian industrial corridors creates whitespace for enterprise metaverse workload migration.
- Blockchain Asset Verification:Cross-border virtual goods transactions in digital asset verification represent underexploited margin pools for platform operators.
- Multi-Source Content Toolchains:Procurement pattern rebalancing away from single-source engine licensing enables mid-tier visualization vendors to capture industrial contracts.
Industry Challenges
- Real-Time 3D Talent Scarcity:Pipeline engineering and spatial computing development functions face acute shortage across European technology labor markets.
- Legacy System Integration Complexity:Synchronous multi-user environments must interface with existing enterprise resource planning and product lifecycle management architectures.
- Algorithmic Transparency Documentation:EU AI Act mandates require extensive technical documentation that strains platform engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metaverse Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $532.83 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: VR Platforms, AR Platforms, Mixed Reality Platforms, Blockchain-Based Platforms User Type: Gamers, Developers, Enterprises, Educational Institutions Technology: 3D Modeling, Artificial Intelligence, Blockchain, Cloud Computing Application: Entertainment, Social Interaction, Training, E-Commerce |
| Companies Covered | Epic Games, Inc., Roblox Corporation, Meta Platforms, Inc., Dassault Systèmes, Decentraland, Microsoft Corporation, Siemens AG, HTC Corporation, NVIDIA Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metaverse Market Trends and Innovations
European metaverse development is pivoting from consumer entertainment infrastructure toward industrial-grade persistent environments. This reorientation is compressing vendor specialization cycles and elevating regulatory compliance to a product design imperative.
Spatial computing hardware is rewriting presence retention benchmarks for enterprise training applications. Automotive manufacturers in Stuttgart and aerospace clusters in Toulouse adopt sub-20 millisecond latency systems for design validation workflows. This specification threshold is compressing competitive differentiation around network engineering rather than content fidelity alone.
The EU AI Act imposes algorithmic transparency obligations on platforms processing behavioral biometric data within European jurisdictions. Industrial metaverse operators must now document decision logic for immersive environment personalization. German and French aerospace manufacturers delay procurement cycles to verify vendor compliance documentation.
Enterprise buyers now unbundle immersive collaboration tools from bundled software suites. French industrial digital twin deployments increasingly source rendering engines, cloud infrastructure, and haptic peripherals through separate procurement channels. This fragmentation is visible across aerospace supply chain visualization projects where multi-vendor integration contracts replace single-source platform licensing.
Europe Metaverse Market Segmentation
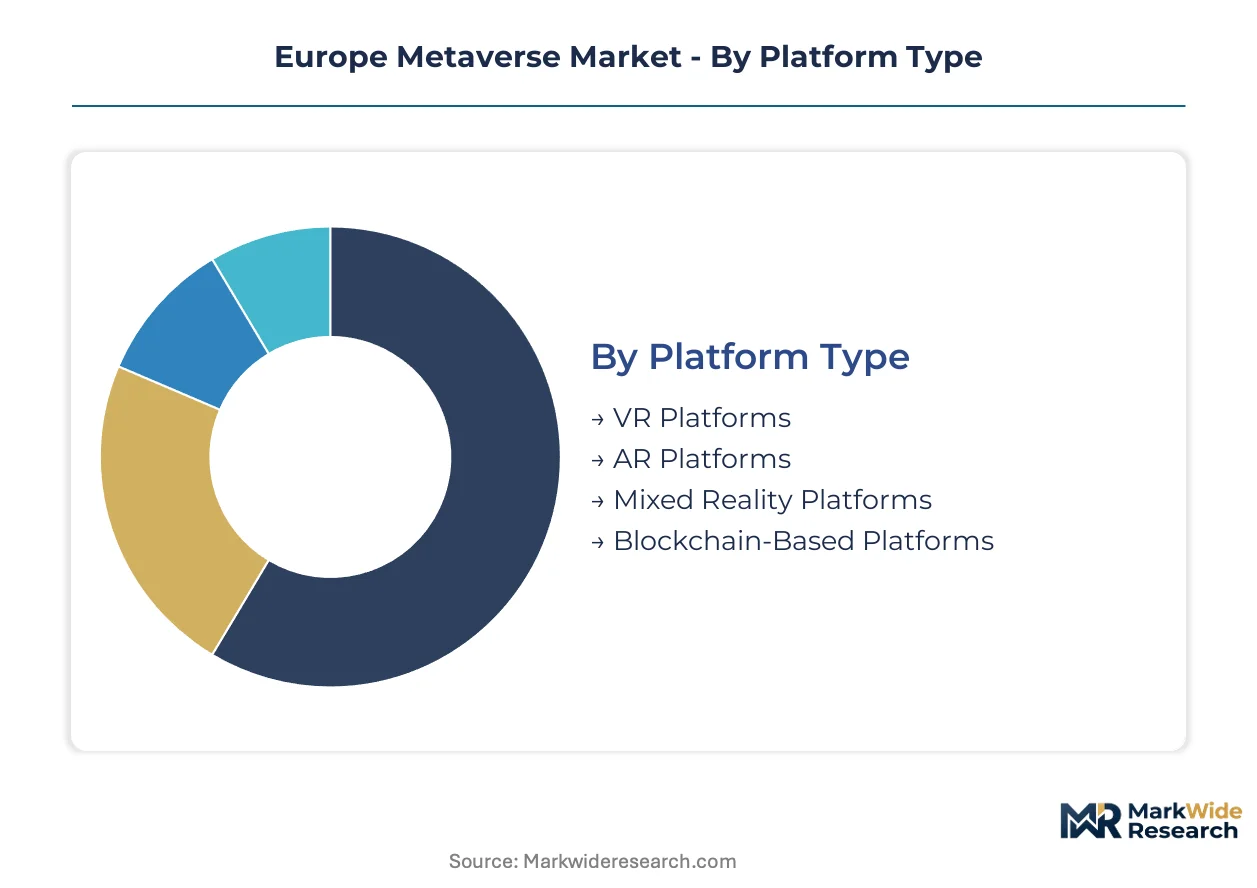
Platform architecture choices determine latency budgets and data residency compliance for European operators. Segmentation reveals where procurement unbundling is creating vendor entry points across industrial versus consumer deployments.
Platform Type:
Volume deployment concentrates in established rendering engines, while premium contracts gravitate toward specialized infrastructure for biometric data processing.
- VR Platforms:Fully immersive head-mounted display ecosystems operating at sub-20 millisecond latency thresholds. German automotive manufacturers in Stuttgart deploy these systems for design validation workflows, though F-Gas Regulation cooling standards inflate regional data center capital requirements.
- AR Platforms:Overlay systems integrating spatial computing with physical manufacturing environments. French aerospace clusters in Toulouse adopt AR visualization for supply chain transparency, pulled by GDPR compliance investment in privacy-preserving architectures.
- Mixed Reality Platforms:Blended environments combining physical and digital presence for enterprise collaboration.
- Blockchain-Based Platforms:Distributed ledger infrastructure enabling digital asset verification and cross-border virtual goods transactions.
Mature deployment sits with VR Platforms. Newer deployment is concentrated in Blockchain-Based Platforms.
User Type:
Procurement authority is shifting from IT departments to operational units with direct P&L responsibility for workforce development.
- Enterprises:Corporate entities deploying immersive environments for training, collaboration, and digital twin visualization. German corporations accelerate procurement to reduce physical facility dependency, creating the steepest expansion trajectory across all user categories.
- Educational Institutions:Universities and vocational training centers adopting spatial computing for technical skills transfer. Dutch technical universities deploy simulation environments for engineering curricula, constrained by algorithmic transparency documentation burdens under EU AI Act.
- Gamers:Consumer entertainment users accessing persistent virtual worlds through personal hardware.
- Developers:Content creators and platform engineers building applications atop metaverse infrastructure.
Revenue concentration favors Enterprises. User volume expansion concentrates in Educational Institutions.
Technology:
Cost tier separation is emerging between commodity cloud infrastructure and specialized spatial computing stacks requiring dedicated talent.
- Artificial Intelligence:Machine learning systems powering environment personalization and behavioral analytics. EMA coordination with French CNIL and German data protection authorities creates enforcement variance that complicates cross-border biometric data processing.
- Cloud Computing:Distributed server infrastructure enabling synchronous multi-user interaction at scale. Nordic manufacturing hubs in Sweden and Denmark migrate workloads to Azure regional instances, attracted by data residency guarantees.
- 3D Modeling:Real-time geometry pipelines for industrial visualization and product design validation.
- Blockchain:Cryptographic verification systems for digital identity and virtual asset provenance.
Margin capture concentrates in Artificial Intelligence. Infrastructure commoditization pressures Cloud Computing.
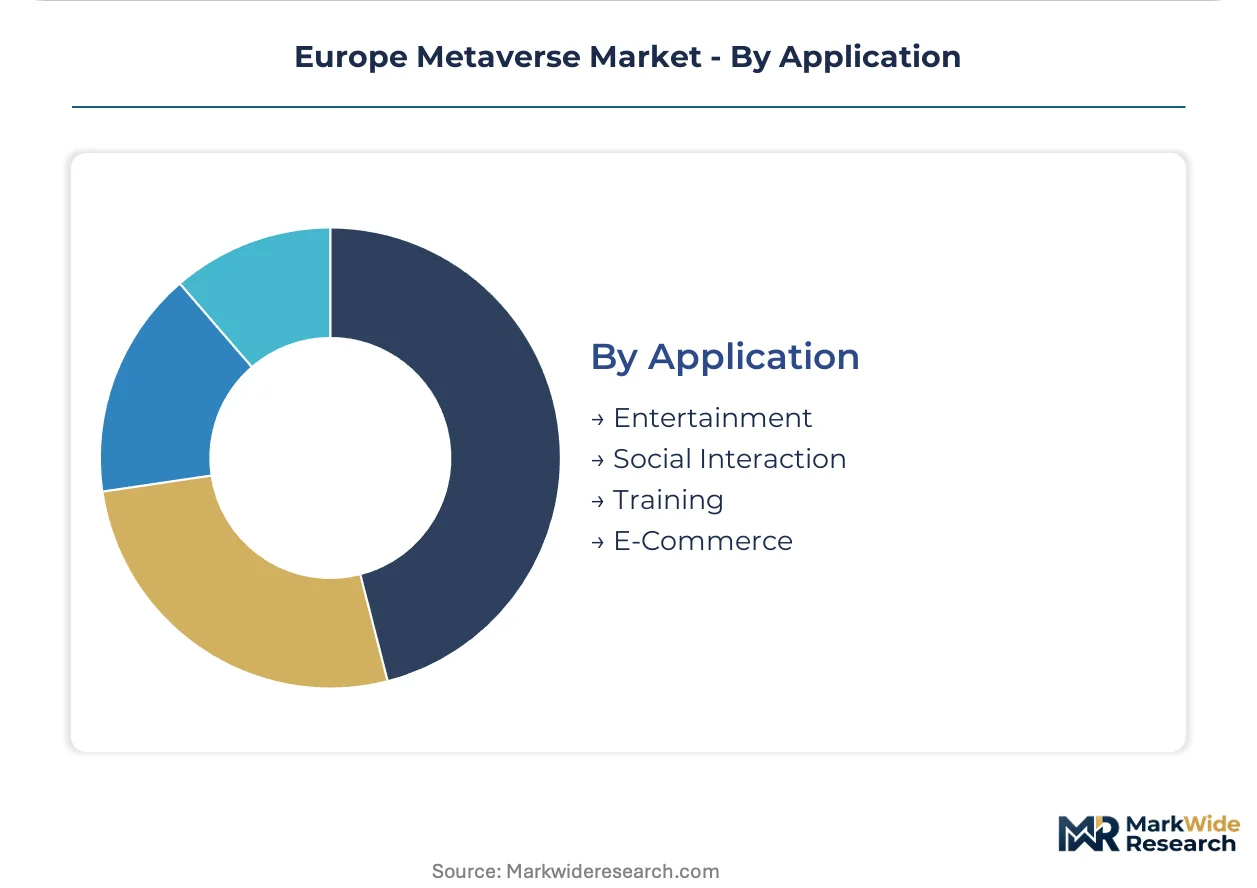
Application:
Geography determines application priority, with industrial corridors favoring training while metropolitan centers retain entertainment concentration.
- Training:Workforce development programs reducing physical facility dependency through immersive simulation. German enterprise procurement accelerates adoption, particularly in automotive and industrial equipment sectors with complex safety protocols.
- E-Commerce:Virtual goods transactions and digital asset marketplaces. Cross-border verification demand in Benelux markets creates margin pool opportunities for privacy-compliant transaction infrastructure.
- Entertainment:Consumer gaming and social experience platforms.
- Social Interaction:Persistent virtual spaces for synchronous communication and community formation.
Procurement maturity sits with Training. Platform innovation concentrates in E-Commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Edge data center buildouts in the Rhine-Ruhr corridor anchor European metaverse infrastructure investment. F-Gas Regulation cooling standards inflate capital requirements across regional facilities. GDPR and EU AI Act compliance frameworks determine which operators can process biometric behavioral data at scale.
Germany
Industrial digital twin demand from Stuttgart automotive manufacturers pulls immersive simulation procurement. The F-Gas Regulation imposes strict cooling and energy efficiency standards on regional edge data centers. Bavarian aerospace clusters deploy sub-20 millisecond latency systems for design validation workflows.
France
Aerospace manufacturers in Toulouse accelerate metaverse platform adoption for supply chain visualization. CNIL coordination with EMA creates enforcement frameworks conditioning market access on privacy-by-design architecture. Île-de-France industrial corridors concentrate procurement authority for enterprise training programs.
Netherlands
Benelux cross-border virtual goods transactions drive demand for blockchain-based asset verification infrastructure. National data protection authorities enforce GDPR data residency requirements on platform operators. Eindhoven technical universities deploy spatial computing environments for engineering curricula.
Sweden
Nordic manufacturing hubs migrate enterprise metaverse workloads to regional cloud instances. Data residency guarantees attract procurement from Scandinavian industrial corridors. Stockholm-based automotive suppliers adopt immersive collaboration tools to reduce physical facility dependency.
United Kingdom
London financial services firms pilot virtual commerce applications for digital asset marketplaces. Post-Brexit regulatory divergence complicates cross-border biometric data processing with EU counterparts. Southeast England technology clusters face real-time 3D talent scarcity in pipeline engineering functions.
Europe Metaverse Market Competitive Landscape
Global majors compete with regional champions across rendering engine licensing and cloud infrastructure provision. The vendor base stratifies between consolidated platform operators and specialized component suppliers. Three archetypes dominate: game engine licensors, industrial software integrators, and cloud infrastructure providers. Competitive moves concentrate on strategic partnerships and geographic expansion rather than vertical integration.
Among game engine specialists, Epic Games, Inc. exemplifies the high-fidelity visualization archetype through its Unreal Engine ecosystem. Siemens AG occupies a position within the industrial software integrator tier, anchoring digital twin capabilities alongside immersive simulation. Microsoft Corporation represents the cloud infrastructure archetype, extending Azure regional instances into Nordic manufacturing corridors.
| Leading Market Players |
|---|
| Epic Games, Inc. |
| Roblox Corporation |
| Meta Platforms, Inc. |
| Dassault Systèmes |
| Decentraland |
| Microsoft Corporation |
| Siemens AG |
| HTC Corporation |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
Neodymium price volatility from Chinese rare earth refineries cascades through European spatial computing hardware supply chains, compressing margins for VR headset manufacturers while inflating premium-tier pricing for industrial-grade haptic peripherals with extended warranty coverage.
Pricing Analysis
Warranty bundling separates enterprise procurement tiers, with German automotive manufacturers demanding 36-month comprehensive coverage against French aerospace buyers accepting limited 12-month terms. SaaS-tiered licensing dominates platform access, though project-based contracting persists for custom digital twin deployments. Price differentiation hinges on GDPR compliance certification tier and latency performance guarantees, with sub-20 millisecond systems commanding substantial premiums. Cost compression in mid-tier cloud infrastructure is intensifying because hyperscaler price competition erodes regional provider margins. Educational institutions exhibit highest price sensitivity, while defense-adjacent aerospace clusters demonstrate lowest.
Supply Chain Analysis
Refurbishment flows for enterprise VR headsets concentrate in Netherlands distribution hubs serving Benelux manufacturing corridors. Component sourcing draws from Taiwan for display panels, China for rare earth magnets, and Germany for precision optics. Supply chain risk centers on single-source vulnerability for spatial computing processors from TSMC's advanced nodes. Distribution runs through direct OEM relationships with automotive and aerospace manufacturers, bypassing traditional IT channel partners for high-value industrial contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European metaverse infrastructure is becoming a vertical-integration race, with platform operators pursuing captive control over edge data center capacity to secure latency performance guarantees and regulatory compliance autonomy.
For Market Incumbents: Anchor market position through backward integration into regional edge infrastructure, securing F-Gas Regulation-compliant cooling systems before capital costs escalate further. Consolidate around privacy-by-design architecture investments to exploit GDPR enforcement variance as a competitive moat against non-compliant challengers. Defensive priority centers on talent retention for real-time 3D pipeline engineering functions facing acute scarcity across German and French technology labor markets. For New Entrants and Emerging Players: Systems integrators represent the most accessible channel partner type for mid-tier visualization vendors seeking industrial contract penetration. White-space opportunity concentrates in Nordic manufacturing hub workload migration, where Azure regional instances have not yet saturated demand. Target educational institution procurement for spatial computing environments, where algorithmic transparency documentation burdens delay incumbent response times. Go-to-market angle should emphasize rapid GDPR compliance certification to accelerate procurement cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized haptic peripheral manufacturers with CE marking expertise in Netherlands and Germany jurisdictions. Long-term viability across the analysis window depends on regulatory compliance automation capabilities rather than content fidelity alone. Acquisition target archetype: mid-tier digital twin visualization vendors with existing aerospace supply chain relationships. Signal to watch: EMA coordination intensity with national data protection authorities as inflection indicator for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unreal Engine ecosystem anchoring with Siemens Xcelerator digital twin infrastructure expands addressable industrial contracts. |
| Geographic Expansion | Azure regional instance deployment into Scandinavian manufacturing corridors captures Nordic data residency requirements. |
| Strategic Partnership | CNIL coordination frameworks with EMA enable privacy-by-design certification pathways for Toulouse aerospace clusters. |
| Acquisition of Specialist Firm | Spatial computing talent scarcity in Stuttgart and Toulouse makes pipeline engineering boutiques attractive targets. |
| Product Launch | Sub-20 millisecond latency systems with F-Gas Regulation-compliant cooling specifications differentiate German automotive offerings. |
Research Methodology
Independent corroboration across platform engineering leads, enterprise IT procurement officers, and spatial computing hardware manufacturers underwrites the qualitative findings. Primary interviews with CTOs at German automotive manufacturers, regulatory affairs specialists at French aerospace clusters, and channel partners in Benelux distribution networks combined with secondary validation from EMA guidance documents, EU AI Act technical standards, hyperscaler capex disclosures, and national data protection authority enforcement frameworks. Bottom-up deployment volume estimates triangulated against top-down infrastructure investment projections.
Rate-of-change decomposition across platform type, user category, technology stack, and application vertical informs the analytical framework. Segmentation dimensions modeled include VR versus AR versus blockchain-based platform architectures, enterprise versus educational versus consumer user types, and training versus e-commerce versus entertainment applications. CAGRs derive from regression analysis of historical infrastructure investment patterns against regulatory compliance cost trajectories. Industry-specific forecast inputs incorporate F-Gas Regulation cooling standard implementation timelines and EMA coordination intensity metrics.
Several conditions sit outside the modeled scope, including post-Brexit UK regulatory divergence effects, Taiwan semiconductor supply disruption scenarios, and consumer entertainment platform pivot decisions. Forecasts reflect documented assumptions about GDPR enforcement uniformity and EU AI Act implementation pace. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market