
 India Desktop Virtualization Market | 2026-2036
India Desktop Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
India Desktop Virtualization Market Foresight
Banking and financial services is expanding as the fastest-growing end-use vertical for desktop virtualization in India, displacing traditional government-led procurement patterns. Microsoft Corporation leverages its Azure Virtual Desktop integration with Office 365 to anchor enterprise accounts across Mumbai and Delhi. Citrix Systems Inc. specializes in high-performance application virtualization for regulated financial workloads. HCL Technologies Limited sustains a dominant systems integration position through its domestic delivery centers and managed desktop services contracts.
India Desktop Virtualization refers to the abstraction of desktop operating systems, applications, and user data from physical endpoint hardware through centralized server-hosted delivery models, typically requiring sub-50 millisecond latency thresholds and GPU acceleration protocols for graphics-intensive workloads. The technology enables secure remote access, centralized patch management, and hardware cost reduction across distributed organizations. Virtual Desktop Infrastructure (VDI) occupies the largest installed base among product types due to legacy enterprise commitments and compliance-driven on-premises retention. Desktop as a Service grows fastest as public cloud providers expand India-region data center capacity and enterprises shift from capital-intensive server farms to operational expenditure models. Hybrid Cloud deployment models capture expanding margin pools by addressing data residency requirements for finance and healthcare while offloading burst workloads to public infrastructure.
MeitY's cloud computing guidelines and the Digital Personal Data Protection Act impose strict data localization and cross-border transfer restrictions that directly shape vendor selection and architecture design for domestic deployments. BIS standards for IT equipment and TRAI's evolving framework for cloud service provider registration add compliance layers that favor established vendors with Indian infrastructure presence. Stakeholders must monitor regulatory divergence between central mandates and state-level procurement rules as sub-national governments develop independent digital workplace strategies.
Market Dynamics
India's Digital Personal Data Protection Act and MeitY's cloud-first mandates are forcing enterprises to rearchitect desktop delivery models around data residency requirements rather than pure cost optimization.
Growth Catalysts
- Financial sector virtualization:RBI guidelines on data localization push banks toward on-premises VDI deployments for trader workstations and customer-facing terminals.
- GPU-accelerated protocols:Graphics-intensive engineering applications in automotive and aerospace design studios now run on centralized virtual desktops with NVIDIA vGPU support.
- Maharashtra-Karnataka cluster density:Mumbai and Bangalore host concentrated IT services delivery centers that generate recurring managed desktop services contracts at scale.
Market Restraints
- Last-mile latency constraints:Sub-50 millisecond thresholds for acceptable user experience exclude Tier-3 and Tier-4 cities from full VDI deployment without edge infrastructure investment.
- Domestic data center capacity gaps:Insufficient India-region GPU cloud instances force enterprises into hybrid architectures that fragment management overhead.
- Windows licensing complexity:Microsoft's per-user subscription models for Azure Virtual Desktop create unpredictable operational expenditure trajectories versus perpetual on-premises licenses.
Strategic Opportunities
- Telangana and Tamil Nadu expansion:Hyderabad and Chennai data center corridors offer lower real estate costs for disaster recovery sites serving financial institutions.
- Healthcare diagnostic imaging:PACS and radiology workstation virtualization opens new vertical demand as hospitals consolidate imaging infrastructure under NABH accreditation pressure.
- PLI scheme alignment:MeitY's production-linked incentives for IT hardware manufacturing reduce endpoint device costs for thin-client deployments in government education programs.
Industry Challenges
- VDI architect scarcity:Specialized skills in Citrix and VMware Horizon profile optimization command premium salaries that inflate project delivery costs.
- Legacy application compatibility:Custom .NET and Java applications built for Windows 7 resist containerization, forcing extended support contracts that block OS migration timelines.
- BIS certification delays:New thin-client hardware models face prolonged testing cycles at Bureau of Indian Standards labs, stretching procurement lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Desktop Virtualization Market |
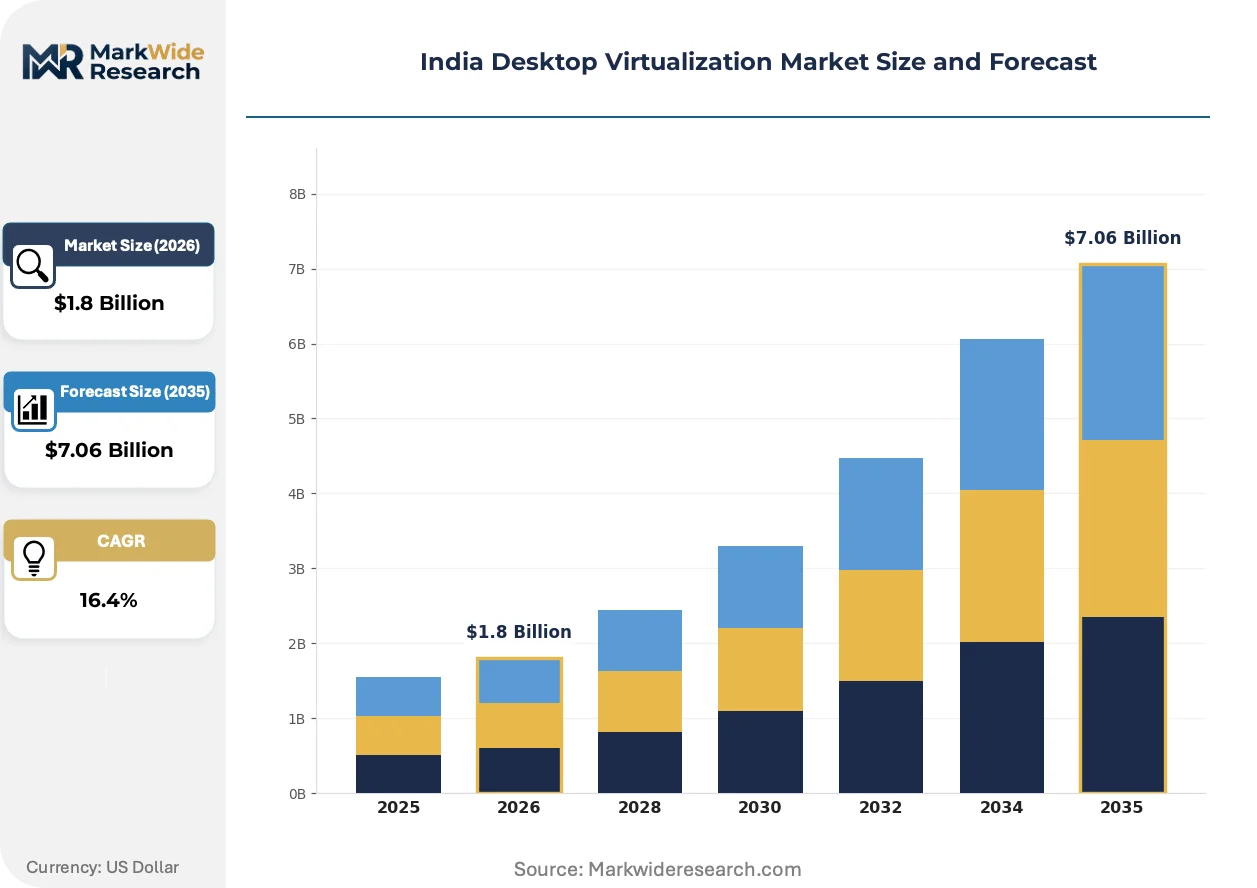
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VDI, Remote Desktop, Application Virtualization, Desktop as a Service End User: Government, Education, Healthcare, Enterprises Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Industry Vertical: Finance, Manufacturing, Retail, Telecommunications |
| Companies Covered | Hewlett-Packard Company, HCL Technologies Limited, Microsoft Corporation, Broadcom Inc. (Symantec Corporation), Huawei Technologies Co. Ltd, Dell Inc., Citrix Systems Inc., Amazon Web Services Inc., Wipro Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Desktop Virtualization Market Shifts & Advancements
Desktop virtualization architectures in India are pivoting from pure on-premises VDI toward GPU-accelerated hybrid models that satisfy data sovereignty while exploiting cloud burst capacity.
GPU virtualization is electrifying high-performance use cases previously considered incompatible with remote delivery. Engineering simulation software and video editing suites now stream from centralized data centers to commodity endpoints. Automotive design centers in Pune and Chennai adopt these configurations to eliminate workstation hardware refresh cycles while protecting intellectual property.
MeitY's cloud computing guidelines and the Digital Personal Data Protection Act impose strict cross-border transfer restrictions that reshape vendor selection criteria. Financial institutions must retain session data within Indian territorial boundaries. This regulatory pressure fragments procurement decisions, with RBI-regulated entities favoring domestic data center operators over multinational cloud providers for primary workloads.
Enterprise buyers now unbundle hardware procurement from desktop management services, treating endpoint devices as consumables while outsourcing entire virtual infrastructure operations. Systems integrators in Mumbai and Bangalore capture recurring revenue through per-seat managed service contracts. This consumption-pattern shift compresses traditional three-year refresh cycles into continuous upgrade programs aligned with software subscription terms.
India Desktop Virtualization Market Segmentation
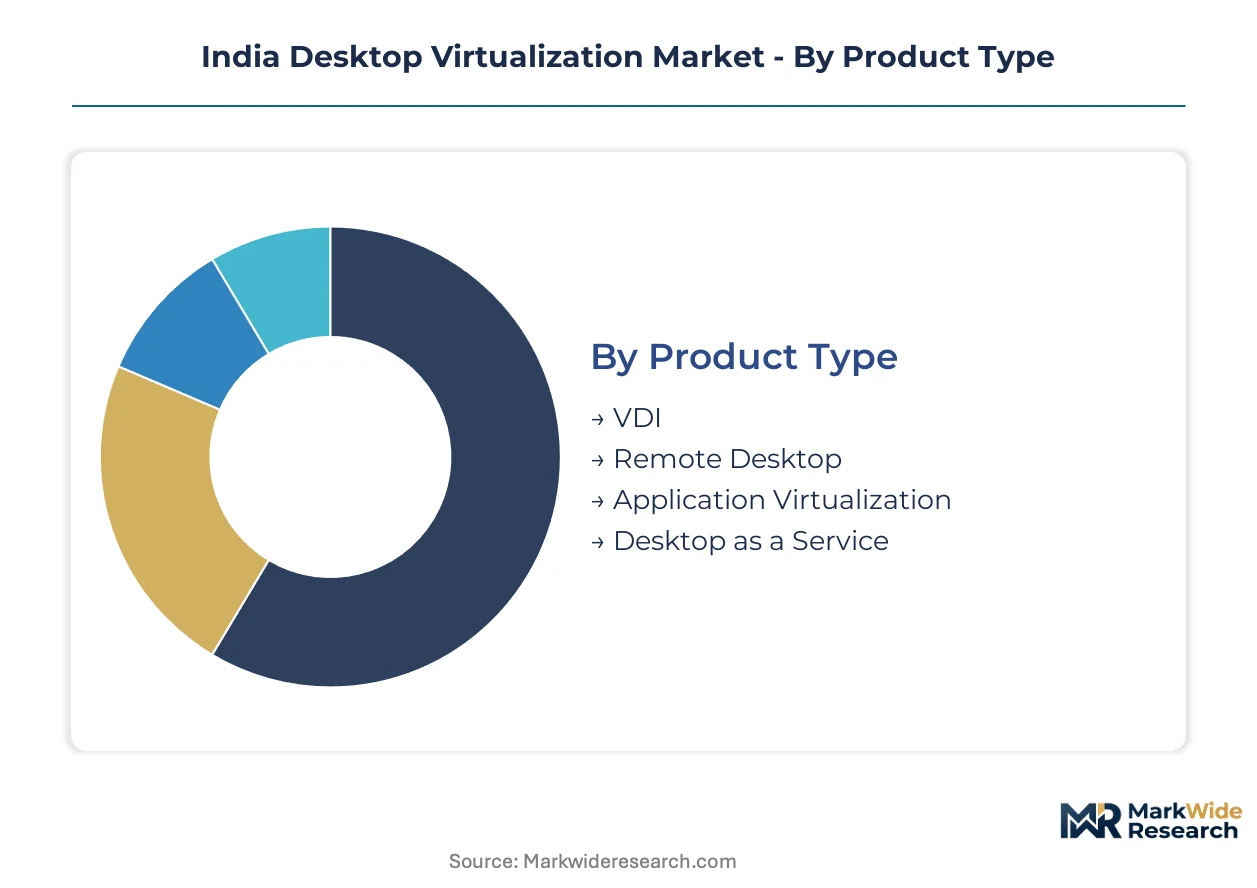
Segmentation in India's desktop virtualization market reflects divergent procurement philosophies across regulated and commercial sectors. Data residency mandates from RBI and MeitY fragment deployment preferences, while GPU acceleration requirements split product architectures between legacy VDI and cloud-native alternatives.
Product Type:
Supply concentration in GPU-enabled infrastructure favors vendors with domestic data center presence.
- VDI:Server-hosted desktop operating systems deliver persistent user environments through hypervisor abstraction. Maharashtra and Karnataka banking clusters drive demand as RBI data localization rules force on-premises retention of trader workstations and customer terminals.
- Desktop as a Service:Cloud-native subscription models eliminate capital expenditure for server farms. Microsoft Azure Virtual Desktop and domestic operators expand India-region capacity to capture enterprise shifts from owned infrastructure.
- Remote Desktop:Session-based protocols stream shared server resources to thin clients.
- Application Virtualization:Containerized delivery isolates legacy software from host operating systems.
VDI absorbs the bulk of installed capacity; Desktop as a Service is expanding most quickly.
End User:
Customer procurement authority concentrates in sectors with regulatory compliance obligations.
- Enterprises:IT services firms and multinational corporations operate distributed delivery centers requiring centralized patch management. Mumbai and Bangalore facilities generate recurring managed desktop contracts at scale.
- Government:Central and state ministries deploy thin-client labs under MeitY cloud-first directives. PLI scheme incentives for domestic hardware manufacturing reduce endpoint costs for education and administrative programs.
- Healthcare:NABH accreditation pressure drives imaging infrastructure consolidation.
- Education:State government digital classroom initiatives standardize on low-maintenance virtual desktops.
Enterprises command the dominant share of current spending; Government procurement is climbing the fastest.
Deployment Model:
Margin pools concentrate in architectures that balance data sovereignty with operational flexibility.
- Hybrid Cloud:Split workloads retain sensitive data on private infrastructure while bursting non-critical operations to public capacity. Financial institutions favor this model to satisfy RBI localization requirements without sacrificing elasticity.
- Private Cloud:Dedicated tenant environments offer single-organization control over security policies and update schedules. Domestic data center operators in Hyderabad and Chennai capture disaster recovery contracts from Mumbai headquarters.
- Public Cloud:Shared multi-tenant infrastructure minimizes per-seat operational expenditure.
- On-Premises:Legacy server farms persist where latency constraints exclude cloud alternatives.
Hybrid Cloud captures the steepest expansion trajectory; On-Premises retains the largest legacy footprint.
Industry Vertical:
Application workload characteristics determine GPU and latency requirements across sectors.
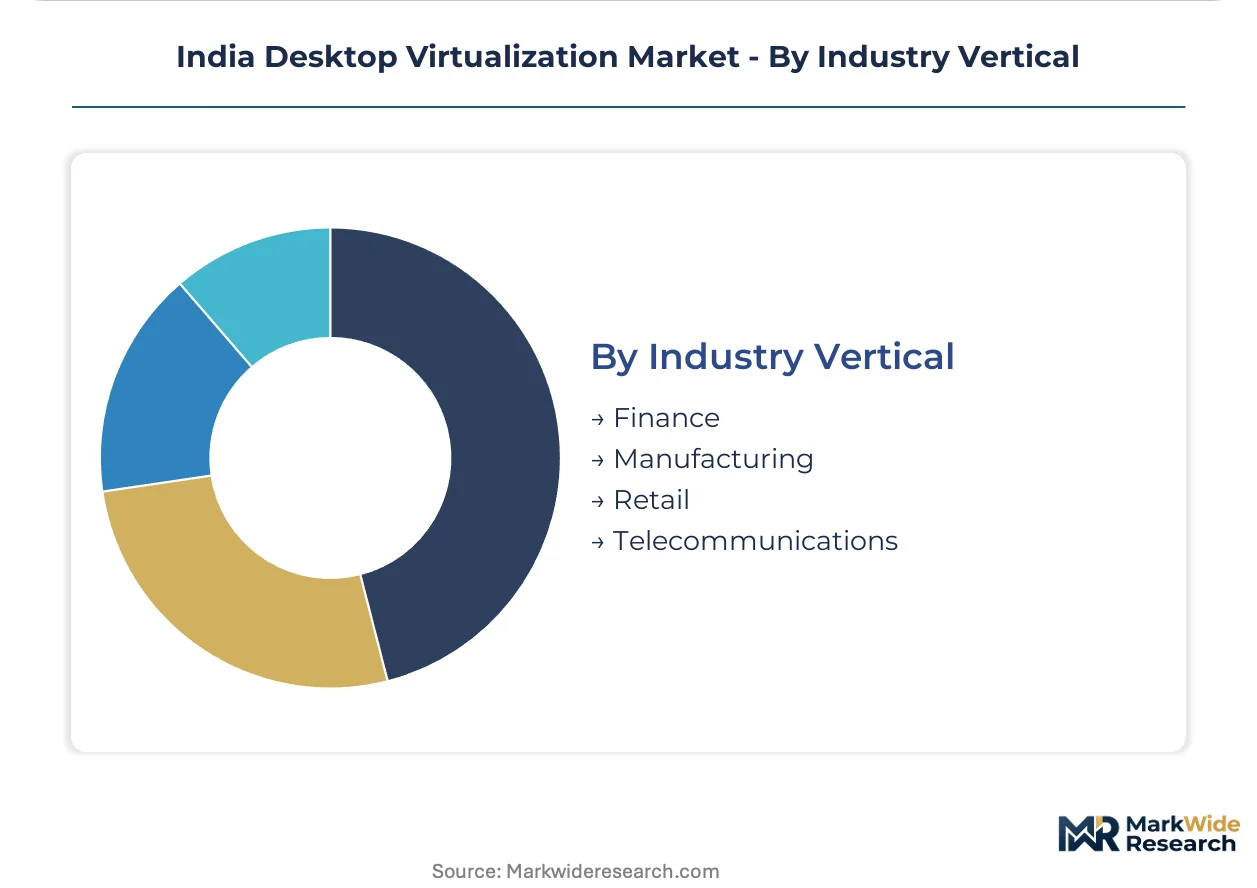
- Finance:Trading floors and branch banking networks demand sub-50 millisecond response times. SEBI and RBI compliance frameworks mandate audit trails and data retention that shape architecture selection.
- Manufacturing:Engineering design centers in Pune and Chennai virtualize CAD and simulation workstations. NVIDIA vGPU support enables centralized delivery of graphics-intensive applications while protecting automotive and aerospace intellectual property.
- Telecommunications:Network operations centers require persistent desktop sessions across shift changes.
- Retail:Distributed point-of-sale terminals benefit from centralized application management.
Finance accounts for the dominant share of current deployment value; Manufacturing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software Technology Parks of India (STPI) zones in Bangalore, Hyderabad, and Pune concentrate desktop virtualization demand through tax incentives and infrastructure support for IT services exporters.
Maharashtra
Mumbai's banking district generates concentrated VDI procurement as RBI data localization rules force on-premises retention of trader workstations. SEBI audit-trail mandates shape architecture selection for broker-dealer networks. The Mumbai-Pune corridor hosts dense clusters of systems integrators delivering managed desktop services to financial institutions.
Karnataka
Bangalore's IT services export sector drives recurring managed desktop contracts at scale. MeitY's cloud-first directives push state government agencies toward thin-client standardization. The Electronics City and Whitefield technology parks concentrate delivery centers requiring centralized patch management across distributed workforces.
Telangana
Hyderabad's data center corridor offers lower real estate costs for disaster recovery sites serving Mumbai financial institutions. The state's startup policy incentives attract SaaS providers building India-region cloud capacity. Financial services firms deploy hybrid architectures here to satisfy RBI localization requirements without sacrificing elasticity.
Tamil Nadu
Chennai's automotive and aerospace engineering centers adopt GPU-accelerated virtual desktops for CAD and simulation workloads. The state's electronics manufacturing policy aligns with PLI scheme incentives for thin-client hardware production. Sriperumbudur and Oragadam industrial belts concentrate design studios virtualizing workstations to protect intellectual property.
Delhi-NCR
Government ministries and public sector undertakings in New Delhi deploy virtual desktops under MeitY's cloud computing guidelines. The region's policy-making concentration shapes national procurement standards that cascade to state implementations. Noida and Gurugram satellite cities host systems integrators serving central government digital workplace programs.
India Desktop Virtualization Market Competitive Landscape
Top-tier vendors anchor enterprise accounts through integrated cloud platforms, while mid-tier specialists capture vertical-specific workloads. The vendor base stratifies across three layers: hyperscale cloud providers with India-region data centers, legacy virtualization specialists with financial services expertise, and domestic systems integrators with managed service capabilities. Dominant competitive moves include public cloud capacity expansion in Mumbai and Chennai availability zones, and strategic partnerships between global software vendors and domestic data center operators to satisfy data residency requirements.
Within the hyperscale tier, Microsoft Corporation and Amazon Web Services Inc. occupy positions defined by India-region infrastructure investment and enterprise subscription models. HCL Technologies Limited exemplifies the domestic systems integrator archetype, leveraging delivery center density for managed desktop services contracts. Citrix Systems Inc. represents the specialized virtualization layer, with positioning shaped by high-performance application delivery capabilities for regulated workloads.
| Leading Market Players |
|---|
| Hewlett-Packard Company |
| HCL Technologies Limited |
| Microsoft Corporation |
| Broadcom Inc. (Symantec Corporation) |
| Huawei Technologies Co. Ltd |
| Dell Inc. |
| Citrix Systems Inc. |
| Amazon Web Services Inc. |
| Wipro Limited |
| Others |
Supply & Pricing Matrix
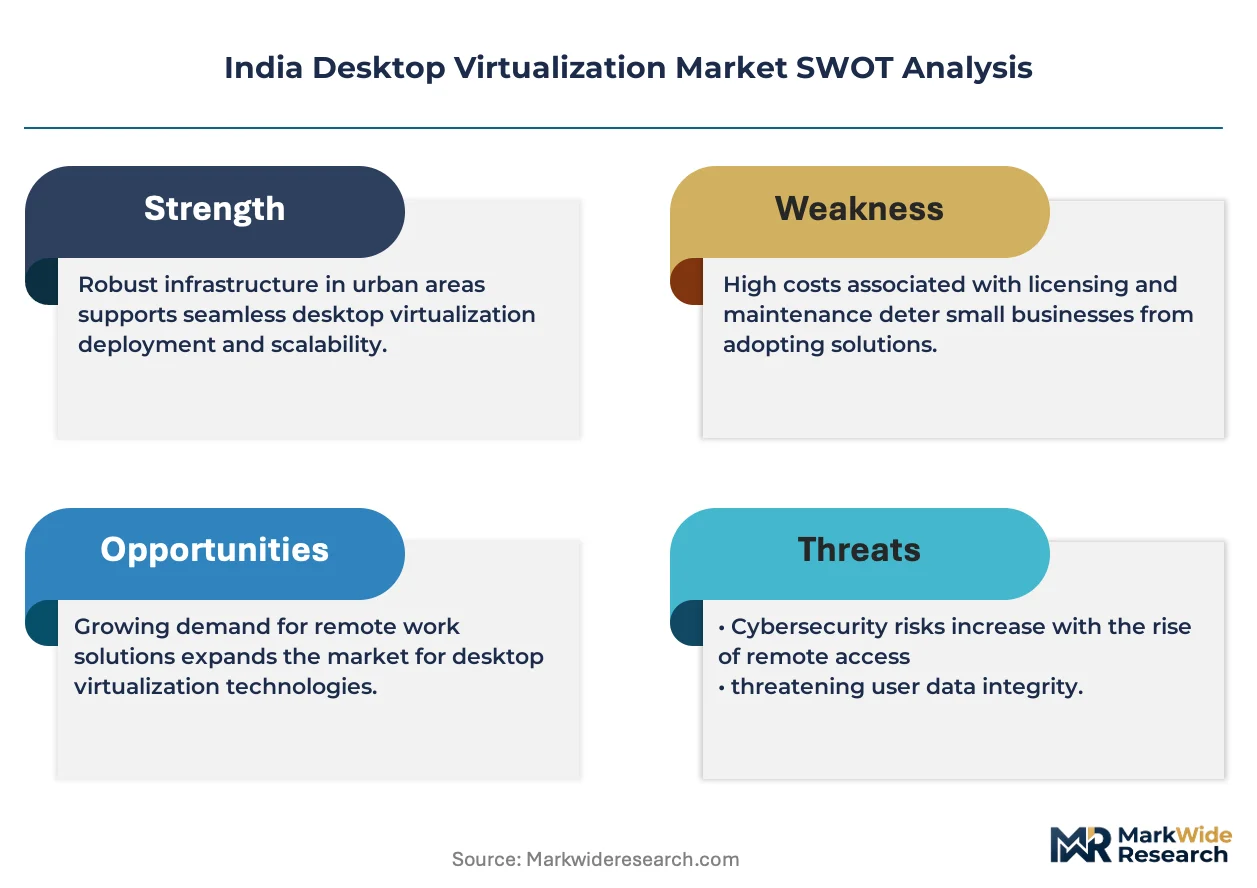
MeitY's cloud-first directives and the Digital Personal Data Protection Act create a dual-gate mechanism that restricts qualified supply to vendors with domestic India-region data center presence while enabling premium-tier pricing for compliant architectures. This regulatory scaffolding compresses the vendor pool and concentrates pricing power among established hyperscale and systems integrator players.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid deployment capability with premium positioning, while spot inventory of certified thin-client hardware commands discounts. The dominant structure operates through subscription-based SaaS tiers for Desktop as a Service, with price differentiation hinging on GPU acceleration levels and BIS certification status. Cost compression in standard VDI tiers is intensifying as domestic operators expand Mumbai and Chennai capacity. Government education buyers exhibit highest price sensitivity due to PLI-scheme budget constraints, whereas RBI-regulated financial institutions accept premium positioning for data residency assurance.
Supply Chain Analysis
BIS certification and MeitY cloud service provider registration function as qualification gates that filter hardware and software vendors before market access. Supply concentrates in China, Taiwan, and South Korea for GPU accelerators and server components, while thin-client assembly localizes under PLI scheme incentives. The chain draws from NVIDIA vGPU licensing, Intel Xeon processor supply, and domestic data center real estate. Single-source vulnerability persists in GPU cloud instance availability within India-region zones. Distribution runs through Mumbai and Bangalore systems integrators delivering managed desktop services contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU cloud capacity scarcity within India-region availability zones props pricing power for vendors with established domestic infrastructure, creating a supply-constrained market structure that favors early movers.
For Market Incumbents: Anticipate margin pressure from domestic operators expanding Hyderabad and Chennai disaster recovery corridors. Defensive positioning requires deepening GPU-enabled infrastructure investments in Maharashtra and Karnataka clusters while securing long-term managed services contracts with IT services exporters. Certification maintenance with BIS and TRAI cloud framework registration preserves competitive moats against multinational entrants lacking local presence. For New Entrants and Emerging Players: Cloud-native channel partnerships with domestic data center operators offer the lowest-friction entry vector. White-space targets concentrate in Tamil Nadu automotive design centers requiring GPU-accelerated CAD virtualization and Telangana healthcare diagnostic imaging consolidation under NABH pressure. A vertical-specific go-to-market anchored in NVIDIA vGPU performance benchmarks bypasses incumbent subscription lock-in. For Investors and Strategic Acquirers: MeitY PLI scheme announcements for domestic thin-client manufacturing is the leading indicator that hardware-software bundling opportunities are materializing. Long-term viability centers on hybrid cloud orchestration capabilities spanning private infrastructure and burst elasticity. Acquisition targets should display Citrix or VMware Horizon certification density with financial services client concentration. The signal to monitor is RBI circulars expanding data localization scope beyond core banking to insurance and securities workloads.| Strategic Initiative | Industry Significance |
|---|---|
| GPU Cloud Capacity Expansion | Domestic availability zone buildout in Mumbai and Chennai captures RBI-regulated financial workloads requiring data residency. |
| Managed Desktop Services Consolidation | Per-seat outsourcing contracts with IT services exporters in Bangalore generate recurring revenue streams at scale. |
| BIS Certification Acceleration | Fast-tracked thin-client hardware testing reduces procurement lead times for government education deployments. |
| Hybrid Cloud Orchestration Platform | Unified management layers spanning private infrastructure and public burst satisfy SEBI audit-trail mandates. |
| Vertical-Specific GPU Benchmarking | Automotive and aerospace design center validation in Pune opens engineering workstation virtualization demand. |
Research Methodology
Independent corroboration across primary interviews with cloud infrastructure architects, VDI deployment specialists, and financial services IT procurement officers, combined with secondary validation through MeitY policy circulars, RBI regulatory filings, and hyperscaler India-region capex disclosures, underwrites the qualitative findings. Bottom-up sizing from individual deployment contracts triangulates against top-down market estimates derived from systems integrator revenue attribution.
Comparable-period anchoring to historical VDI and DaaS adoption curves across the projection horizon shaped the forecast framework. Segmentation dimensions modeled include deployment model, organization size, vertical regulatory intensity, GPU acceleration requirement, and regional data center proximity. CAGRs were derived from slope analysis of subscription revenue trajectories and infrastructure capacity expansion timelines, with inputs from thin-client shipment volumes and managed services contract renewal rates.
The model holds under stable MeitY cloud-first policy enforcement and sustained RBI data localization interpretation; deviation in central-state regulatory divergence or GPU supply chain disruption would shift trajectory assumptions. Forecasts reflect documented assumptions about latency threshold maintenance and BIS certification throughput. A model refresh is warranted upon material change in PLI scheme scope or TRAI cloud service provider registration requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in BFSI Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
Industrial Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market