
 China Metaverse Market | 2026-2036
China Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
China Metaverse Market Insights
GB/T standard certification for virtual reality equipment is rotating market access toward qualified domestic manufacturers. Tencent leverages its gaming ecosystem to anchor content pipelines for immersive environments. Huawei sustains infrastructure dominance through base station and cloud-edge compute investments for low-latency rendering.
The China Metaverse comprises persistent, shared virtual environments built on real-time 3D rendering engines, blockchain-anchored digital identity systems, and haptic feedback hardware operating below 20-millisecond motion-to-photon latency. These systems serve industrial simulation, social commerce, and distributed collaboration. Gaming environments capture the largest revenue pool among platform types, while enterprise solutions command the widest margin expansion as corporations deploy VR training modules. Blockchain-based asset verification sits at the intersection of regulatory scrutiny and developer investment, creating a bifurcated growth trajectory.
MIIT's VR industry development plan, SAMR's digital asset trading guidelines, and the national dual carbon goals collectively shape infrastructure investment priorities and energy consumption standards for data centers powering metaverse workloads. SAMR's evolving stance on cryptocurrency-linked transactions directly constrains blockchain monetization pathways. Stakeholders must monitor regulatory calibration between innovation encouragement and financial stability enforcement.
Market Dynamics
MIIT's VR industry development plan is compressing infrastructure deployment timelines while SAMR's digital asset trading guidelines constrain blockchain monetization pathways, creating a bifurcated investment environment for platform operators.
Growth Catalysts
- GB/T standard certification:Domestic manufacturers gain preferential market access as VR equipment standards rotate toward qualified local producers. This accelerates hardware ecosystem maturation.
- Enterprise training divisions:Industrial simulation demand from manufacturing and energy sectors pulls high-margin VR module deployment. Corporations prioritize safety-critical skill transfer.
- Shenzhen-Hong Kong technology corridor:Guangdong province concentrates R&D talent and component supply chains. Hardware startups cluster within 50 kilometers of core foundry capacity.
Market Restraints
- Motion-to-photon latency threshold:Sub-20 millisecond rendering requirements demand specialized chip architectures. Foundry bottlenecks constrain headset production scaling.
- Dual carbon energy standards:Data center power consumption faces tightening MEE oversight. Rendering workload growth collides with provincial emissions caps.
- Cryptocurrency transaction prohibition:SAMR restrictions on virtual currency settlement block NFT monetization rails. Digital asset verification requires alternative trust architectures.
Strategic Opportunities
- Cloud-edge compute convergence:Huawei's base station investments enable distributed rendering architectures. Latency-sensitive applications migrate from centralized data centers.
- Social commerce integration:Virtual storefronts and immersive product demonstration create new transaction venues. Live-streaming commerce platforms extend into persistent 3D environments.
- Haptic feedback hardware:Glove and suit peripherals remain underdeveloped relative to visual systems. Tactile interface startups capture margin pools abandoned by display-focused incumbents.
Industry Challenges
- Real-time 3D engine talent scarcity:Unreal Engine and Unity specialists command premium compensation. Universities lack curricula aligned to immersive development pipelines.
- Blockchain identity compliance:Digital verification systems must satisfy SAMR know-your-customer mandates without cryptocurrency rails. Legal engineering costs inflate platform development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Metaverse Market |
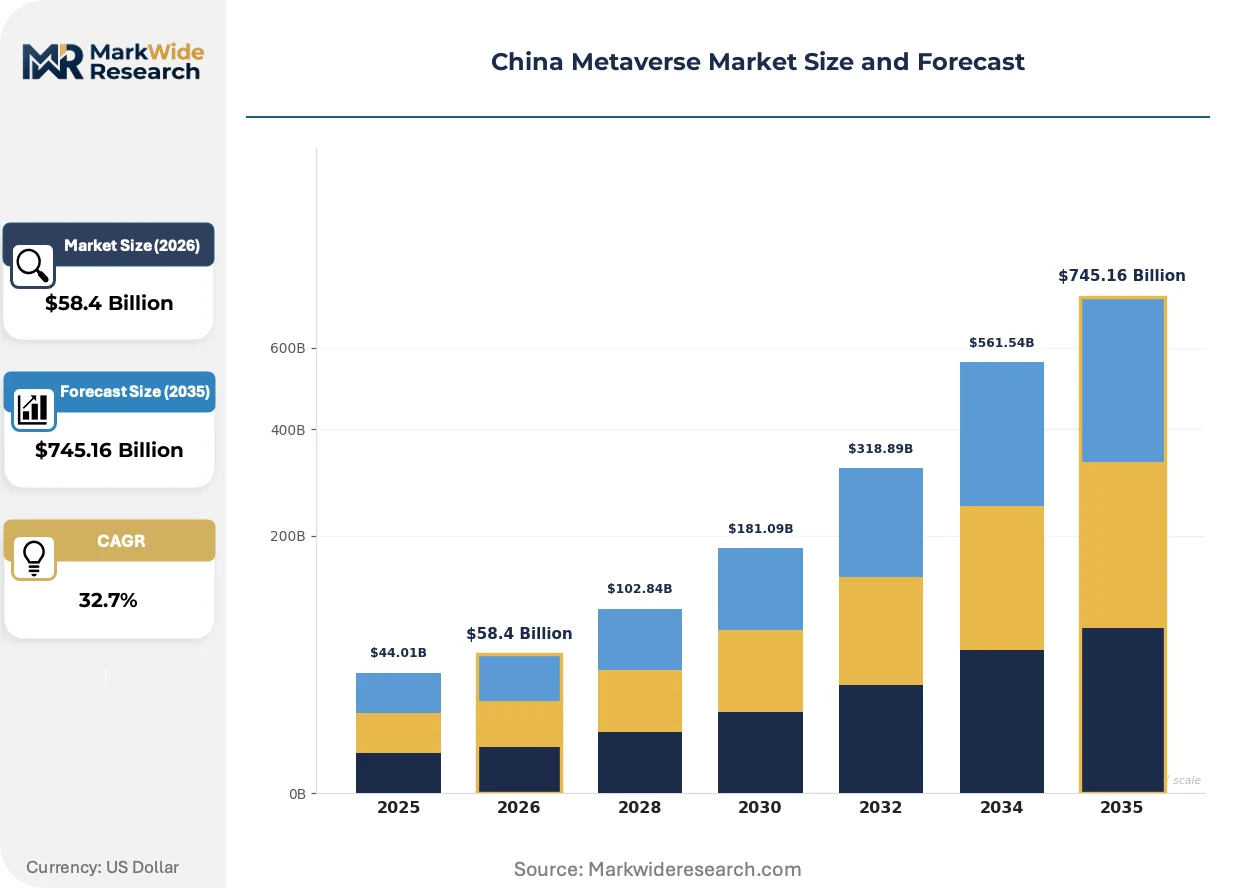
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $745.16 Billion |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Social Platforms, Gaming Environments, Virtual Real Estate, Enterprise Solutions Technology: VR, AR, Blockchain, 3D Modeling Use Case: Gaming, Education, Training, Social Interaction End User: Corporations, Developers, Educators, Consumers |
| Companies Covered | Baidu, ByteDance, Tencent, Lilith Games, MiHoYo, Huawei, NetEase, Xiaomi, Alibaba, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Metaverse Market Trends and Innovations
Rendering architectures and regulatory frameworks are diverging simultaneously, forcing platform operators to place parallel bets on centralized cloud and distributed edge infrastructure while navigating asset monetization constraints.
Spatial computing hardware is fragmenting into specialized form factors. Industrial training divisions adopt tethered headsets with sub-millimeter tracking precision. Consumer gaming segments trial lightweight standalone devices. This bifurcation is fragmenting component supply chains as display and sensor vendors customize SKUs for divergent latency and resolution specifications.
MIIT's VR industry development plan mandates interoperability standards for head-mounted displays. Equipment manufacturers must certify against unified controller and tracking protocols. Shenzhen-based hardware labs accelerate GB/T compliance testing to secure government procurement eligibility.
Enterprise buyers now demand consumption-based pricing for training simulation platforms. Per-seat licenses lose ground to usage-metered contracts tied to module completion rates. State-owned manufacturing conglomerates in Shandong and Jiangsu provinces pilot outcome-linked payment structures for safety certification programs.
China Metaverse Market Segmentation
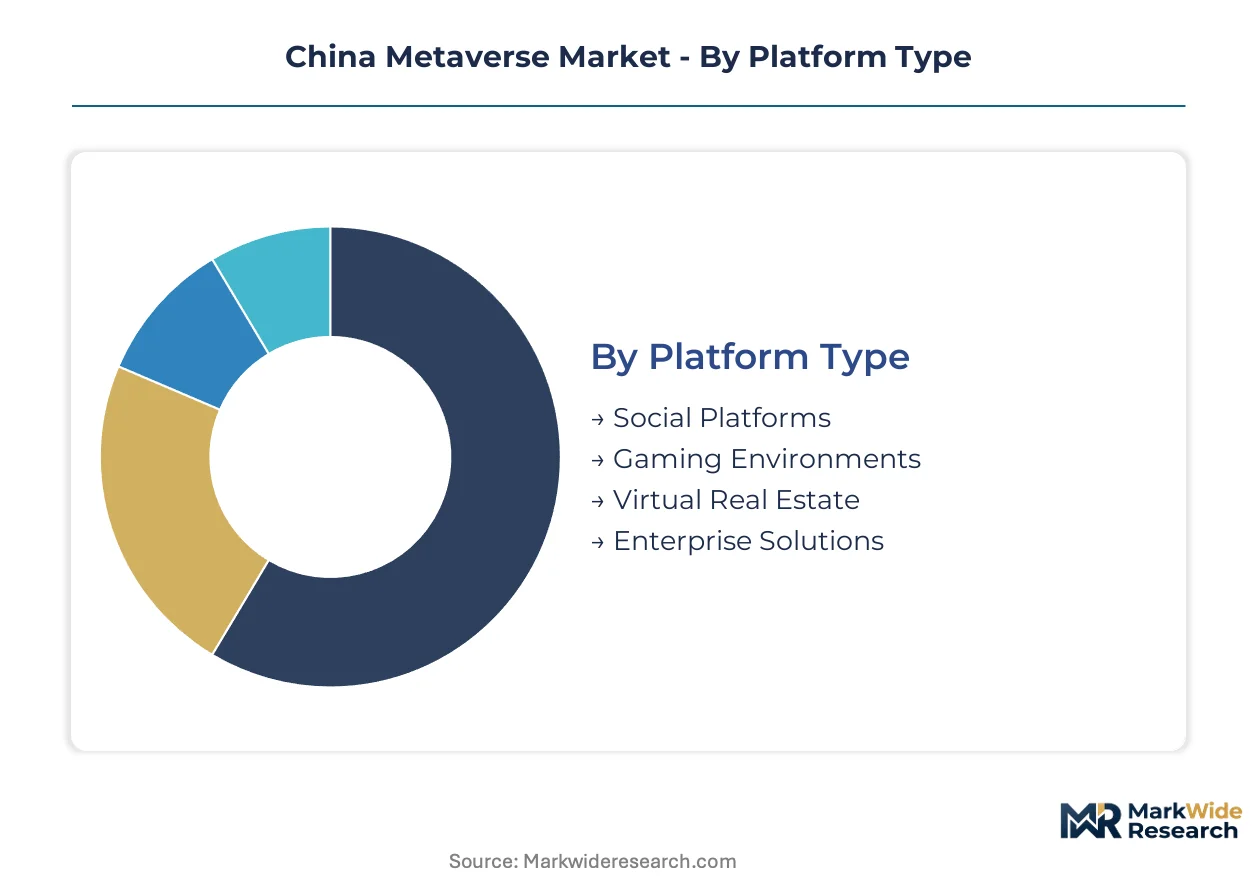
Platform operators in China must navigate MIIT's interoperability mandates and SAMR's asset trading restrictions simultaneously, making segment selection a strategic bet on regulatory endurance. The four segmentation dimensions reveal where compliance costs concentrate and which customer bases absorb premium pricing for certified infrastructure.
Platform Type:
MIIT's GB/T certification requirements for VR equipment create divergent compliance burdens across platform architectures, with persistent environments facing stricter latency verification than transient applications.
- Gaming Environments:Persistent worlds built on real-time 3D engines with sub-20 millisecond motion-to-photon latency requirements. Tencent's content pipelines anchor demand in Guangdong province's Shenzhen-Hong Kong corridor, though cryptocurrency monetization rails remain blocked by SAMR restrictions.
- Enterprise Solutions:Industrial simulation platforms deployed for safety-critical skill transfer in manufacturing and energy sectors. State-owned conglomerates in Shandong and Jiangsu pilot consumption-based pricing tied to module completion rates, commanding the widest margin expansion among platform types.
- Social Platforms:Shared virtual spaces emphasizing real-time avatar interaction and persistent digital identity. Blockchain-anchored verification systems must satisfy SAMR know-your-customer mandates without cryptocurrency settlement.
- Virtual Real Estate:Persistent digital land parcels with blockchain-based ownership records. SAMR's evolving stance on digital asset trading constrains monetization pathways and forces alternative trust architectures.
Gaming Environments handles the majority of throughput; Enterprise Solutions is the fastest mover on share.
Technology:
Cost tiers separate mass-market accessibility from specialized industrial deployment, with foundry bottlenecks and dual carbon energy standards compressing margins at the high-performance end.
- VR:Head-mounted displays requiring sub-20 millisecond rendering latency and specialized chip architectures. Shenzhen-based hardware labs accelerate GB/T compliance testing to secure government procurement eligibility, though foundry capacity constrains headset production scaling.
- Blockchain:Distributed ledger systems for digital identity and asset verification. SAMR restrictions on virtual currency settlement force legal engineering investments to satisfy know-your-customer mandates without cryptocurrency rails.
- AR:Optical see-through displays overlaying digital content on physical environments. Lightweight standalone devices trial in consumer segments while industrial applications demand tethered precision.
- 3D Modeling:Real-time rendering engines powering persistent virtual environments. Unreal Engine and Unity specialists command premium compensation as universities lack aligned curricula.
VR absorbs the largest capital deployment; Blockchain faces the steepest regulatory headwinds.
Use Case:
Application maturity determines where standardized procurement frameworks already exist versus where buyers experiment with outcome-linked contracts.
- Training:VR modules for safety-critical skill transfer in manufacturing, energy, and heavy industry. Per-seat licenses lose ground to usage-metered contracts as state-owned enterprises pilot outcome-linked payment structures.
- Gaming:Immersive entertainment environments capturing the largest revenue pool among use cases. Content pipelines leverage existing gaming ecosystems while navigating cryptocurrency monetization prohibitions.
- Education:Virtual classrooms and simulated laboratory environments for K-12 and vocational instruction. Procurement concentrates in provincial pilot programs with MIIT-aligned interoperability standards.
- Social Interaction:Persistent virtual spaces for distributed collaboration and digital community formation. Live-streaming commerce platforms extend into 3D environments, creating new transaction venues.
Training commands the highest per-deployment value; Social Interaction is expanding most quickly as commerce platforms migrate.
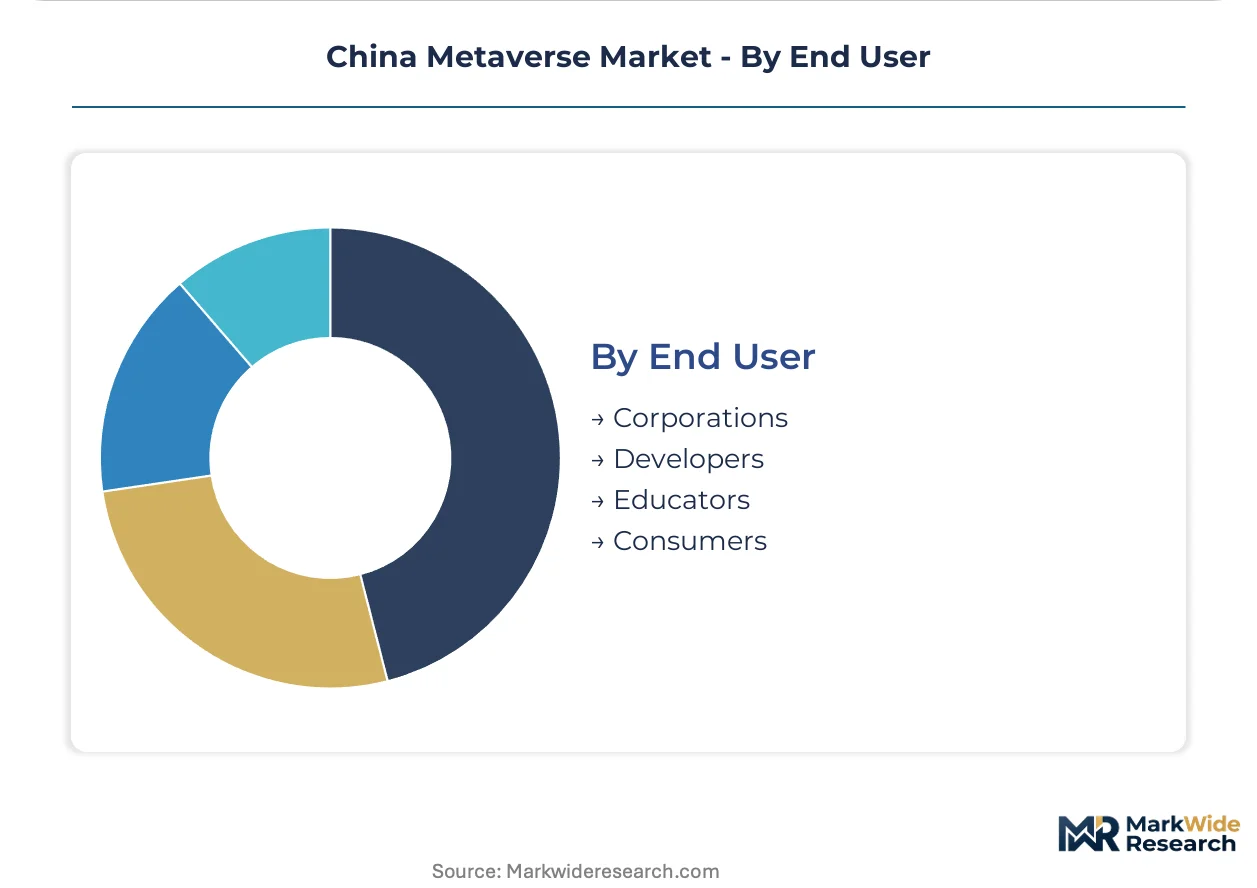
End User:
Customer type determines pricing power, with state-backed buyers extracting volume discounts and individual consumers facing premium hardware costs.
- Corporations:Manufacturing and energy sector buyers deploying industrial simulation at scale. Shandong and Jiangsu state-owned conglomerates negotiate consumption-based contracts tied to safety certification outcomes.
- Developers:Content creators and platform builders requiring 3D engine expertise and blockchain compliance architecture. Talent scarcity inflates development budgets as universities lag curriculum alignment.
- Educators:Provincial education bureaus and vocational institutions piloting VR classroom infrastructure. Procurement eligibility requires GB/T-certified hardware from qualified domestic manufacturers.
- Consumers:Individual purchasers of standalone headsets and gaming content. Price sensitivity segments demand toward lightweight devices despite inferior latency specifications.
Corporations drive the largest contract values; Developers face the steepest input cost inflation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-owned manufacturing conglomerates and gaming studios concentrate procurement power in eastern coastal provinces, while western regions pilot rural digital infrastructure programs. MIIT's VR industry development plan directs investment toward technology corridors with existing semiconductor foundry access. Provincial emissions caps under dual carbon goals reshape data center placement decisions.
Guangdong Province
Gaming studios and hardware manufacturers drive demand in the Shenzhen-Hong Kong technology corridor. MIIT's GB/T certification requirements accelerate compliance testing at Shenzhen-based hardware labs. Shenzhen anchors component supply chains within 50 kilometers of core foundry capacity.
Jiangsu Province
State-owned manufacturing conglomerates pilot consumption-based contracts for VR training modules. SAMR's digital asset trading guidelines constrain blockchain monetization pathways for platform operators. Nanjing and Suzhou industrial parks concentrate enterprise simulation deployment.
Shandong Province
Energy sector buyers deploy safety-critical VR training for heavy industry certification programs. Dual carbon energy standards tighten MEE oversight of rendering workload data centers. Qingdao and Yantai host pilot outcome-linked payment structures for industrial simulation.
Beijing-Tianjin-Hebei
Cloud-edge compute investments from infrastructure providers enable distributed rendering architectures. The national capital's regulatory clarity attracts blockchain compliance engineering talent. Zhongguancun technology cluster anchors 3D engine development pipelines.
Sichuan-Chongqing
Western China pilot programs extend rural digital infrastructure for immersive education applications. Provincial emissions caps favor hydroelectric-powered data centers for latency-sensitive rendering. Chengdu's gaming development studios feed content pipelines for persistent virtual environments.
China Metaverse Market Competitive Landscape
Player mix skews toward integrated technology conglomerates with existing gaming ecosystems and infrastructure hardware divisions. Market structure concentrates around three archetypes: cloud infrastructure providers with edge compute investments, gaming studios leveraging content pipelines for immersive environments, and hardware manufacturers certifying against GB/T interoperability standards. Competitive moves center on strategic partnerships between content creators and infrastructure operators, plus portfolio diversification into haptic feedback peripherals.
Within the infrastructure-provider tier, Huawei exemplifies edge compute convergence through base station investments. Among gaming-centric conglomerates, Tencent and NetEase occupy positions leveraging existing content ecosystems. ByteDance represents the social platform archetype extending live-streaming commerce into persistent 3D environments.
| Leading Market Players |
|---|
| Baidu |
| ByteDance |
| Tencent |
| Lilith Games |
| MiHoYo |
| Huawei |
| NetEase |
| Xiaomi |
| Alibaba |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day component lead times for specialized VR chipsets concentrate pricing power with Shenzhen-based foundry-adjacent assemblers while compressing margins for inland distributors lacking direct fab relationships. GB/T certification eligibility rotates procurement decisions toward qualified domestic manufacturers with verified MIIT interoperability lab access.
Pricing Analysis
Cost-plus contracts with quarterly silicon wafer indexation dominate enterprise training module procurement, with foundry spot prices feeding directly into headset assembly quotes. Pricing stratifies across GB/T-certified premium tiers, SAMR-compliant standard tiers, and uncertified economy tiers lacking government procurement eligibility. Cost compression in the economy tier intensifies because Shenzhen-Hong Kong corridor manufacturers absorb volume discounts unavailable to inland competitors. State-owned manufacturing conglomerates in Shandong and Jiangsu exhibit lowest price sensitivity due to outcome-linked safety certification budgets; individual consumers demonstrate highest sensitivity, deferring purchases until lightweight standalone devices reach mass-market price bands.
Supply Chain Analysis
Inbound logistics costs through Shenzhen port congestion and Yangtze River Delta container bottlenecks inflate landed component costs for inland assembly facilities. Supply concentrates in Taiwan for advanced display panels, South Korea for memory modules, and domestic China for final headset integration and GB/T compliance testing. The chain rests on gallium nitride power semiconductors, micro-OLED displays, and precision inertial measurement units. Single-source vulnerability in Taiwan-sourced high-refresh-rate panels exposes assemblers to geopolitical disruption. Distribution runs through MIIT-certified equipment distributors to provincial education bureaus and state-owned enterprise procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China Metaverse Market represents a platform-economics inflection where MIIT's interoperability mandates and SAMR's asset trading restrictions are simultaneously compressing monetization pathways and consolidating infrastructure control around ecosystem-integrated incumbents.
For Market Incumbents: Compound cloud-edge compute investments with haptic feedback peripheral acquisitions to capture margin pools abandoned by display-focused competitors. Defend against ByteDance's live-streaming commerce extension into persistent 3D environments by anchoring enterprise training relationships through consumption-based outcome contracts. Prioritize GB/T certification maintenance as MIIT procurement eligibility tightens.
For New Entrants and Emerging Players: Lead with tactile interface hardware development targeting the underdeveloped glove and suit peripheral segment where incumbents lack specialized focus. Target western China rural education pilot programs in Sichuan-Chongqing as the most penetrable geography with hydroelectric-powered data center cost advantages and less saturated vendor competition. Deploy direct provincial education bureau sales channels bypassing distributor markups.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated technology conglomerates spinning non-core haptic hardware divisions or blockchain compliance engineering units. Long-term viability hinges on regulatory endurance between innovation encouragement and financial stability enforcement. Watch SAMR's evolving stance on alternative trust architectures for digital asset verification as the inflection signal distinguishing viable monetization pathways from stranded blockchain investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Huawei's base station investments enable distributed rendering architectures migrating latency-sensitive applications from centralized data centers. |
| GB/T Certification Investment | Shenzhen-based hardware labs accelerate compliance testing to secure government procurement eligibility under MIIT interoperability mandates. |
| Haptic Peripheral Development | Glove and suit specialists capture margin pools abandoned by display-focused incumbents in industrial training deployments. |
| Consumption-Based Contracting | Shandong and Jiangsu state-owned conglomerates pilot outcome-linked payment structures tying VR module pricing to safety certification completion rates. |
| Cloud-Edge Compute Convergence | Beijing-Tianjin-Hebei infrastructure providers enable latency-sensitive rendering migration from centralized data centers toward distributed edge architectures. |
Research Methodology
A spread of perspectives from VR hardware procurement managers at state-owned enterprises, MIIT certification lab directors, gaming studio technical leads, cloud infrastructure platform engineers, and provincial education bureau technology officers converged on the working assumptions underlying demand projections. Primary interview insights combined with secondary validation from MIIT policy documents, SAMR regulatory filings, hyperscaler capex disclosures, and provincial pilot program procurement records. Bottom-up headset shipment estimates and top-down enterprise training budget allocations were triangulated against foundry capacity constraints and dual carbon energy standard compliance costs.
Segmentation dimensions modeled include platform type, underlying technology stack, application use case, and end-user organizational category across the analysis window. CAGRs were derived from weighted scenario analysis incorporating infrastructure deployment timelines, regulatory endurance assumptions, and technology adoption S-curves. Forecast inputs incorporated MIIT VR industry development plan milestone schedules, SAMR digital asset trading guideline evolution trajectories, and provincial emissions cap trajectories affecting data center placement economics.
Forecasts assume regulatory continuity in MIIT's interoperability mandates and SAMR's cryptocurrency transaction prohibitions; material policy shifts would require re-modeling monetization pathway viability and infrastructure investment returns. Technology adoption assumptions reflect current headset latency specifications and foundry capacity expansion plans. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Industrial Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market