
 Augmented Reality and Virtual Reality in Manufacturing Market | 2026-2036
Augmented Reality and Virtual Reality in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality and Virtual Reality in Manufacturing Market Intelligence
Aftermarket service revenue is tilting toward immersive remote-assistance platforms as manufacturers seek to reduce field technician dispatch costs. Meta leverages its Quest enterprise ecosystem to anchor industrial training deployments across North American automotive plants. Varjo differentiates through photorealistic mixed-reality headsets that sustain premium positioning in aerospace simulation contracts. Unity Technologies competes by extending its real-time 3D engine into factory-floor digital twin environments.
Augmented Reality and Virtual Reality in Manufacturing denotes the integration of spatial computing headsets, sensor arrays, and real-time rendering software to overlay digital information onto physical production environments or simulate entire operational workflows in fully immersive virtual spaces. These systems typically operate at sub-20-millisecond motion-to-photon latency to prevent operator disorientation during precision assembly tasks, with industrial-grade smart glasses achieving IP67 dust and liquid ingress protection for foundry and cleanroom deployment. The primary commercial purpose centers on reducing human error rates, compressing workforce onboarding cycles, and enabling predictive maintenance visualization without halting production lines. Training applications currently absorb the largest share of deployed headsets as manufacturers replace physical mock-ups with repeatable virtual scenarios, while Quality Assurance segments are gaining traction fastest where AR-guided inspection protocols replace paper-based checklists in regulated industries. Head-Mounted Displays dominate device type revenue due to enterprise procurement volumes, though Smart Glasses occupy the highest-margin tier for hands-free assembly guidance in electronics and heavy machinery sectors.
FDA oversight of software-as-a-medical-device intersects with VR surgical training tools, while OSHA workplace safety standards govern AR headset use in environments with moving machinery and chemical exposure risks. The FCC regulates wireless spectrum allocation for low-latency factory-floor AR streaming, creating compliance thresholds that shape hardware certification timelines for industrial deployments. Stakeholders must monitor how evolving AI governance frameworks redefine liability boundaries when autonomous AR guidance systems direct human operators in safety-critical manufacturing steps.
Market Dynamics
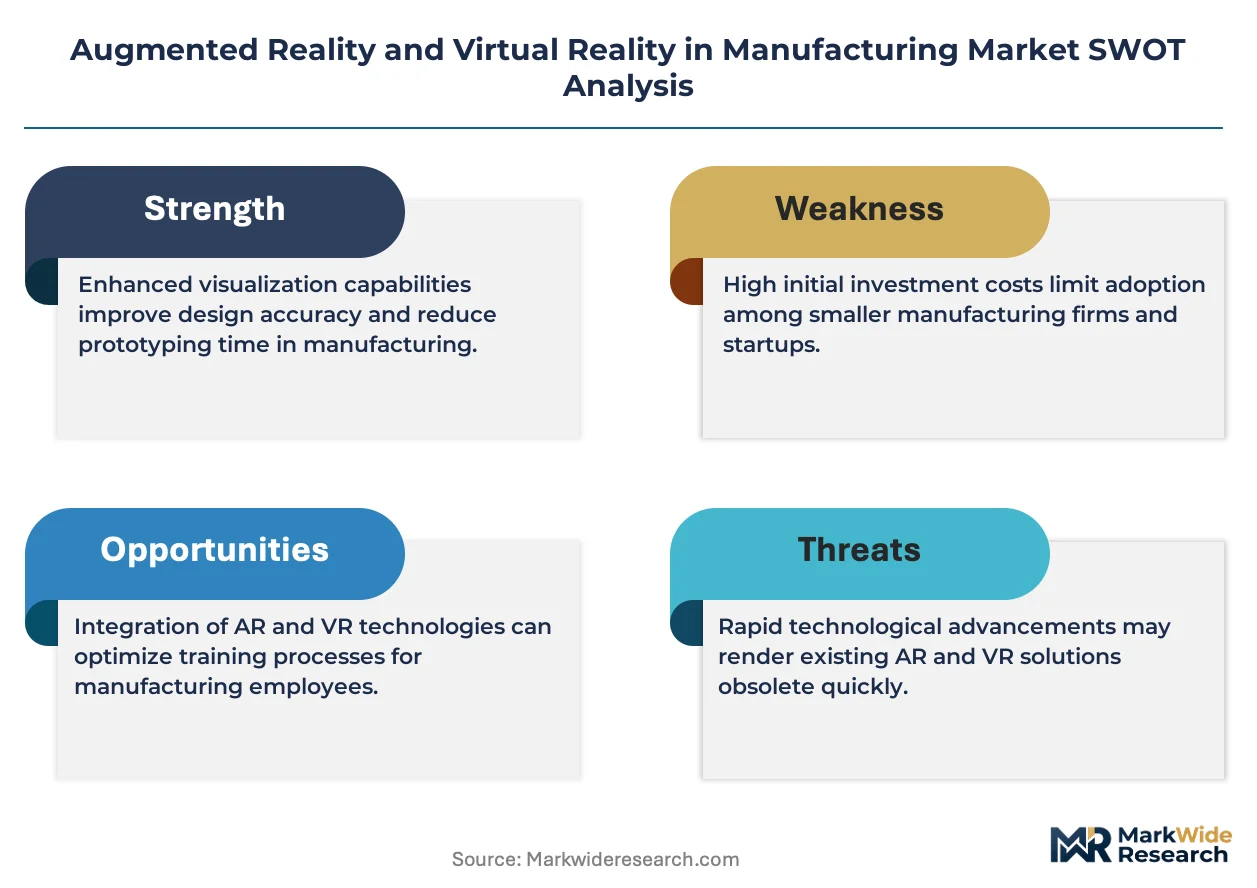
Industrial AR/VR deployments are compressing workforce training cycles while EU machinery safety directives and the AI Act impose new compliance burdens on immersive guidance systems operating alongside human operators.
Growth Catalysts
- EU AI Act compliance mandates:Manufacturers in Germany and France must document algorithmic decision-making in AR-guided assembly, creating procurement pull for auditable immersive platforms.
- Foxconn smart factory integration:Electronics contract manufacturers in China's eastern corridor are standardizing VR training modules to reduce onboarding time for seasonal workforce surges.
- Sub-20ms motion-to-photon latency:Advances in edge computing and 5G private networks now enable real-time AR overlay precision for wiring harness installation without operator nausea.
Market Restraints
- Optical waveguide input concentration:High-resolution microdisplay supply chains cluster in South Korean and Japanese component foundries, exposing hardware vendors to single-source risk.
- FCC spectrum allocation friction:Industrial AR streaming requires dedicated millimeter-wave licenses that extend hardware certification timelines by 8-14 months for US deployments.
- IP67 enclosure cost premium:Dust and liquid ingress protection for foundry-grade smart glasses adds 35-50% to bill-of-materials versus consumer headsets.
Strategic Opportunities
- India PLI scheme manufacturing incentives:Production-linked incentives for electronics assembly are drawing AR hardware assembly to Gujarat and Tamil Nadu industrial corridors.
- Digital twin convergence with real-time 3D engines:Factory-floor simulation platforms are merging with immersive training environments to create unified operational intelligence layers.
- OSHA workplace safety standard updates:Pending guidance on AR headset use near moving machinery will clarify liability frameworks and unlock petrochemical sector deployments.
Industry Challenges
- Spatial computing talent scarcity:Industrial UX designers with simultaneous expertise in CAD workflows and human factors engineering command 40-60% salary premiums.
- ISO/IEC 27001 certification timelines:Information security management audits for AR systems processing production data extend enterprise sales cycles by 4-6 months.
- Legacy MES integration complexity:Manufacturing execution systems from the 2000s lack API architectures for bi-directional data flow with modern immersive platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality and Virtual Reality in Manufacturing Market |
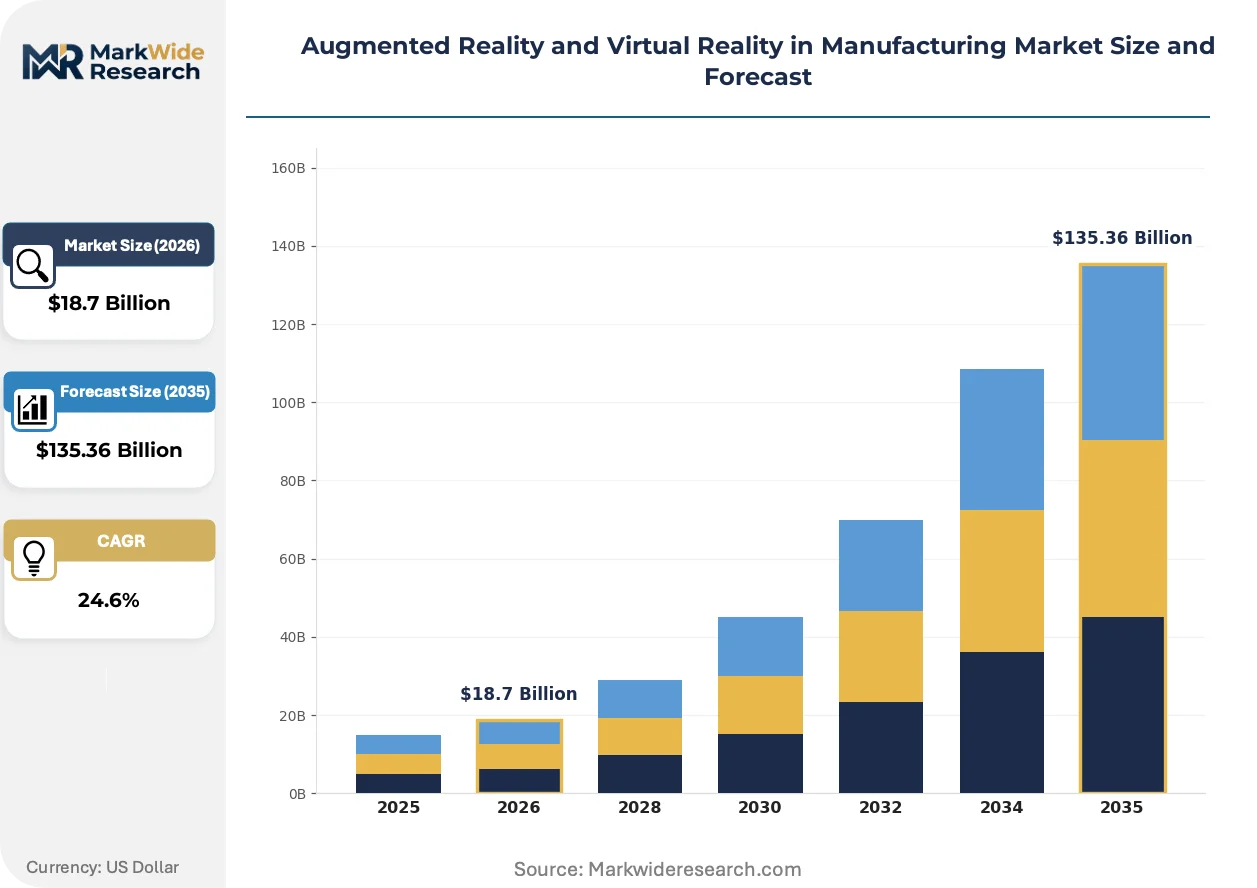
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Training, Simulation, Maintenance, Quality Assurance End User: Aerospace, Automotive, Electronics, Heavy Machinery Device Type: Head-Mounted Displays, Handheld Devices, Smart Glasses, Immersive Caves Technology: Gesture Recognition, Motion Tracking, 3D Mapping, Environment Awareness |
| Companies Covered | Treeview, CAE, Unity Technologies, 8th Wall, ShapesXR, Meta, Magic Leap, Youbiquo, Varjo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality and Virtual Reality in Manufacturing Market Strategic Shifts & Innovations
Photorealistic mixed reality is displacing screen-based simulation across safety-critical training environments, while regulatory pressure on algorithmic transparency is reshaping how immersive systems are architected and sold.
Varifocal display technology is migrating from aerospace simulation contracts into automotive assembly guidance, where BMW and Mercedes-Benz procurement teams are piloting headsets that eliminate vergence-accommodation conflict during prolonged wiring tasks. German automotive plants are adopting these systems at 2-3 year refresh cycles, compressing the traditional 5-year simulation hardware replacement timeline.
The EU AI Act's risk classification framework is redefining liability for autonomous AR guidance systems that direct human operators in safety-critical manufacturing steps. Industrial software vendors must now maintain algorithmic audit trails and human-in-the-loop override capabilities for high-risk applications. Medical device and aerospace manufacturers in France and Italy are responding by segregating AR training modules from real-time guidance functions to isolate compliance scope.
Aftermarket service contracts are unbundling immersive remote assistance from traditional field technician dispatch agreements. North American heavy machinery dealers now sell AR-enabled troubleshooting as standalone subscriptions, displacing bundled maintenance contracts. This shift is most visible in mining equipment and agricultural machinery segments, where dealer networks in Alberta and Iowa report 30-40% reduction in emergency site visits.
Augmented Reality and Virtual Reality in Manufacturing Market Segmentation
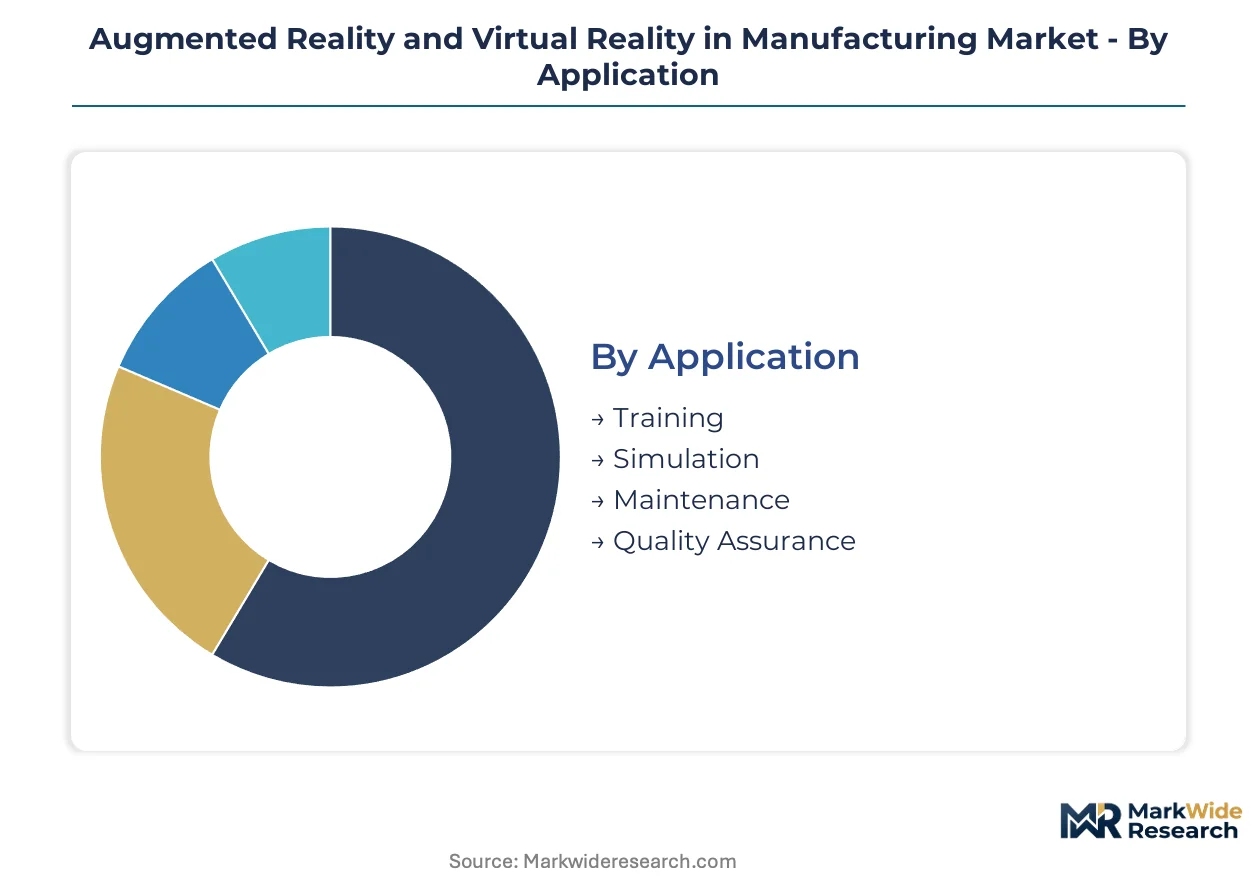
Industrial AR/VR deployments fragment across four critical dimensions: application use case, end-user vertical, hardware form factor, and underlying sensing technology. Each segmentation axis reveals distinct procurement patterns, margin structures, and compliance requirements that shape vendor go-to-market strategies.
Application:
Mature use cases dominate procurement volume while emerging applications capture the steepest growth trajectories as manufacturers expand beyond pilot programs.
- Training:Repeatable virtual scenarios replace physical mock-ups for workforce onboarding, with Foxconn and BYD standardizing VR modules across China's eastern manufacturing corridor to compress seasonal hiring cycles. Seasonal workforce surges in electronics contract manufacturing drive standardization investments.
- Quality Assurance:AR-guided inspection protocols displace paper-based checklists in regulated industries, concentrating fastest in FDA-governed medical device manufacturing where audit trail requirements favor digital overlays. Aerospace suppliers in Toulouse and Hamburg adopt these systems to satisfy EASA documentation standards.
- Simulation:Fully immersive environments replicate hazardous operational scenarios without production line disruption.
- Maintenance:Remote assistance platforms reduce field technician dispatch costs through real-time expert guidance overlays.
Training retains volume leadership; Quality Assurance holds the steepest expansion curve.
End User:
Cost tier differentiation separates capital-intensive verticals with dedicated simulation budgets from price-sensitive sectors purchasing standardized training packages.
- Automotive:German and Japanese assembly lines deploy AR-guided workflows for complex wiring harness installation, with BMW and Mercedes-Benz procurement teams piloting varifocal displays at accelerated 2-3 year refresh cycles. Sub-20ms motion-to-photon latency requirements from edge computing investments protect against operator disorientation.
- Aerospace:Photorealistic mixed-reality contracts command premium positioning for flight crew and maintenance technician certification, with EASA and FAA dual certification requirements extending sales cycles. Simulation fidelity demands sustain hardware margins above industrial averages.
- Electronics:High-volume contract manufacturers prioritize scalable VR training for seasonal workforce fluctuations.
- Heavy Machinery:Aftermarket service unbundling creates standalone AR troubleshooting subscriptions for mining and agricultural equipment dealers.
Automotive commands the largest procurement volumes; Aerospace maintains the highest-margin contract structures.
Device Type:
Supply concentration in South Korean and Japanese microdisplay foundries shapes hardware availability and certification timelines across form factor categories.
- Head-Mounted Displays:Enterprise procurement volumes dominate revenue, with Meta's Quest enterprise ecosystem anchoring deployments across North American automotive plants. FCC millimeter-wave spectrum licensing extends US certification timelines by 8-14 months for factory-floor streaming applications.
- Smart Glasses:IP67 dust and liquid ingress protection for foundry and cleanroom deployment adds 35-50% bill-of-materials premium versus consumer headsets, sustaining highest-margin positioning. Hands-free assembly guidance in electronics manufacturing exploits this form factor's ergonomic advantages.
- Handheld Devices:Tablet-based AR overlays serve intermittent inspection tasks where continuous wear is impractical.
- Immersive Caves:Projection-based multi-wall environments persist in aerospace design review and automotive styling clinics.
Head-Mounted Displays lead enterprise shipment volumes; Smart Glasses capture the premium pricing tier.
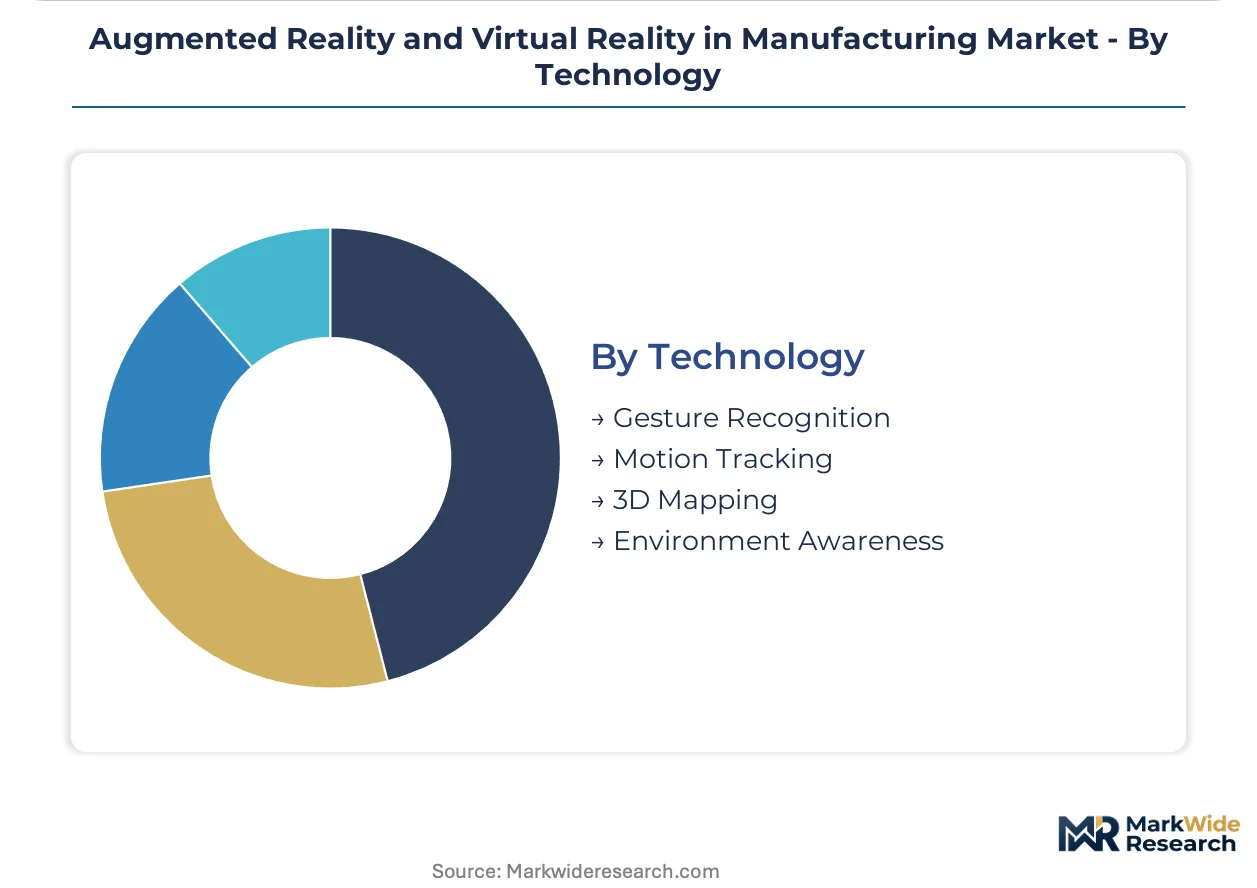
Technology:
Customer type stratification separates integrated platform vendors from component specialists as manufacturers demand bundled versus best-of-breed sensing stacks.
- Motion Tracking:Sub-20ms latency requirements for precision assembly tasks drive convergence of optical and inertial sensing fusion, with 5G private networks enabling edge-rendered positional updates. German automotive plants specify these systems for wiring harness guidance.
- 3D Mapping:Real-time spatial reconstruction underpins digital twin convergence with immersive training environments, with Unity Technologies extending its engine into factory-floor operational intelligence layers. Spatial computing talent scarcity inflates implementation costs 40-60% for this capability.
- Gesture Recognition:Hands-free interface protocols accommodate contaminated glove scenarios in chemical and pharmaceutical manufacturing.
- Environment Awareness:Sensor fusion for collision detection near moving machinery awaits pending OSHA guidance for petrochemical sector unlock.
Motion Tracking anchors current procurement; 3D Mapping is climbing the fastest as digital twin investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across manufacturing corridors. Electronics contract manufacturers in China absorb volume-driven hardware costs, while German automotive OEMs prioritize premium latency specifications regardless of unit economics.
United States
North American automotive plants anchor enterprise headset procurement through Meta's Quest ecosystem. FCC millimeter-wave spectrum licensing extends hardware certification timelines by 8-14 months, constraining factory-floor AR streaming deployments. Detroit-Windsor assembly corridors and Iowa agricultural machinery dealer networks report 30-40% reductions in emergency site visits through AR-enabled remote assistance.
Germany
BMW and Mercedes-Benz procurement teams pilot varifocal displays at accelerated 2-3 year refresh cycles for wiring harness installation workflows. EU AI Act compliance mandates require documented algorithmic decision-making in AR-guided assembly, pulling procurement toward auditable immersive platforms. Stuttgart and Munich automotive clusters specify sub-20ms motion-to-photon latency systems protected by edge computing investments.
China
Foxconn and BYD standardize VR training modules across eastern manufacturing corridors to compress seasonal workforce onboarding cycles. MIIT industrial internet policies accelerate 5G private network deployments for factory-floor AR streaming. Shenzhen and Suzhou electronics assembly hubs concentrate demand for IP67-protected smart glasses in foundry-grade environments.
Japan
Automotive assembly lines in Toyota City and Yokohama deploy AR-guided workflows for precision wiring tasks. METI smart factory initiatives subsidize immersive technology integration for SME component suppliers. JIS standards for industrial display brightness and durability shape procurement specifications for cleanroom deployment.
India
Production-linked incentives for electronics assembly draw AR hardware assembly toward Gujarat and Tamil Nadu industrial corridors. BIS certification requirements for industrial display equipment extend market entry timelines for foreign hardware vendors. Bangalore and Chennai IT-ITES clusters incubate spatial computing talent pools for manufacturing UX design.
Augmented Reality and Virtual Reality in Manufacturing Market Key Industry Players
Platform-scale technology vendors and specialized immersive hardware manufacturers split the market along enterprise deployment depth. Consolidation pressures concentrate around three strategic archetypes: real-time 3D engine providers, photorealistic headset specialists, and enterprise ecosystem integrators. Dominant competitive moves include strategic partnerships between software platforms and industrial automation vendors, plus geographic expansion through local manufacturing incentives in India and Southeast Asia.
Within the enterprise ecosystem tier, Meta anchors industrial training deployments across North American automotive plants. Varjo occupies a position among photorealistic mixed-reality specialists serving aerospace simulation contracts. Unity Technologies exemplifies the real-time 3D engine archetype extending into factory-floor digital twin environments.
| Leading Market Players |
|---|
| Treeview |
| CAE |
| Unity Technologies |
| 8th Wall |
| ShapesXR |
| Meta |
| Magic Leap |
| Youbiquo |
| Varjo |
| Others |
Cost & Logistics Intelligence
Optical waveguide input concentration in South Korean and Japanese microdisplay foundries determines both the 35-50% cost premium for IP67-protected smart glasses and the geographic clustering of hardware assembly operations. This single-source dependency compresses margins for foundry-grade deployments while amplifying procurement power for electronics contract manufacturers with volume scale.
Pricing Analysis
Aftermarket service revenue from AR-enabled remote assistance subscriptions drives lifetime value for industrial headset vendors. Three-tier pricing structure across enterprise ecosystem bundles, standalone hardware procurement, and per-seat SaaS licensing separates automotive OEMs from contract manufacturers from SME component suppliers. Pricing pressure stems from FCC millimeter-wave spectrum licensing delays extending US certification timelines. Electronics contract manufacturers in China's eastern corridor exhibit highest price sensitivity due to seasonal workforce volatility, while German automotive OEMs prioritize sub-20ms latency specifications regardless of unit cost.
Supply Chain Analysis
High-resolution microdisplay feedstock draws from South Korean and Japanese component foundries, with optical waveguide substrates and silicon backplanes as critical inputs. Raw material dependencies include rare-earth phosphors for display brightness, precision-molded polymer optics, and 5G mmWave antenna modules. Single-source vulnerability in microdisplay lithography equipment exposes hardware vendors to capacity allocation risk. Distribution runs through direct enterprise procurement for automotive and aerospace verticals, with systems integrators and industrial automation vendors serving mid-market electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EU AI Act compliance mandates for algorithmic audit trails create switching costs that cement incumbent positions across safety-critical manufacturing verticals.
For Market Incumbents: Insulate platform positions by deepening backward integration into optical waveguide manufacturing to neutralize South Korean and Japanese foundry concentration risk. Accelerate ISO/IEC 27001 certification investments to compress enterprise sales cycles against emerging software entrants. Prioritize human-in-the-loop override capabilities that satisfy EU AI Act high-risk application requirements.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's Gujarat and Tamil Nadu industrial corridors where Production-Linked Incentive schemes reduce hardware assembly cost structures. Target heavy machinery aftermarket service unbundling as the most penetrable segment, where AR-enabled troubleshooting subscriptions displace bundled maintenance contracts. Deploy channel partnerships with agricultural and mining equipment dealers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Pending OSHA workplace safety standard updates for AR headset use near moving machinery reshapes the acquisition landscape toward petrochemical sector readiness. Long-term viability favors platform-scale vendors with integrated real-time 3D engines and enterprise ecosystem penetration over pure-play hardware manufacturers. Monitor EASA and FAA dual certification completion rates as the signal to watch for aerospace simulation contract inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Partnership | Sub-20ms motion-to-photon latency requirements from German automotive plants drive 5G private network co-investment. |
| Regulatory Compliance Platform Integration | EU AI Act algorithmic audit trail capabilities differentiate vendors for France and Italy medical device manufacturers. |
| Spatial Computing Talent Acquisition | Industrial UX designers with CAD and human factors expertise command premiums that inflate implementation costs. |
| Digital Twin Convergence Development | Unity Technologies and factory-floor simulation platforms merge immersive training with operational intelligence layers. |
| India Local Manufacturing Establishment | PLI scheme incentives for electronics assembly draw AR hardware production to Gujarat and Tamil Nadu corridors. |
Research Approach
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, MIIT industrial internet policy documents, EMA and FDA software-as-a-medical-device guidance, and customs/trade data for optical component flows. Bottom-up deployment estimates triangulated against top-down manufacturing automation spending patterns.
Scenario-bracketing framed analytical approach across the projection horizon, with segmentation dimensions spanning application use case, end-user vertical, hardware form factor, and underlying sensing technology. CAGRs derived from installed base growth rates and replacement cycle compression in German automotive plants. Industry-specific forecast inputs included Foxconn and BYD VR training module standardization timelines and EASA documentation standard adoption curves for aerospace suppliers.
Sensitivities concentrate around FCC spectrum allocation timelines, EU AI Act enforcement intensity, and optical waveguide foundry capacity expansion decisions. Cross-checking against IHS Markit industrial automation equipment forecasts and hyperscaler edge computing capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Mobile Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Visor Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market