
 Spatial Augmented Reality Market | 2026-2036
Spatial Augmented Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Spatial Augmented Reality Market Analytics
Silicon photonics is expanding its footprint in spatial AR headset waveguides, displacing conventional glass-based combiners across mid-tier hardware tiers. Microsoft leverages its Azure cloud backbone to anchor enterprise deployment pipelines for industrial digital-twin overlays. Magic Leap specializes in precision optical manufacturing for medical and defense training simulations. Meta competes through aggressive R&D intensity in consumer-facing passthrough mixed-reality architectures.
Spatial augmented reality superimposes computer-generated imagery onto physical environments without isolating displays, typically employing projection mapping, depth-sensing arrays, or transparent waveguide optics operating at sub-10-millisecond motion-to-photon latency. Its primary commercial purpose spans real-time annotation, remote assistance, and immersive product visualization across manufacturing and retail workflows. Hardware platforms currently dominate capital allocation as headset and projector OEMs race to resolve thermal dissipation and field-of-view constraints. Software and services segments capture expanding margin pools as enterprises prioritize subscription-based content authoring tools and managed deployment frameworks over one-time device purchases.
The FCC governs radio-frequency emissions and unlicensed spectrum use for wireless spatial AR devices in the United States, while the EU AI Act imposes conformity requirements on biometric inference and environmental scanning algorithms entering European commercial channels. GDPR data-localization rules further shape cloud-rendering architectures, forcing vendors to regionalize processing nodes or adopt edge-heavy designs. Stakeholders must monitor evolving product-safety classifications for head-worn projection systems as national medical-device regulators scrutinize ocular exposure thresholds and cognitive-load thresholds in occupational settings.
Market Dynamics
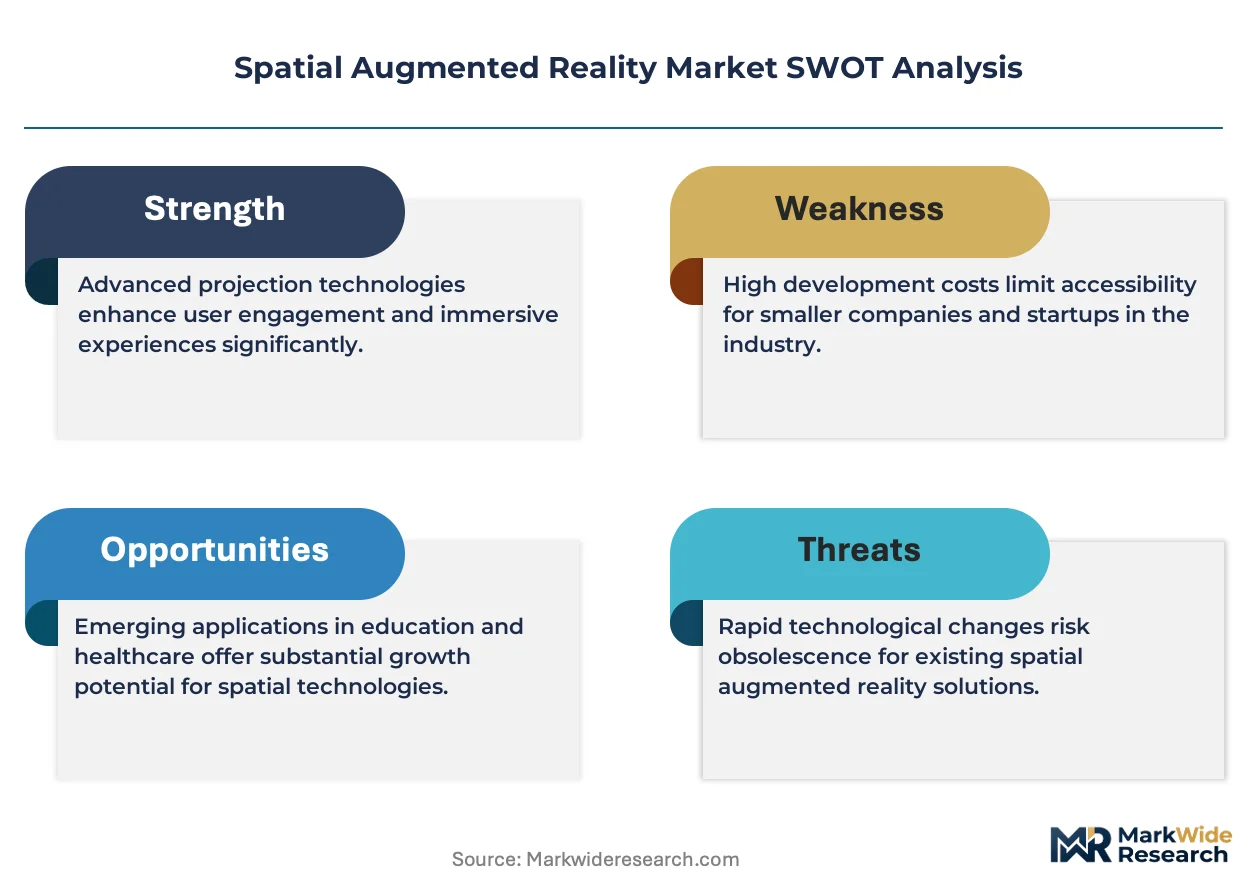
Enterprise demand for sub-10-millisecond motion-to-photon latency is compressing hardware refresh cycles and forcing OEMs to rearchitect thermal dissipation systems around silicon photonics waveguides.
Growth Catalysts
- EU AI Act Conformity Requirements:Biometric inference and environmental scanning mandates are accelerating privacy-preserving edge-computing deployments across German industrial automation corridors.
- Silicon Photonics Integration:Transparent waveguide optics are displacing conventional glass combiners in mid-tier headset tiers, reducing weight and power draw for extended occupational use.
- Automotive Design Visualization:BMW and Siemens anchor applied research programs that validate spatial AR for assembly guidance and digital-twin overlay workflows.
Market Restraints
- Field-of-View Thermal Constraints:Passive cooling limitations in compact waveguide engines cap maximum display angles before ocular exposure thresholds trigger occupational safety reviews.
- Rare Earth Magnet Supply Concentration:Precision actuator motors for depth-sensing arrays depend on concentrated upstream refining capacity outside OECD jurisdictions.
- GDPR Data-Localization Friction:Cloud-rendering architectures face mandatory regionalization of processing nodes, fragmenting economies of scale for centralized SaaS content platforms.
Strategic Opportunities
- Medical Training Simulation White Space:Precision optical manufacturing capabilities developed for defense applications are transferable to surgical rehearsal and radiological anatomy visualization.
- CSRD Sustainability Disclosure Alignment:Enterprise spatial AR deployments reduce physical prototyping waste, qualifying adopters for enhanced ESG scoring and green financing access.
- Edge-Heavy Architecture Convergence:5G network slicing and on-device neural inference are collapsing latency requirements for remote assistance use cases in distributed manufacturing footprints.
Industry Challenges
- Optical Engineering Talent Scarcity:Waveguide design and silicon photonics integration require specialized photonics PhD pipelines that lag hardware roadmap demands by 24-36 months.
- MDR Certification Timelines:Head-worn projection systems face evolving medical-device classifications in European occupational settings, extending commercialization cycles for workplace wellness applications.
- Legacy MES Integration Complexity:Spatial AR overlay deployment requires custom API middleware for SAP and Siemens manufacturing execution systems, inflating professional services attach rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spatial Augmented Reality Market |
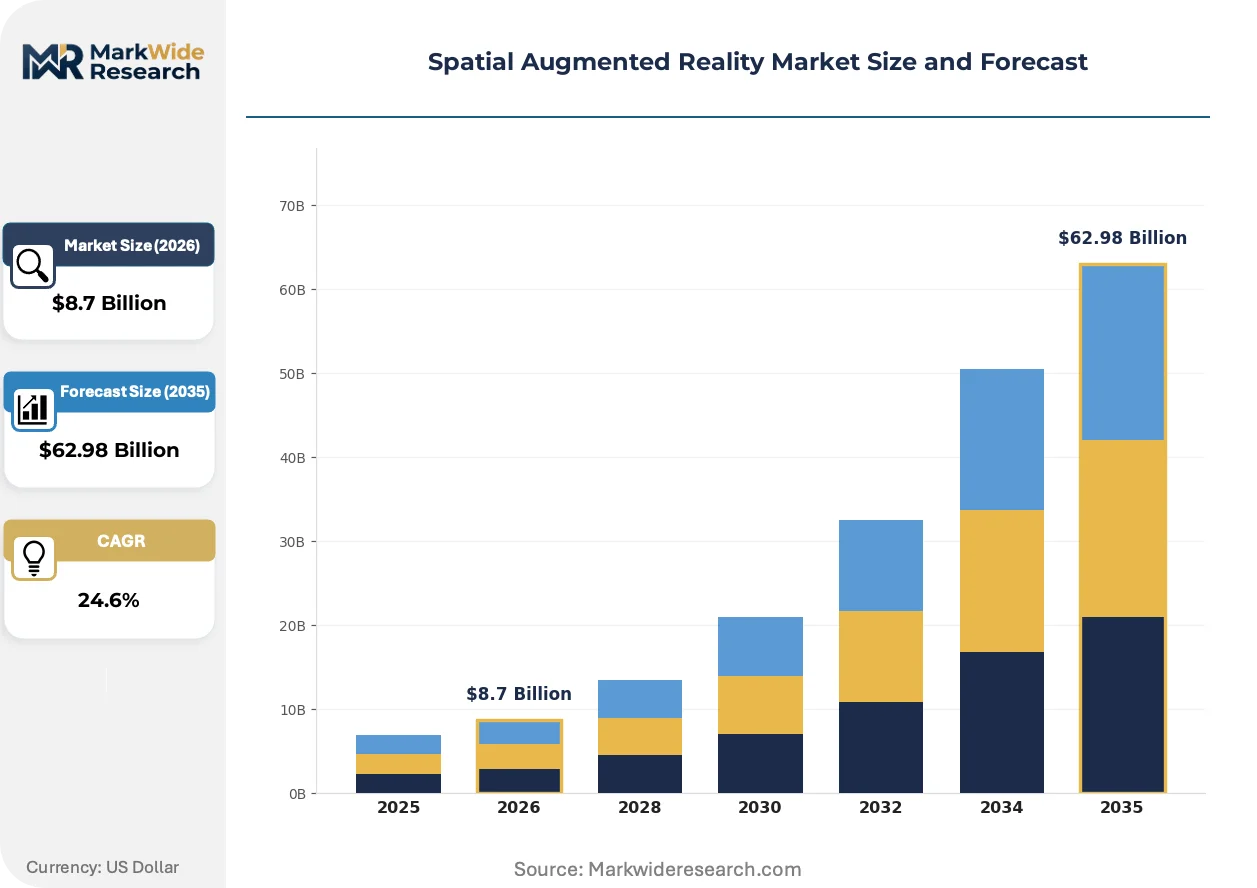
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Advertising, Gaming, Retail, Education Technology: Projection Mapping, Marker-Based, Markerless, Digital Twin End User: Enterprises, Consumers, Artists, Educators Product Type: Hardware, Software, Services, Platforms |
| Companies Covered | Microsoft, Magic Leap, Meta, Autodesk, Snap Inc., PTC, Niantic, RealWear, Unity Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spatial Augmented Reality Market Evolving Landscape
Silicon photonics is actively reconfiguring optical stack economics while regulatory pressure on biometric data processing forces architectural pivots toward federated inference models.
Waveguide combiners fabricated on silicon photonics platforms are converging with micro-LED emitter arrays to shrink optical engine volume by half. Automotive and aerospace design studios are piloting these integrated stacks for collaborative review sessions. The convergence is compressing bill-of-materials differentiation between premium and mid-tier headset tiers, forcing OEMs to compete on software ecosystem depth rather than hardware specifications alone.
The EU AI Act's risk-classification framework for biometric inference systems is mandating conformity assessments for environmental scanning algorithms before European commercial channel entry. Industrial digital-twin vendors must now document algorithmic transparency and human oversight protocols. German automotive manufacturers are responding by pre-certifying spatial AR modules through notified bodies to avoid production line deployment delays.
Subscription-based content authoring tools are displacing perpetual-license software procurement in enterprise spatial AR deployments. Manufacturing engineering teams now prioritize managed deployment frameworks with embedded training and content update services over one-time device purchases. This preference shift is most visible in Bavaria's industrial automation corridor, where BMW and Siemens procurement specifications now require SaaS delivery models for new spatial computing vendor selection.
Spatial Augmented Reality Market Segmentation
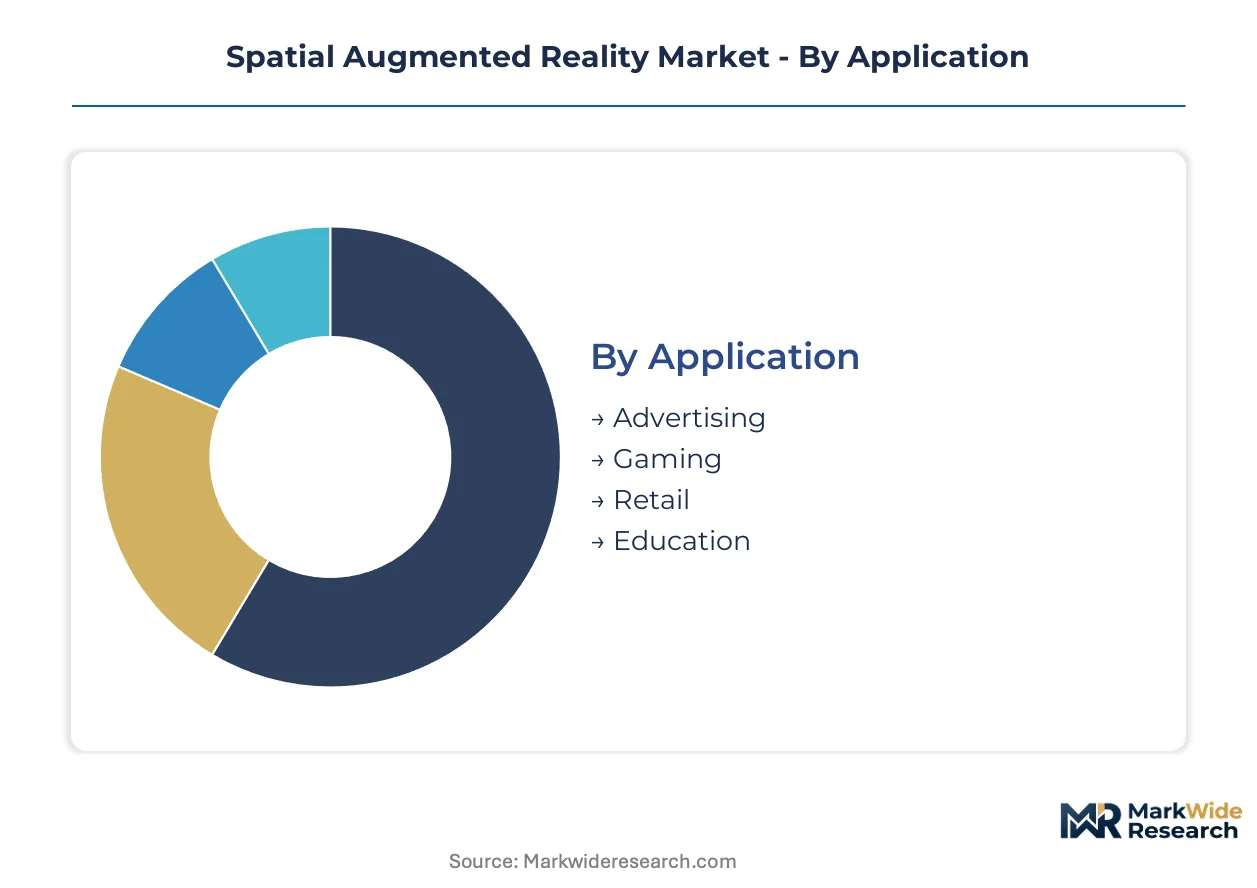
Spatial augmented reality market segmentation reveals divergent technology maturity curves and deployment economics across application contexts. Hardware platforms currently absorb disproportionate capital allocation while software margins expand through subscription monetization. Understanding segment boundaries clarifies where silicon photonics integration and EU regulatory compliance create competitive separation.
Application:
Projection density and environmental control requirements vary sharply across deployment contexts, dictating hardware specifications and content authoring complexity.
- Advertising:High-lumen projector arrays dominate urban out-of-home deployments where ambient light suppression demands active calibration systems. German automotive manufacturers BMW and Siemens pilot spatial AR advertising for showroom experiential marketing, validating motion-to-photon latency below 10 milliseconds for consumer engagement retention.
- Gaming:Passthrough mixed-reality architectures enable immersive gameplay without environmental isolation, requiring depth-sensing arrays with sub-millimeter spatial accuracy. Meta's consumer-facing R&D investments concentrate here, though thermal dissipation constraints limit session duration before comfort thresholds intervene.
- Retail:Product visualization overlays in furniture and apparel sectors leverage markerless tracking for seamless customer journeys.
- Education:Institutional procurement cycles favor managed deployment frameworks with embedded training services over hardware-only purchases.
Advertising leads on scale; gaming leads on momentum.
Technology:
Optical stack architecture determines bill-of-materials structure and thermal design envelope across hardware tiers.
- Projection Mapping:Active calibration systems with ambient light compensation anchor large-venue industrial and automotive visualization workflows. Bavaria's automation corridor deploys these systems for assembly guidance where environmental scanning algorithms must comply with EU AI Act conformity assessments.
- Markerless:Simultaneous localization and mapping eliminates physical fiducial dependencies, enabling spontaneous deployment in unstructured environments. Depth-sensing array power consumption remains the primary constraint for battery-operated field use.
- Marker-Based:Optical tracking via printed or projected fiducials persists in cost-constrained educational deployments.
- Digital Twin:Real-time overlay synchronization with industrial data streams requires edge-heavy architectures to satisfy GDPR data-localization requirements.
Projection mapping commands current deployment volume; markerless systems are expanding most quickly through 5G network slicing integration.
End User:
Procurement authority and budget cycle predictability segment deployment risk profiles and vendor relationship structures.
- Enterprises:Manufacturing execution system integration requirements dominate vendor selection, with SAP and Siemens middleware compatibility now mandatory in German industrial automation procurement specifications. Subscription-based content authoring tools displace perpetual licenses as BMW and Siemens anchor applied research programs.
- Consumers:Price elasticity and ecosystem lock-in sensitivity concentrate demand in passthrough mixed-reality headsets with application store depth. Meta competes through aggressive R&D intensity while thermal dissipation and field-of-view constraints remain unresolved.
- Artists:Creative professional workflows prioritize projection mapping precision for installation and performance contexts.
- Educators:Institutional procurement favors SaaS delivery models with embedded professional development over capital-intensive hardware acquisitions.
Enterprises dominate absolute spend; consumers show steepest expansion trajectory as silicon photonics reduces headset weight and power draw.
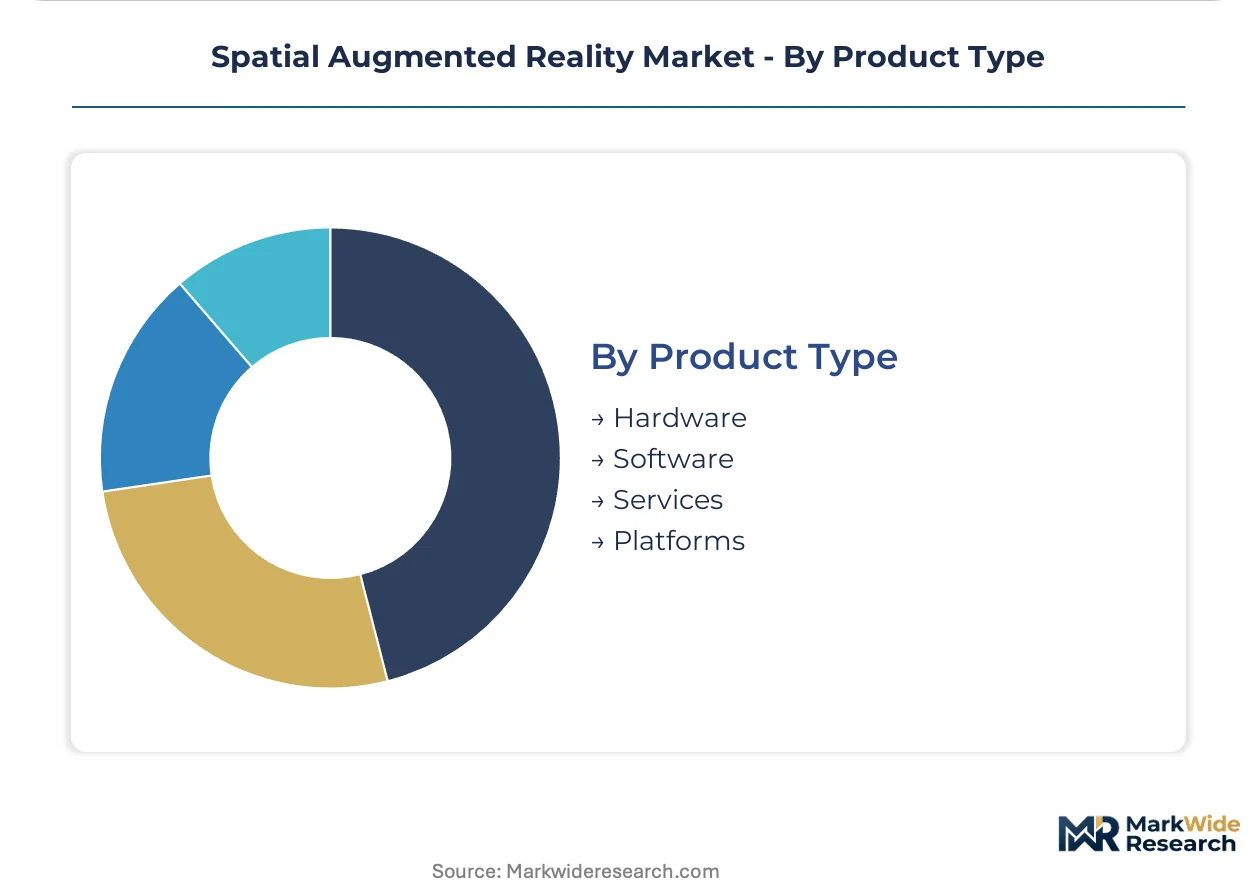
Product Type:
Margin pool distribution shifts from device sales toward recurring revenue as deployment scale matures.
- Hardware:Headset and projector OEMs race to resolve thermal dissipation around silicon photonics waveguides, with transparent combiners displacing conventional glass across mid-tier tiers. Field-of-view constraints trigger occupational safety reviews before European commercial channel entry.
- Services:Managed deployment frameworks with embedded training and content update services capture expanding margin pools as manufacturing engineering teams prioritize operational continuity over one-time device purchases.
- Software:Content authoring tools and digital-twin overlay platforms require custom API middleware for legacy manufacturing execution system integration.
- Platforms:Cloud-rendering architectures face mandatory regionalization of processing nodes under GDPR rules, fragmenting economies of scale.
Hardware retains revenue concentration; services gain share fastest through subscription monetization alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation corridor concentrates the most advanced spatial AR deployment pipelines, with automotive manufacturers and machinery OEMs driving procurement specifications for sub-10-millisecond latency systems.
United States
Enterprise digital-twin visualization and defense training simulations anchor demand across aerospace clusters in California and Washington. The FCC governs radio-frequency emissions for wireless spatial AR devices while OSHA scrutinizes ocular exposure thresholds in occupational settings. Microsoft's Azure cloud backbone supports industrial deployment pipelines from Redmond engineering facilities.
Germany
BMW and Siemens procurement specifications mandate SaaS delivery models and SAP middleware compatibility for assembly guidance systems. The EU AI Act imposes conformity assessments on environmental scanning algorithms before commercial channel entry. Bavaria's automation corridor hosts applied research programs validating spatial AR for manufacturing execution system integration.
China
Consumer passthrough mixed-reality headsets and markerless tracking for retail visualization drive volume manufacturing in Shenzhen and Dongguan electronics clusters. MIIT standards govern wireless device certification while GB standards address product safety classifications. Yangtze River Delta optical foundries supply silicon photonics waveguides for mid-tier headset tiers.
Japan
Precision optical manufacturing for medical training simulations and industrial maintenance guidance concentrates demand in Nagoya and Osaka machinery corridors. METI industrial policy supports spatial computing R&D through targeted subsidy programs. Kanto region electronics OEMs integrate micro-LED emitter arrays with silicon photonics platforms for reduced optical engine volume.
United Kingdom
Creative professional workflows for projection mapping installations and immersive advertising campaigns anchor demand in London and Manchester media clusters. The UK Information Commissioner's Office enforces biometric data processing rules aligned with GDPR frameworks. Southeast England technology parks host edge-computing infrastructure for GDPR-compliant cloud-rendering architectures.
Spatial Augmented Reality Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and precision optical manufacturing dimensions, producing a tiered structure with consolidation at the platform layer and fragmentation among specialized hardware OEMs. Three strategic archetypes dominate: cloud-native platform vendors, precision optical specialists, and industrial software integrators. Capacity expansion in silicon photonics foundries and strategic partnerships for manufacturing execution system middleware represent the dominant competitive moves.
Within the cloud-native platform tier, Microsoft exemplifies enterprise deployment pipeline anchoring through Azure infrastructure. Magic Leap occupies a position among precision optical specialists focused on medical and defense training applications. Meta represents the consumer-facing passthrough mixed-reality archetype with aggressive R&D intensity in thermal-dissipation-constrained headset architectures.
| Leading Market Players |
|---|
| Microsoft |
| Magic Leap |
| Meta |
| Autodesk |
| Snap Inc. |
| PTC |
| Niantic |
| RealWear |
| Unity Technologies |
| Others |
Value Network & Pricing Analysis
Optical engineering PhD pipelines concentrated in Bavaria and Kanto regions drive labor-cost differentials that widen pricing-tier spreads between premium silicon photonics headsets and economy-tier projection systems. Subscription-based SaaS delivery models capture expanding margin pools as manufacturing execution system integration complexity inflates professional services attach rates.
Pricing Analysis
Input-cost pass-through from rare earth magnet refining capacity outside OECD jurisdictions compresses margins on precision actuator motors for depth-sensing arrays. Three-tier pricing structure across premium, standard, and economy levels separates medical-device-certified optical engines from industrial-grade projection systems and marker-based educational hardware. Price differentiation hinges on silicon photonics integration depth and GDPR-compliant edge-computing architecture certification. Pricing pressure stems from thermal dissipation engineering bottlenecks that extend hardware refresh cycles. Enterprise manufacturing buyers show least price sensitivity due to SAP middleware compatibility mandates, while educational institutions exhibit highest sensitivity favoring capital-light SaaS procurement.
Supply Chain Analysis
Freight cost volatility from Yangtze River Delta optical foundries to German automotive assembly corridors shapes inventory positioning strategies for silicon photonics waveguide substrates. Supply concentrates in China for micro-LED emitter arrays, Japan for precision optical manufacturing equipment, and Germany for industrial automation integration hardware. Raw material dependencies span rare earth elements for actuator motors, high-purity silicon for photonics platforms, and specialized glass substrates for conventional combiners. Single-source vulnerability in non-OECD rare earth refining capacity presents structural supply chain risk. Distribution runs through hyperscale cloud infrastructure regionalized under GDPR data-localization mandates, with edge-computing nodes fragmenting centralized SaaS platform economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics cost curves are flattening optical stack economics while premium-tier medical-device certification creates pricing power separation. Margin expansion opportunities concentrate in subscription monetization and precision optical manufacturing capabilities.
For Market Incumbents: Anticipate regulatory compression from EU AI Act conformity timelines by pre-certifying environmental scanning algorithms through notified bodies before commercial channel entry. Consolidate position through backward integration into silicon photonics foundry capacity in Yangtze River Delta clusters to secure waveguide supply against rare earth magnet volatility. Deepen SAP and Siemens manufacturing execution system middleware partnerships to inflate professional services attach rates and defend against cloud-native platform disintermediation. For New Entrants and Emerging Players: Direct-to-enterprise SaaS channels offer the lowest customer acquisition friction for spatial AR content authoring tools targeting Bavaria's industrial automation corridor. White-space opportunities concentrate in medical training simulation applications where precision optical manufacturing capabilities transfer from defense contracts. Surgical rehearsal and radiological anatomy visualization segments show lowest incumbent penetration. Prioritize GDPR-compliant edge-heavy architectures with embedded training services to bypass centralized cloud-rendering infrastructure disadvantages. For Investors and Strategic Acquirers: Cloud infrastructure hyperscalers are the most active acquirer in this space, seeking vertical integration into spatial computing deployment pipelines. Long-term viability favors precision optical specialists with silicon photonics manufacturing capabilities and established notified body relationships for EU MDR certification. Acquisition target archetypes include industrial software integrators with SAP middleware expertise and regional content authoring platforms with embedded training frameworks. Monitor silicon photonics yield improvements at Yangtze River Delta foundries as inflection indicator for hardware cost compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Investment | Backward integration into waveguide manufacturing reduces rare earth supply vulnerability for OEMs. |
| EU AI Act Pre-Certification | Notified body alignment accelerates commercial channel entry for environmental scanning algorithms. |
| SaaS Content Platform Launch | Subscription monetization captures manufacturing engineering teams prioritizing operational continuity. |
| Medical Device Certification Pathway | MDR compliance unlocks surgical rehearsal and occupational wellness application pricing premiums. |
| 5G Network Slicing Partnership | Edge-heavy architecture convergence collapses latency requirements for distributed manufacturing footprints. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with optical engineering directors, manufacturing execution system integrators, cloud infrastructure procurement officers, and medical device regulatory affairs specialists with secondary validation. Secondary sources encompassed SEC filings from headset OEMs, hyperscaler capex disclosures, EU notified body certification databases, and industrial automation trade association deployment surveys. Bottom-up hardware shipment modeling and top-down enterprise IT spending allocation triangulated market sizing across the analysis window.
Comparable-period anchoring linked projection horizon assumptions to historical refresh cycle patterns in industrial display equipment and enterprise software adoption curves. Segmentation dimensions spanned optical stack architecture, deployment model, end-user procurement authority, application latency requirements, and regional regulatory framework clusters. CAGRs derived from installed base growth rates and average revenue per unit trajectories across subscription and perpetual license mix shifts. Forecast inputs incorporated silicon photonics yield improvement curves and EU AI Act implementation timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for transparent waveguide optics versus conventional glass combiners would alter the outlook. Forecasts reflect documented assumptions regarding thermal dissipation engineering progress and rare earth supply chain stability. A model refresh is warranted upon material change in EU MDR certification timelines or silicon photonics foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Amusement Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market