
 Global Group IV and V Lubricants Market | 2026-2036
Global Group IV and V Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Group IV and V Lubricants Market Foresight
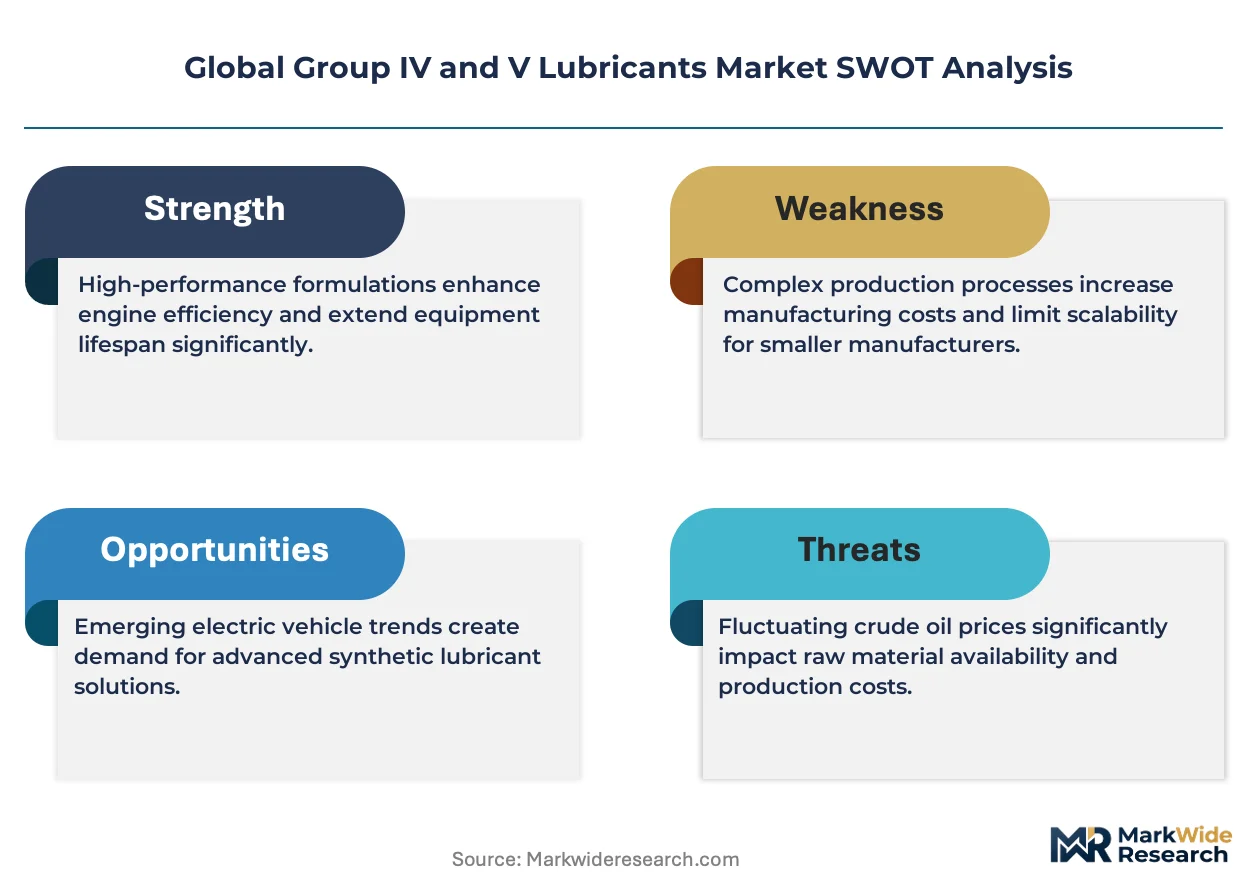
The capital-intensity divergence between integrated refiners and specialty chemical blenders is collapsing as polyalphaolefin production requires identical metallocene catalyst investments across both tiers. ExxonMobil leverages its Baytown, Texas, alphaolefin complex to sustain captive feedstock economics for Group IV base stocks. Idemitsu Kosan anchors its Asian position through technology leadership in low-viscosity PAO grades for hybrid vehicle transmissions. Fuchs competes by dominating the European industrial aftermarket with ester-based hydraulic fluids certified to DIN 51524.
Group IV and V lubricants comprise synthetic base oils engineered through oligomerization of alphaolefins or esterification of organic acids, delivering viscosity indices above 130 and pour points below minus forty degrees Celsius for extreme-temperature machinery protection. Polyalphaolefins lead product-type value generation due to their compatibility with existing mineral-oil infrastructure, while esters capture premium margin pools in aviation turbine applications requiring thermal oxidative stability above 200 degrees Celsius. Fleet managers represent the fastest-growing end-user channel as telematics-enabled oil-drain optimization justifies higher synthetic unit costs through extended service intervals.
FAA airworthiness directives and EASA Certification Memoranda mandate synthetic lubricant performance for new turbofan architectures, while EPA fuel-economy standards and REACH substance restrictions shape automotive formulation requirements in the United States and Europe. China's GB 11121 and GB 11122 standards, administered by SAMR, enforce synthetic content minimums for heavy-duty diesel engine oils. Stakeholders must monitor divergence between OEM factory-fill specifications and aftermarket certification protocols as electric drivetrain penetration redefines thermal management fluid requirements across passenger and commercial vehicle platforms.
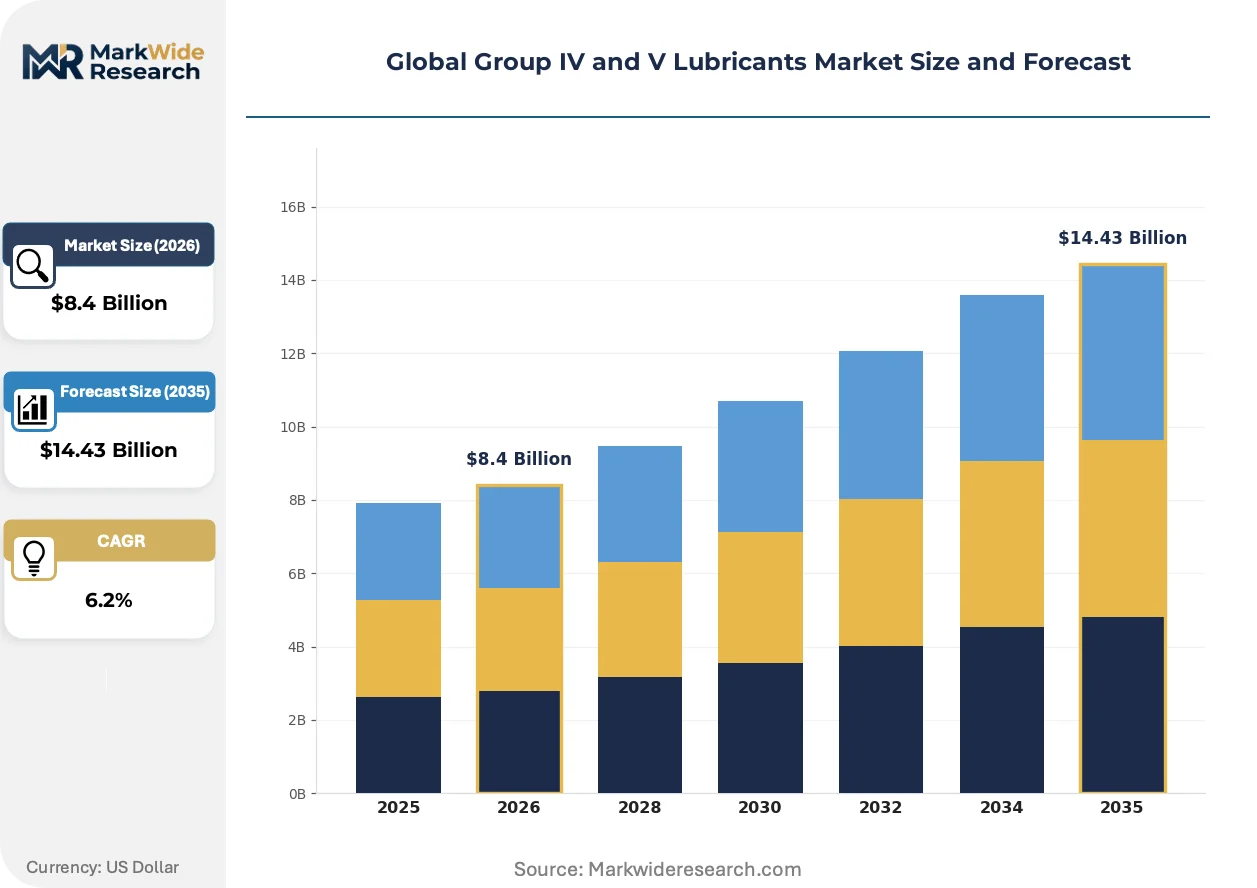
Market Dynamics
Metallocene catalyst investments are collapsing the capital barrier between integrated refiners and specialty blenders, forcing identical production economics across tiers that previously operated in separate cost structures.
Growth Catalysts
- FAA Airworthiness Directives:Mandates for synthetic lubricant performance in new turbofan architectures create locked-in demand from aerospace turbine engine manufacturers.
- Telematics-enabled oil-drain optimization:Fleet managers leverage real-time monitoring to justify higher synthetic unit costs through extended service intervals.
- China's SAMR-administered GB standards:GB 11121 and GB 11122 enforce synthetic content minimums for heavy-duty diesel engine oils across domestic manufacturing.
Market Restraints
- Alphaolefin feedstock concentration:Captive supply from integrated petrochemical complexes limits independent blender access to cost-competitive Group IV base stocks.
- REACH substance restrictions:ECHA registration requirements for novel ester formulations extend commercialization timelines by 18-24 months.
- Mineral oil infrastructure compatibility:Existing plant and distribution systems designed for Group I-III stocks create technical friction for synthetic substitution.
Strategic Opportunities
- Electric drivetrain thermal management:Battery and motor cooling systems require dielectric fluid formulations with synthetic base stock performance profiles.
- India's PLI scheme for automotive:Domestic OEM factory-fill specifications create localized demand for PAO-based transmission fluids.
- Performance-based lubricant contracts:Industrial end-users in Germany's precision manufacturing corridor adopt uptime-guarantee pricing models.
Industry Challenges
- Metallocene catalyst operator scarcity:Specialized polymerization expertise concentrates at legacy alphaolefin producers, constraining new entrant scale-up.
- OEM factory-fill specification divergence:Electric vehicle platforms develop proprietary thermal fluid requirements incompatible with existing certification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Group IV and V Lubricants Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyalphaolefins, Esters, Alkylated Naphthalenes, Synthetic Hydrocarbons, Diesters Application: Automotive Engines, Industrial Machinery, Aircraft, Marine Equipment, Hydraulic Systems End User: OEMs, Heavy Equipment Operators, Fleet Managers, Equipment Maintenance Providers, Aviation Operators Packaging Type: Drums, Bulk Containers, Tins, Bottles, Cartridges |
| Companies Covered | ExxonMobil, Chevron, Royal Dutch Shell, BP, Total, Fuchs, ConocoPhillips, Indian Oil Corporation, Idemitsu Kosan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Group IV and V Lubricants Market Shifts & Advancements
Synthetic lubricant formulation is fragmenting across performance tiers as end-users abandon one-size-fits-all mineral oil replacements in favor of application-optimized chemistries.
Low-viscosity polyalphaolefin grades are fragmenting the traditional viscosity-grade ladder for hybrid vehicle transmissions. Japanese OEMs specify 0W-8 and 0W-12 grades for thermal efficiency gains. The technology is fragmenting established supply relationships as blenders without metallocene capacity lose access to premium factory-fill contracts.
REACH substance restrictions are compressing the approved additive palette for European automotive lubricants. ECHA authorization requirements for zinc dialkyldithiophosphate alternatives force reformulation of anti-wear packages. Ester-based formulations capture margin premiums as compliant solutions for high-performance segments.
Condition-based monitoring contracts are displacing fixed-drain maintenance schedules in North American fleet operations. Telematics providers integrate oil analysis sensors to trigger service events. Heavy-duty trucking corridors through Texas and California show fastest uptake as fuel economy regulations tighten.
Global Group IV and V Lubricants Market Segmentation
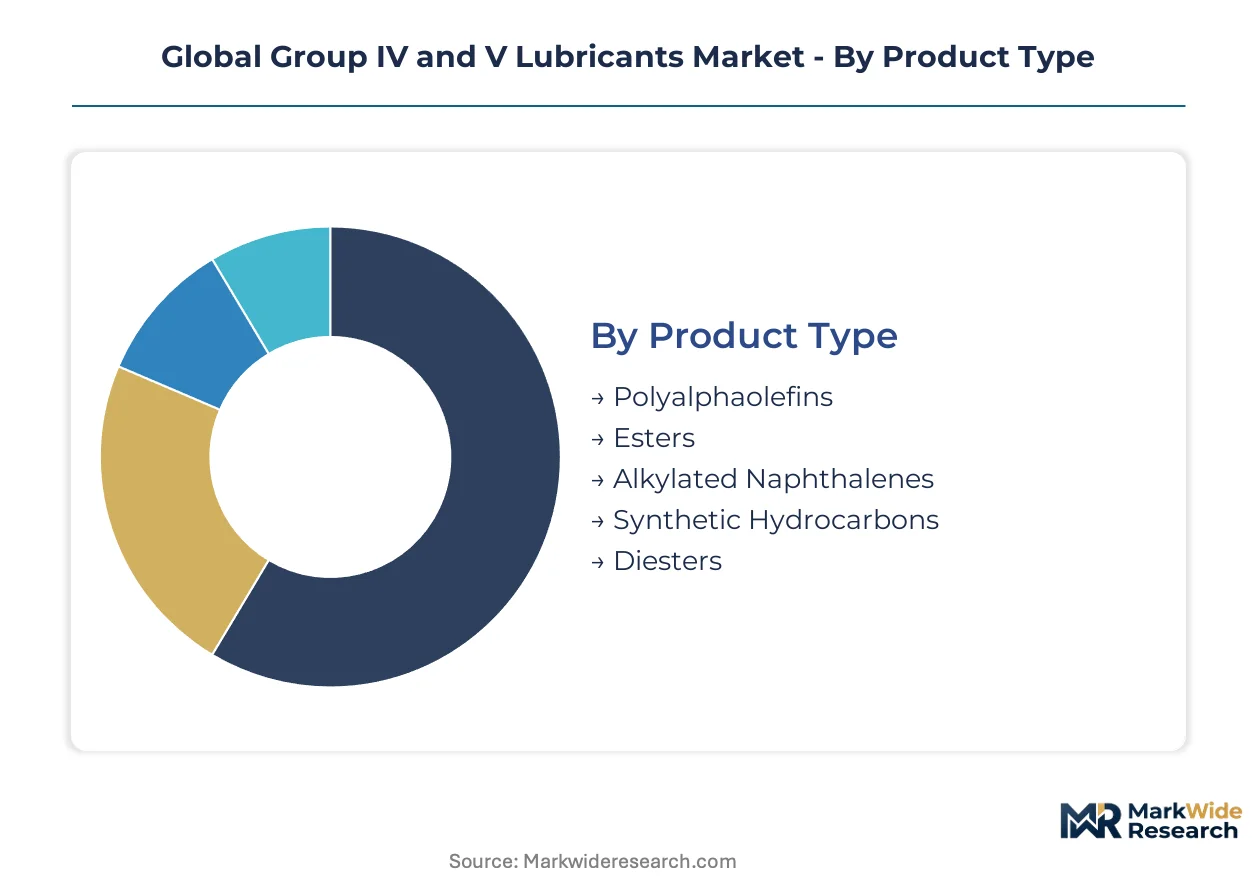
Synthetic lubricant value pools fragment sharply across chemistries and end-use specifications. Each segment carries distinct margin profiles tied to certification requirements, feedstock access, and formulation complexity.
Product Type:
Margin concentration sits with ester formulations for aviation turbine applications, where thermal oxidative stability above 200 degrees Celsius commands premium pricing.
- Polyalphaolefins:Manufactured through oligomerization of alphaolefins using metallocene catalysts. Demand concentrates in Germany's precision manufacturing corridor for automotive OEM supply chains, driven by compatibility with existing mineral-oil infrastructure and DIN 51524 certification requirements.
- Esters:Produced via esterification of organic acids with alcohols, delivering viscosity indices above 130 and pour points below minus forty degrees Celsius. Aerospace turbine engine manufacturers in the United States and Europe procure these formulations to meet tightening FAA and EASA thermal stability specifications.
- Alkylated Naphthalenes:Deliver oxidative stability for high-temperature industrial applications.
- Synthetic Hydrocarbons:Bridge performance gaps between PAOs and mineral oils for cost-sensitive segments.
- Diesters:Serve niche compressor and refrigeration applications with biodegradability advantages.
The dominant share belongs to Polyalphaolefins, while Esters is closing the gap fastest.
Application:
Volume leadership sits with automotive engines, though aviation applications retain the steepest margin expansion trajectory.
- Automotive Engines:Factory-fill specifications from hybrid vehicle manufacturers in Japan specify 0W-8 and 0W-12 low-viscosity grades for thermal efficiency gains. China's SAMR-administered GB 11121 and GB 11122 standards enforce synthetic content minimums for heavy-duty diesel engine oils across domestic manufacturing.
- Industrial Machinery:Germany's precision manufacturing corridor drives uptake of ester-based hydraulic fluids certified to DIN 51524, with Fuchs-affiliated blenders dominating aftermarket supply relationships.
- Aircraft:FAA Airworthiness Directives and EASA Certification Memoranda mandate synthetic lubricant performance for new turbofan architectures.
- Marine Equipment:Faces IMO environmental compliance pressures accelerating synthetic substitution.
- Hydraulic Systems:Condition-based monitoring contracts displace fixed-drain schedules in North American fleet operations.
Automotive Engines holds the volume base, though Aircraft is gaining share fastest.
End User:
Procurement authority is shifting from OEM factory-fill specifications toward fleet operators with telematics-enabled optimization capabilities.
- OEMs:Factory-fill specifications from Japanese and German automotive manufacturers lock in synthetic content minimums for transmission and engine oils, with metallocene-captive suppliers securing multi-year supply agreements.
- Fleet Managers:Represent the steepest expansion trajectory as telematics-enabled oil-drain optimization justifies higher synthetic unit costs through extended service intervals in heavy-duty trucking corridors through Texas and California.
- Heavy Equipment Operators:Drive demand for bulk-container procurement in mining and construction applications.
- Equipment Maintenance Providers:Specifying synthetic formulations for uptime-guarantee contracts.
- Aviation Operators:Mandated procurement under FAA and EASA airworthiness directives.
OEMs retain the dominant specification authority, while Fleet Managers is climbing the fastest.
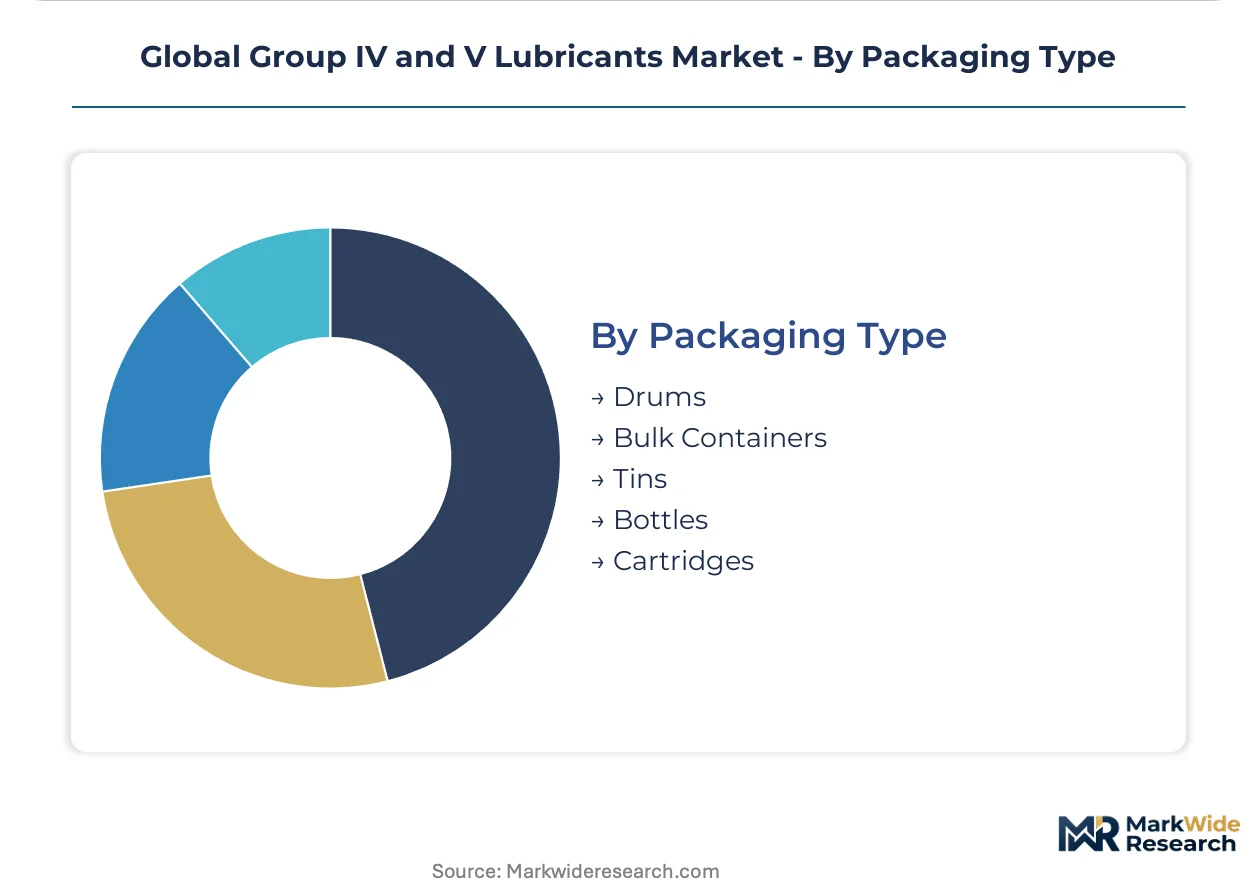
Packaging Type:
Cost structure divergence between bulk and packaged formats mirrors customer scale and inventory turnover requirements.
- Bulk Containers:Serve integrated manufacturing facilities and fleet depots with direct-to-tank delivery, concentrating in Germany's automotive OEM supply chains and Chinese heavy-duty diesel manufacturing plants.
- Drums:Standard format for industrial maintenance providers and mid-scale fleet operators across North American and European distribution networks.
- Bottles:Retail and small-workshop channel in aftermarket automotive applications.
- Tins:Specialty lubricant packaging for aviation and precision instrument applications.
- Cartridges:Pre-measured formats for specific OEM equipment maintenance protocols.
Bulk Containers commands the dominant procurement volume, while Drums remains the most versatile format across geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Group IV and V lubricants trade flows reflect a structural deficit in alphaolefin feedstock capacity outside integrated petrochemical corridors, with import dependence concentrating in precision manufacturing clusters lacking domestic metallocene production.
United States
Aerospace turbine engine manufacturers in Connecticut and Ohio drive ester-based synthetic procurement under tightening FAA airworthiness directives. The EPA's fuel-economy standards shape automotive formulation requirements for hybrid vehicle platforms. The Gulf Coast petrochemical corridor around Baytown, Texas, anchors captive alphaolefin supply for integrated PAO production serving domestic OEM factory-fill specifications.
Germany
Fuchs-affiliated blenders dominate aftermarket supply relationships for ester-based hydraulic fluids certified to DIN 51524 across the precision manufacturing corridor. ECHA REACH substance restrictions compress the approved additive palette for automotive lubricants, forcing reformulation of anti-wear packages. The Baden-Württemberg automotive cluster locks in synthetic content minimums for transmission and engine oils through multi-year OEM supply agreements.
China
SAMR-administered GB 11121 and GB 11122 standards enforce synthetic content minimums for heavy-duty diesel engine oils across domestic manufacturing. The Yangtze River Delta automotive cluster accelerates polyalphaolefin substitution for mineral oils under NMPA-aligned industrial lubricant standards. Shanghai-based blenders face feedstock access constraints from integrated petrochemical complexes controlling alphaolefin supply.
Japan
METI energy-efficiency mandates accelerate low-viscosity PAO grade adoption for hybrid vehicle transmissions, with 0W-8 and 0W-12 specifications gaining factory-fill traction. The Chubu region around Nagoya anchors technology leadership in metallocene-catalyzed oligomerization for domestic OEM supply chains. Idemitsu Kosan secures multi-year agreements with Toyota and Honda for transmission fluid formulations.
India
The PLI scheme for automotive manufacturing creates localized demand for PAO-based transmission fluids as domestic OEMs develop factory-fill specifications. Indian Oil Corporation leverages refining integration to secure feedstock economics for Group IV base stock production. The Tamil Nadu automotive cluster around Chennai concentrates procurement authority for transmission and engine oil formulations serving export-oriented vehicle assembly.
Global Group IV and V Lubricants Market Competitive Landscape
Concentration sits with integrated petrochemical majors possessing captive alphaolefin feedstock and metallocene catalyst capacity. The competitive structure fragments between upstream-integrated refiners, specialty chemical blenders with formulation expertise, and national oil companies leveraging domestic feedstock access. Three archetypes dominate: Gulf Coast-integrated majors with backward control over alphaolefin supply, European formulation specialists serving DIN-certified industrial aftermarket channels, and Asian national champions securing OEM factory-fill relationships through technology licensing. Competitive moves center on metallocene capacity expansion and strategic partnerships for electric drivetrain thermal fluid development.
Among integrated petrochemical majors, ExxonMobil and Royal Dutch Shell exemplify the upstream-integrated archetype with captive feedstock economics. Fuchs occupies a position within the European formulation specialist tier, anchoring aftermarket supply relationships through DIN-certified product portfolios. Idemitsu Kosan represents the Asian national champion model, securing technology leadership in low-viscosity grades for hybrid vehicle specifications.
| Leading Market Players |
|---|
| ExxonMobil |
| Chevron |
| Royal Dutch Shell |
| BP |
| Total |
| Fuchs |
| ConocoPhillips |
| Indian Oil Corporation |
| Idemitsu Kosan |
| Others |
Supply & Pricing Matrix
Forty-five to sixty days of alphaolefin feedstock inventory separates integrated petrochemical majors from independent blenders, concentrating pricing power with Gulf Coast producers while forcing specialty formulators into premium sourcing arrangements.
Pricing Analysis
The customization-premium spread between configured-to-order ester formulations and standard polyalphaolefin grades runs wide, with contract-based long-term offtake dominating aerospace procurement while spot-adjacent pricing prevails in industrial aftermarket channels. Price differentiation stems from certification tier—FAA airworthiness versus DIN 51524 industrial—and volume scale, with fleet managers extracting discounts against OEM factory-fill premiums. Cost compression in standard PAO grades is intensifying because metallocene capacity additions are loosening feedstock scarcity. Fleet managers exhibit highest price sensitivity, while aviation turbine engine manufacturers accept premium positioning for thermal oxidative stability above 200 degrees Celsius.
Supply Chain Analysis
Inbound logistics costs from Rotterdam to Hamburg have tightened margin capture for European blenders lacking captive alphaolefin supply, amplifying disadvantage against integrated majors. Production gravity centers on the United States, Germany, and Japan, with metallocene-catalyzed oligomerization capacity anchoring supply. The chain draws from ethylene-derived alphaolefins, alcohol feedstocks for esterification, and specialty additive packages. Single-source vulnerability concentrates around metallocene catalyst suppliers, where specialized polymerization expertise constrains new entrant scale-up. Distribution runs through direct-to-tank bulk delivery for OEM factory-fill relationships, with drum-format channels serving mid-scale industrial maintenance providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymerization expertise has become the binding constraint, with metallocene catalyst operator scarcity creating defendable moats for legacy alphaolefin producers while locking out capital-rich entrants lacking technical depth.
For Market Incumbents: Shield captive feedstock economics through backward integration into ethylene-alphaolefin complexes, particularly around Baytown and the Gulf Coast corridor. Secure metallocene catalyst supply agreements with technology licensors to preempt emerging entrant access. Prioritize certification investment in FAA airworthiness and EASA compliance to maintain aerospace margin pools against mineral oil substitution threats. For New Entrants and Emerging Players: Anchor in India's PLI-scheme automotive corridor, where domestic OEM factory-fill specifications for PAO-based transmission fluids remain underpenetrated by established majors. Target condition-based monitoring contract channels in North American fleet operations, where telematics-enabled oil-drain optimization creates service-layer differentiation beyond base stock supply. Pursue joint venture structures with Indian Oil Corporation to leverage refining integration for feedstock access. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because metallocene capacity scarcity and regulatory certification burdens favor scale economics over fragmentation. Acquisition targets should display European formulation expertise with DIN-certified industrial aftermarket positions or Asian technology licensing relationships for low-viscosity hybrid vehicle grades. Monitor electric drivetrain thermal fluid specification divergence as the inflection signal—proprietary dielectric formulations for battery cooling systems will reshape competitive boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Metallocene Capacity Expansion | Captive alphaolefin production secures cost position against integrated majors in Germany and Texas. |
| Backward Integration into Feedstock | Ethylene-alphaolefin complex control eliminates supply vulnerability for European ester blenders. |
| Certification Investment in Aviation | FAA airworthiness and EASA compliance lock in aerospace turbine engine manufacturer procurement. |
| Joint Venture for Electric Thermal Fluids | Dielectric formulation partnerships with battery OEMs preempt specification divergence risks. |
| Condition-Based Monitoring Service Layer | Telematics integration with fleet managers creates pricing power beyond commodity base stocks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at alphaolefin production facilities, procurement leads at automotive OEMs, distribution channel partners in European industrial aftermarket networks, and technical R&D directors at specialty blenders; alongside secondary validation through customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings from integrated petrochemical majors, and FAA airworthiness directive databases. Bottom-up triangulation against top-down production capacity estimates ensured convergence on volume and value outputs.
Across the analysis window, the forecasting framework modeled demand through segmentation across chemistry type, application specification, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from production capacity expansion schedules, OEM factory-fill specification timelines, and fleet telematics penetration curves. Industry-specific inputs included metallocene catalyst deployment rates, REACH substance restriction implementation phases, and electric vehicle thermal management fluid development milestones.
Underlying assumptions cover regulatory enforcement continuity for FAA, EASA, and SAMR standards, with deviation risk concentrated in electric drivetrain penetration speed and alphaolefin feedstock price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
China Automotive Engine Oils Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
High Performance Lubricants Market
Lubricants
Mexico Lubricants Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Global Finished Lubricant Market
Lubricants
Construction Lubricants Market
Lubricants
South Korea Commercial Vehicles Lubricants Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Global Independent Lubricant Manufacturers Market
Lubricants
Egypt Lubricants Market