
 Europe Metal Finishing Market | 2026-2036
Europe Metal Finishing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Metal Finishing Market Foresight
Multi-source outsourcing among tier-one automotive suppliers is hardening across Central Europe. Henkel AG & Co. KGaA leverages its adhesive and surface treatment portfolio to anchor long-term supply agreements with German OEMs. OC Oerlikon Management AG competes through PVD coating specialization for aerospace turbine blades. Chemetall GmbH dominates pretreatment chemistry for aluminum automotive body panels, sustaining formulation leadership through in-house R&D.
Europe metal finishing encompasses electrochemical, mechanical, thermal, and hybrid processes that deposit or modify surface layers to achieve specified thickness, hardness, or conductivity parameters on metal substrates. The primary purpose is to extend component service life in corrosive or high-wear environments while meeting functional specifications for electrical contact or thermal management. Electroplating remains the largest process category by installed capacity, though powder coating generates superior margin pools in architectural and appliance applications where VOC restrictions under EU directives tighten compliance costs for liquid alternatives. Chrome plating faces structural decline as REACH authorization requirements elevate operating costs and accelerate substitution toward trivalent formulations and PVD alternatives.
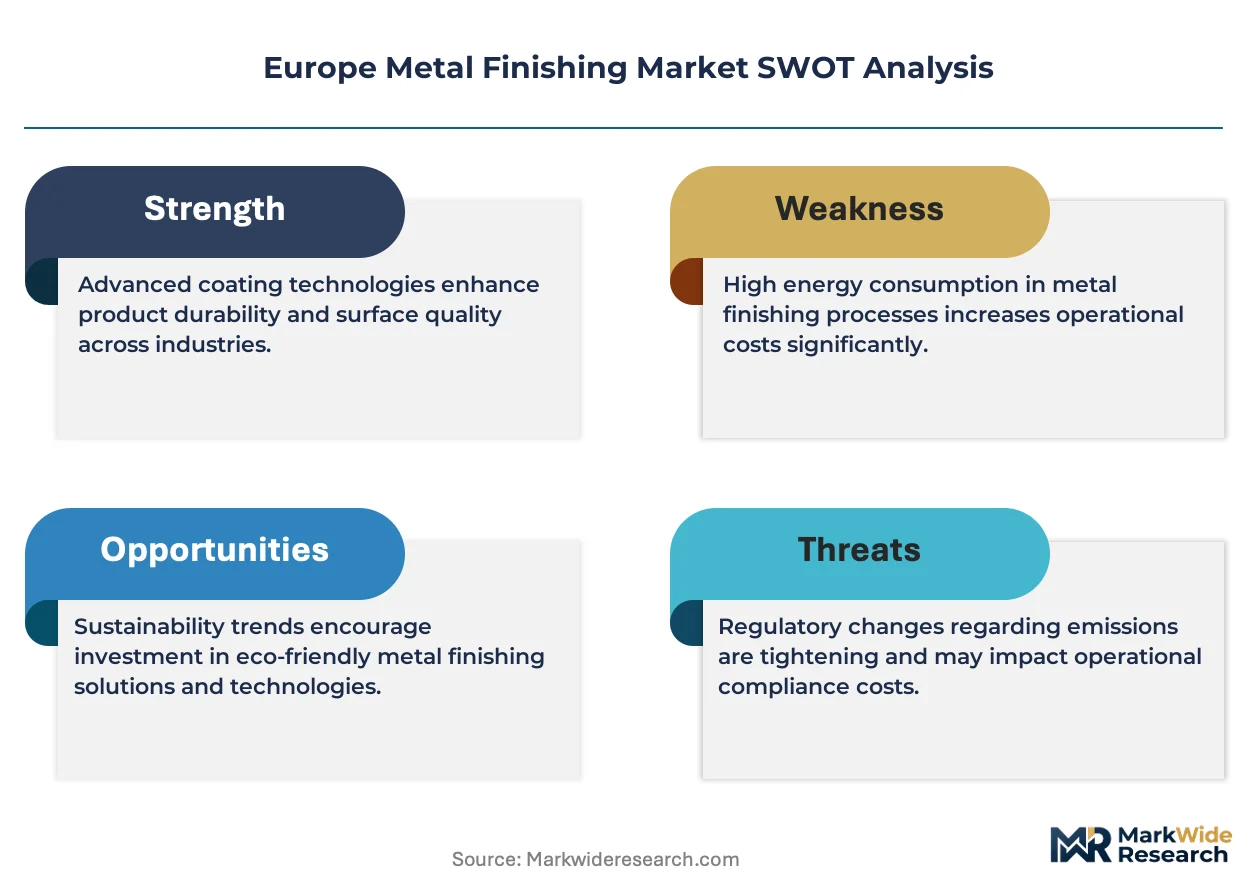
REACH, the EU F-Gas Regulation, and CE marking collectively reshape product formulation, process emissions, and market access across European metal finishing operations. ECHA substance authorization procedures force reformulation of hexavalent chromium and certain nickel compounds, redirecting R&D expenditure toward compliant chemistries. Stakeholders must monitor regulatory divergence between EU harmonized standards and emerging national restrictions in member states, as this fragmentation determines competitive positioning in cross-border supply contracts.
Market Dynamics
REACH authorization timelines and the EU F-Gas Regulation are forcing wholesale process reconfiguration across European metal finishing operations, compressing the viable technology set and redrawing supplier relationships.
Growth Catalysts
- REACH-driven chemistry reformulation:ECHA substance authorization procedures for hexavalent chromium compounds are redirecting R&D expenditure toward compliant trivalent alternatives, creating first-mover advantages for formulation specialists.
- Automotive lightweighting:Aluminum-intensive vehicle architectures in Germany and France require expanded pretreatment and coating capacity for body-in-white applications.
- Eastern European manufacturing concentration:Industrial park incentives in Poland and the Czech Republic are attracting tier-one suppliers seeking integrated surface treatment clusters.
Market Restraints
- Input cost volatility:Nickel and cobalt compound prices fluctuate with battery sector demand, squeezing electroplating margin structures.
- Supply concentration risk:Specialty chemical formulation for aerospace PVD coatings depends on a limited German and Swiss supplier base.
- Technical limitation:Trivalent chromium formulations still fail to match hexavalent salt-spray performance in heavy-duty corrosion applications.
Strategic Opportunities
- Underpenetrated geography:Romania and Bulgaria offer greenfield expansion potential as automotive supply chains extend into lower-cost EU member states.
- Regulatory tailwind:The EU Green Deal's circular economy requirements favor powder coating recovery and reuse systems over liquid alternatives.
- Technology convergence:Hybrid PVD-chemical coating processes are opening performance specifications previously unattainable with single-method approaches.
Industry Challenges
- Specialized technician scarcity:Electroplating bath chemistry management and PVD chamber operation require skills with limited vocational training pipelines.
- Capex intensity:Emission control upgrades for existing wet process lines demand substantial capital outlay with extended payback periods.
- Certification timeline compression:CE marking conformity assessment for new coating chemistries faces extended ECHA consultation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Metal Finishing Market |
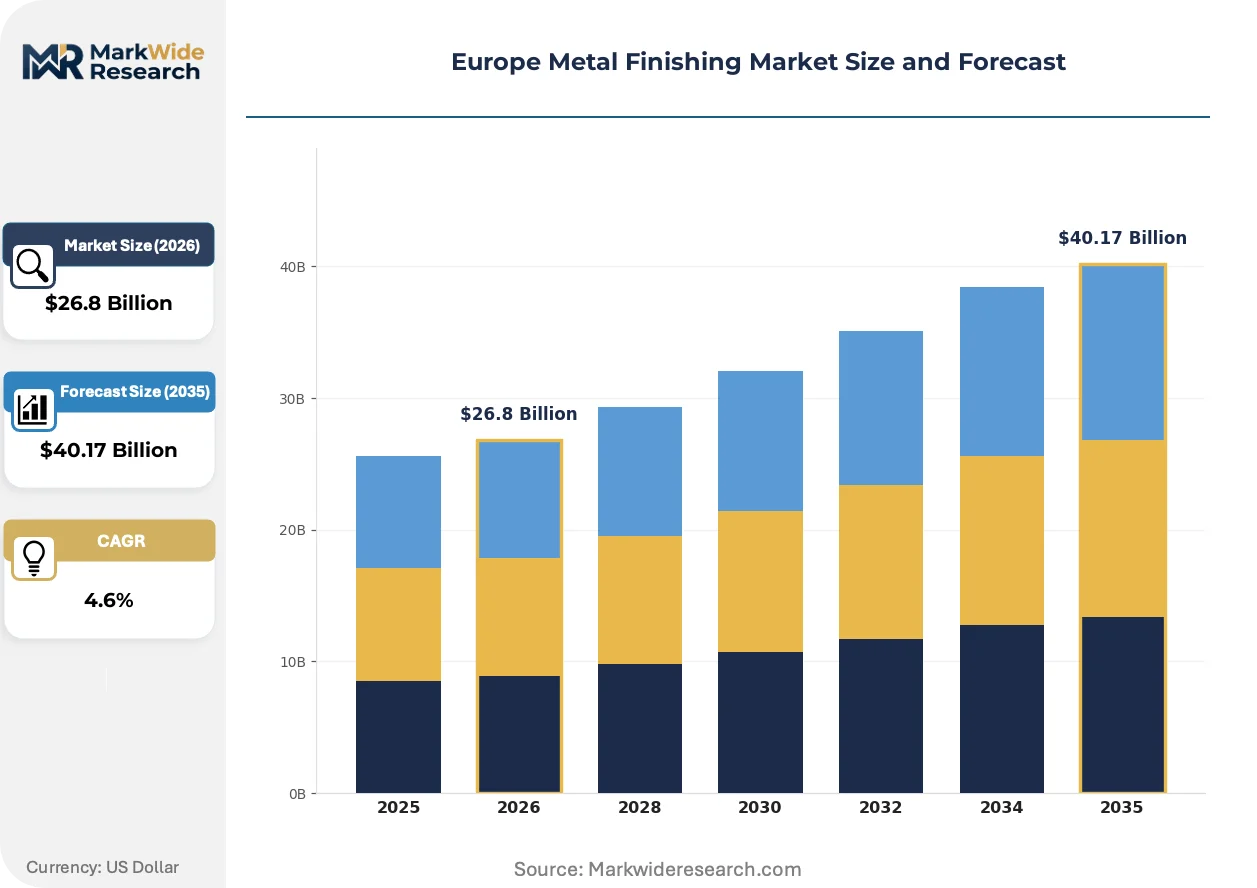
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $40.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroplating, Anodizing, Powder Coating, Chrome Plating End User: Aerospace, Automotive, Consumer Electronics, Industrial Equipment Technology: Electrochemical, Mechanical, Hybrid, Thermal Application: Corrosion Resistance, Aesthetic Enhancement, Wear Resistance, Electrical Conductivity |
| Companies Covered | Honeywell International Inc., Linde plc, OC Oerlikon Management AG, Atotech, Elementis PLC, TIB Chemicals AG, Henkel AG & Co. KGaA, Chemetall GmbH, POSCO, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Metal Finishing Market Shifts & Advancements
Process substitution and chemistry reformulation are converging to reshape the European metal finishing landscape, with regulatory pressure acting as the primary accelerant rather than end-user pull.
PVD coating technology for turbine blade thermal barrier applications is absorbing volume previously served by plasma-sprayed ceramics and electroplated overlays. Aerospace OEMs in France and the UK are qualifying these processes for next-generation engine programs. The shift is compressing demand for traditional high-temperature electroplating capacity while expanding vacuum equipment installation requirements.
ECHA's authorization requirements under REACH Annex XIV are eliminating hexavalent chromium from automotive decorative trim and functional hardware applications by specified sunset dates. German and Italian coating houses face facility reconfiguration or closure decisions. The affected segments are accelerating trivalent process validation and exploring physical vapor deposition alternatives for critical corrosion specifications.
Consolidated procurement through automotive platform engineering teams is displacing fragmented supplier selection at individual plant level. Tier-one suppliers in Central Europe now negotiate master service agreements covering multiple OEM programs. This concentration is most visible in Germany, where Volkswagen Group and BMW procurement organizations have reduced their approved surface treatment vendor lists by over half since 2020.
Europe Metal Finishing Market Segmentation
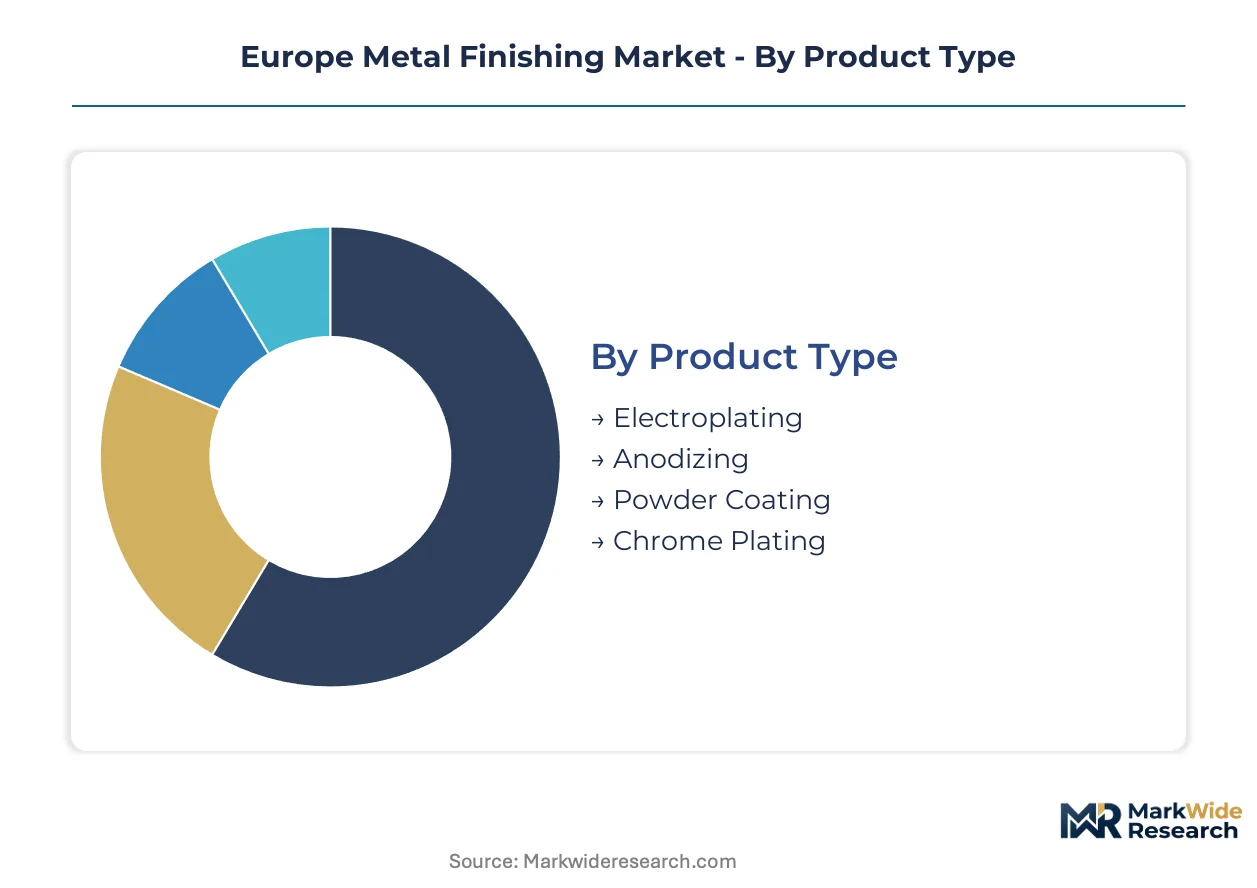
Metal finishing processes serve distinct functional requirements across European manufacturing. Process selection depends on substrate compatibility, regulatory constraints, and end-use performance specifications. Each segmentation dimension reveals different competitive dynamics and margin structures.
Product Type:
Supply concentration varies sharply across process categories, with powder coating capacity consolidating faster than wet chemistry operations.
- Electroplating:Electrochemical deposition of metallic coatings from aqueous solutions delivers precise thickness control and conductivity. German automotive suppliers in Stuttgart and Wolfsburg drive demand for nickel and zinc-nickel formulations as OEMs outsource surface treatment to REACH-compliant specialists.
- Powder Coating:Thermoset polymer application via electrostatic spray achieves zero-VOC compliance under EU directives. Industrial parks in Poland and the Czech Republic concentrate new capacity serving appliance and architectural metal fabricators seeking integrated finishing clusters.
- Anodizing:Electrochemical oxide formation on aluminum substrates creates hard, corrosion-resistant surfaces. Aerospace fastener manufacturers in France specify sulfuric acid processes for airframe components.
- Chrome Plating:Decorative and functional chromium deposition faces structural contraction as ECHA authorization deadlines eliminate hexavalent formulations. Italian decorative hardware producers accelerate trivalent process conversion.
Today's leader: Electroplating. Tomorrow's challenger: Powder Coating.
End User:
Customer concentration patterns reflect procurement centralization trends across European manufacturing.
- Automotive:Body-in-white pretreatment and decorative trim finishing absorb the largest process volumes. Volkswagen Group and BMW procurement organizations have consolidated approved vendor lists, compressing supplier counts across German supply chains.
- Aerospace:Turbine blade thermal barrier coatings and landing gear corrosion protection demand certified process traceability. Rolls-Royce and Safran qualification programs in the UK and France drive PVD technology adoption.
- Consumer Electronics:Precision decorative finishing for handheld devices requires thin-film deposition capabilities. Connector manufacturers specify gold and palladium-nickel plating for signal integrity.
- Industrial Equipment:Heavy machinery and agricultural equipment use zinc and alloy coatings for outdoor durability. German and Italian manufacturers source from regional job shops with ISO certification.
Automotive commands current volume. Aerospace offers the steepest expansion trajectory through engine program qualification cycles.
Technology:
Process technology selection increasingly reflects regulatory compliance economics rather than pure performance optimization.
- Electrochemical:Aqueous bath processes including electroplating, anodizing, and electroless deposition dominate installed European capacity. REACH-driven chemistry reformulation absorbs R&D expenditure across German and French formulation houses.
- Thermal:Plasma spraying and hot-dip galvanizing serve heavy corrosion specifications in infrastructure and construction applications. Bridge and highway component specifications in France and Germany sustain demand.
- Mechanical:Shot peening, polishing, and mass finishing prepare surfaces for subsequent coating or improve fatigue resistance. Automotive powertrain suppliers in Spain and Italy employ these processes for crankshaft and camshaft treatment.
- Hybrid:Combined PVD-chemical processes achieve performance specifications unattainable with single methods. Aerospace fastener manufacturers in the UK pilot these systems for next-generation engine programs.
Electrochemical processes retain scale advantages. Hybrid systems are gaining share fastest in premium specification segments.
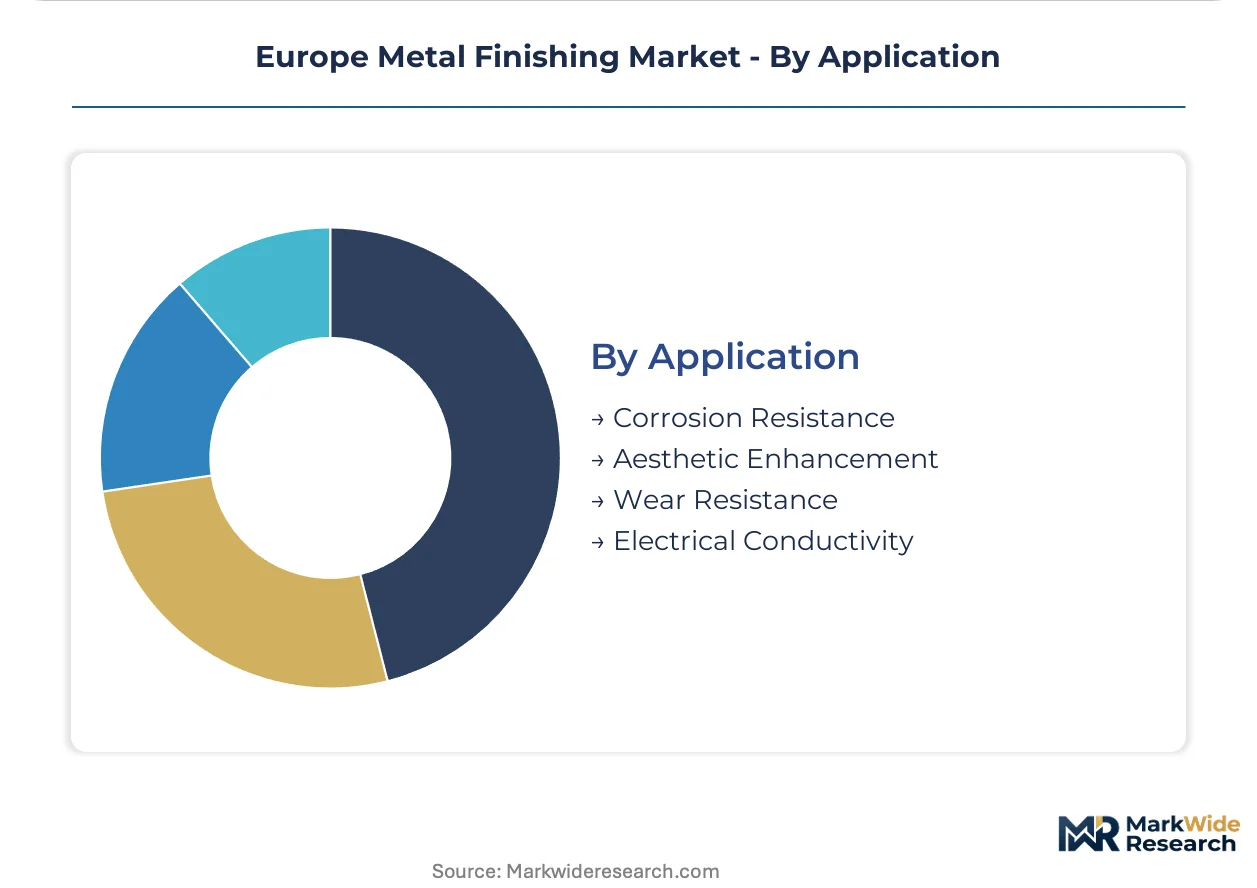
Application:
Functional requirement segmentation determines pricing power and formulation complexity across customer contracts.
- Corrosion Resistance:Salt spray and cyclic corrosion specifications drive coating selection for automotive underbody and aerospace landing gear. ECHA restrictions on hexavalent chromium force reformulation toward trivalent and PVD alternatives.
- Wear Resistance:Hard chrome and diamond-like carbon coatings extend component life in hydraulic cylinders and cutting tools. Machine tool manufacturers in Germany specify these finishes for precision guides.
- Aesthetic Enhancement:Decorative chrome, nickel, and PVD color finishes serve consumer-facing automotive trim and hardware applications. Italian faucet and fixture producers drive demand for durable decorative specifications.
- Electrical Conductivity:Precious metal plating ensures low-contact resistance in connectors and switchgear. Telecom infrastructure suppliers in France and Germany specify silver and gold deposits.
Corrosion resistance anchors volume. Electrical conductivity offers premium margin structures in precision electronic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters in Stuttgart and Wolfsburg anchor European metal finishing demand. REACH compliance costs and OEM outsourcing contracts are redrawing supplier geography across the continent.
Germany
Volkswagen Group and BMW procurement teams have halved approved surface treatment vendors since 2020. ECHA authorization deadlines for hexavalent chromium force Stuttgart plating houses toward trivalent conversion or closure. Wolfsburg suppliers now operate under consolidated master service agreements covering multiple OEM programs.
France
Rolls-Royce and Safran engine qualification cycles are absorbing PVD coating capacity for turbine blade thermal barriers. The EU F-Gas Regulation pressures Paris-region job shops to abandon older wet chemistry lines. Lyon aerospace fastener manufacturers pilot hybrid PVD-chemical processes for next-generation airframe specifications.
Poland
Industrial park incentives in Silesia and Greater Poland attract tier-one automotive suppliers seeking integrated finishing clusters. CE marking requirements for exported components concentrate compliance expertise in Warsaw and Krakow service hubs. Poznan hosts expanding powder coating capacity serving appliance manufacturers.
Czech Republic
Automotive supply chain extension from Germany drives pretreatment demand for aluminum body-in-white applications. The EU Green Deal's circular economy requirements favor Moravian powder coating recovery systems over liquid alternatives. Brno engineering centers develop REACH-compliant formulation substitutes for hexavalent processes.
Italy
Decorative hardware producers in Lombardy and Veneto accelerate trivalent chromium conversion ahead of ECHA sunset dates. Turin automotive trim suppliers face facility reconfiguration decisions as REACH authorization costs render electroplating uneconomical. Bologna coating houses explore PVD alternatives for critical corrosion specifications.
Europe Metal Finishing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid process specialization and geographic white-space expansion. The vendor base organizes around three strategic archetypes: diversified chemical conglomerates with formulation depth, specialized PVD equipment and coating houses, and regional job shops with OEM qualification heritage. Competitive moves concentrate on M&A for REACH-compliant capacity and strategic partnerships for automotive platform engineering access.
Among diversified chemical specialists, Henkel AG & Co. KGaA and Chemetall GmbH exemplify formulation-led positioning anchored in German automotive supply relationships. OC Oerlikon Management AG occupies a position within the PVD specialization tier, representing vacuum coating technology convergence for aerospace and industrial applications. These three entities illustrate the competitive structure: chemical formulation leadership, physical vapor deposition expertise, and integrated surface treatment portfolios each command distinct customer access pathways.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Linde plc |
| OC Oerlikon Management AG |
| Atotech |
| Elementis PLC |
| TIB Chemicals AG |
| Henkel AG & Co. KGaA |
| Chemetall GmbH |
| POSCO |
| Others |
Supply & Pricing Matrix
Trivalent chromium conversion across German and Italian plating houses compresses process economics while redrawing supplier geography toward REACH-compliant specialists with captive formulation capabilities. Powder coating capacity expansion in Polish industrial parks exploits lower operating costs and EU Green Deal incentives, creating price arbitrage against wet chemistry alternatives in Western Europe.
Pricing Analysis
Input-cost pass-through from nickel and cobalt compound volatility squeezes electroplating margin structures, particularly for job shops serving automotive underbody specifications. Three-tier pricing structure across aerospace-certified, automotive-qualified, and general industrial tiers reflects certification investment recovery and volume scale economics. Pricing pressure stems from battery sector demand competing for specialty metal salts. General industrial job shops exhibit highest price sensitivity; aerospace PVD coating houses command premium stability through long-term engine program contracts.
Supply Chain Analysis
Workforce-availability constraints in Stuttgart and Wolfsburg plating clusters force capacity relocation toward Silesia and Greater Poland industrial parks. Specialty chemical formulation draws from a concentrated German and Swiss supplier base for aerospace PVD precursors. Single-source vulnerability runs through hexavalent chromium authorization deadlines forcing process conversion. Distribution runs through tier-one automotive master service agreements consolidating procurement across multiple OEM programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Western European REACH compliance costs and Eastern European industrial park incentives defines competitive positioning. German OEM outsourcing contracts favor suppliers with integrated Central European footprints over standalone Western facilities.
For Market Incumbents: Anchor market position through backward integration into trivalent chromium formulation and PVD equipment captive supply. Consolidate REACH-compliant capacity acquisitions in Poland and Czech Republic before greenfield scarcity elevates entry costs. Defend against emerging hybrid-process specialists by accelerating automotive platform engineering team qualification cycles. For New Entrants and Emerging Players: Enter via Romania and Bulgaria automotive supply chain extension, the most penetrable geography with limited incumbent pretreatment capacity. Target powder coating recovery and reuse systems serving EU Green Deal circular economy requirements. Pursue joint development agreements with Lyon aerospace fastener manufacturers piloting hybrid PVD-chemical specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among regional Italian decorative hardware job shops facing ECHA sunset date reconfiguration costs. Long-term viability centers on formulation R&D depth and automotive OEM qualification heritage rather than installed wet process capacity. Monitor ECHA authorization timeline acceleration as inflection signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trivalent Formulation | Chemetall GmbH and Henkel AG sustain margin defense through captive chemistry R&D against raw material volatility. |
| Capacity Expansion in Polish Industrial Parks | Tier-one suppliers exploit Silesia incentives to serve Volkswagen Group consolidated procurement organizations. |
| Long-term Supply Agreement with Aerospace OEMs | OC Oerlikon Management AG anchors PVD coating revenue through Rolls-Royce and Safran engine qualification cycles. |
| Joint Venture for Hybrid Process Development | UK aerospace fastener manufacturers pilot PVD-chemical convergence for next-generation thermal barrier specifications. |
| Green Manufacturing Transition to Powder Coating | Moravian recovery systems align with EU Green Deal circular economy requirements versus liquid alternative compliance costs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plating house operations managers, automotive Tier 1 procurement leads, aerospace coating qualification engineers, and specialty chemical R&D directors with secondary validation. Trade data from Eurostat and Cefic chemical industry reports, ECHA substance authorization databases, and SEC filings from listed coating equipment manufacturers anchored supply-side sizing. Bottom-up facility capacity counts and top-down end-use consumption estimates triangulated market segmentation.
Comparable-period anchoring linked forward projections to historical electroplating and powder coating capacity installation patterns across the analysis window. Segmentation modeling incorporated process technology type, end-use industry vertical, substrate material class, and regional regulatory cluster dimensions. CAGRs derived from installed capacity expansion schedules and OEM outsourcing contract visibility. Forecast inputs included ECHA authorization timeline assumptions and automotive lightweighting aluminum intensity trajectories.
Inputs from ECHA consultation databases and automotive platform engineering disclosures were available through the study window; gaps in privately held job shop financial performance introduce uncertainty bands around margin structure estimates. Forecasts reflect documented assumptions regarding REACH enforcement consistency and F-Gas Regulation implementation pace. Practitioners should monitor ECHA sunset date acceleration and battery sector nickel demand spikes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Surface Protection Films Market
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Marine Deck Coatings Market
Coatings
Bio-Fouling Prevention Coatings Market
Coatings
Yacht Coatings Market
Coatings
BPA-Free Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Silicate Coatings Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Qatar Protective Coatings Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Global Hydrophobic Coating Market
Coatings
South Africa Automotive OEM Coatings Market