
 Japan Automotive OEM Coatings Market | 2026-2036
Japan Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive OEM Coatings Market Foresight
Software-defined color customization and digital tint-matching services is pivoting how Japanese OEMs contract coating supply, shifting procurement from bulk resin orders to per-vehicle digital color recipes. Kansai Paint Co., Ltd. leverages its domestic R&D campus in Osaka to anchor development of low-temperature cure systems for aluminum-intensive vehicle architectures. PPG Industries Inc. competes through its technical service centers in Yokohama and Nagoya, sustaining direct engineer-to-plant relationships with major Japanese assemblers.
Japan Automotive OEM Coatings comprise solvent-borne, water-borne, and powder formulations applied to vehicle bodies during original manufacture, typically requiring 4-5 mil dry film thickness for exterior basecoat-clearcoat systems to achieve gloss retention and chip resistance over a 10-year warranty life. Basecoat formulations dominate value capture due to pigment complexity and color-matching precision requirements, while clearcoat segments carry premium margins driven by scratch-healing and self-cleaning additive integration. Primer demand is accelerating fastest among structural segments as OEMs adopt multi-substrate body-in-white designs requiring adhesion promoters for aluminum, carbon fiber, and high-strength steel combinations.
METI enforces industrial VOC emission standards under the Air Pollution Control Act, compelling paint shops to adopt water-borne basecoats or invest in thermal oxidizer retrofitting. JIS K 5600 series standards govern coating performance testing for weatherability and adhesion, creating compliance barriers for non-domestic suppliers without certified local laboratories. Stakeholders must monitor METI's evolving carbon-neutrality roadmaps for manufacturing, as anticipated process energy regulations will reshape cure-oven technology investments and coating chemistry selection criteria.
Market Dynamics
Japan's automotive OEM coatings sector is undergoing a fundamental restructuring as METI's VOC emission ceilings force paint shops to choose between water-borne chemistry conversion and capital-intensive thermal oxidizer retrofits, compressing operating margins while accelerating supplier consolidation.
Growth Catalysts
- Aluminum-intensive architectures:Multi-material body-in-white designs are expanding primer demand for adhesion promoters across high-strength steel and carbon fiber combinations. Japanese OEMs specify these systems for weight reduction targets.
- Electric vehicle thermal management:Battery substrate coatings now require specialized formulations for heat dissipation. Manufacturing lines in Aichi Prefecture are expanding coating specifications to manage these substrates.
- METI carbon-neutrality roadmaps:Anticipated process energy regulations are driving cure-oven technology investments. Paint shops are pre-positioning for compliance with stricter manufacturing emissions standards.
Market Restraints
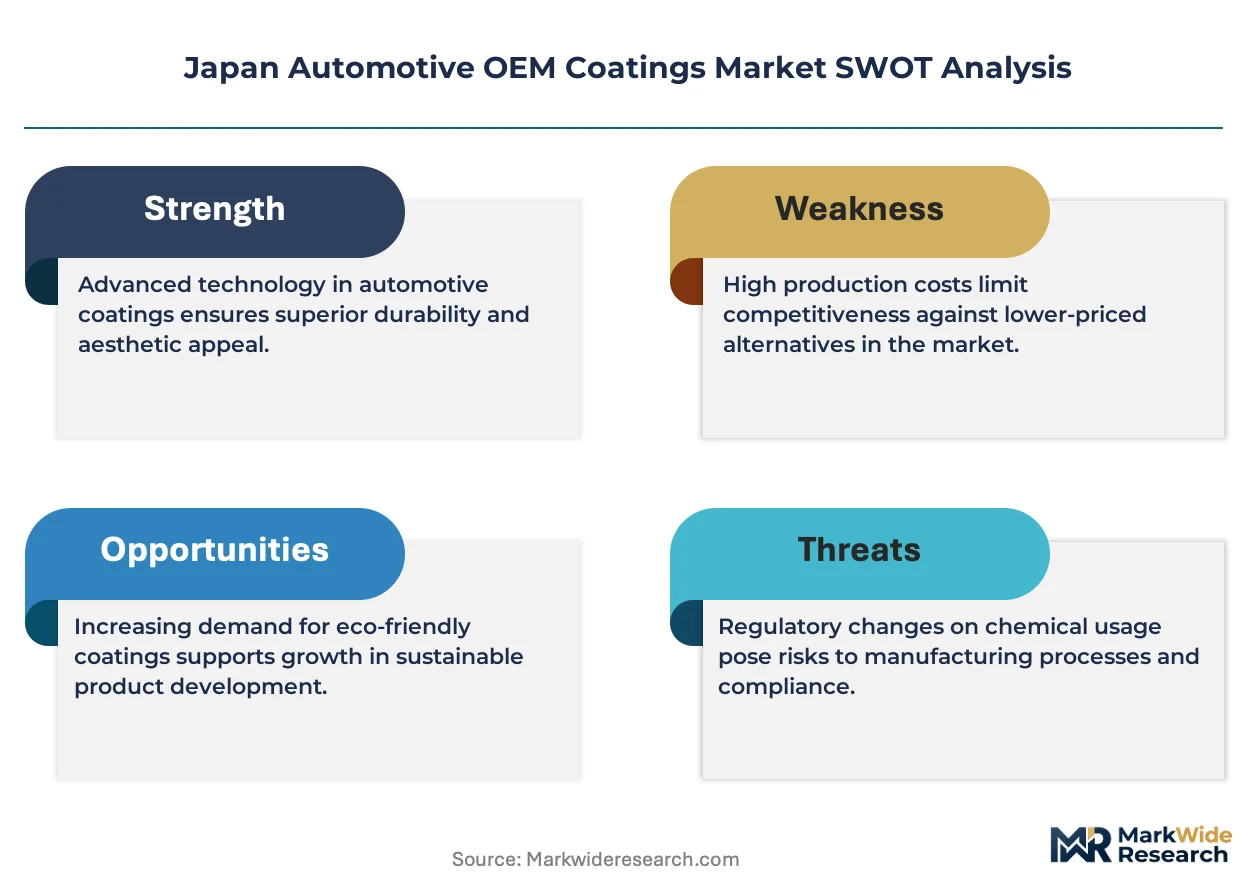
- Epoxy resin supply volatility:Petrochemical feedstock fluctuations create input cost instability for clearcoat formulations. Formulators face margin compression during crude price spikes.
- Domestic supplier concentration:Aichi Prefecture's geographic clustering of coating demand creates single-region exposure. Disruptions to the Toyota City-Nagoya corridor ripple through procurement schedules.
- JIS K 5600 certification barriers:Weatherability and adhesion testing requirements lock out non-domestic suppliers without certified local laboratories. Foreign entrants face 18-24 month approval timelines.
Strategic Opportunities
- Kansai region R&D anchoring:Osaka-based development campuses can serve aluminum-intensive vehicle programs. Low-temperature cure systems address multi-substrate adhesion requirements.
- Software-defined color recipes:Digital tint-matching services enable per-vehicle procurement models. Bulk resin orders are giving way to recipe-based contracting with Japanese OEMs.
- Self-healing clearcoat additives:Scratch-recovery and self-cleaning functionalities command premium positioning. Integration of these chemistries differentiates supplier offerings.
Industry Challenges
- Paint shop engineer shortages:Thermal oxidizer operation and water-borne process control require specialized technician training. Vocational pipelines have not kept pace with technology turnover.
- Legacy solvent-borne asset stranding:Existing spray booth infrastructure faces accelerated depreciation. Retrofit capex competes with new water-borne line investments for limited capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive OEM Coatings Market |
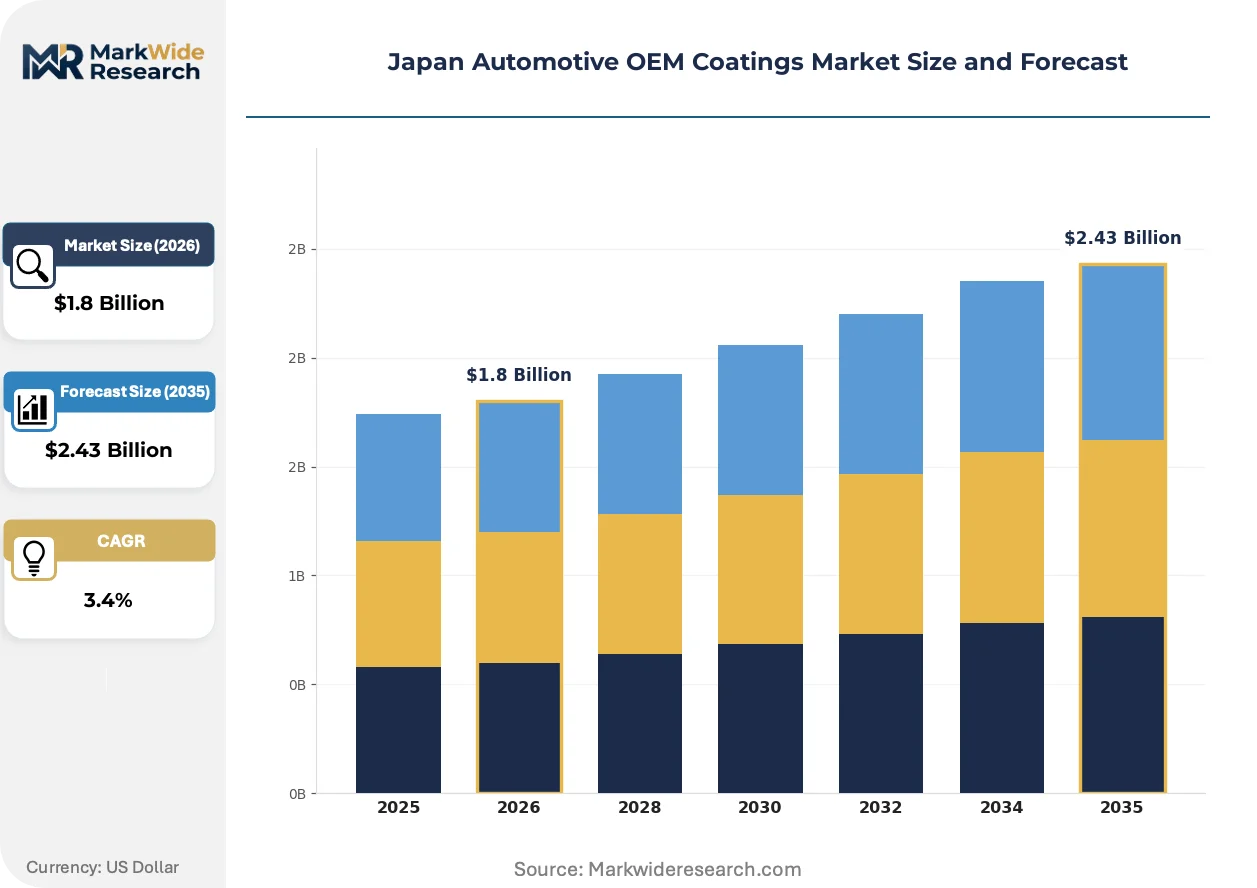
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Basecoat, Clearcoat, Primer, Undercoat Application Method: Spray, Roller, Dip, Brush Vehicle Segment: SUV, Sedan, Hatchback, Coupe Supplier Type: Tier-1 Suppliers, Independent Manufacturers, Distributors, Others |
| Companies Covered | Axalta Coating Systems, BASF SE, Nippon Paint Holdings Co., Ltd., PPG Industries Inc., Kansai Paint Co., Ltd., AkzoNobel N.V., The Sherwin-Williams Company, Beckers Group, Jotun, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive OEM Coatings Market Shifts & Advancements
Digital color specification platforms are rewriting procurement relationships between Japanese OEMs and coating suppliers. Three convergent developments are compressing traditional supply arrangements.
Low-temperature cure chemistry is decentralizing the thermal requirements of automotive paint shops. These systems reduce oven energy consumption by enabling cure cycles below 140°C. Tier-1 suppliers serving aluminum-intensive platforms are adopting these formulations fastest. The technology is decentralizing capital allocation away from centralized high-temperature oven infrastructure toward distributed, lower-energy process lines.
METI's Air Pollution Control Act enforcement is mandating VOC emission reductions across automotive paint operations. Industrial facilities must now meet tightened ceilings or face operational penalties. Water-borne basecoat segments are absorbing the compliance investment, while solvent-borne shops delay thermal oxidizer decisions.
Buyer concentration around Aichi Prefecture OEM clusters is compressing supplier negotiation leverage. Tier-1 coating vendors now maintain technical service centers in Yokohama and Nagoya to sustain direct engineer-to-plant relationships. This geographic buyer concentration is most visible in basecoat procurement, where color-matching precision requirements lock in long-term supply contracts.
Japan Automotive OEM Coatings Market Segmentation
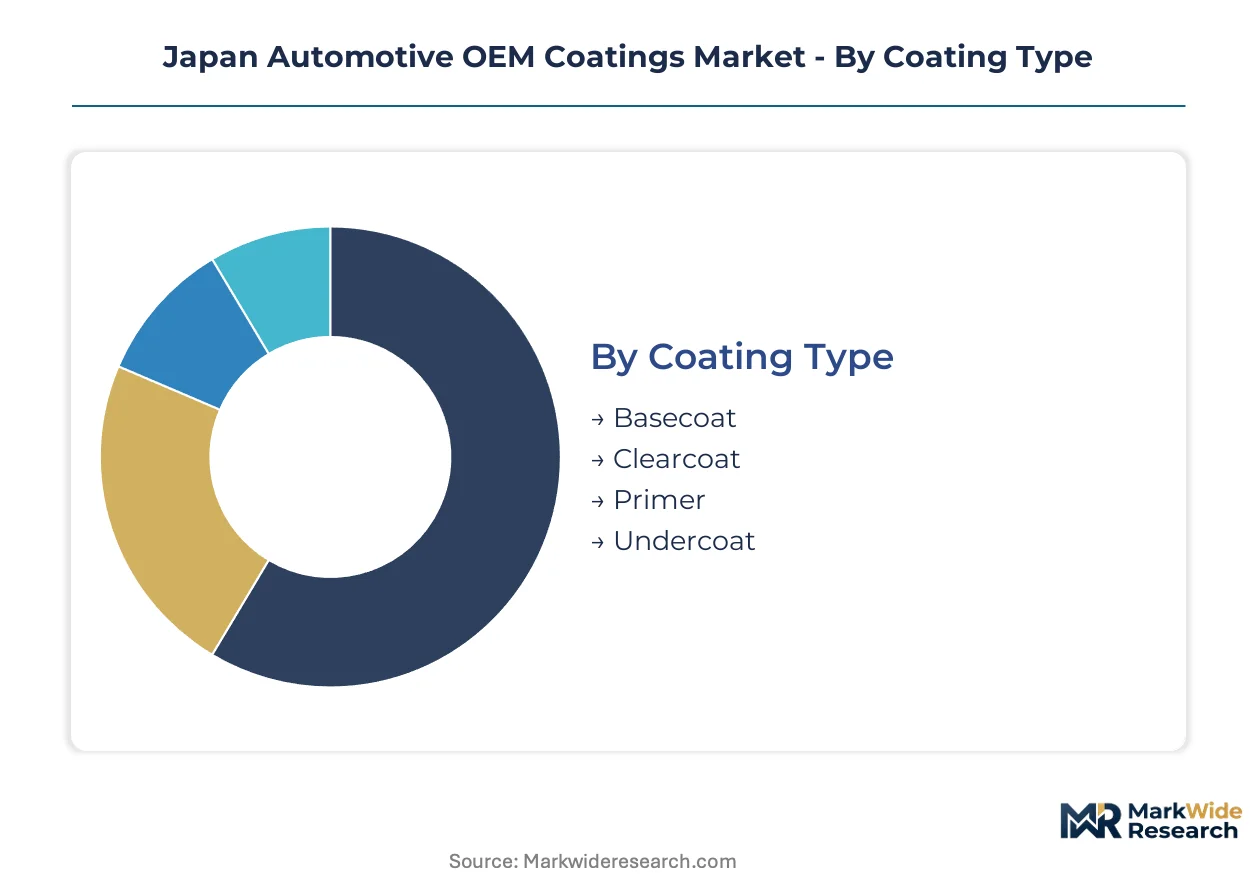
Coating formulations in Japan's automotive OEM sector fragment across chemistry types, application equipment, vehicle architectures, and supply chain tiers. Each segmentation axis reveals distinct margin structures and technical barriers that shape procurement relationships with Aichi Prefecture assemblers.
Coating Type:
Standalone film layers dominate exterior finishing sequences, while embedded functional coatings integrate directly into substrate manufacturing.
- Basecoat:Pigment-dispersed resin systems deliver color saturation and UV stability through 4-5 mil dry film specifications. Toyota City assembly plants specify these formulations for their color-matching precision requirements, though per-vehicle digital recipe procurement is compressing bulk order volumes.
- Clearcoat:Acrylic-urethane top layers incorporate scratch-healing additives and self-cleaning functionalities for 10-year warranty performance. Premium positioning in this segment reflects integration of advanced additive chemistries demanded by Nagoya-area OEM technical centers.
- Primer:Adhesion promoters for multi-substrate body-in-white designs.
- Undercoat:Corrosion-resistant base layers applied prior to body assembly.
Volume placements concentrate in Basecoat; the faster expansion belongs to Primer.
Application Method:
Capital intensity and line throughput rates separate automated processes from manual touch-up operations.
- Spray:Electrostatic rotary atomizers achieve transfer efficiency above 85% in high-volume paint shops. METI VOC emission ceilings are accelerating conversion from solvent-borne to water-borne spray systems across Aichi Prefecture facilities.
- Dip:Electrodeposition tanks provide uniform coverage for complex body-in-white geometries. The technology serves corrosion protection requirements for aluminum-intensive architectures emerging from Osaka-based R&D programs.
- Roller:Limited deployment for flat panel interior substrates.
- Brush:Restricted to repair and prototype applications.
Throughput dominance sits with Spray; Dip lines are gaining share fastest on multi-material vehicle platforms.
Vehicle Segment:
Coating specification complexity scales with body panel area and surface curvature requirements.
- SUV:Expanded surface areas and roof rack mounting zones demand enhanced chip resistance in lower body sections. Higher ground clearances expose these vehicles to gravel impact, driving specification of thicker primer systems at Toyota City and Nagoya assembly plants.
- Sedan:Streamlined panel geometries enable optimized transfer efficiency in automated spray lines. The segment retains volume concentration in domestic Japanese production, though coating thickness specifications are standardizing downward.
- Hatchback:Rear door integration creates complex curvature coating challenges.
- Coupe:Low-volume specialty finishing with premium color options.
Production volume centers on Sedan; coating specification expansion is steepest for SUV.
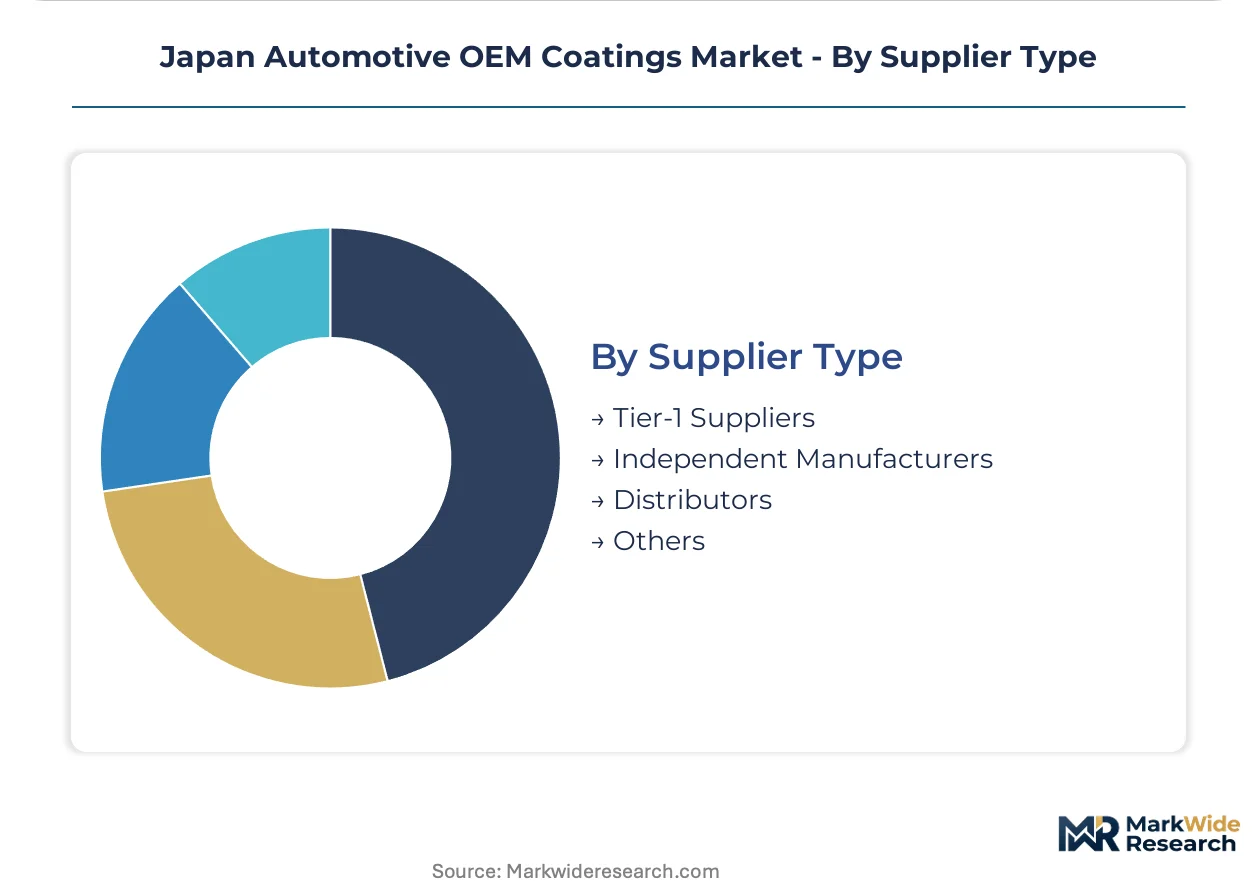
Supplier Type:
Direct plant presence versus arm's-length distribution determines technical service intensity and contract duration.
- Tier-1 Suppliers:Integrated formulators maintain Yokohama and Nagoya technical service centers for direct engineer-to-plant relationships. These vendors capture long-term basecoat contracts through JIS K 5600 certified laboratories and color-matching precision guarantees.
- Independent Manufacturers:Regional specialists serve secondary assembly operations and niche vehicle programs. Their positioning relies on low-temperature cure system development for aluminum-intensive platforms without captive R&D campuses.
- Distributors:Inventory and logistics intermediaries for standard formulations.
- Others:Captive OEM coating operations and import agents.
Contract value aggregates with Tier-1 Suppliers; Independent Manufacturers are climbing fastest on technology licensing arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toyota City anchors Japan's automotive coatings demand through its concentration of final assembly plants and tier-1 supplier technical centers. The Aichi Prefecture corridor generates procurement gravity that shapes coating formulation specifications nationwide.
Aichi Prefecture
Toyota Motor Corporation's headquarters city drives basecoat procurement volumes through just-in-time color-matching requirements. METI's VOC emission ceilings compel paint shops here to accelerate water-borne chemistry conversion. Nagoya-based technical service centers from Kansai Paint and PPG Industries sustain direct engineer-to-plant relationships with assemblers.
Osaka-Kobe Corridor
Kansai Paint Co., Ltd. leverages its R&D campus in Osaka to develop low-temperature cure systems for aluminum-intensive vehicle architectures. The region's chemical industry heritage supplies epoxy resin feedstocks for clearcoat formulations. METI's carbon-neutrality roadmaps are driving cure-oven technology investments across Osaka-based coating development programs.
Yokohama
PPG Industries Inc. maintains technical service infrastructure here to serve Nissan and other OEM engineering centers. The port city's logistics connectivity supports resin import flows for solvent-borne formulations facing phase-out pressure. JIS K 5600 certified laboratories in Yokohama create compliance barriers for non-domestic suppliers seeking market entry.
Fukuoka-Kitakyushu
Kyushu's automotive component manufacturing base generates secondary demand for primer systems on stamped metal parts. Regional paint shops face compressed margins from thermal oxidizer retrofit requirements under Air Pollution Control Act enforcement. Local suppliers specialize in electrodeposition coatings for complex body-in-white geometries serving export-oriented assembly.
Hokkaido
Subaru's manufacturing presence in Gunma and northern Honshu access creates distributed demand for chip-resistant SUV coating specifications. Cold-climate durability testing programs here validate 10-year warranty performance claims. The region's distance from Aichi procurement centers forces independent supply chain arrangements for lower-volume vehicle programs.
Japan Automotive OEM Coatings Market Competitive Landscape
Capital-heavy integrated formulators compete with asset-light specialty developers for position in Japan's automotive OEM coatings sector. The market structure consolidates around four to six dominant suppliers capturing long-term basecoat contracts through JIS certification and color-matching precision guarantees. Strategic archetypes include integrated multinational chemical conglomerates, domestic R&D-anchored specialists, and regional independent manufacturers licensing technology. Competitive moves center on thermal oxidizer retrofit partnerships with paint shops and low-temperature cure system development for multi-substrate vehicle platforms.
Within the domestic specialist tier, Kansai Paint Co., Ltd. and Nippon Paint Holdings Co., Ltd. exemplify Osaka-based R&D-anchored positioning. Among multinational integrated suppliers, BASF SE and Axalta Coating Systems occupy positions serving global OEM programs with localized technical service infrastructure. These named entities represent the competitive tension between domestic formulation expertise and global scale advantages in procurement relationships with Aichi Prefecture assemblers.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| BASF SE |
| Nippon Paint Holdings Co., Ltd. |
| PPG Industries Inc. |
| Kansai Paint Co., Ltd. |
| AkzoNobel N.V. |
| The Sherwin-Williams Company |
| Beckers Group |
| Jotun |
| Others |
Supply & Pricing Matrix
Tier-1 OEM procurement teams concentrated around Aichi Prefecture command contract structures that tether coating prices to per-vehicle color recipe precision rather than bulk resin volumes. This buyer concentration compresses supplier margins while elevating value-based premiums for JIS K 5600 certified formulations with guaranteed 10-year weatherability performance.
Pricing Analysis
Yield-guaranteed color-matching precision anchors value-based pricing for basecoat formulations, with Toyota City assemblers paying premiums for digital tint-matching services that eliminate rework costs. Three-tier pricing structure across premium, standard, and economy levels separates self-healing clearcoat additives from conventional acrylic-urethane top layers and basic primer systems. Cost compression in solvent-borne tiers is intensifying because METI thermal oxidizer retrofit requirements strand legacy assets without compliance pathways. Mid-size independent manufacturers exhibit highest price sensitivity as they lack scale to absorb water-borne conversion capex, while integrated multinationals with captive R&D campuses leverage lowest sensitivity through technology licensing revenue.
Supply Chain Analysis
Single-source vulnerability sits with epoxy resin feedstock streams drawn from Osaka-Kobe petrochemical complexes and import flows through Yokohama port terminals. Geographic supply concentration centers on Japan's domestic chemical manufacturing belt, South Korean specialty resin imports, and Chinese titanium dioxide pigment sources. Raw material dependencies rest on petrochemical-derived acrylic monomers, urethane isocyanates, and aluminum flake pigments for metallic basecoats. Tariff exposure on Chinese pigment imports creates margin volatility for formulators lacking backward integration into mineral processing. Distribution runs through just-in-time technical service centers in Nagoya and Yokohama that maintain direct engineer-to-plant relationships with Aichi Prefecture assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's automotive OEM coatings sector sits in a forced technology-transition phase as water-borne chemistry systematically displaces solvent-borne systems under METI's tightening VOC emission ceilings. Low-temperature cure formulations for aluminum-intensive architectures represent the replacement technology reshaping competitive positioning.
For Market Incumbents: Deepen vertical integration into epoxy resin feedstock production to insulate margin structures from petrochemical price volatility. Secure JIS K 5600 certification expansion across multiple regional laboratory locations to defend against emerging entrants exploiting 18-24 month approval timeline gaps. Priority investment in thermal oxidizer retrofit partnerships with Aichi Prefecture paint shops locks in long-term basecoat supply contracts before water-borne conversion capex cycles complete. For New Entrants and Emerging Players: Digital color recipe platforms offer the lowest-friction entry vector for bypassing bulk resin procurement relationships dominated by incumbents. White-space concentration sits with independent manufacturers serving secondary assembly operations in Fukuoka-Kitakyushu and Hokkaido regions outside Aichi procurement gravity. Technology licensing arrangements for low-temperature cure systems provide fastest path to revenue without captive R&D campus investment. For Investors and Strategic Acquirers: The window for entry favors Osaka-based R&D-anchored specialists with proven aluminum-intensive vehicle platform formulations. Long-term viability hinges on positioning ahead of METI's anticipated process energy regulations that will reshape cure-oven technology investments across the analysis window. Watch for inflection signals in thermal oxidizer retrofit partnership announcements from Aichi Prefecture paint shops as leading indicator of supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Borne Chemistry Conversion | METI VOC compliance mandates force paint shop capex cycles that reshape supplier contracting power. |
| Low-Temperature Cure System Development | Osaka-based R&D programs enable aluminum-intensive multi-substrate adhesion without high-temperature oven infrastructure. |
| Thermal Oxidizer Retrofit Partnerships | Aichi Prefecture facilities face accelerated depreciation of solvent-borne assets without compliance investment. |
| Digital Color Recipe Platform Deployment | Per-vehicle procurement models compress bulk resin volumes while elevating precision-service premiums. |
| JIS K 5600 Certification Expansion | Certified local laboratory networks create 18-24 month approval barriers against non-domestic entrants. |
Research Methodology
Multi-period observation of vehicle production volumes, coating formulation patent filings, and METI regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with paint shop operations managers, OEM platform engineers, Tier 1 supplier procurement leads, and coating R&D directors. Secondary validation drew from customs trade data, JIS standard revision notices, SEC 10-K filings from listed coating suppliers, and automotive production databases. Bottom-up segment sizing triangulated against top-down market value estimates from petrochemical feedstock flow analysis.
Segment-weighting across coating type, application method, vehicle architecture, and supplier tier informed the analytical framework throughout the projection horizon. Modeled dimensions included chemistry conversion rates, cure-oven technology adoption curves, and regional procurement cluster concentration. CAGRs were derived from trend extrapolation of historical formulation shifts and regulatory compliance investment cycles. Industry-specific forecast inputs incorporated METI carbon-neutrality roadmap milestones and aluminum-intensive vehicle platform rollout schedules from Aichi Prefecture OEMs.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in real-time paint shop capex commitment data introduce uncertainty bands around thermal oxidizer retrofit timing assumptions. Forecasts reflect documented assumptions about water-borne conversion rates and process energy regulation stringency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Global Polyurea Coating Market
Coatings
Global Performance Coating Market
Coatings
Asia-Pacific Thermal Spray Market
Coatings
Marine Deck Coatings Market
Coatings
Global Intumescent Coatings Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Ultraviolet (UV) Coatings Market
Coatings
South America Thermal Spray Market
Coatings
Global Hydrophobic Coating Market
Coatings
Fluoropolymer Coating Market
Coatings
Compound Coating Market
Coatings
Global Graphite Coatings Market
Coatings
CVD Coating Technology Market
Coatings
Mexico Floor Coatings Market
Coatings
Canada Automotive OEM Coatings Market