
 Asia-Pacific Alcohol-Infused Ice Cream Market | 2026-2036
Asia-Pacific Alcohol-Infused Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Alcohol-Infused Ice Cream Market Insights
Hospitality procurement is decoupling from conventional dessert supply chains as hotels and cocktail bars in Japan and Australia build dedicated alcohol-infused dessert menus. Nestle leverages its frozen dairy infrastructure across Southeast Asian manufacturing hubs to serve this emerging channel. Haagen-Dazs sustains premium positioning through controlled alcohol-by-volume formulations that comply with varied national food-alcohol classifications. Unilever competes via broad distribution reach into convenience retail across South Korea and Taiwan.
Asia-Pacific alcohol-infused ice cream denotes frozen dairy or non-dairy desserts incorporating distilled spirits, liqueurs, or fermented alcohol bases at concentrations typically below five percent by volume, requiring blast-freezing at minus thirty-five degrees Celsius to preserve texture integrity during alcohol-induced freezing-point depression. The category serves experiential consumption occasions in licensed venues and premium retail. Gelato commands structural attention for its denser mouthfeel and superior alcohol suspension properties, while specialty shops represent the highest-margin distribution channel due to controlled serving environments and personalized flavor customization. Hard ice cream dominates volume throughput through supermarket and convenience store penetration.
Food Standards Australia New Zealand enforces strict alcohol-content disclosure thresholds, while Japan's Ministry of Health, Labour and Welfare classifies these products under processed food standards with alcohol taxation triggers. China's National Health Commission maintains evolving guidelines on alcohol-in-food marketing that constrain youth-targeted positioning. Stakeholders must monitor regulatory divergence across the region's fragmented food-alcohol frameworks to determine localized formulation and channel strategies.
Market Dynamics
Hospitality procurement in Japan and Australia is decoupling from conventional dessert supply chains as licensed venues build dedicated alcohol-infused dessert menus. This structural shift is compressing traditional wholesale margins while opening premium positioning for formulation specialists.
Growth Catalysts
- Food Standards Australia New Zealand labeling mandates:Stricter alcohol-content disclosure thresholds are legitimizing the category and enabling premium pricing in licensed retail channels.
- Tokyo-Osaka hospitality corridor:Cocktail bars and hotels are integrating alcohol-infused gelato into experiential dining concepts, creating pull-through demand for controlled-ABV formulations.
- Blast-freezing infrastructure:Minus thirty-five degrees Celsius freezing technology is preserving texture integrity despite alcohol-induced freezing-point depression, enabling scalable production.
Market Restraints
- Dairy input volatility:Butterfat and cream price fluctuations compress margins for premium formulations requiring high dairy solids.
- Supply concentration in Southeast Asian manufacturing:Frozen dairy infrastructure clusters in Thailand and Malaysia create geographic vulnerability for Australia and Japan demand.
- Japan's alcohol taxation triggers:Ministry of Health, Labour and Welfare thresholds add compliance cost and limit ABV experimentation.
Strategic Opportunities
- South Korea convenience retail:Underpenetrated channels in Seoul and Busan offer volume expansion for single-serve formats.
- Plant-based alcohol suspension:Oat and coconut fat bases are converging with traditional dairy freezing technology to capture lactose-intolerant consumers.
- China's evolving marketing guidelines:National Health Commission constraints on youth-targeted alcohol-in-food positioning create first-mover advantage for adult-premium branding.
Industry Challenges
- Formulation chemistry expertise:Scarcity of food scientists skilled in alcohol-protein emulsion stability slows product development cycles.
- Cross-border cold chain integrity:Maintaining minus thirty-five degrees Celsius through multi-country distribution requires capex-heavy reefer infrastructure.
- Dual classification compliance:Products falling under both processed food standards and alcohol regulations face extended certification timelines in multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Alcohol-Infused Ice Cream Market |
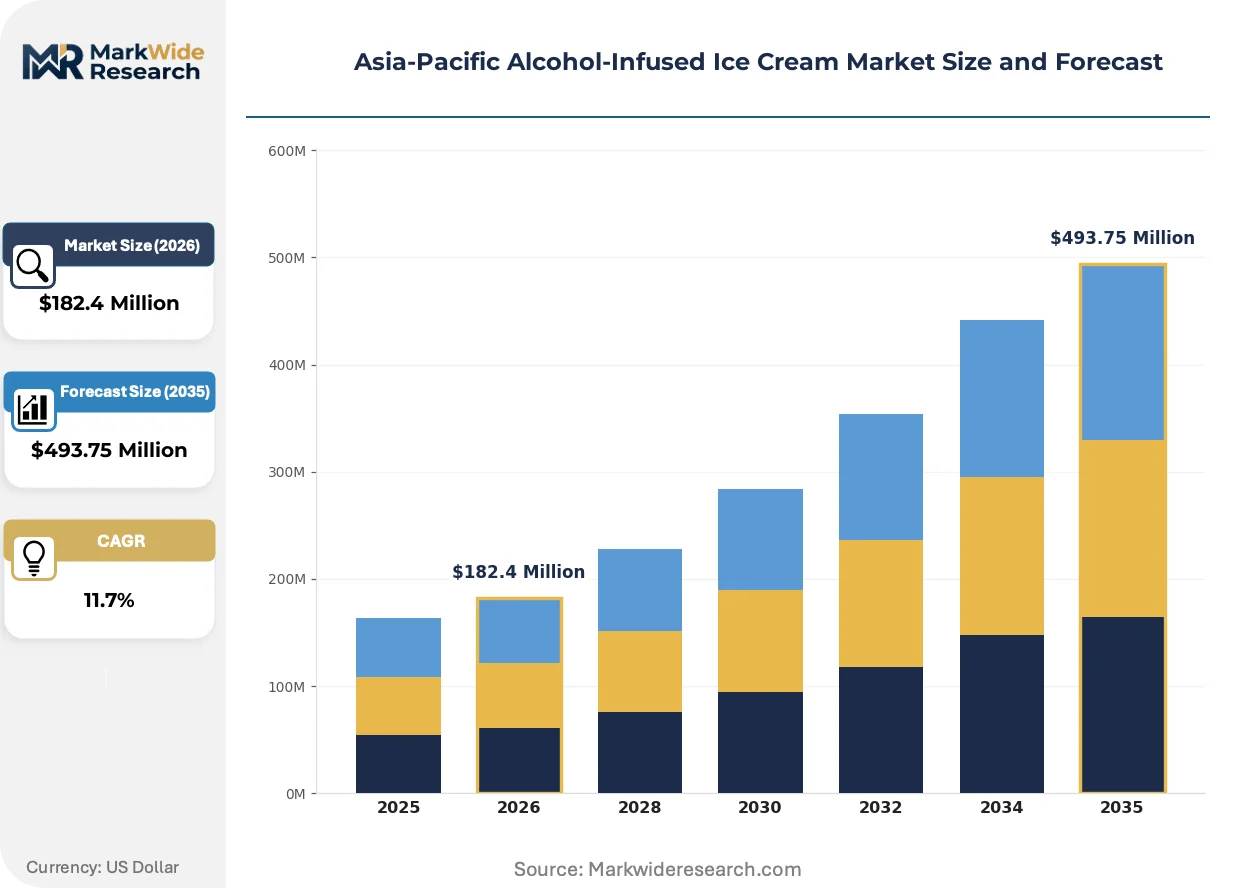
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $493.75 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Ice Cream, Soft Serve, Gelato, Sorbet Flavor Profile: Chocolate, Vanilla, Strawberry, Mango Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops Target Audience: Young Adults, Couples, Event Planners, Health-Conscious Consumers |
| Companies Covered | Nestle, Quore Gelato, Haagen-Dazs, Tipsy Scoop, Speakeasy Ice Creams, Ben & Jerry's Homemade, Kraft Foods, Mercer's Dairy, Unilever, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Alcohol-Infused Ice Cream Market Trends and Innovations
Blast-freezing technology and plant-base formulation advances are compressing production barriers while regulatory divergence across the Asia-Pacific is forcing localized adaptation strategies.
Precision blast-freezing systems are integrating alcohol-protein stabilization protocols that maintain gelato density at elevated ABV levels. Japanese specialty shops are adopting these systems fastest, with Tokyo venues upgrading equipment within eighteen-month cycles. The technology is integrating formerly separate dessert and beverage supply chains into unified hospitality procurement.
Food Standards Australia New Zealand is tightening alcohol-content disclosure thresholds while requiring ingredient provenance documentation. Industrial consequence includes reformulation costs and extended product development timelines. Australian manufacturers are responding by segmenting SKUs into licensed-venue-only versus retail-eligible variants.
Buyer concentration in Sydney-Melbourne hotel chains is compressing supplier negotiation cycles from annual to quarterly reviews. Boutique gelaterias are displacing traditional wholesale distributors through direct-account relationships with cocktail bars. This pattern is most visible in Australia's premium hospitality corridor where venue procurement teams now specify ABV ranges and flavor profiles directly.
Asia-Pacific Alcohol-Infused Ice Cream Market Segmentation
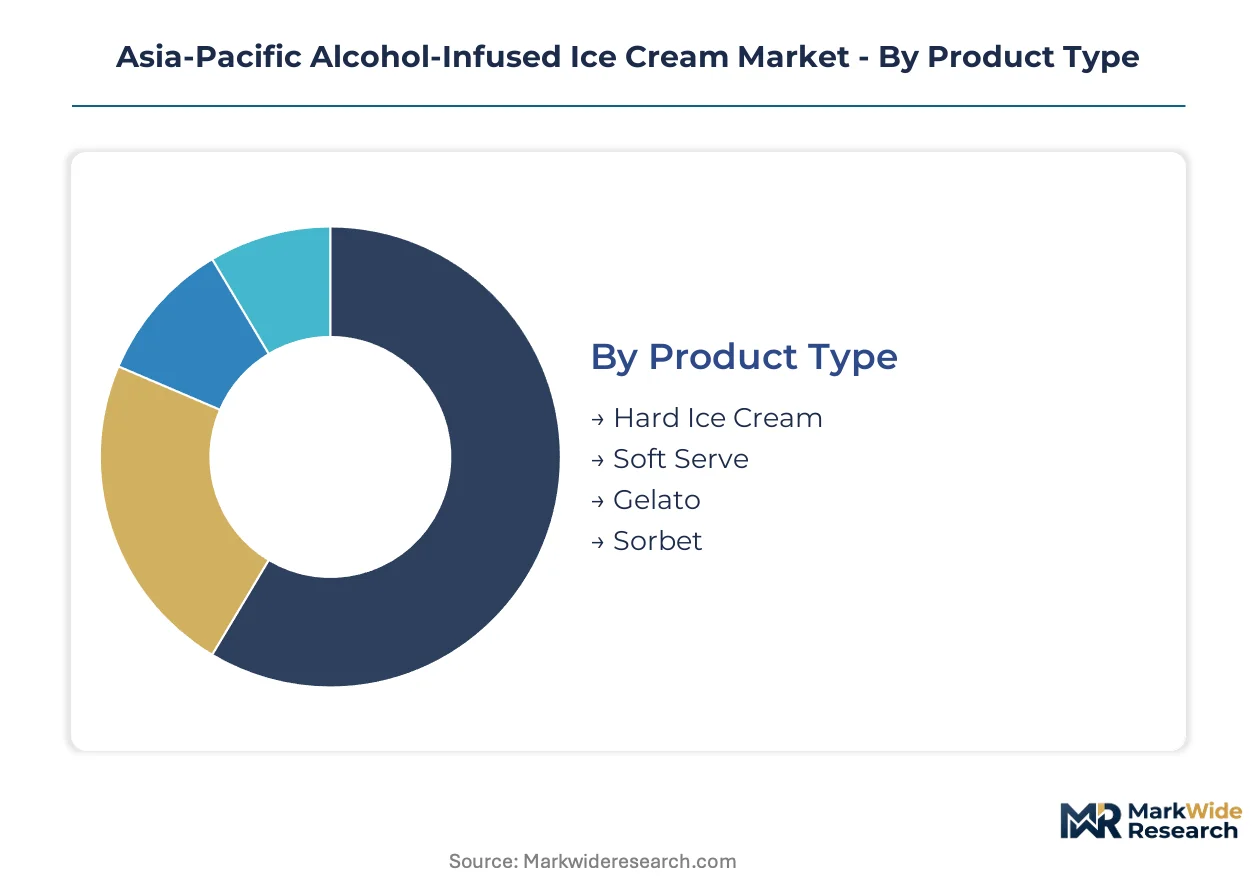
Segmentation in Asia-Pacific alcohol-infused ice cream reveals divergent margin structures across product physics and channel access. Buyers prioritize texture integrity at elevated ABV levels or controlled serving environments that justify premium pricing.
Product Type:
Buyers differentiate by freezing-point depression tolerance and alcohol suspension capacity.
- Hard Ice Cream:High butterfat formulations withstand alcohol-induced freezing-point depression through controlled overrun. Demand concentrates in Australia's Sydney-Melbourne supermarket corridor where retail packaging scales offset formulation costs. Dairy input volatility compresses margins for premium variants.
- Gelato:Denser mouthfeel and lower air content enable superior alcohol suspension at elevated ABV without texture breakdown. Tokyo-Osaka cocktail bars specify gelato for experiential dessert menus, creating pull-through demand for precision blast-freezing equipment. Japan's alcohol taxation triggers constrain ABV experimentation.
- Soft Serve:Lower capital equipment requirements suit convenience retail in South Korea's Seoul-Busan corridor.
- Sorbet:Plant-based formulations capture lactose-intolerant consumers in Australia's health-conscious segments.
Volume sits with Hard Ice Cream; growth tilts toward Gelato.
Flavor Profile:
Flavor selection tracks regional alcohol pairing traditions and ingredient sourcing reliability.
- Chocolate:Cocoa butter fat structure stabilizes alcohol emulsions across dairy and plant bases. Australian manufacturers source Ghanaian and Indonesian cocoa through established supply chains, with Sydney-Melbourne venues specifying single-origin variants for premium positioning.
- Vanilla:Neutral base enables alcohol-forward profiles where spirit character dominates. Japanese specialty shops in Tokyo deploy Madagascar Bourbon vanilla for high-ABV gelato, with Food Standards Australia New Zealand disclosure mandates legitimizing premium retail channels.
- Strawberry:Seasonal sourcing constraints limit year-round production scalability in Southeast Asian manufacturing hubs.
- Mango:Philippine and Thai supply clusters serve regional demand but face cold chain integrity challenges to Japan and Australia.
Chocolate captures volume leadership; Vanilla expands most quickly in licensed venues.
Distribution Channel:
Channel choice determines ABV compliance requirements and serving temperature control.
- Specialty Shops:Controlled serving environments enable personalized flavor customization and highest-margin positioning. Tokyo venues upgrade blast-freezing equipment within eighteen-month cycles, integrating formerly separate dessert and beverage procurement.
- Supermarkets:Mass volume throughput requires retail-eligible ABV formulations below taxation thresholds. Australian manufacturers segment SKUs into licensed-venue-only versus retail-eligible variants per Food Standards Australia New Zealand mandates.
- Convenience Stores:Single-serve formats target South Korea's underpenetrated Seoul-Busan channels.
- Online Retail:Cold chain integrity requirements limit geographic reach from Southeast Asian manufacturing clusters.
Supermarkets dominate volume; Specialty Shops gain share fastest.
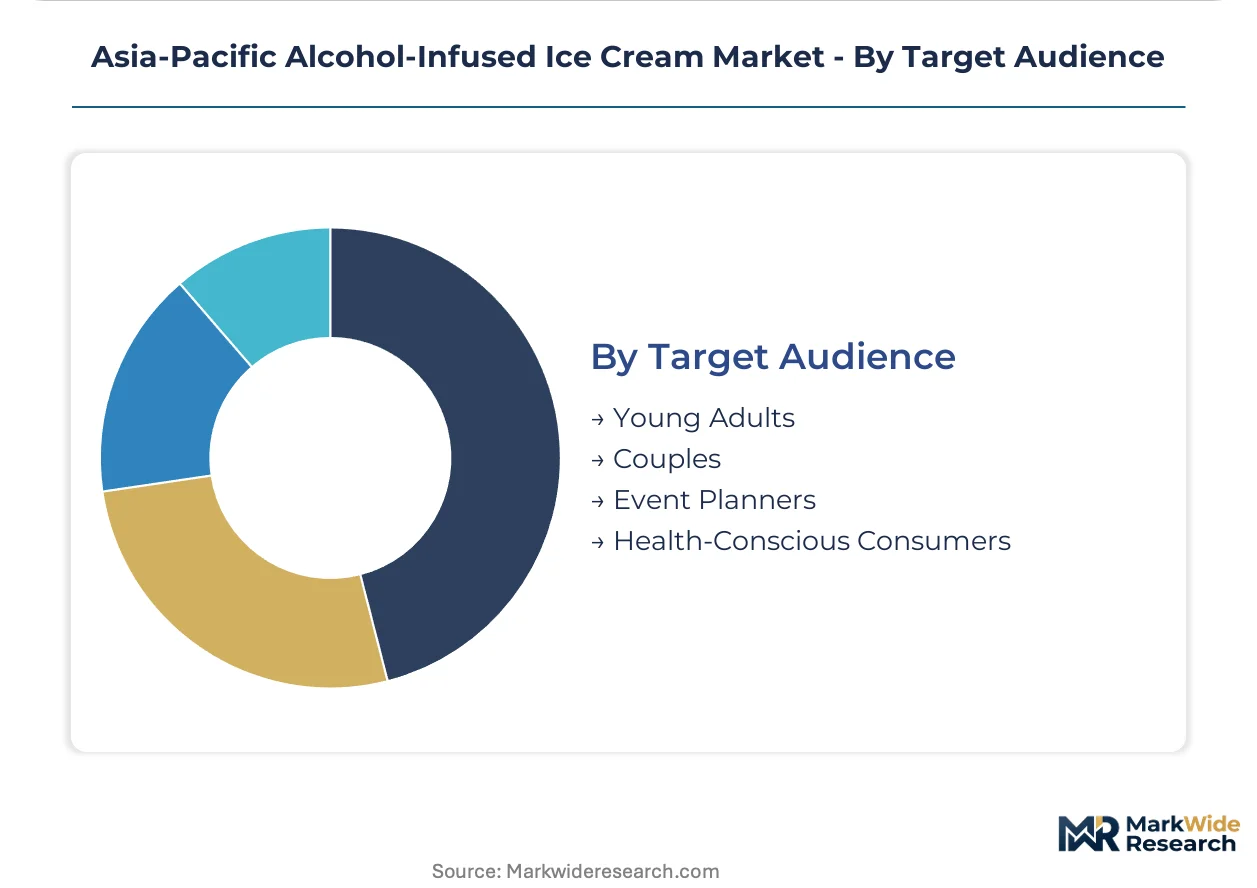
Target Audience:
Audience segmentation aligns consumption occasion with regulatory exposure and price sensitivity.
- Young Adults:Experiential consumption in licensed venues drives trial and premium pricing acceptance. Japan's Ministry of Health, Labour and Welfare processed food standards constrain marketing positioning, with China's National Health Commission guidelines adding youth-targeted restrictions.
- Couples:Date-night and celebration occasions support higher per-occasion spend in Australia's hospitality corridor.
- Event Planners:Bulk procurement compresses margins despite volume concentration in Sydney-Melbourne corporate segments.
- Health-Conscious Consumers:Plant-based and reduced-sugar variants attract lactose-intolerant and wellness-oriented buyers.
Young Adults anchor volume; Couples show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bangkok Special Economic Zone and Thailand's Board of Investment incentives for frozen food manufacturing have concentrated blast-freezing infrastructure investment, drawing multinational dairy processors to serve Australia and Japan demand corridors.
Japan
Tokyo-Osaka cocktail bars are integrating alcohol-infused gelato into experiential dining concepts, creating pull-through demand for precision blast-freezing equipment. METI processed food standards and Ministry of Health, Labour and Welfare alcohol taxation triggers constrain ABV experimentation. Kanto region specialty shops upgrade equipment within eighteen-month cycles, integrating formerly separate dessert and beverage procurement.
Australia
Sydney-Melbourne hotel chains are compressing supplier negotiation cycles from annual to quarterly reviews as hospitality procurement decouples from conventional dessert supply chains. Food Standards Australia New Zealand labeling mandates and alcohol-content disclosure thresholds are legitimizing premium retail channels. Victorian boutique gelaterias displace traditional wholesale distributors through direct-account relationships with cocktail bars.
South Korea
Seoul-Busan convenience retail channels remain underpenetrated for single-serve alcohol-infused formats, offering volume expansion opportunities. MFDS processed food standards govern alcohol-in-food classification with compliance requirements that add certification timelines. Daegu-Gyeongbuk manufacturing clusters supply domestic demand while importing precision freezing technology from Japanese vendors.
China
National Health Commission evolving guidelines on alcohol-in-food marketing constrain youth-targeted positioning, creating first-mover advantage for adult-premium branding strategies. SAMR processed food standards intersect with provincial alcohol regulations in fragmented compliance frameworks. Yangtze River Delta hospitality venues in Shanghai and Hangzhou pilot controlled-ABV dessert menus for experiential consumption occasions.
Thailand
Board of Investment tax incentives for frozen food manufacturing have concentrated blast-freezing infrastructure serving regional export demand. Thai FDA processed food standards align with ASEAN harmonization initiatives for cross-border trade. Bangkok manufacturing hubs supply hard ice cream formulations to Australian supermarket chains while facing cold chain integrity challenges to Tokyo-Osaka corridors.
Asia-Pacific Alcohol-Infused Ice Cream Market Competitive Landscape
Top-tier vendors anchor premium hospitality procurement, while mid-scale specialists occupy formulation-intensive niches and regional dairy processors compete on distribution reach. The competitive terrain splits between multinational frozen dairy conglomerates with Southeast Asian manufacturing footprints and boutique gelaterias with direct venue relationships. Three archetypes dominate: controlled-ABV formulation specialists, broad-distribution dairy processors, and experiential channel direct suppliers. M&A activity concentrates on blast-freezing equipment capabilities and licensed-venue distribution networks.
Within the multinational dairy processor tier, Nestle leverages frozen dairy infrastructure across Southeast Asian manufacturing hubs to serve emerging hospitality channels. Haagen-Dazs sustains premium positioning through controlled alcohol-by-volume formulations that comply with varied national food-alcohol classifications. Unilever competes via broad distribution reach into convenience retail across South Korea and Taiwan, representing the scale-driven archetype that prioritizes volume throughput over margin capture.
| Leading Market Players |
|---|
| Nestle |
| Quore Gelato |
| Haagen-Dazs |
| Tipsy Scoop |
| Speakeasy Ice Creams |
| Ben & Jerry's Homemade |
| Kraft Foods |
| Mercer's Dairy |
| Unilever |
| Others |
Pricing and Supply Chain Analysis
Premium hospitality procurement in Tokyo-Osaka and Sydney-Melbourne commands formulation premiums that commodity retail channels cannot match, with this bifurcation driving divergent supply chain configurations across Southeast Asian manufacturing hubs and Japanese specialty equipment vendors. Licensed venues absorb higher per-unit costs for controlled-ABV gelato with personalized flavor profiles, while supermarket chains in Australia enforce cost-down targets that compress margins for hard ice cream variants sourced from Thai blast-freezing facilities.
Pricing Analysis
Short lead-time premiums of thirty percent or more apply to Tokyo specialty shops requiring eighteen-month equipment upgrade cycles, while spot inventory from Malaysian dairy processors trades at discounts to contract offtake. Three-tier pricing structure across premium hospitality, standard retail, and economy convenience segments tracks butterfat content and alcohol suspension certification. Cost compression in economy tiers intensifies because Thai manufacturing overcapacity feeds price competition. Event planners in Australia's corporate segments exhibit highest price sensitivity; cocktail bars in Japan's Kanto region show least.
Supply Chain Analysis
Dual-sourcing requirements from Australian hotel chains now mandate qualification of both Thai and Malaysian blast-freezing suppliers to mitigate geographic concentration risk. Manufacturing gravity centers on Thailand, Malaysia, and Indonesia for frozen dairy infrastructure. Raw material dependencies span Ghanaian cocoa butter, Madagascar vanilla, and Australian cream. Single-source vulnerability in precision freezing equipment from Japanese vendors threatens capacity expansion timelines. Distribution runs through dedicated reefer corridors to Sydney-Melbourne and Tokyo-Osaka demand belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures are intensifying as Food Standards Australia New Zealand labeling mandates raise compliance barriers that weaker regional dairy processors cannot absorb, forcing exits or distressed sales to formulation specialists with dedicated regulatory affairs capabilities.
For Market Incumbents: Deploy backward integration into captive blast-freezing equipment supply to defend against Japanese vendor bottlenecks threatening capacity expansion. Nestle and Haagen-Dazs should deepen direct-account relationships with Sydney-Melbourne hotel chains before boutique gelaterias displace traditional wholesale distributors entirely. Channel control through dedicated hospitality procurement teams represents the critical defensive lever against margin compression. For New Entrants and Emerging Players: Food Standards Australia New Zealand disclosure thresholds in Australia open a window for first-mover positioning in retail-eligible ABV formulations that incumbent SKU segmentation has left undersupplied. Target South Korea's Seoul-Busan convenience corridor for single-serve format penetration where Unilever's broad distribution has not yet specialized. Partner with Thai Board of Investment manufacturing hubs for cost-competitive hard ice cream supply to Australian supermarket chains. For Investors and Strategic Acquirers: Exit pathways concentrate in precision blast-freezing equipment specialists and licensed-venue distribution networks as hospitality procurement decouples from conventional dessert supply chains. Long-term viability favors acquirers of formulation chemistry capabilities and direct venue relationships over commodity dairy processors. Watch for MFDS processed food standard clarifications in South Korea as inflection signal for convenience retail penetration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Blast-Freezing Equipment Acquisition | Captures precision alcohol-protein stabilization technology that Japanese vendors currently dominate. |
| Direct Hospitality Procurement Integration | Eliminates wholesale distributor margins in Sydney-Melbourne and Tokyo-Osaka venue networks. |
| Plant-Based Formulation Development | Addresses lactose-intolerant segments in Australia's health-conscious consumer corridors. |
| Licensed-Venue-Only SKU Segmentation | Complies with Food Standards Australia New Zealand disclosure mandates while preserving premium positioning. |
| Southeast Asian Manufacturing Expansion | Leverages Thai Board of Investment incentives to serve Australian and Japanese export demand. |
Research Methodology
Multi-period observation of blast-freezing equipment upgrade cycles, ABV formulation patent filings, and hospitality procurement contract structures anchored the trend analysis, supplemented by interviews with frozen dairy plant managers, cocktail bar beverage directors, hotel procurement leads, and Australian regulatory affairs specialists. Secondary validation drew from Food Standards Australia New Zealand disclosure filings, Japanese Ministry of Health processed food registrations, Thai FDA export certifications, and customs trade data for frozen dessert categories. Bottom-up volume modeling across product types and channels triangulated against top-down macroeconomic indicators for the Asia-Pacific region.
Segment-weighting applied differential growth assumptions across hard ice cream, gelato, soft serve, and sorbet categories, with channel splits between specialty shops, supermarkets, convenience stores, and online retail calibrated to observed penetration patterns. The analytical framework incorporated alcohol taxation threshold compliance costs, dairy input price volatility indices, and cold chain infrastructure investment flows throughout the forecast period. CAGRs derived from regression analysis of historical frozen dessert consumption elasticities against discretionary spending indicators.
The model assumes a particular technology adoption path for precision blast-freezing systems; alternative pathways for alcohol-protein emulsion stabilization would alter the outlook for texture integrity at elevated ABV levels. Forecasts reflect assumptions about regulatory harmonization across ASEAN markets and sustained hospitality procurement decoupling from conventional dessert supply chains. Deviation in Japan's Ministry of Health alcohol taxation trigger thresholds or China's National Health Commission marketing guideline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Keto Low-Calorie Meals Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
Hot Pot Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Chamomile Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Middle East and Africa Free-From Food Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Areca Bowl Market
Specialty Foods
Sea Moss Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Marine Thermal Water Ferments Market