
 North America Alcohol-Infused Ice Cream Market | 2026-2036
North America Alcohol-Infused Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alcohol-Infused Ice Cream Market Insights
Market Context with Strategic Players
Artisanal dairy craftsmanship and licensed alcohol handling expertise is redrawing competitive boundaries in this specialty frozen dessert category. Tipsy Scoop leverages its Manhattan-based production facility and direct-to-consumer channel control to dominate the boutique retail segment. Mercer's Dairy sustains decades of farm-level vertical integration, anchoring its supply of cream base inputs across upstate New York and into Canadian distribution. PROOF Alcohol Ice Cream competes through precise ABV calibration technology that navigates varying state liquor board thresholds.
Technical Definition and Structural Segments
North America alcohol-infused ice cream denotes frozen dairy or non-dairy desserts containing distilled spirits, wine, or liqueurs at concentrations typically below five percent alcohol by volume, requiring controlled overrun rates and sub-zero hardening tunnels to prevent ethanol-induced texture breakdown. Cream base formulations currently occupy the largest volume share due to fat content stability with ethanol emulsions, while vegan alternatives represent the fastest-expanding margin pool as oat and coconut protein technologies mature. Bourbon and vodka variants lead the alcohol type dimension, with bourbon concentrating in southern U.S. manufacturing clusters and vodka enabling cleaner flavor layering for gourmet food enthusiasts. Distribution through boutique stores and restaurant partnerships captures the highest per-unit margins, whereas supermarket placement demands reformulated, lower-ABV SKUs to comply with retail alcohol licensing frameworks.
Regulatory Frame and Forward-Looking Close
The Alcohol and Tobacco Tax and Trade Bureau enforces formula approval and labeling standards for interstate commerce, while individual state liquor control boards impose divergent caps on retail ABV content that fragment product portability across jurisdictions. Health Canada and provincial liquor authorities maintain parallel but non-identical standards, forcing dual-compliance investments for cross-border manufacturers. FDA dairy safety protocols and state-level cottage food laws further complicate small-batch production scaling. Stakeholders must monitor pending state legislative revisions to alcohol-in-food classifications and build modular formulation capabilities that adapt to jurisdiction-specific thresholds without complete product redesign.
Market Dynamics
State-level alcohol-by-volume caps are fragmenting product portability across the United States and Canada, forcing manufacturers to maintain modular formulation capabilities and jurisdiction-specific SKUs rather than unified national product lines.
Growth Catalysts
- Hospitality Venue Expansion:Premium dessert lounges in New York City, Los Angeles, and Toronto are expanding alcohol-infused frozen dessert menus, creating pull-through demand for wholesale supply contracts.
- TTB Formula Standardization:The Alcohol and Tobacco Tax and Trade Bureau's interstate labeling requirements are reducing compliance ambiguity for multi-state operators, lowering market entry friction.
- Oat Protein Stabilization:Advanced oat protein emulsion technologies are enabling vegan alcohol-infused formulations with texture parity to dairy bases, unlocking allergen-sensitive consumer segments.
Market Restraints
- Cream Base Input Volatility:Dairy commodity price swings and concentrated upstate New York farm supply create margin pressure for vertically integrated producers.
- Ethanol-Induced Texture Degradation:Alcohol's freezing point depression requires sub-zero hardening tunnel investments that small-batch manufacturers cannot absorb.
- State Liquor Board Fragmentation:Divergent ABV thresholds across California, Texas, Florida, and New York force redundant product line maintenance and compliance costs.
Strategic Opportunities
- Canadian Provincial Expansion:Ontario and British Columbia liquor authority frameworks present underpenetrated retail licensing pathways for U.S. manufacturers with Health Canada pre-approval.
- Direct-to-Consumer Cold Chain:Insulated packaging and same-day delivery logistics are enabling bypass of traditional retail alcohol licensing constraints in metropolitan corridors.
- Bourbon-Barrel Aging Convergence:Partnerships with Kentucky and Tennessee distilleries for spent barrel flavor extraction are creating differentiated premium SKUs with provenance storytelling.
Industry Challenges
- Licensed Alcohol Handler Certification:FDA dairy safety protocols and state cottage food laws create overlapping compliance timelines that delay small-batch scaling by 8-14 months.
- Cross-Border Formulation Reconciliation:Health Canada and TTB non-identical standards force dual-compliance investments without harmonization mechanisms.
- Cold Chain Integrity Maintenance:Ethanol content compromises overrun stability during temperature excursions, requiring specialized transport equipment with limited third-party availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alcohol-Infused Ice Cream Market |
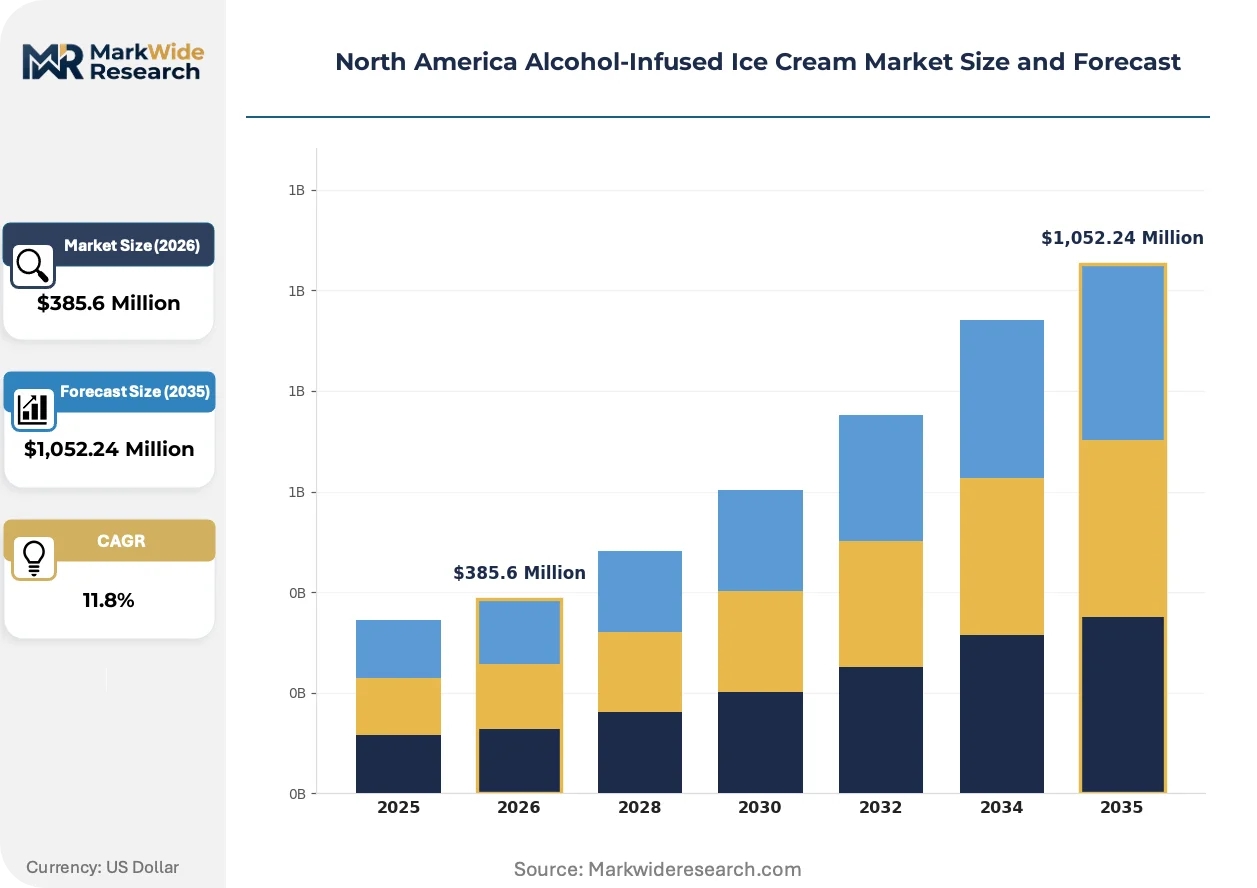
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,052.24 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Base, Sorbet, Gelato, Vegan Alcohol Type: Vodka, Rum, Bourbon, Wine Distribution Channel: Supermarkets, Online, Boutique Stores, Restaurants End User: Adults, Gourmet Food Enthusiasts, Event Planners, Foodies |
| Companies Covered | Tipsy Scoop, Buzz Bar, LLC., Mercer's Dairy, PROOF Alcohol Ice Cream, New Orleans Ice Cream Company, DizziBrands, LLC, Ben & Jerry's Homemade, Inc., Jeni's Splendid Ice Creams, LLC., Salt & Straw, LLC., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alcohol-Infused Ice Cream Market Trends and Innovations
Precision ABV calibration and alternative protein stabilization are converging to expand addressable dietary segments while regulatory technology investments compress multi-jurisdiction compliance cycles.
Flash-freezing nitrogen tunnel systems are displacing conventional hardening equipment in artisanal production facilities. Boutique manufacturers in Brooklyn and Austin are adopting these systems to achieve sub-zero temperatures without ethanol-induced crystallization defects. The technology is displacing batch-hardening methods that produced inconsistent texture profiles across ABV variants.
State legislative revisions to alcohol-in-food classifications are accelerating across the southern United States. Texas and Florida liquor control boards are evaluating dedicated licensing tiers for frozen desserts with distilled spirits content above three percent ABV. Manufacturers with existing TTB formula approvals are pre-positioning compliance documentation to capture first-mover retail placement in revised regulatory environments.
Restaurant procurement teams are consolidating supplier relationships around full-service frozen dessert programs. Hospitality groups in Chicago, Miami, and Vancouver are replacing multiple single-category vendors with integrated alcohol-infused dessert and conventional ice cream partnerships. This concentration is most visible in multi-unit fine dining chains seeking menu differentiation through exclusive flavor collaborations.
North America Alcohol-Infused Ice Cream Market Segmentation
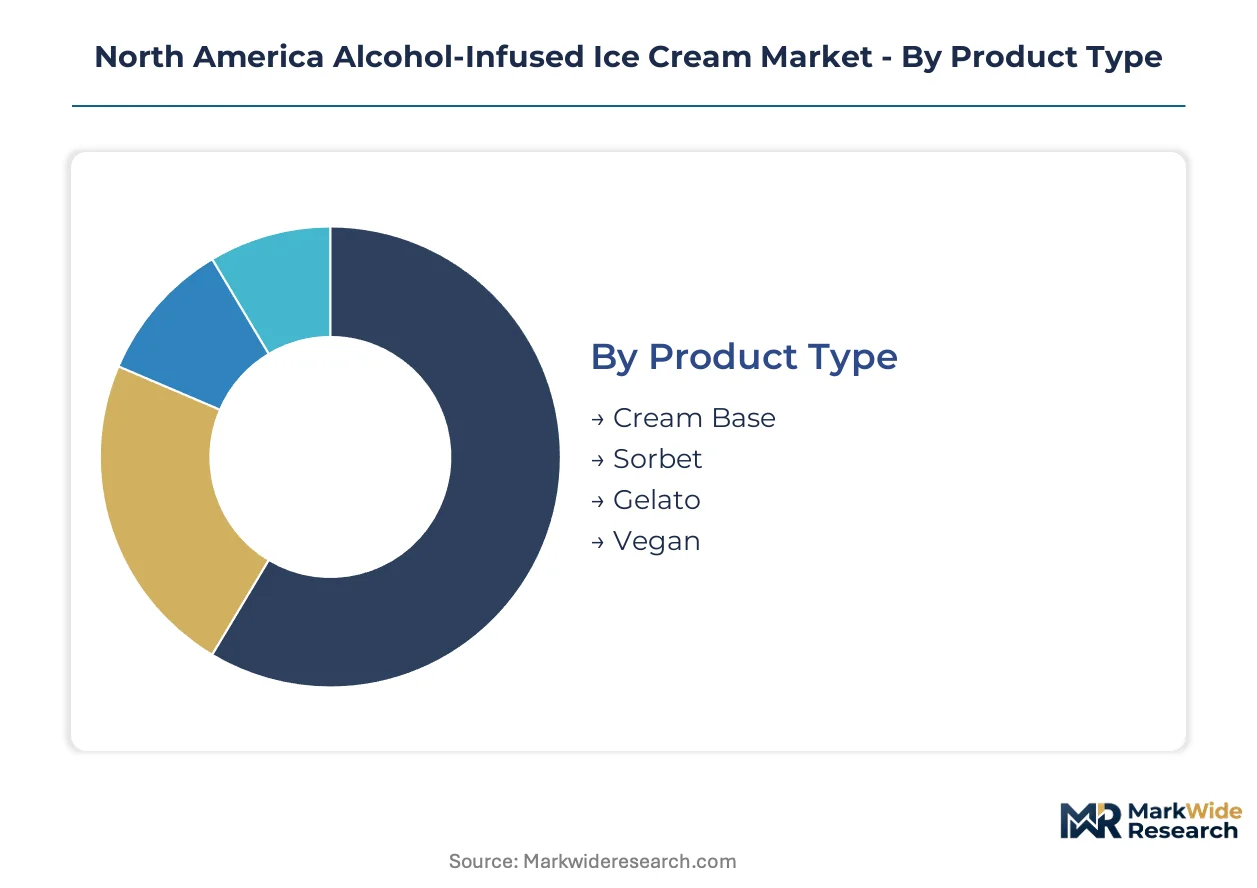
Alcohol-infused frozen dessert manufacturers navigate divergent technical requirements and licensing constraints across product formats, forcing portfolio architectures that balance formulation complexity against addressable market breadth. Segmentation discipline determines which SKUs merit jurisdiction-specific compliance investments versus standardized national distribution.
Product Type:
Cream base formulations face intensifying substitution pressure from stabilized vegan alternatives as oat protein emulsion technologies mature, while sorbet and gelato segments defend niche positioning through cleaner flavor profiles.
- Cream Base:High-fat dairy emulsions provide ethanol stability through controlled overrun rates above 80%. Demand concentrates in southern U.S. manufacturing clusters where bourbon-barrel aging partnerships with Kentucky distilleries create provenance differentiation. TTB formula approvals for interstate cream-base SKUs require documented pasteurization protocols.
- Vegan:Advanced oat and coconut protein stabilization achieves texture parity with dairy bases at ABV concentrations below 5%. Metropolitan corridors including Brooklyn and Austin drive demand as allergen-sensitive consumers expand addressable segments beyond traditional dairy-restricted populations.
- Sorbet:Fruit-forward formulations with wine-based alcohol integration target summer seasonal demand in coastal California and Florida markets.
- Gelato:Dense, low-overrun textures require modified ethanol calibration to prevent crystallization defects in artisanal production settings.
Cream base retains volume leadership; vegan holds the steepest expansion curve.
Alcohol Type:
Cost tier stratification separates premium spirit categories from accessible wine-based formulations, with distribution channel access correlating directly to ABV calibration investments.
- Bourbon:Kentucky and Tennessee distillery partnerships enable spent-barrel flavor extraction with documented provenance storytelling. Southern state liquor board frameworks favor bourbon-forward SKUs in retail placement evaluations.
- Vodka:Neutral spirit profiles enable cleaner flavor layering for gourmet food enthusiasts in Manhattan and Los Angeles hospitality venues. Precise ABV calibration technology navigates varying state thresholds without complete formula redesign.
- Rum:Caribbean-sourced molasses derivatives concentrate in Miami and coastal Florida distribution.
- Wine:Lower ABV content facilitates supermarket placement under retail alcohol licensing frameworks in California and New York.
Bourbon dominates revenue concentration; vodka is expanding most quickly across metropolitan hospitality procurement.
Distribution Channel:
Application-specific margin structures separate immediate-consumption venues from retail stockkeeping, with licensing complexity inversely correlating to per-unit profitability.
- Restaurants:Full-service frozen dessert programs capture highest per-unit margins through exclusive flavor collaborations with Chicago and Vancouver hospitality groups. Multi-unit fine dining chains consolidate supplier relationships around integrated alcohol-infused and conventional ice cream partnerships.
- Boutique Stores:Manhattan-based production facilities with direct-to-consumer channel control enable ABV variants above supermarket thresholds. Tipsy Scoop's retail footprint demonstrates volume potential in licensed specialty environments.
- Supermarkets:Reformulated lower-ABV SKUs comply with retail alcohol licensing frameworks across fragmented state jurisdictions.
- Online:Insulated packaging and same-day delivery logistics bypass traditional retail licensing constraints in metropolitan corridors.
Restaurants command margin leadership; boutique stores are gaining share fastest through experiential retail positioning.
End User:
Customer type segmentation aligns procurement behavior with occasion-based consumption patterns, from individual indulgence to event-scale hospitality procurement.
- Gourmet Food Enthusiasts:Flavor-layering sophistication drives repeat purchase in direct-to-consumer channels with subscription-based seasonal releases. Brooklyn and Austin flash-freezing nitrogen tunnel adoption targets this segment's texture-quality expectations.
- Event Planners:Bulk procurement for weddings and corporate functions concentrates demand in Toronto and Los Angeles metropolitan areas with licensed catering frameworks.
- Adults:General population access depends on state-level cottage food law compliance timelines.
- Foodies:Social media-driven trial behavior accelerates new flavor adoption in coastal urban markets.
Gourmet food enthusiasts anchor revenue stability; event planners represent the fastest-growing procurement segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The TTB anchors the United States as the dominant geography, with state-level alcohol-by-volume caps fragmenting product portability across jurisdictions. Metropolitan corridors drive concentrated demand, while provincial frameworks in Canada create parallel but non-identical compliance requirements.
United States
Premium dessert lounges in New York City, Los Angeles, and Chicago expand alcohol-infused frozen dessert menus, creating wholesale pull-through demand. The TTB enforces formula approval and interstate labeling standards, though California, Texas, Florida, and New York maintain divergent ABV thresholds. Brooklyn and Austin manufacturing clusters adopt flash-freezing nitrogen tunnel systems to achieve texture parity across bourbon and vodka variants.
Canada
Toronto and Vancouver hospitality venues drive cross-border procurement interest from U.S. manufacturers seeking Health Canada pre-approval. Provincial liquor authorities in Ontario and British Columbia maintain frameworks distinct from TTB standards, forcing dual-compliance investments. Ontario's retail licensing pathways remain underpenetrated relative to U.S. metropolitan saturation.
Mexico
Tourism corridors in Cancún and Los Cabos generate seasonal demand for alcohol-infused frozen desserts in resort hospitality. Federal Commission for the Protection against Sanitary Risk (COFEPRIS) oversees food-alcohol hybrid classifications with emerging clarity. Mexico City Metro manufacturing remains nascent, with distribution concentrated through informal channels rather than licensed retail frameworks.
North America Alcohol-Infused Ice Cream Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with farm-level cream base control and direct-to-consumer channel ownership separating the upper tier from contract-dependent entrants. Manhattan-based production facilities with licensed alcohol handler certification anchor the boutique retail segment, while national dairy brands leverage existing cold chain infrastructure for lower-ABV supermarket SKUs. Strategic moves concentrate on modular formulation capabilities for jurisdiction-specific compliance and exclusive flavor collaborations with multi-unit hospitality groups.
Among specialist producers, Tipsy Scoop and Mercer's Dairy exemplify contrasting archetypes of urban production facility control versus decades-long farm-level vertical integration. PROOF Alcohol Ice Cream occupies a position within the precision technology tier, with company nomenclature signaling ABV calibration specialization. These three entities represent the competitive vectors of channel ownership, input control, and regulatory technology that define strategic positioning across fragmented state liquor board environments.
| Leading Market Players |
|---|
| Tipsy Scoop |
| Buzz Bar, LLC. |
| Mercer's Dairy |
| PROOF Alcohol Ice Cream |
| New Orleans Ice Cream Company |
| DizziBrands, LLC |
| Ben & Jerry's Homemade, Inc. |
| Jeni's Splendid Ice Creams, LLC. |
| Salt & Straw, LLC. |
| Others |
Pricing and Supply Chain Analysis
Oat protein stabilization replacing traditional dairy emulsions simultaneously shifts manufacturing gravity toward Brooklyn and Austin technology clusters while compressing margin structures for upstate New York cream base suppliers. This substitution dynamic fragments pricing power across input tiers and forces reformulation investments that diverge by distribution channel licensing constraints.
Pricing Analysis
Metropolitan corridor pricing spreads widen against supermarket tiers due to ABV calibration complexity and licensed retail overhead. Three-tier pricing structure across premium bourbon-barrel aged, standard vodka-based, and economy wine-integrated levels separates gourmet enthusiasts from mass-market trialists. Price differentiation hinges on provenance documentation and flash-freezing nitrogen tunnel certification. Cost compression in economy tiers intensifies because Health Canada dual-compliance investments flow through to cross-border SKUs. Event planners demonstrate lowest price sensitivity while supermarket buyers face hard ceiling constraints from state liquor board volume caps.
Supply Chain Analysis
Inventory lead times for specialized sub-zero hardening equipment extend 14-20 weeks due to limited third-party cold chain infrastructure availability. Manufacturing concentrates in the United States, Canada, and emerging Mexico City Metro clusters. Cream base inputs draw from upstate New York dairy farms, Kentucky distillery spent-barrel partnerships, and stabilized oat protein processors. Single-source vulnerability concentrates in flash-freezing nitrogen tunnel fabricators with no qualified secondary suppliers. Distribution runs through licensed alcohol handler networks, direct-to-consumer insulated packaging logistics, and conventional frozen dessert wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
State-level regulatory fragmentation creates multiple defendable niches as hospitality procurement teams consolidate around full-service frozen dessert programs requiring jurisdiction-specific formulation expertise.
For Market Incumbents: Shield market position by deepening captive supply of cream base inputs through upstate New York farm partnerships and accelerating TTB formula approval documentation for pending Texas and Florida licensing tier revisions. Modular formulation capabilities defend against emerging oat protein specialists threatening texture parity claims. Channel control through direct-to-consumer cold chain ownership anchors pricing power against supermarket private label entrants. For New Entrants and Emerging Players: TTB certification fast-track investments unlock first-mover placement in revised southern state regulatory environments before incumbents complete compliance documentation. Ontario and British Columbia provincial liquor authority frameworks present the most penetrable white-space for U.S. manufacturers with Health Canada pre-approval. Boutique store experiential retail positioning bypasses supermarket ABV ceiling constraints while capturing margin premiums from Manhattan and Los Angeles gourmet enthusiasts. For Investors and Strategic Acquirers: The market sits at a regulatory clarification phase that favors precision ABV calibration technology holders and licensed alcohol handler certification assets. Long-term viability centers on modular formulation platforms adaptable to jurisdiction-specific thresholds without complete product redesign. Acquisition target archetypes include flash-freezing nitrogen tunnel operators and Health Canada pre-approved cross-border manufacturers. Monitor Texas and Florida liquor control board final rule publications as inflection indicators for retail licensing tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Formulation Platform Development | Enables jurisdiction-specific ABV compliance without complete SKU redesign across fragmented state liquor boards. |
| Flash-Freezing Nitrogen Tunnel Acquisition | Secures sub-zero hardening capacity that prevents ethanol-induced crystallization defects in artisanal production. |
| Health Canada Pre-Approval Investment | Unlocks Ontario and British Columbia retail licensing pathways ahead of U.S. competitor cross-border expansion. |
| Bourbon-Barrel Aging Partnership | Creates provenance-differentiated premium SKUs through Kentucky distillery spent-barrel flavor extraction agreements. |
| Direct-to-Consumer Cold Chain Buildout | Bypasses traditional retail alcohol licensing constraints through insulated packaging and same-day metropolitan delivery. |
Research Methodology
Cross-validation between primary interviews with frozen dessert formulation chemists, state liquor board compliance officers, hospitality procurement directors, and licensed alcohol handler certification specialists anchors the qualitative findings. Secondary validation draws from TTB formula approval databases, FDA dairy safety protocol filings, Health Canada pre-approval records, and provincial liquor authority regulatory notices. Bottom-up SKU-level volume estimates and top-down category expenditure analysis triangulate market sizing across the projection horizon.
Sensitivity analysis tests forecast outputs against alternative ABV threshold scenarios and hospitality venue expansion trajectories in New York City, Los Angeles, and Toronto. The analytical framework models product type, alcohol type, distribution channel, and end user dimensions throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against aggregate category expansion. Forecast inputs include oat protein emulsion technology adoption curves and state legislative revision timelines for alcohol-in-food classifications.
Underlying assumptions cover stable TTB interstate labeling standards and gradual southern state licensing tier expansion, with deviation risk concentrated in unanticipated FDA dairy safety protocol amendments or abrupt Health Canada formula approval delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Grain-Free Pet Food Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Kosher Food Market
Specialty Foods
Moringa Products Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Heat-Stable Fruit Fillings Market