
 Therapeutic Dog Food Market | 2026-2036
Therapeutic Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Dog Food Market Insights
Pea protein is broadening formulation economics as manufacturers reduce reliance on traditional animal-based ingredients in therapeutic recipes. Hill's Pet Nutrition leverages its prescription diet heritage to dominate veterinary channel relationships. Purina PetCare sustains manufacturing scale across wet and dry therapeutic lines. Mars Petcare anchors global distribution infrastructure that supports regional customization of clinical nutrition products.
Therapeutic dog food comprises clinically formulated nutrition designed to manage, prevent, or alleviate specific canine health conditions through controlled ingredient profiles, nutrient modifications, and veterinary oversight. These products typically feature restricted sodium levels, adjusted protein-to-fat ratios, or novel protein sources to address pathologies ranging from renal dysfunction to food sensitivities, with manufacturing occurring under feed safety protocols that exceed conventional pet food standards. Prescription diets command the dominant margin pool due to veterinary endorsement requirements and restricted distribution, while limited ingredient diets represent the fastest-expanding category as allergy diagnoses multiply among companion animals. Wet food formulations attract premium positioning among aging dog populations with dental or digestive compromises, whereas dry therapeutic kibble retains volume leadership through shelf stability and cost efficiency.
The FDA Center for Veterinary Medicine regulates therapeutic pet food health claims and ingredient safety, compelling manufacturers to substantiate clinical efficacy before marketing disease-specific benefits. AAFCO nutrient profiles and state-level feed control officials collectively establish the compositional boundaries within which therapeutic products must operate, creating compliance moats that favor established producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving veterinary telehealth regulations and their potential to reshape prescription verification workflows across direct-to-consumer channels.
Market Dynamics
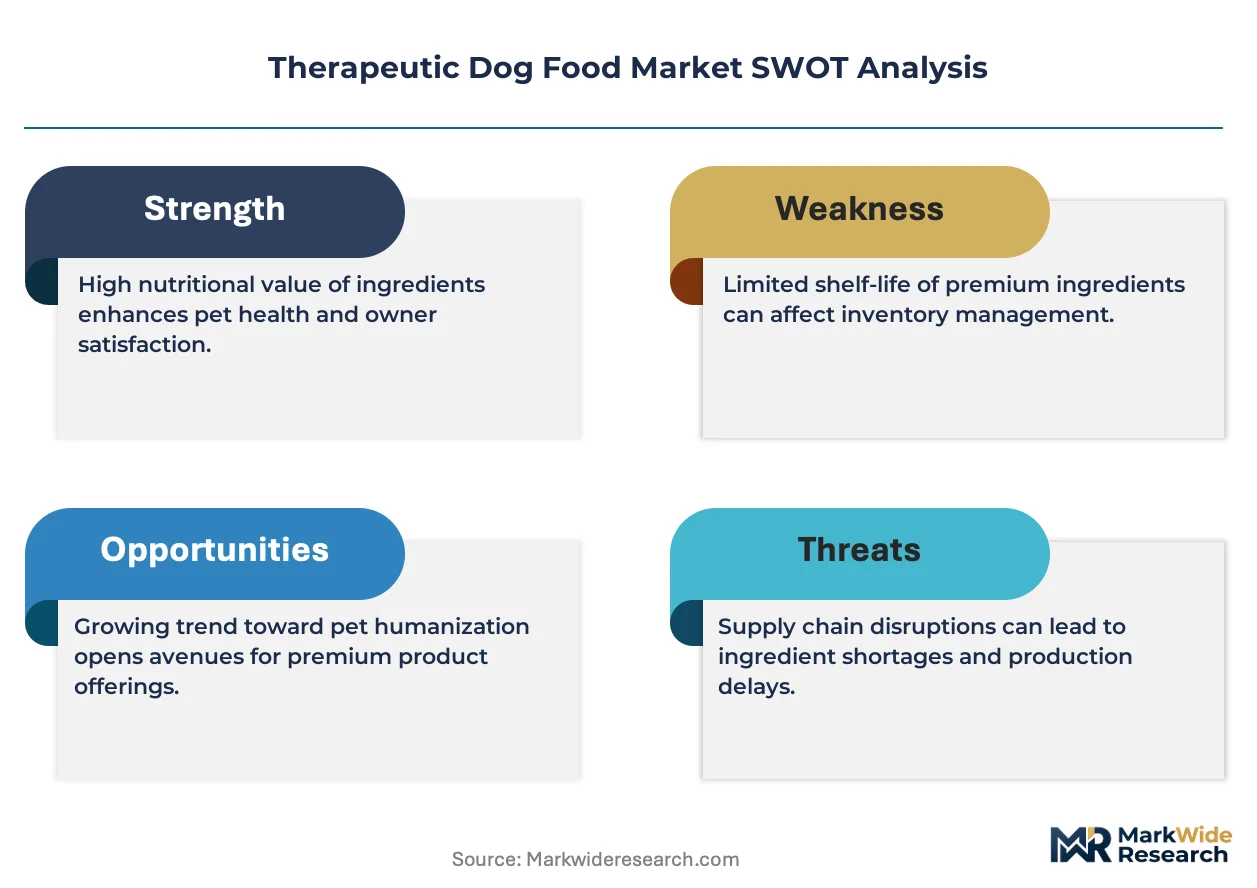
Veterinary clinics are consolidating their position as the primary distribution channel for prescription diets, creating a structural bottleneck that elevates compliance costs while locking out conventional retail competitors from the highest-margin therapeutic segments.
Growth Catalysts
- Pet Humanization Trajectory:Companion animal owners increasingly treat clinical nutrition as essential healthcare expenditure rather than discretionary spending, expanding addressable demand for renal, diabetic, and gastrointestinal formulations.
- FDA Center for Veterinary Medicine Oversight:Rigorous substantiation requirements for disease-specific health claims create compliance moats that protect established manufacturers from commodity entrants.
- Telehealth Integration:Veterinary telemedicine platforms are streamlining prescription verification workflows, reducing friction for chronic condition management and refill compliance.
Market Restraints
- Novel Protein Input Volatility:Kangaroo, venison, and hydrolyzed protein sources face supply concentration among Australian and New Zealand suppliers, exposing formulations to currency and shipping cost fluctuations.
- Veterinary Channel Gatekeeping:Prescription diet authorization requirements restrict direct-to-consumer sales, forcing manufacturers to absorb distributor margins and clinic stocking fees.
- AAFCO Nutrient Profile Rigidity:State-level feed control officials enforce compositional boundaries that limit formulation innovation for emerging pathologies not yet codified in official guidelines.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Telehealth-enabled prescription verification is converging with automated replenishment platforms, opening veterinary-endorsed bypass channels for chronic condition diets.
- Microbiome-Targeted Formulations:Fecal transplant science and postbiotic research are creating white space for gut-health positioning beyond traditional fiber modification.
- India Companion Animal Expansion:Rising veterinary infrastructure investment and pet humanization in metropolitan centers present first-mover positioning for renal and weight management diets.
Industry Challenges
- Veterinary Nutrition Specialist Shortage:Board-certified veterinary nutritionists represent the credential bottleneck for clinical trial design and regulatory submission, constraining new entrant pipeline velocity.
- Legacy ERP Integration:Prescription verification systems require real-time connectivity with clinic practice management software, forcing costly middleware development for regional manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Dog Food Market |
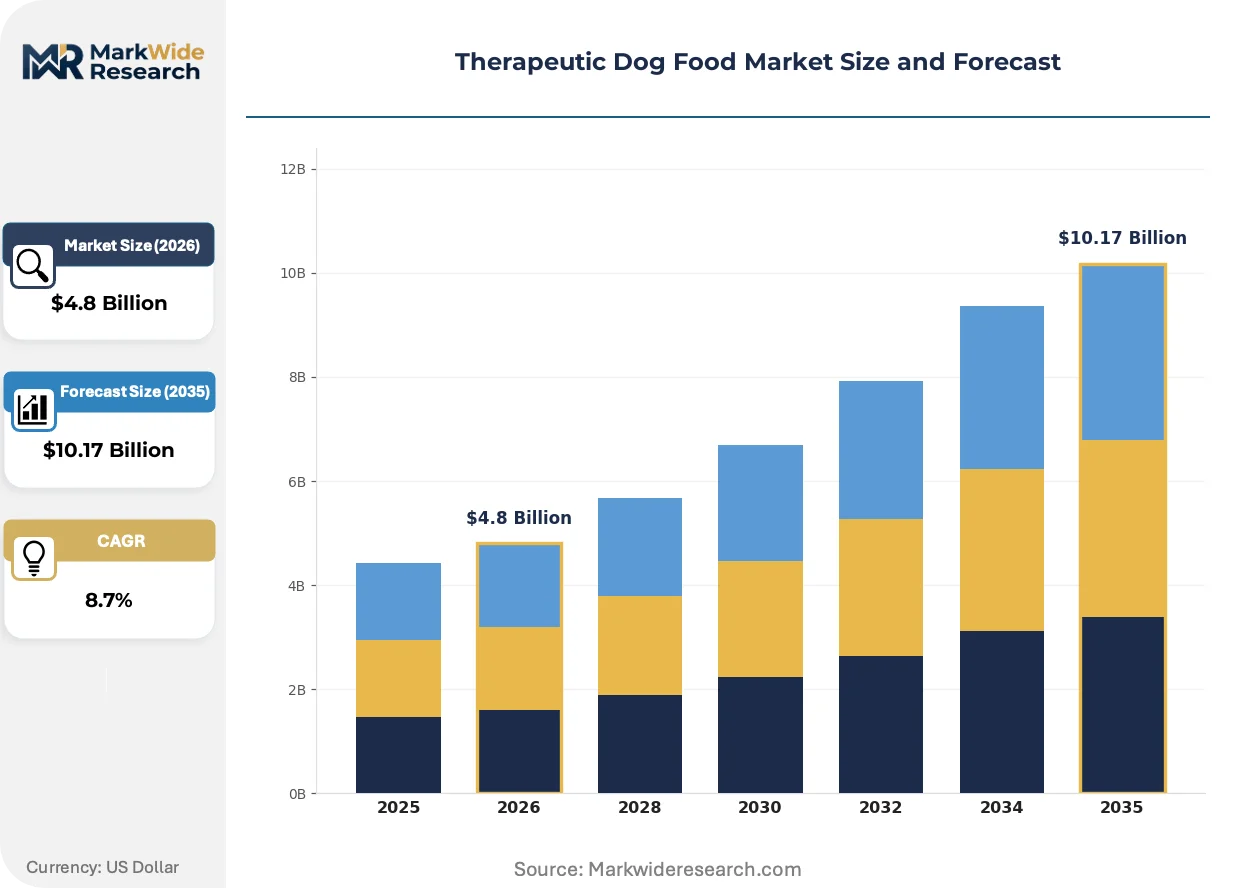
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Diet, Limited Ingredient Diet, Grain-Free Diet, Veterinary-Exclusive Diet Target Health Issue: Allergies, Obesity, Joint Health, Digestive Health Formulation Type: Dry Food, Wet Food, Freeze-Dried, Raw Food Distribution Channel: Pet Specialty Stores, Veterinarian Clinics, Online Retailers, Supermarkets |
| Companies Covered | Hill's Pet Nutrition, Purina PetCare, Mars Petcare, Blue Buffalo Company, Virbac, Diamond Pet Foods, JustFoodForDogs, Farmina Pet Foods, Rayne Clinical Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Dog Food Market Trends and Innovations
Precision nutrition platforms are displacing one-size-fits-all therapeutic categories, enabling condition-specific micro-segmentation that rewards manufacturers with granular clinical data assets.
Hydrolyzed protein technology is converging with mass spectrometry quality control, enabling molecular-level allergen detection that satisfies the most stringent veterinary dermatology protocols. Specialty and emergency veterinary hospitals are adopting these formulations at accelerated rates for refractory atopic cases. The structural consequence is compressing competitive differentiation around analytical capabilities rather than ingredient sourcing alone.
REACH chemical registration requirements in Europe are extending to novel feed additives and processing aids, compelling manufacturers to document full substance toxicity profiles before market entry. This regulatory burden disproportionately affects imported therapeutic lines seeking EU distribution. German and French veterinary wholesalers are consolidating supplier relationships to reduce compliance verification overhead.
Subscription-based replenishment models are displacing episodic clinic purchases for chronic conditions like renal insufficiency and diabetes. Pet owners in US coastal metropolitan areas are gravitating toward auto-ship platforms that integrate with telehealth follow-up protocols. This behavioral shift is compressing traditional veterinary clinic inventory turns while elevating manufacturer working capital requirements for fulfillment infrastructure.
Therapeutic Dog Food Market Segmentation
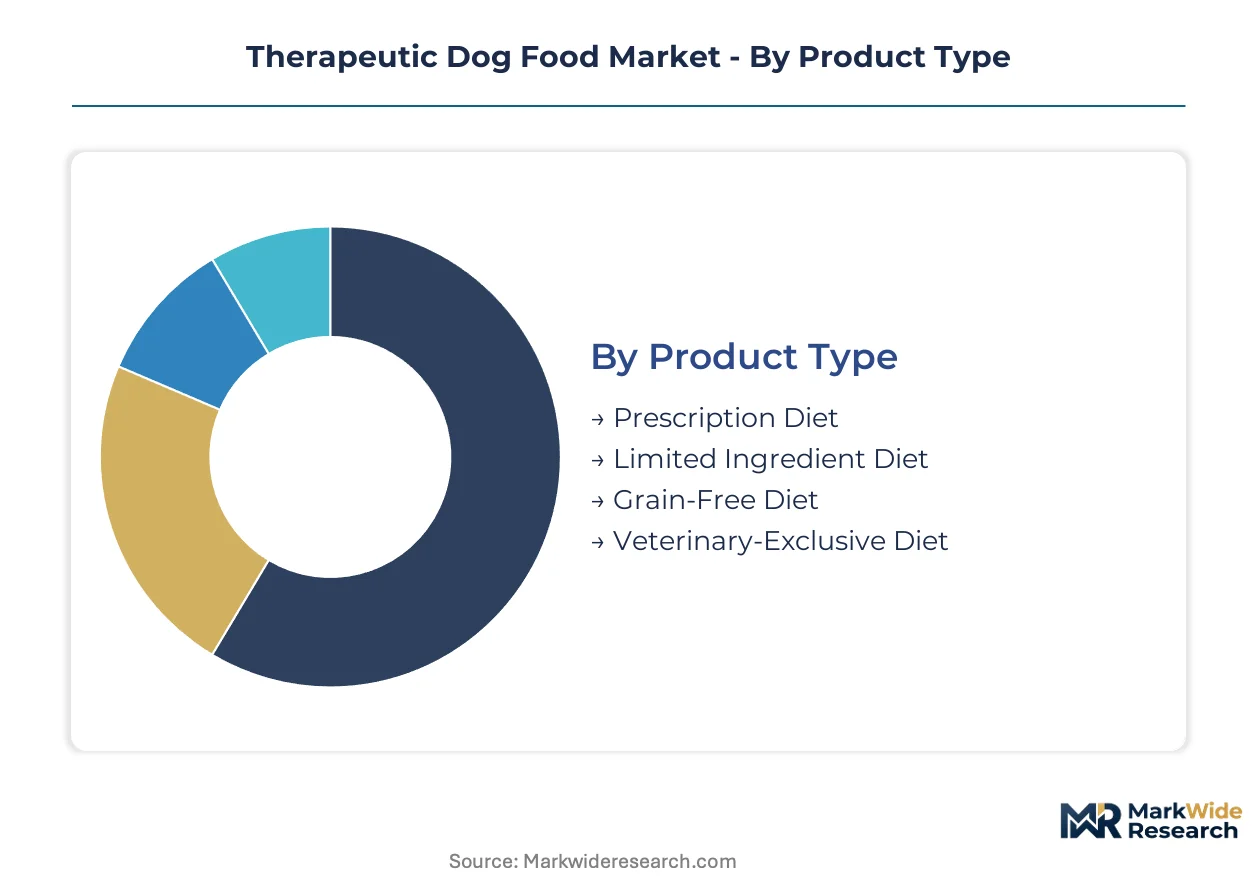
Therapeutic dog food segmentation reflects divergent clinical validation requirements and purchasing authority patterns across veterinary, retail, and direct channels. Manufacturers must align formulation investment with the specific compliance burdens and margin structures inherent to each category.
Product Type:
Veterinary authorization requirements and ingredient complexity separate buyers seeking clinically substantiated solutions from those managing mild sensitivities through retail alternatives.
- Prescription Diet:Formulations require veterinary diagnosis and ongoing supervision, featuring precise nutrient modifications for renal, hepatic, or diabetic pathologies. Demand concentrates among specialty and emergency veterinary hospitals in the United States, where pet insurance reimbursement sustains premium positioning. FDA Center for Veterinary Medicine oversight mandates clinical trial documentation for disease-specific claims.
- Limited Ingredient Diet:Restricted protein and carbohydrate sources address food allergies without requiring prescription authorization. Growth accelerates among millennial pet owners in metropolitan areas who self-diagnose sensitivities and prioritize ingredient transparency over clinical validation.
- Grain-Free Diet:Eliminates corn, wheat, and soy in favor of legume and tuber carbohydrates. Appeals to owners linking grain consumption to inflammatory conditions, though veterinary cardiologists have raised concerns about dilated cardiomyopathy associations.
- Veterinary-Exclusive Diet:Distributed solely through clinic channels with no retail or online availability. Captures the highest margin pool through enforced scarcity and professional endorsement requirements.
Prescription Diet leads volumes today; Limited Ingredient Diet is gaining share fastest.
Target Health Issue:
Chronic condition prevalence and diagnostic accessibility determine which therapeutic applications command sustained formulation investment versus episodic purchasing patterns.
- Allergies:Atopic dermatitis and food sensitivities drive the largest addressable population, with hydrolyzed protein and novel protein formulations capturing repeat purchasing loyalty. Veterinary dermatology referral networks in Germany and France anchor European demand concentration.
- Obesity:Calorie-restricted, high-fiber formulations address metabolic syndrome and osteoarthritis prevention. Growth reflects expanding veterinary weight management programs and wearable activity tracker integration.
- Joint Health:Glucosamine, chondroitin, and omega-3 fortified diets target osteoarthritis in aging large breeds. Demand clusters among owners of German Shepherds, Labrador Retrievers, and Golden Retrievers in suburban United States households.
- Digestive Health:Highly digestible proteins, prebiotic fibers, and postbiotic additives manage inflammatory bowel disease and chronic enteropathies. Prescription authorization requirements limit this segment to veterinary channel distribution.
Allergies dominates current revenue; Obesity shows the steepest expansion trajectory.
Formulation Type:
Moisture content and processing method trade off shelf stability against palatability, with buyer age and dental condition influencing format selection.
- Dry Food:Extruded kibble with precise nutrient density enables cost-effective chronic disease management and automated feeding systems. Retains volume leadership through warehouse club distribution and extended storage viability.
- Wet Food:Canned or pouch formats with elevated moisture content support renal function and appetite stimulation in geriatric or ill animals. Premium positioning reflects higher protein inclusion and manufacturing complexity.
- Freeze-Dried:Minimal processing preserves raw nutrient integrity while eliminating pathogen risks through sublimation dehydration. Appeals to raw feeding advocates seeking veterinary-compatible safety profiles.
- Raw Food:Unprocessed meat, bone, and organ formulations with probiotic supplementation. Faces regulatory scrutiny from state-level feed control officials over Salmonella and Listeria contamination risks.
Dry Food maintains the largest installed base; Wet Food is climbing the fastest among aging dog populations.
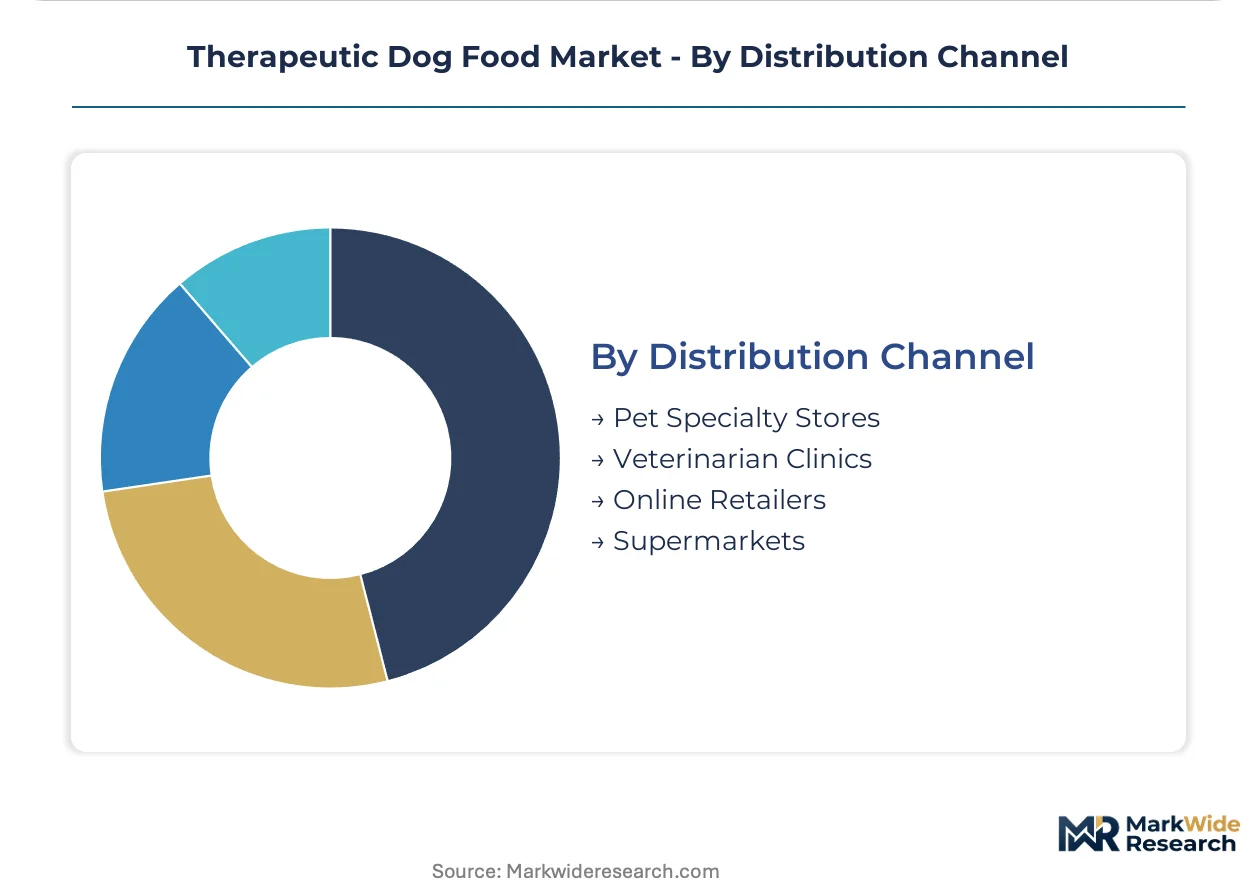
Distribution Channel:
Channel selection determines prescription verification requirements, margin capture, and customer relationship ownership between manufacturers and intermediaries.
- Veterinarian Clinics:Exclusive distribution for prescription diets with real-time health monitoring and compliance tracking. Captures the highest per-unit margins through professional endorsement and diagnosis-linked purchasing.
- Online Retailers:Telehealth-enabled prescription verification is expanding authorized access beyond physical clinic footprints. Chewy and Amazon Pet are investing in veterinary pharmacy licensure to capture chronic condition replenishment.
- Pet Specialty Stores:Curated assortment of limited ingredient and grain-free options with trained staff consultation. Petco and PetSmart are expanding in-store veterinary clinics to bridge prescription and retail segments.
- Supermarkets:Mass-market therapeutic positioning through limited ingredient and digestive health SKUs. Price compression and slotting fee structures favor manufacturers with national scale.
Veterinarian Clinics anchor current volume; Online Retailers are expanding most quickly through subscription automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States veterinary spending sustains the dominant cluster for therapeutic formulation development and prescription diet distribution.
United States
Pet humanization trends and high disposable incomes drive premium positioning for renal and diabetic formulations. FDA Center for Veterinary Medicine oversight mandates clinical trial documentation for disease-specific health claims. Specialty veterinary hospitals in Boston and Los Angeles anchor prescription diet adoption for chronic condition management.
Germany
Veterinary dermatology referral networks concentrate demand for hydrolyzed protein and novel protein diets. REACH chemical registration requirements extend to novel feed additives, elevating compliance burdens for imported therapeutic lines. Munich and Berlin host the densest clusters of specialty animal hospitals prescribing clinical nutrition protocols.
France
Expanding pet insurance reimbursement sustains premium pricing for prescription gastrointestinal and weight management diets. EFSA guidelines on feed additive safety influence formulation standards across domestic manufacturers. The Lyon veterinary corridor drives regional concentration of allergy and digestive health diet prescriptions.
United Kingdom
Telehealth-enabled veterinary services accelerate subscription-based replenishment for chronic condition diets. FSA feed hygiene regulations govern manufacturing standards for therapeutic products distributed through veterinary channels. The Greater London metropolitan area generates the highest per-capita spending on veterinary-exclusive formulations.
Japan
Aging dog populations and geriatric care specialization elevate demand for renal support and joint health diets. METI standards on pet food manufacturing safety shape quality protocols for domestic and imported therapeutic lines. Tokyo and Osaka veterinary medical centers lead adoption of precision nutrition platforms for metabolic disease management.
Therapeutic Dog Food Market Competitive Landscape
Global majors compete with regional champions across veterinary channel relationships and regulatory compliance capacity. The market structure consolidates around three tiers: multinational conglomerates with dedicated prescription diet divisions, mid-scale specialists with veterinary-exclusive distribution, and emerging direct-to-consumer platforms leveraging telehealth verification. Strategic archetypes include veterinary channel gatekeepers, novel protein sourcing specialists, and microbiome research pioneers. Competitive moves center on acquiring board-certified veterinary nutritionist expertise and integrating real-time prescription verification with clinic practice management software.
Within the multinational conglomerate tier, Hill's Pet Nutrition, Purina PetCare, and Mars Petcare occupy positions defined by manufacturing scale and veterinary endorsement heritage. These entities exemplify the veterinary channel gatekeeper archetype through exclusive clinic distribution networks. Hill's Pet Nutrition represents the prescription diet heritage model. Purina PetCare anchors wet and dry therapeutic manufacturing capabilities. Mars Petcare sits within global distribution infrastructure supporting regional customization of clinical nutrition products.
| Leading Market Players |
|---|
| Hill's Pet Nutrition |
| Purina PetCare |
| Mars Petcare |
| Blue Buffalo Company |
| Virbac |
| Diamond Pet Foods |
| JustFoodForDogs |
| Farmina Pet Foods |
| Rayne Clinical Nutrition |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap manufacturers in Italy and Spain anchor the European therapeutic dog food landscape, preserving pricing discipline through controlled ingredient sourcing and limited private-label exposure. Their ownership structures insulate margin targets from quarterly earnings pressure, enabling sustained investment in novel protein supply relationships that commodity competitors cannot replicate.
Pricing Analysis
Input-cost pass-through from kangaroo and hydrolyzed protein suppliers runs through prescription diet tiers faster than limited ingredient alternatives. Pricing stratifies across veterinary-authorized, retail-clinical, and mass-market economy tiers, with certification grade under FDA Center for Veterinary Medicine oversight commanding the widest spreads. Cost compression in grain-free formulations is intensifying due to legume carbohydrate substitution. Pet specialty store buyers exhibit the highest price sensitivity, while specialty veterinary hospital procurement committees prioritize clinical validation over per-unit cost.
Supply Chain Analysis
Ocean freight cost volatility from Australian and New Zealand novel protein exporters is forcing inventory repositioning among North American distributors. Manufacturing concentrates in the United States, Germany, and Thailand, with Thailand serving as the primary hub for hydrolyzed protein processing. Raw material dependencies center on venison, pea protein isolates, and omega-3 fish oil concentrates. Single-source vulnerability from Australian kangaroo meat suppliers exposes formulations to currency and biosecurity disruption. Distribution runs through veterinary clinic direct accounts, telehealth-enabled subscription platforms, and pet specialty retail with in-store veterinary partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through microbiome-targeted premium tier development and telehealth-enabled subscription automation that reduces customer acquisition costs. Pea protein economics and precision nutrition platform scale provide structural cost-down drivers.
For Market Incumbents: Anchor prescription diet market share through exclusive veterinary channel relationships and real-time practice management software integration that locks out competitor prescription verification. Defend against direct-to-consumer platform entrants by acquiring telehealth pharmacy licensure in coastal metropolitan clusters. Vertical integration into hydrolyzed protein processing secures supply against Australian supplier concentration. For New Entrants and Emerging Players: The gap between premium prescription diets and economy limited ingredient alternatives opens white space for mid-tier clinically validated formulations. Target metropolitan India and Southeast Asia veterinary infrastructure expansion as the most penetrable geography. Pursue partnership-first go-to-market positioning with regional veterinary distributors lacking multinational direct relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among European mid-scale therapeutic specialists with REACH-compliant manufacturing and concentrated German-French veterinary channel presence. Long-term viability across the projection horizon rests on regulatory affairs capacity and board-certified veterinary nutritionist retention. Acquisition target archetypes include microbiome research platforms with companion animal application pipelines. Watch telehealth prescription verification regulatory clarity as the inflection signal for direct-to-consumer channel economics.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Integration | Real-time prescription verification with clinic practice management software locks in distribution control. |
| Novel Protein Supply Agreement | Long-term offtake contracts with Australian and New Zealand suppliers hedge currency and biosecurity exposure. |
| Microbiome Platform Development | Postbiotic and fecal transplant science applications create premium tier differentiation beyond fiber modification. |
| Telehealth Pharmacy Licensure | Direct-to-consumer subscription automation captures chronic condition replenishment outside clinic inventory. |
| Precision Nutrition Data Assets | Granular clinical outcome databases enable condition-specific micro-segmentation and veterinary endorsement. |
Research Methodology
Coverage spans the United States, Germany, France, the United Kingdom, and Japan, with primary inputs from each market's veterinary nutrition specialists and distribution channel managers. The research combines structured interviews with board-certified veterinary nutritionists, regulatory affairs directors at therapeutic pet food manufacturers, specialty veterinary hospital procurement leads, and telehealth platform operators with secondary validation from FDA Center for Veterinary Medicine filings, AAFCO nutrient profile databases, EFSA feed additive safety assessments, and national veterinary medical association prescription diet utilization surveys. Bottom-up demand modeling and top-down manufacturer capacity triangulation cross-verify volume estimates.
Rate-of-change decomposition separates volume expansion from mix-shift and pricing trajectory across the analysis window. The analytical framework models therapeutic dog food demand by product authorization tier, target health condition, moisture format, and distribution channel structure, with regional regulatory cluster overlay for compliance cost differentiation. CAGRs derive from segmented growth rate blending weighted by current revenue concentration. Veterinary telehealth adoption curves and pet insurance reimbursement expansion patterns inform chronic condition diet replenishment velocity assumptions.
The model assumes a particular technology adoption path for hydrolyzed protein quality control and microbiome-targeted formulation development; alternative pathways for precision nutrition platform deployment would alter the outlook for manufacturer competitive differentiation. Forecasts reflect assumptions about regulatory clarity for direct-to-consumer prescription verification and the pace of veterinary infrastructure investment in emerging markets. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Silver Food Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Free-From Food Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Algeria Couscous Market
Specialty Foods
Global Nata De Coco Market
Specialty Foods
United States Tofu Market
Specialty Foods
North America Popping Boba/Juice Balls Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Low Calorie Popsicles Market