
 Chamomile Market | 2026-2036
Chamomile Market Size, Share, and Industry Trends Forecast 2026-2036
Chamomile Market Intelligence
Organic certification under USDA NOP and EU Council Regulation 834/2007 is bifurcating the supplier base into certified and conventional tiers. Martin Bauer Group leverages its vertical integration from field cultivation to extract refinement to sustain premium positioning in pharmaceutical channels. Associated British Foods plc anchors its chamomile sourcing through long-term grower contracts in Egypt and Argentina.
Chamomile comprises dried flower heads of Matricaria chamomilla or Chamaemelum nobile species, typically standardized to 0.3–1.5% essential oil content and 2–5% flavonoid concentration for therapeutic applications. German chamomile extract dominates pharmaceutical and dietary supplement formulations due to higher matricin content, while chamomile essential oil commands margin pools in personal care and aromatherapy segments. Roman chamomile occupies niche premium positioning in artisanal cosmetics and high-end tea blends.
FDA dietary supplement GMPs, EFSA Novel Food approvals, and EU Organic Regulation shape ingredient purity thresholds and market access timelines for new suppliers. India's FSSAI and CDSCO are tightening import testing protocols for botanical extracts used in Ayurvedic-integrated products. Stakeholders must monitor evolving pharmacopeial monograph revisions and adapt extraction technologies to meet tightening heavy metal and pesticide residue limits.
Market Dynamics
EU Novel Food regulations and tightening organic certification standards are bifurcating the supplier base, forcing extractors to invest in traceability infrastructure while pharmaceutical-grade demand concentrates procurement power among vertically integrated processors.
Growth Catalysts
- Pharmaceutical-grade matricin standardization:German chamomile extract with elevated matricin content is securing preferred supplier status in dietary supplement formulations targeting sleep and gastrointestinal health applications.
- EU Council Regulation 834/2007 organic mandates:Certification requirements for ingredient traceability are locking in long-term contracts between processors and certified cultivation zones, reducing spot market volatility.
- Egyptian cultivation infrastructure:Nile Delta irrigation networks and established drying facilities provide cost-competitive raw material throughput for essential oil distillation operations serving personal care manufacturers.
Market Restraints
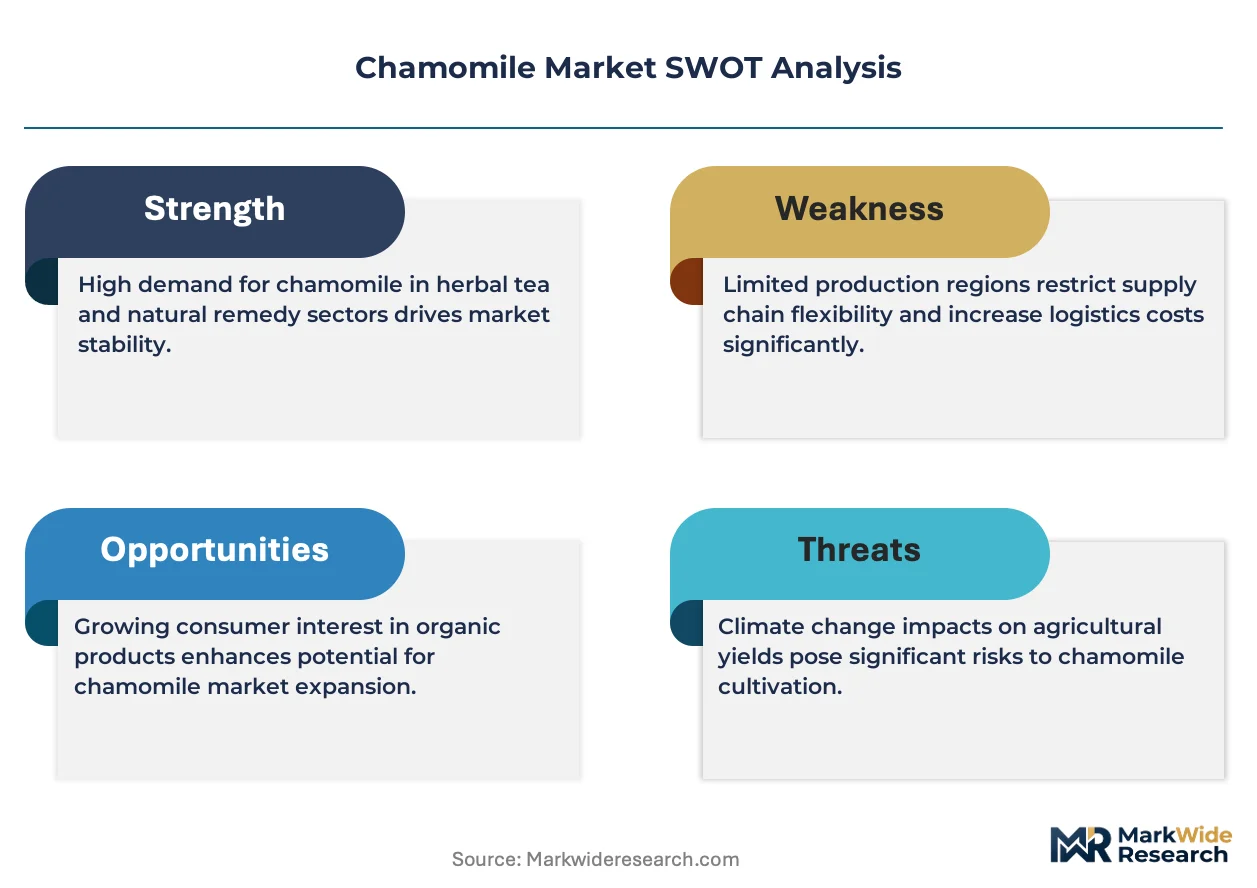
- Input cost volatility:Climate-induced fluctuations in Egyptian and Argentinian harvest yields create raw material price instability for non-integrated processors lacking captive cultivation.
- Regulatory friction:India's FSSAI import testing protocols for botanical extracts impose extended clearance timelines and batch rejection risk for Ayurvedic-integrated product suppliers.
- Substitution threat:Synthetic linalool and bisabolol compounds from petrochemical feedstocks compete with natural chamomile essential oil in mass-market personal care formulations.
Strategic Opportunities
- Underpenetrated German pharmaceutical channel:Established herbal medicine tradition creates pull-through demand for standardized extracts in prescription-adjacent sleep aids and anxiolytic supplements.
- Technology convergence:Supercritical CO2 extraction paired with molecular distillation enables higher purity fractions for cosmeceutical applications previously served by lower-grade solvent extracts.
- Regulatory tailwind:FDA dietary supplement GMP enforcement is elevating barrier-to-entry for uncertified suppliers, consolidating volume toward compliant processors with documented supply chain controls.
Industry Challenges
- Certification timeline compression:USDA NOP and EU organic dual-certification requirements demand 18-36 month field conversion periods, constraining rapid capacity expansion for new entrants.
- Heavy metal compliance capex:Pharmacopeial monograph revisions tightening lead and cadmium thresholds force extractors to deploy ion exchange and activated carbon purification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chamomile Market |
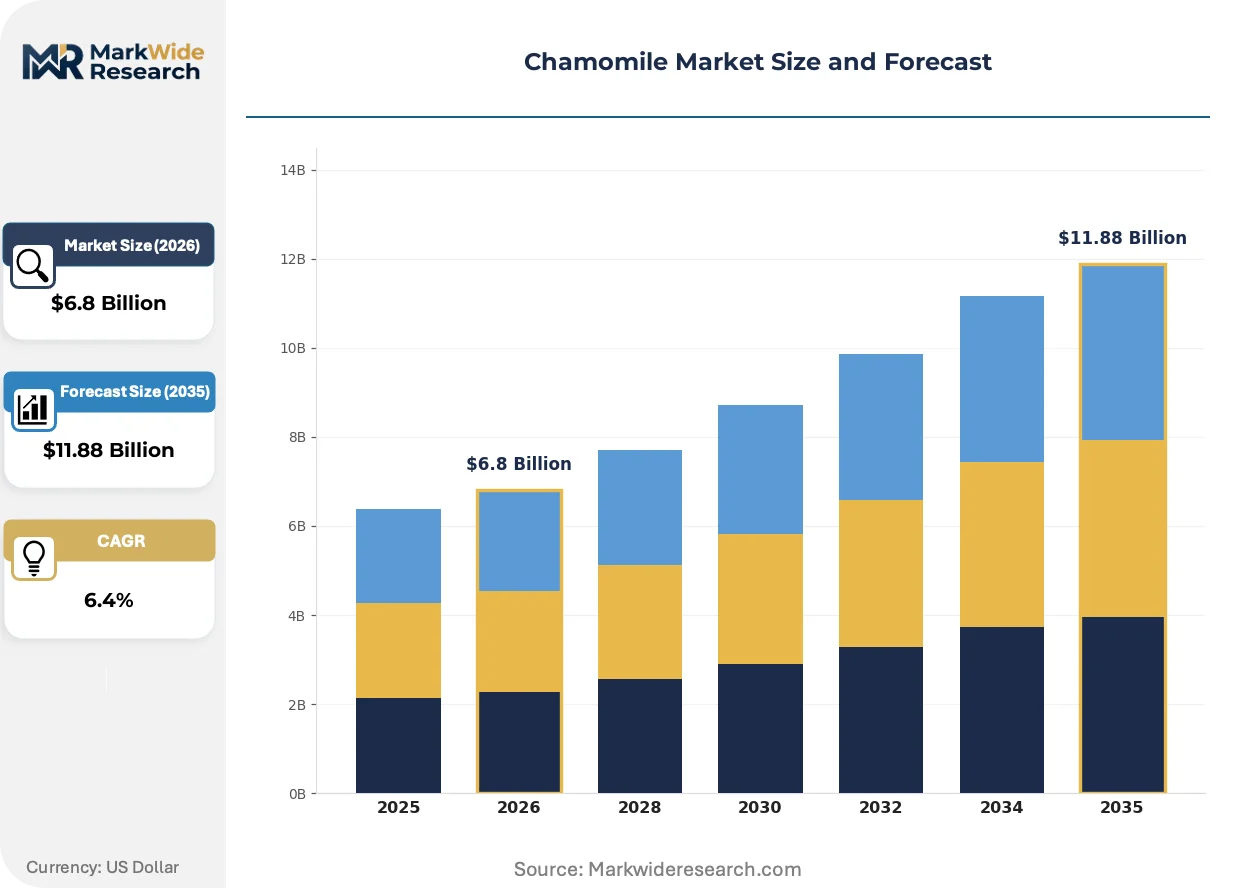
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roman Chamomile, German Chamomile, Chamomile Extract, Chamomile Essential Oil Application: Tea, Cosmetics, Dietary Supplements, Herbal Remedies End User: Households, Food & Beverage Industry, Pharmaceuticals, Personal Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Martin Bauer Group, Associated British Foods plc, Unilever, The Pharmaceutical Plant Company, Celestial Seasonings, Tata Consumer Products Limited, Kemin Industries, Inc., Changsha Vigorous-Tech Co., Ltd., Arjuna Natural Extracts Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chamomile Market Strategic Shifts & Innovations
Extraction technology advances and regulatory disclosure mandates are restructuring competitive advantage around purity verification capabilities rather than raw scale, while demand-side certification preferences reshape procurement hierarchies.
Supercritical CO2 extraction systems are supplanting traditional steam distillation and hexane solvent methods in high-value pharmaceutical and cosmeceutical applications. German and Swiss processors are adopting these systems to meet pharmacopeial monograph specifications for residual solvent limits. The technology is enabling premium positioning in dietary supplement channels where heavy metal and pesticide documentation determines supplier selection.
REACH registration requirements and EFSA Novel Food approval pathways are tightening substance safety documentation obligations for botanical extracts entering EU food and supplement channels. Compliance costs are concentrating market access among established processors with dedicated regulatory affairs capabilities. Small-scale Argentinian and Egyptian suppliers without EU-established importers are retreating to aromatherapy and cosmetic applications with lower documentation burdens.
Certification-driven procurement hierarchies are elevating dual-certified organic and pharmacopeial-grade suppliers above conventional tier offerings in German and Austrian retail pharmacy channels. Buyers are unbundling spot purchases in favor of multi-year supply agreements with processors offering batch-level traceability documentation. This pattern is most visible in Munich and Vienna distribution corridors serving compounding pharmacies and herbal medicine practitioners.
Chamomile Market Segmentation
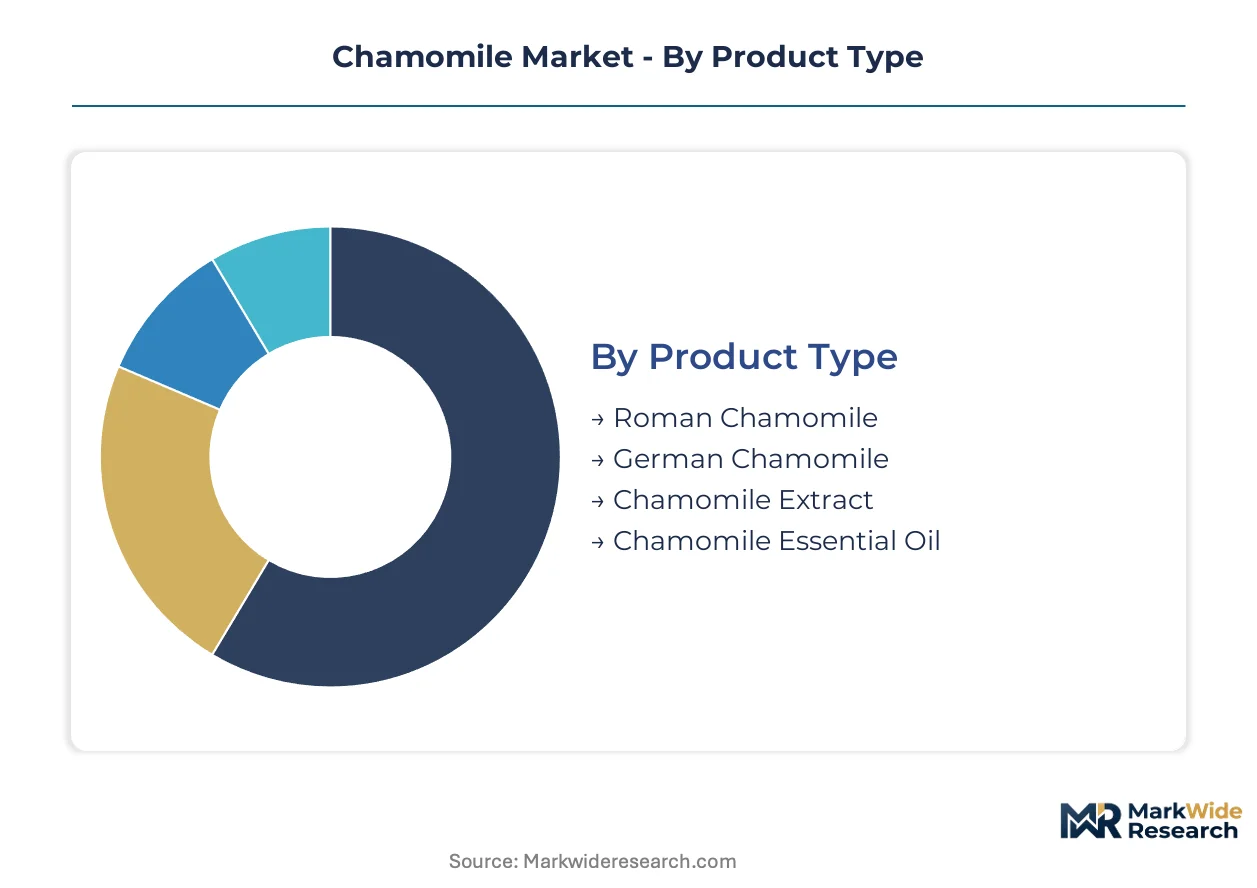
Chamomile market segmentation reflects divergent purity requirements and regulatory burdens across therapeutic versus commodity applications. Product type and application categories show the sharpest bifurcation between pharmaceutical-grade premiums and mass-market substitution vulnerability.
Product Type:
Synthetic bisabolol and petrochemical-derived linalool exert the strongest substitution pressure on commodity segments, while standardized extracts defend position through pharmacopeial compliance.
- German Chamomile:Higher matricin and chamazulene content defines pharmaceutical-grade specifications for dietary supplements targeting sleep and gastrointestinal applications. German processors command premium positioning through EFSA Novel Food dossiers and pharmacopeial monograph adherence.
- Chamomile Extract:Standardized flavonoid and essential oil fractions supply cosmeceutical and prescription-adjacent supplement formulations. Supercritical CO2 extraction systems in Germany and Switzerland enable heavy metal compliance for EU pharmacy channel access.
- Roman Chamomile:Lower azulene content restricts use to artisanal cosmetics and premium tea blends where ester-rich profiles justify niche positioning.
- Chamomile Essential Oil:Steam-distilled fractions serve aromatherapy and mass personal care, facing direct competition from synthetic fragrance compounds in cost-sensitive formulations.
German Chamomile anchors the volume base while Chamomile Extract gains share at the steepest rate.
Application:
Application segments stratify by documentation burden, with pharmaceutical-adjacent categories requiring batch-level traceability that conventional suppliers cannot provide.
- Dietary Supplements:Standardized matricin content and FDA dietary supplement GMP compliance determine supplier selection for sleep aid and anxiolytic formulations. German retail pharmacy channels pull through prescription-adjacent demand with documented supply chain controls.
- Cosmetics:Cosmeceutical formulations demand heavy metal and pesticide residue documentation, favoring processors with ion exchange purification and activated carbon filtration systems.
- Herbal Remedies:Traditional medicine practitioners in Germany and Austria source pharmacopeial-grade dried flower heads through compounding pharmacy networks.
- Tea:Commodity-grade dried flowers face price compression from Egyptian and Argentinian spot market supply, with organic certification premiums concentrated in German and Austrian retail channels.
Tea retains the broadest volume footprint while Dietary Supplements expands most quickly.
End User:
End user concentration reflects procurement capability divergence between institutional buyers with regulatory affairs infrastructure and fragmented household demand.
- Pharmaceuticals:Vertically integrated processors supply standardized extracts with EMA-quality documentation for compounding pharmacies and herbal medicine practitioners in Munich and Vienna corridors.
- Personal Care:Mass-market manufacturers source Egyptian-derived essential oils for fragrance applications, while premium cosmeceutical brands specify Swiss and German supercritical extracts.
- Food & Beverage Industry:Tea blenders and functional beverage manufacturers require FSSAI-compliant documentation for India-destined Ayurvedic-integrated products, constraining supplier eligibility.
- Households:Direct-to-consumer sales concentrate in German organic retail and online channels, with certification premiums visible in USDA NOP and EU dual-certified offerings.
Pharmaceuticals commands the highest margin tier while Personal Care delivers the steepest volume expansion.
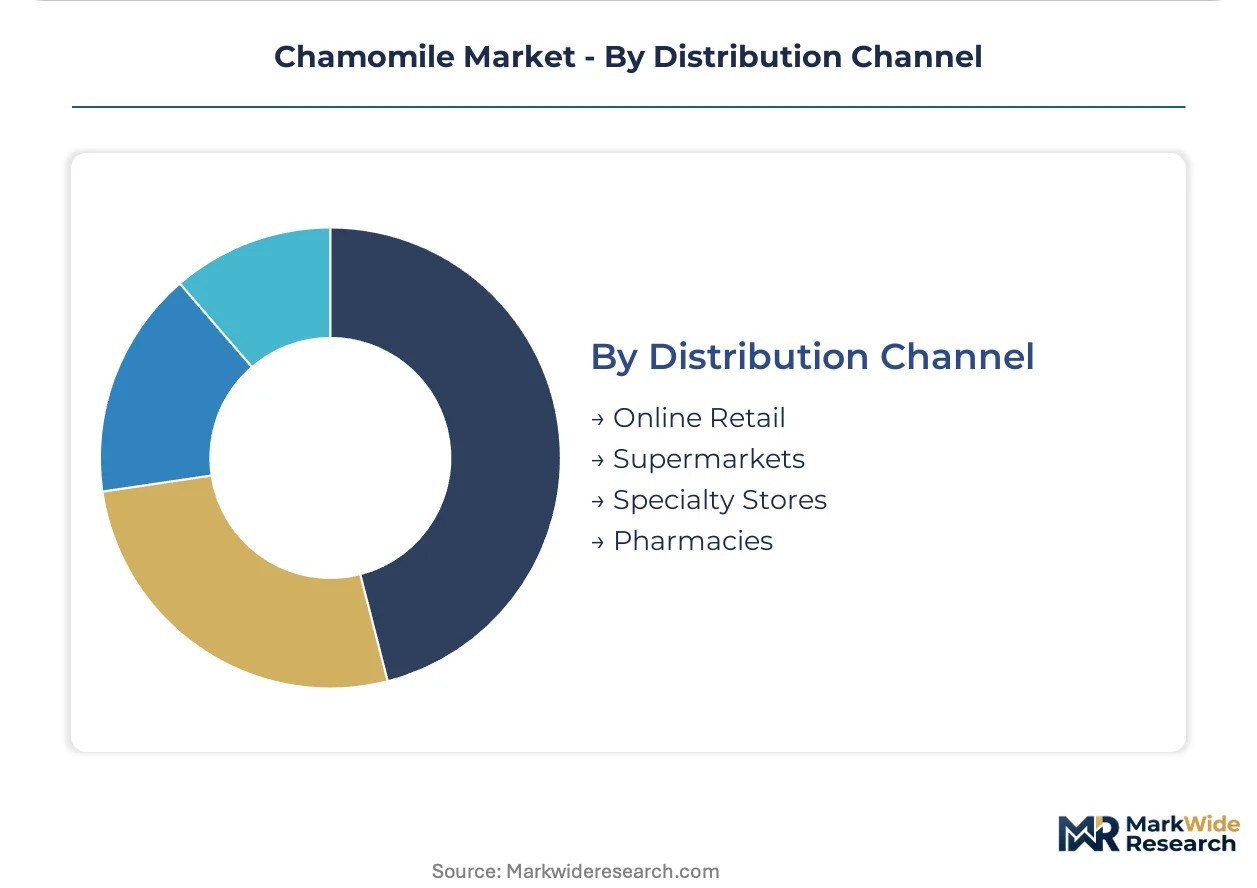
Distribution Channel:
Channel structure reflects documentation requirements and customer education needs, with regulatory complexity favoring intermediaries over direct sourcing.
- Pharmacies:German and Austrian pharmacy chains enforce pharmacopeial-grade sourcing with batch-level traceability, locking in multi-year supply agreements with certified processors.
- Specialty Stores:Organic and herbal medicine retailers in Berlin and Vienna curate dual-certified product lines, serving practitioners and informed consumers with documentation demands.
- Online Retail:Direct-to-consumer platforms aggregate conventional and certified tiers, with transparency requirements elevating established processor brands over commodity traders.
- Supermarkets:Mass retail channels in Germany stock conventional-grade tea and personal care products, with organic SKUs concentrated in premium private label lines.
Pharmacies defend the highest margin structure while Online Retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade buyers concentrate procurement power in Germany and Austria, while personal care manufacturers source cost-competitive essential oils from Egyptian and Argentinian cultivation zones. Tea blenders and Ayurvedic-integrated product suppliers drive secondary demand clusters in India and select Southeast Asian markets.
Germany
Retail pharmacy chains and compounding herbal medicine practitioners anchor demand for pharmacopeial-grade German chamomile extracts. EFSA Novel Food dossier requirements and EU Council Regulation 834/2007 organic mandates shape supplier eligibility. Munich and Stuttgart corridors host vertically integrated processors supplying standardized matricin fractions to prescription-adjacent sleep aid formulations.
Egypt
Nile Delta irrigation networks and established flower-drying infrastructure support cost-competitive essential oil distillation for personal care manufacturers. Egyptian cultivation serves European fragrance houses and mass-market cosmetic brands seeking steam-distilled fractions. Alexandria and Kafr El Sheikh processing clusters export bulk essential oil to German and Swiss refiners.
India
Ayurvedic-integrated dietary supplement manufacturers drive import demand for botanical extracts meeting FSSAI and CDSCO testing protocols. Domestic tea blenders source conventional-grade dried flowers for mass-market chai formulations. Mumbai and Ahmedabad distribution hubs handle clearance logistics for imported extracts destined to herbal medicine practitioners.
Argentina
Organic-certified cultivation zones in Córdoba and Santa Fe provinces supply EU-destined raw material for processors seeking USDA NOP and EU dual-certification. Argentinian growers face retreat from food-grade channels due to REACH registration documentation burdens. Buenos Aires export infrastructure channels volume toward aromatherapy and cosmetic applications with lower regulatory thresholds.
Switzerland
Swissmedic-registered processors deploy supercritical CO2 extraction systems to supply cosmeceutical brands demanding heavy metal-compliant fractions. Premium positioning in dietary supplement channels leverages proximity to German retail pharmacy demand. Basel and Zurich clusters specialize in molecular distillation for high-purity bisabolol isolation.
Chamomile Market Key Industry Players
Player mix skews toward vertically integrated agricultural processors and diversified food conglomerates with captive botanical supply chains. Market structure exhibits tiered concentration, with pharmaceutical-grade channels consolidating around certified processors while commodity tea and essential oil segments retain fragmented spot-market dynamics. Strategic archetypes include field-to-extract integrators, long-term contract anchor buyers, and regional cultivation specialists. Dominant competitive moves encompass backward integration into certified cultivation zones and multi-year supply agreement locking with pharmacy distribution networks.
Within the integrated processor tier, Martin Bauer Group exemplifies field-to-extract control spanning German cultivation through pharmacopeial-grade refinement. Associated British Foods plc anchors commodity sourcing through Egyptian and Argentinian grower contracts, occupying a position bridging agricultural procurement and branded consumer goods. Changsha Vigorous-Tech Co., Ltd. represents Chinese extract specialists serving cosmeceutical manufacturers with standardized flavonoid fractions.
| Leading Market Players |
|---|
| Martin Bauer Group |
| Associated British Foods plc |
| Unilever |
| The Pharmaceutical Plant Company |
| Celestial Seasonings |
| Tata Consumer Products Limited |
| Kemin Industries, Inc. |
| Changsha Vigorous-Tech Co., Ltd. |
| Arjuna Natural Extracts Ltd |
| Others |
Cost & Logistics Intelligence
EU Council Regulation 834/2007 organic certification gates both supplier qualification and price differentiation simultaneously, bifurcating procurement into certified premium tiers and conventional spot markets while compressing margins for non-compliant processors. German retail pharmacy chains enforce pharmacopeial-grade documentation requirements that translate into multi-year contract premiums, whereas Egyptian and Argentinian spot supply feeds commodity tea and fragrance channels at volatile cost-plus terms.
Pricing Analysis
Cost-plus contracts with Egyptian essential oil indexation anchor personal care procurement, while German pharmaceutical buyers negotiate fixed-price multi-year agreements for standardized matricin extracts. Three-tier pricing structure across premium, standard, and economy levels separates EFSA Novel Food-compliant processors from conventional extractors and spot-market traders. Pricing pressure stems from synthetic bisabolol substitution in mass-market cosmetics, compressing natural essential oil premiums. Household consumers through German organic retail channels show least price sensitivity, while mass-market tea blenders exhibit highest elasticity to Egyptian spot fluctuations.
Supply Chain Analysis
Nile Delta drying infrastructure chokepoints underwrite Egyptian essential oil throughput to European fragrance houses, constraining surge capacity during climate-induced harvest shortfalls. Raw material supply draws from German certified cultivation, Egyptian Nile Delta conventional zones, and Argentinian Córdoba organic regions. Input dependencies center on irrigation water access, pharmacopeial-grade drying equipment, and supercritical CO2 extraction systems. Single-source vulnerability concentrates in Egyptian flower drying during Q3 harvest windows. Distribution runs through Munich and Vienna pharmacy distribution corridors for pharmaceutical grades, with Alexandria bulk export handling commodity essential oil flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chamomile procurement is shifting toward platform-economics dynamics where batch-level traceability documentation interoperability determines supplier lock-in, with EFSA Novel Food dossier databases and USDA NOP certification registries creating ecosystem switching costs.
For Market Incumbents: Fortify backward integration into German certified cultivation zones to defend matricin standardization premiums against Egyptian spot-market volatility. Secure multi-year pharmacy distribution agreements in Munich and Stuttgart corridors before FDA dietary supplement GMP enforcement elevates compliance barriers. Deploy ion exchange purification capex ahead of pharmacopeial heavy metal threshold revisions to maintain EMA-quality documentation leadership. For New Entrants and Emerging Players: USDA NOP fast-track certification for Argentinian Córdoba cultivation unlocks white-space access to German dual-certified retail pharmacy channels underserved by incumbent capacity constraints. Target Swiss cosmeceutical manufacturers seeking secondary supercritical CO2 extraction suppliers with heavy metal-compliant fractions. Pursue compounding pharmacy direct sales in Vienna and Berlin specialty retail corridors as lowest-friction go-to-market pathway. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German field-to-extract processors lacking EFSA Novel Food regulatory affairs depth for portfolio expansion. Long-term viability hinges on 5-10 year regulatory compliance moat sustainability rather than commodity scale. Monitor FDA dietary supplement GMP enforcement intensity as inflection signal for consolidation acceleration among uncertified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Cultivation | Captures margin pool from field to pharmacopeial-grade extract in German pharmacy channels. |
| Supercritical CO2 Extraction Deployment | Enables heavy metal compliance for EMA-quality documentation serving Swiss cosmeceutical brands. |
| EFSA Novel Food Dossier Investment | Secures preferred supplier status in prescription-adjacent dietary supplement formulations. |
| Multi-Year Pharmacy Distribution Agreements | Locks in Munich and Vienna corridor volume against spot-market volatility. |
| Dual Certification Program | USDA NOP and EU organic alignment opens German retail pharmacy and Austrian herbal practitioner access. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU Novel Food registration databases, pharmacopeial monograph revisions, and customs trade data for Egyptian and Argentinian chamomile exports. Primary interviews engaged extraction technology specialists, regulatory affairs directors at German processors, pharmacy procurement managers in Munich and Vienna, and Egyptian cultivation cooperative representatives. Secondary validation drew from EFSA Novel Food dossier filings, USDA NOP certification registries, and FDA dietary supplement GMP inspection records. Bottom-up volume estimates from cultivation area and yield assumptions triangulated against top-down pharmaceutical and personal care consumption trends.
Segmentation dimensions modeled span product type, application, end user, and distribution channel across the analysis window, with regional clusters for Germany, Egypt, Argentina, India, and Switzerland. CAGRs derived from regression against historical pharmaceutical-grade extract pricing and personal care essential oil volume trends. Industry-specific forecast inputs incorporated EFSA Novel Food approval timelines, pharmacopeial monograph revision schedules, and FDA GMP enforcement intensity trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained EU organic certification stringency and stable Nile Delta irrigation access; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as climate-induced Egyptian harvest volatility and synthetic bisabolol substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
GCC Halal Food Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Curculin Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Europe Hummus Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Tahini Market
Specialty Foods
Global Freeze-Dried Pet Food Market