
 Areca Bowl Market | 2026-2036
Areca Bowl Market Size, Share, and Industry Trends Forecast 2026-2036
Areca Bowl Market Outlook
Plastic is repositioning downward across European foodservice procurement as areca leaf bowls capture cost-parity at volume. Ziffe Exports Private Limited leverages captive plantation networks in Karnataka to secure raw material consistency. Conservia Ecocrafts India Private Limited anchors premium positioning through EU-compliant sterilization protocols. Gaah Green Products Private Limited competes on wholesale pricing for North American bulk buyers.
Areca bowls are rigid, compostable containers pressed from fallen sheaths of Areca catechu palm, typically measuring 4-10 inches in diameter with natural wax coatings that resist liquid penetration for 2-4 hours. Restaurants and catering services represent the dominant demand channel where single-use plastic bans have eliminated incumbent alternatives. Online retail is expanding fastest among distribution channels as direct-to-foodservice platforms bypass traditional import intermediaries. Decorative usage remains niche but commands margin premiums through lacquered finishes and custom shaping for hospitality gifting.
EU REACH compliance and F-Gas Regulation indirectly shape areca bowl competitiveness by elevating synthetic alternative costs. India's BIS standards for biodegradable disposables and the US FDA's food-contact substance notifications govern export market access. Stakeholders must monitor evolving compostability certification requirements across target jurisdictions to maintain shelf placement.
Market Dynamics
EU Single-Use Plastics Directive enforcement is systematically eliminating plastic serveware from European foodservice channels, redirecting procurement budgets toward biodegradable alternatives with established compostability credentials.
Growth Catalysts
- REACH Regulation compliance costs:Synthetic alternative manufacturers face elevated testing and registration burdens under ECHA protocols, narrowing the price gap with areca leaf products in German and French foodservice procurement.
- India PLI scheme for biodegradable manufacturing:Production-linked incentives for compostable tableware are concentrating capacity expansion in Karnataka and Tamil Nadu processing clusters.
- Quick-service restaurant chains:Pan-Asian fast-casual brands operating in the United Kingdom and Netherlands are mandating areca bowl specifications for takeaway packaging to meet corporate sustainability targets.
Market Restraints
- Monsoon-dependent raw material flows:Areca sheath collection in India's Western Ghats faces 3-4 month seasonal interruptions that compress processing margins and create spot shortages.
- Single-origin supply risk:Karnataka plantations supply over 60% of export-grade sheaths, concentrating geopolitical and climate exposure in one sub-national zone.
- Composting infrastructure gaps:Industrial composting facility scarcity in the United States and United Kingdom forces areca bowls into landfill streams, undermining their environmental value proposition and inviting regulatory scrutiny.
Strategic Opportunities
- Vietnam export processing zones:Da Nang and Ho Chi Minh City logistics corridors offer tariff-advantaged re-export positioning for EU-bound shipments under EVFTA provisions.
- Cold-chain food delivery:Insulated areca bowl variants with natural fiber linings are penetrating meal-kit and premium grocery delivery channels in France and Germany.
- BIS certification harmonization:India's national standards for biodegradable disposables are gaining recognition equivalence with EU EN 13432 protocols, streamlining dual-market access for certified manufacturers.
Industry Challenges
- Mold fabrication technician scarcity:Precision aluminum die production for bowl pressing equipment requires skilled machinists concentrated in Coimbatore and Rajkot industrial clusters, creating hiring bottlenecks for capacity expansion.
- Compostability certification timelines:TÜV Austria and DIN CERTCO validation cycles extend 8-14 months for new product geometries, delaying market entry for seasonal promotional designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Areca Bowl Market |
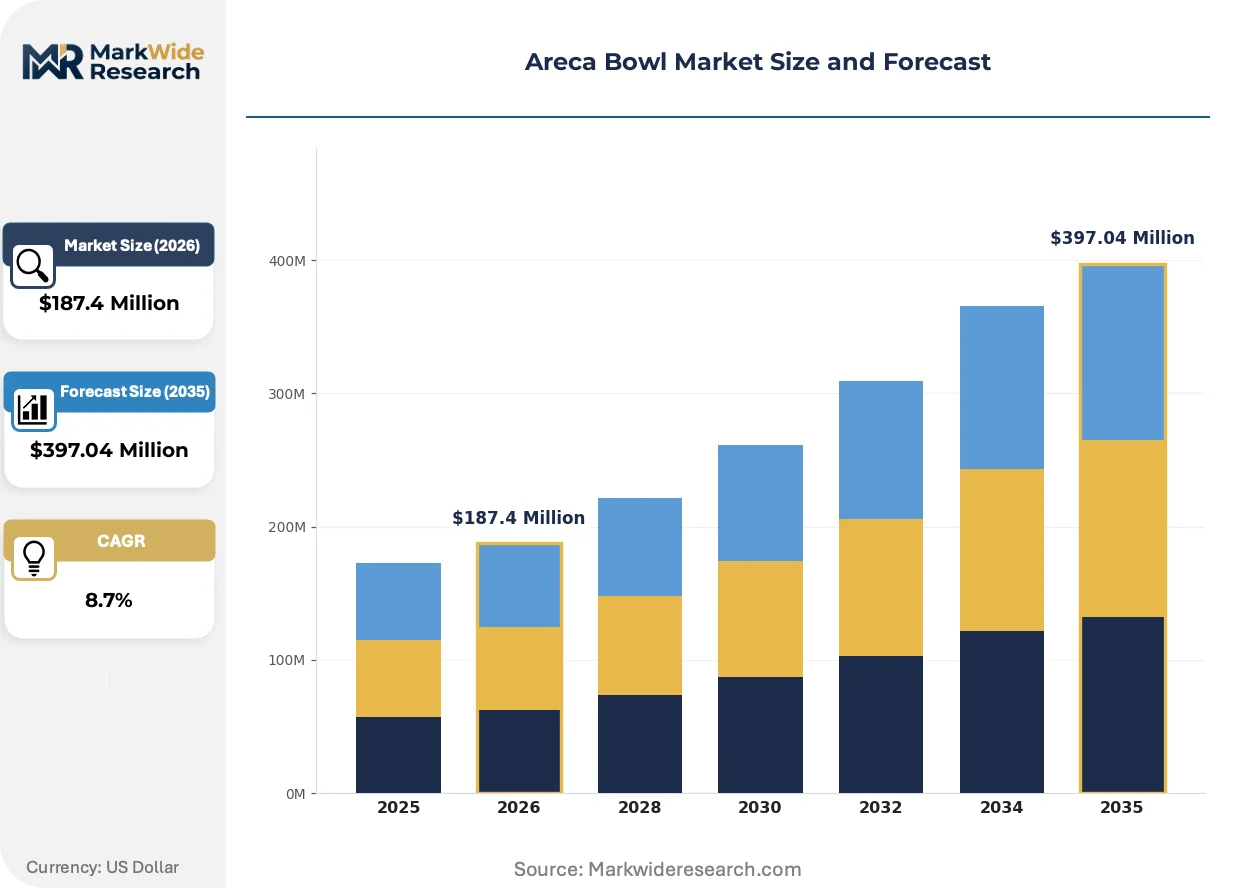
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Natural Areca Leaf, Plastic, Biodegradable Material, Paper Usage Type: Disposable, Reusable, Decorative, Utility End User: Restaurants, Catering Services, Home Use, Events Distribution Channel: Online Retail, Wholesale, Supermarkets, Specialty Stores |
| Companies Covered | Ziffe Exports Private Limited, Vetrivelavan Enterprise, Bannariamman, Conservia Ecocrafts India Private Limited, Eco-Mithra, Vigna Exports, Gaah Green Products Private Limited, Eco Planet, Srinivasa Traders, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Areca Bowl Market Strategic Shifts
Mechanical pressing automation and surface treatment chemistry are converging to extend areca bowl functional performance beyond traditional liquid resistance limits, opening substitution opportunities in previously unserved food categories.
Plasma-enhanced wax deposition is expanding into high-fat-content foodservice applications previously reserved for synthetic barriers. French contract caterers serving corporate cafeterias in Lyon and Marseille are piloting these enhanced bowls for hot sauce and oil-based dressing containment. The technology is expanding into premium positioning where 4-6 hour liquid resistance commands 35-50% price premiums over standard grades.
EU F-Gas Regulation phase-down schedules are accelerating synthetic foam and insulated plastic alternative cost inflation across European cold-chain packaging. German food distributors report 18-24 month procurement contract renegotiations favoring natural fiber insulation composites including areca-based solutions. Cold logistics operators in Hamburg and Rotterdam port zones are responding with pilot programs testing areca-fiber hybrid containers for seafood and dairy export shipments.
Direct-to-foodservice platform procurement is displacing traditional import intermediary relationships across North American and European mid-market restaurant segments. Web-based sourcing portals operated by Indian and Vietnamese exporters now handle specification negotiation, certification verification, and container logistics in consolidated workflows. This channel shift is most visible in United Kingdom independent restaurant groups and United States fast-casual chains with 15-50 location footprints seeking transparent origin documentation for ESG reporting requirements.
Areca Bowl Market Segmentation
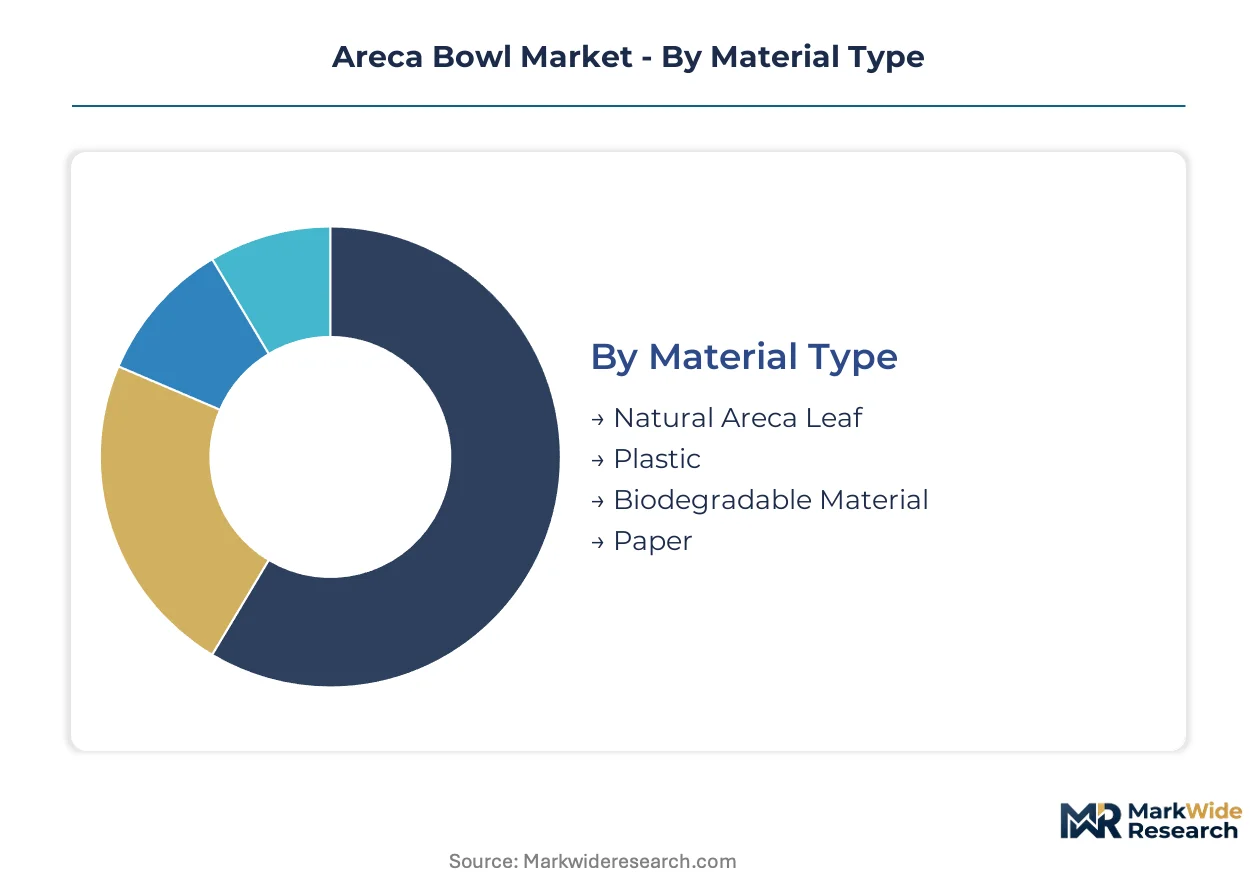
Segmentation in the Areca Bowl Market reveals how material specifications, usage patterns, and channel structures create distinct competitive arenas. Each axis exposes different margin profiles and regulatory exposure, from compostability certification requirements to direct procurement platform economics.
Material Type:
Material composition determines functional performance thresholds and regulatory compliance pathways across foodservice applications.
- Natural Areca Leaf:Pressed from fallen Areca catechu sheaths with natural wax coatings providing 2-4 hour liquid resistance. EU Single-Use Plastics Directive enforcement in Germany and France is redirecting procurement budgets toward this grade for restaurant serveware replacement.
- Biodegradable Material:Engineered compounds combining areca fiber with cassava or bagasse binders to accelerate decomposition timelines. BIS certification harmonization efforts in India are streamlining dual-market access for manufacturers targeting both domestic and EU export channels.
- Plastic:Polypropylene and polystyrene alternatives facing systematic phase-out across European foodservice channels under REACH compliance cost escalation.
- Paper:Kraft and molded pulp variants with limited liquid resistance, positioned in cold food applications where cost minimization dominates procurement criteria.
Natural Areca Leaf leads on scale; Biodegradable Material leads on momentum.
Usage Type:
Usage patterns segment the market by replacement frequency and value-added service potential.
- Disposable:Single-use containers for takeaway and event service, capturing volume concentration in quick-service restaurant chains across the United Kingdom and Netherlands with mandated sustainability specifications.
- Decorative:Lacquered and custom-shaped variants for hospitality gifting and premium table settings, commanding margin premiums through artisan finishing in Karnataka processing clusters.
- Reusable:Reinforced areca-composite designs for limited-cycle applications, positioned in corporate cafeteria contracts seeking durability without synthetic material exposure.
- Utility:Unfinished bowls for industrial and agricultural applications outside foodservice, absorbing seasonal raw material oversupply during monsoon collection peaks.
Disposable dominates procurement volumes; Decorative climbs the fastest on margin expansion.
End User:
End-user concentration shapes certification requirements and order size distribution.
- Restaurants:Full-service and fast-casual establishments in France, Germany, and the United Kingdom replacing plastic serveware under EU directive enforcement, driving specification standardization for compostability credentials.
- Catering Services:Contract foodservice operators piloting plasma-enhanced wax deposition variants for hot sauce and oil-based dressing containment in Lyon and Marseille corporate cafeterias.
- Events:Wedding and festival rental demand for decorative areca bowls, concentrated in Indian domestic market seasonal peaks and European summer outdoor dining.
- Home Use:Individual consumers purchasing through online retail channels, expanding fastest among distribution modalities as direct-to-foodservice platforms bypass traditional import intermediaries.
Restaurants anchor procurement scale; Catering Services gain share fastest on premium application development.
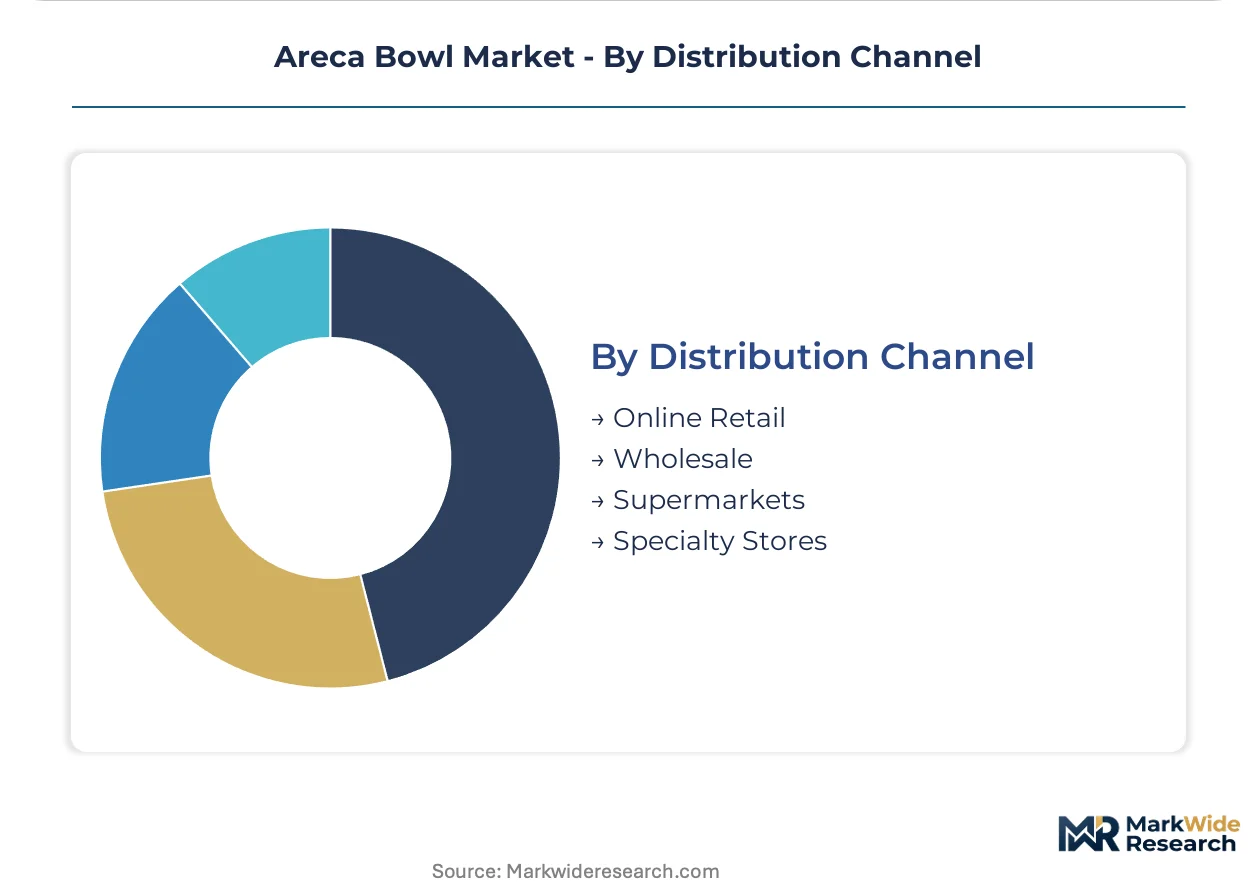
Distribution Channel:
Channel structure determines origin documentation transparency and ESG reporting compliance access.
- Online Retail:Web-based sourcing portals operated by Indian and Vietnamese exporters consolidating specification negotiation, certification verification, and container logistics for United Kingdom independent restaurant groups and United States fast-casual chains.
- Wholesale:Traditional import intermediary relationships serving North American and European mid-market segments, facing displacement pressure from platform-based procurement consolidation.
- Supermarkets:Retail shelf placement for home use segments, dependent on industrial composting facility proximity to validate environmental claims in United States and United Kingdom markets.
- Specialty Stores:Eco-product boutiques and zero-waste shops curating premium decorative grades with full supply chain traceability documentation.
Wholesale retains volume concentration; Online Retail expands most quickly on procurement workflow consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Karnataka's plantation belt generates the dominant share of export-grade areca sheaths, with processing clusters in Mysuru and Shivamogga supplying European and North American foodservice channels under EU Single-Use Plastics Directive compliance timelines.
Germany
Quick-service restaurant chains and contract caterers in Berlin and Hamburg are replacing plastic serveware with compostable alternatives. ECHA REACH compliance costs for synthetic manufacturers are narrowing price gaps with areca leaf products. The Rhine-Ruhr logistics corridor is consolidating import distribution for EU-bound shipments.
United Kingdom
Independent restaurant groups with 15-50 location footprints are sourcing directly through web-based procurement platforms. The country's national environmental regulator enforces packaging waste regulations that redirect procurement budgets toward certified biodegradable alternatives. London foodservice distributors are piloting plasma-enhanced wax deposition variants for extended liquid resistance.
France
Corporate cafeteria operators in Lyon and Marseille are testing enhanced areca bowls for hot sauce and oil-based dressing containment. EU F-Gas Regulation phase-down schedules are accelerating synthetic foam alternative cost inflation. The Port of Rotterdam-adjacent cold logistics operators are responding with pilot programs for seafood export shipments.
India
BIS certification harmonization efforts are streamlining dual-market access for manufacturers targeting domestic and EU export channels. The national standards body is gaining recognition equivalence with EU EN 13232 protocols. Tamil Nadu processing clusters are expanding capacity under PLI scheme incentives for biodegradable tableware production.
Vietnam
Da Nang and Ho Chi Minh City logistics corridors offer tariff-advantaged re-export positioning for EU-bound shipments under EVFTA provisions. Export processing zone expansion is concentrating supply-side investment in Southeast Asian manufacturing. The country's central economic zone authority is streamlining customs clearance for certified compostable disposables.
Areca Bowl Market Competitive Environment
Global majors compete with regional champions across certification and distribution reach, with market structure tiering between plantation-integrated processors and specialized export houses. The vendor base clusters around three strategic archetypes: captive plantation operators securing raw material consistency, sterilization protocol specialists anchoring premium positioning, and wholesale pricing competitors serving North American bulk buyers. Capacity expansion and direct-to-foodservice platform development represent the dominant competitive moves.
Among Indian exporters, Ziffe Exports Private Limited, Conservia Ecocrafts India Private Limited, and Gaah Green Products Private Limited occupy distinct positioning vectors. Ziffe Exports exemplifies the plantation-integrated archetype through Karnataka-based raw material control. Conservia Ecocrafts represents the compliance-specialist tier with EU-aligned sterilization capabilities. Gaah Green Products sits within the volume-driven wholesale segment targeting price-sensitive North American procurement.
| Leading Market Players |
|---|
| Ziffe Exports Private Limited |
| Vetrivelavan Enterprise |
| Bannariamman |
| Conservia Ecocrafts India Private Limited |
| Eco-Mithra |
| Vigna Exports |
| Gaah Green Products Private Limited |
| Eco Planet |
| Srinivasa Traders |
| Others |
Value Chain & Pricing Dynamics
Certification-grade stratification between EU EN 13432-compliant sterilization protocols and standard domestic-grade processing creates divergent margin architectures across the areca bowl value chain. Premium-tier producers in Karnataka command 35-50% price premiums through TÜV Austria validation, while commodity processors absorb monsoon-driven raw material volatility through spot-market sheath sourcing.
Pricing Analysis
Input-cost pass-through from areca sheath collection dominates pricing dynamics across processing tiers. Contract-based long-term offtake agreements anchor volume procurement for quick-service restaurant chains in Germany and France, insulating buyers from seasonal spot-price spikes. Price differentiation hinges on compostability certification tier and sterilization protocol alignment, with EU-compliant grades carrying substantial premiums over BIS-standard domestic product. Pricing pressure stems from monsoon-dependent collection interruptions in the Western Ghats, compressing processor margins during July-October supply troughs. North American wholesale buyers exhibit highest price sensitivity, while French contract caterers prioritize performance specifications over unit cost.
Supply Chain Analysis
Certification/qualification gating through TÜV Austria and DIN CERTCO validation cycles creates 8-14 month entry barriers for new product geometries. Geographic supply concentration centers on India, Vietnam, and emerging processing capacity in Bangladesh. Raw material dependencies rest on fallen areca sheaths, aluminum pressing dies from Coimbatore toolshops, and plasma-enhanced wax deposition chemicals. Single-origin vulnerability in Karnataka's plantation belt—supplying over 60% of export-grade sheaths—concentrates climate and geopolitical exposure. Distribution runs through direct-to-foodservice web platforms displacing traditional import intermediaries across United Kingdom and North American mid-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The areca bowl market operates as a regulatory compounder where EU Single-Use Plastics Directive enforcement systematically eliminates plastic alternatives and redirects procurement budgets toward certified biodegradable serveware.
For Market Incumbents: Cement raw material security through captive plantation networks or long-term collection contracts in Karnataka's Western Ghats belt. Expand sterilization protocol capacity to capture premium-tier margins as TÜV Austria validation becomes table stakes for EU foodservice access. Defend against Vietnamese export processing zone competitors by accelerating BIS-EN 13432 dual-certification harmonization. For New Entrants and Emerging Players: Direct-to-foodservice web platforms offer the lowest-friction entry vector for mid-market restaurant groups seeking transparent origin documentation. Target United States fast-casual chains with 15-50 location footprints where procurement centralization favors platform-based sourcing over traditional import relationships. Penetrate cold-chain food delivery segments through insulated areca-fiber hybrid development for meal-kit applications. For Investors and Strategic Acquirers: Asymmetric upside sits with plantation-integrated processors possessing captive raw material control and existing EU certification infrastructure. Five-to-ten year viability favors operators with backward integration into sheath collection and forward integration into direct-platform distribution. Monitor BIS-EN protocol recognition equivalence milestones as inflection indicators for dual-market access scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Plantation Network Development | Karnataka-based raw material control insulates processors from monsoon-driven spot price volatility. |
| Dual-Certification Investment | Simultaneous BIS and EN 13432 compliance streamlines access to Indian domestic and EU export channels. |
| Plasma-Enhanced Wax Deposition Scale-Up | French contract caterers in Lyon and Marseille pilot extended liquid resistance for premium positioning. |
| Direct-to-Foodservice Platform Launch | Web-based procurement portals consolidate specification negotiation and certification verification for UK restaurant groups. |
| Vietnam Export Processing Zone Entry | Da Nang and Ho Chi Minh City logistics corridors offer tariff-advantaged re-export positioning under EVFTA provisions. |
Study Parameters
Multiple input streams — plantation operator interviews, foodservice procurement manager surveys, and customs trade data — were reconciled to construct supply-side and demand-side estimates. Primary engagement with Karnataka processing cluster managers, German quick-service restaurant supply chain directors, and Vietnamese export processing zone authorities informed operational assumptions. Secondary validation drew from EU ECHA regulatory filings, BIS standards documentation, and India PLI scheme disbursement records. Bottom-up capacity modeling and top-down demand segmentation were cross-referenced for convergence.
Data-stream reconciliation across material type, usage pattern, end-user concentration, and distribution channel dimensions anchored the analytical framework. Segmentation modeling captured natural areca leaf versus biodegradable material grade splits, disposable versus decorative usage bifurcation, and online retail versus wholesale channel dynamics. CAGRs were derived from installed processing capacity expansion trajectories and EU directive enforcement timelines. Forecast inputs incorporated monsoon seasonality patterns and composting infrastructure development gaps in target markets.
Monsoon failure severity, EU certification timeline extensions, and industrial composting facility deployment shortfalls are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding regulatory enforcement consistency and raw material collection labor availability. A model refresh is warranted upon material change in BIS-EN protocol recognition equivalence status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Goldenseal Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Algeria Couscous Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Poke Food Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Aloe Vera Gel Market