
 Keto Low-Calorie Meals Market | 2026-2036
Keto Low-Calorie Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Keto Low-Calorie Meals Market Analytics
Market Context with Strategic Players
Quick-service restaurant digital ordering infrastructure is reconfiguring how keto low-calorie meals reach consumers. Chipotle Mexican Grill leverages its customizable bowl platform to anchor ketogenic positioning across urban markets. Wendy's sustains competitive pressure with protein-focused menu engineering that targets carbohydrate-restricted diets. Subway differentiates through transparent macro labeling and vegetable-forward customization protocols that appeal to calorie-conscious segments.
Technical Definition and Structural Segments
Keto low-calorie meals are prepared food products formulated to maintain ketogenic macronutrient ratios—typically under fifty grams of net carbohydrates daily—while restricting caloric density through controlled fat and protein portions, often employing sous-vide or flash-freezing processes to preserve nutrient integrity. These products serve consumers pursuing metabolic ketosis for weight management, glycemic control, or athletic performance optimization. Frozen meals occupy the largest volume position due to extended shelf stability and batch production economics, while meal kits capture the fastest expansion as subscription logistics mature and home preparation preferences persist. Online retail channels concentrate margin pools through direct-to-consumer data capture and recurring revenue structures, though supermarkets retain dominant physical touchpoints for trial and impulse purchase.
Regulatory Framework and Forward Outlook
The FDA governs nutritional labeling accuracy and health claim substantiation for packaged keto meals, while the USDA oversees ingredient sourcing standards and organic certification pathways applicable to protein and vegetable inputs. State-level health departments impose additional prepared-food safety protocols that vary across jurisdictions, creating compliance complexity for multi-state distribution. Stakeholders must monitor evolving FDA guidance on carbohydrate disclosure methodologies and anticipate how state-level sodium reduction mandates could reformulate existing product architectures.
Market Dynamics
Corporate wellness procurement is accelerating category volume as employers subsidize ketogenic meal programs for metabolic health outcomes. This institutional demand channel is restructuring production scheduling and contract pricing architectures away from pure retail velocity.
Growth Catalysts
- USDA Organic Certification:Protein and vegetable suppliers achieving organic status command premium placement in retail freezer sections, expanding addressable shelf space for compliant keto meal producers.
- Flash-Freezing Technology:Cryogenic freezing systems preserve micronutrient density in prepared proteins, extending product integrity windows and reducing cold-chain spoilage rates.
- United States:Established keto diet communities and health-conscious consumer clusters in coastal metropolitan areas generate sustained repeat purchase velocity and subscription retention.
Market Restraints
- Avocado Oil Price Volatility:Primary fat source for ketogenic formulations experiences agricultural yield fluctuations that compress gross margins during supply contractions.
- Midwest Dairy Concentration:Specialty cheese inputs for high-fat meal components source from limited geographic supplier bases, creating single-source vulnerability.
- FDA Carbohydrate Disclosure Methodologies:Evolving guidance on net versus total carbohydrate reporting creates label redesign costs and consumer confusion friction.
Strategic Opportunities
- Germany:Underdeveloped ketogenic retail infrastructure presents first-mover advantage for frozen meal entrants targeting carbohydrate-aware consumers in DACH markets.
- AI-Driven Personalization:Machine learning algorithms analyzing biometric data enable customized macro ratios, converging nutrition science with digital health platforms.
- Direct-to-Employer Distribution:Bypassing retail markup through corporate cafeteria and benefits platform integration captures institutional procurement budgets.
Industry Challenges
- Food Safety Certification Timelines:HACCP validation for novel low-moisture ketogenic formulations extends product launch cycles by six to nine months.
- Legacy ERP Integration:Subscription meal kit operators struggle to synchronize recurring billing systems with batch production scheduling software.
Report Scope
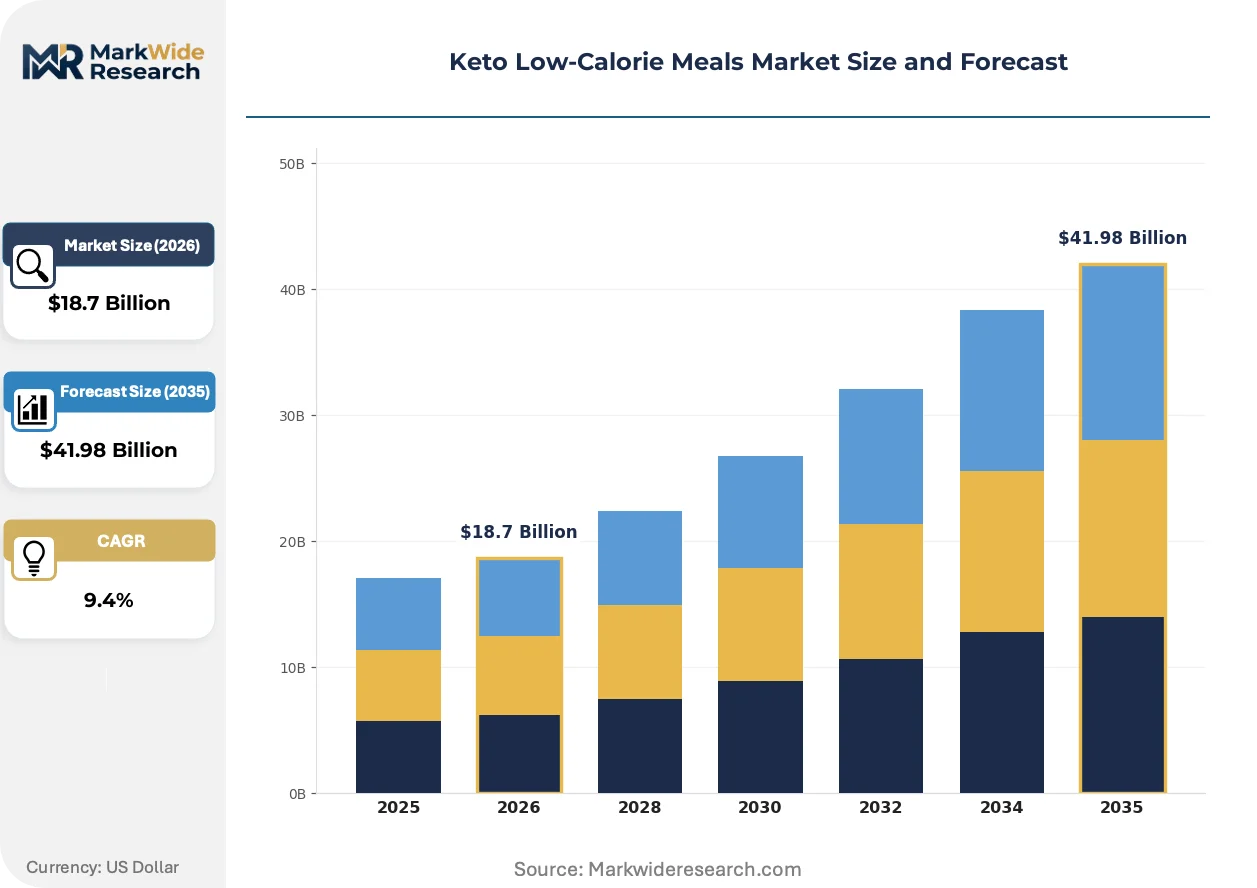
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keto Low-Calorie Meals Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Meal Kits, Snacks, Beverages Ingredient Type: Protein Sources, Vegetables, Fats, Seasonings Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales Customer Type: Health Enthusiasts, Diabetics, Weight Watchers, Fitness Professionals |
| Companies Covered | Chipotle Mexican Grill, Wendy's, Chick-fil-A, Taco Bell, Subway, KFC, Red Lobster, P.F. Chang's, Outback Steakhouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keto Low-Calorie Meals Market Evolving Landscape
Smart packaging and blockchain traceability are reconfiguring trust architectures in prepared ketogenic foods. These technologies address the core consumer anxiety around hidden carbohydrate content and ingredient provenance.
Sous-vide cooking systems paired with IoT temperature monitoring are digitizing quality assurance protocols across contract manufacturing networks. Mid-size meal kit providers adopt these sensor arrays to demonstrate HACCP compliance to corporate procurement officers. Real-time data streams compress audit timelines and reduce insurance liability premiums for cold-chain operators.
REACH chemical safety protocols in the European Union are restricting certain food-contact plastics used in microwaveable tray packaging. Manufacturers serving EU export markets reformulate container compositions to maintain market access. This regulatory pressure is accelerating migration toward fiber-based compostable alternatives in production facilities regardless of destination market.
Subscription auto-renewal models are displacing single-unit trial purchases as the dominant customer acquisition pathway. Direct-to-consumer brands leverage recurring revenue predictability to secure inventory financing. This behavioral shift concentrates margin pools with vertically integrated operators who control fulfillment infrastructure rather than third-party marketplace sellers.
Keto Low-Calorie Meals Market Segmentation
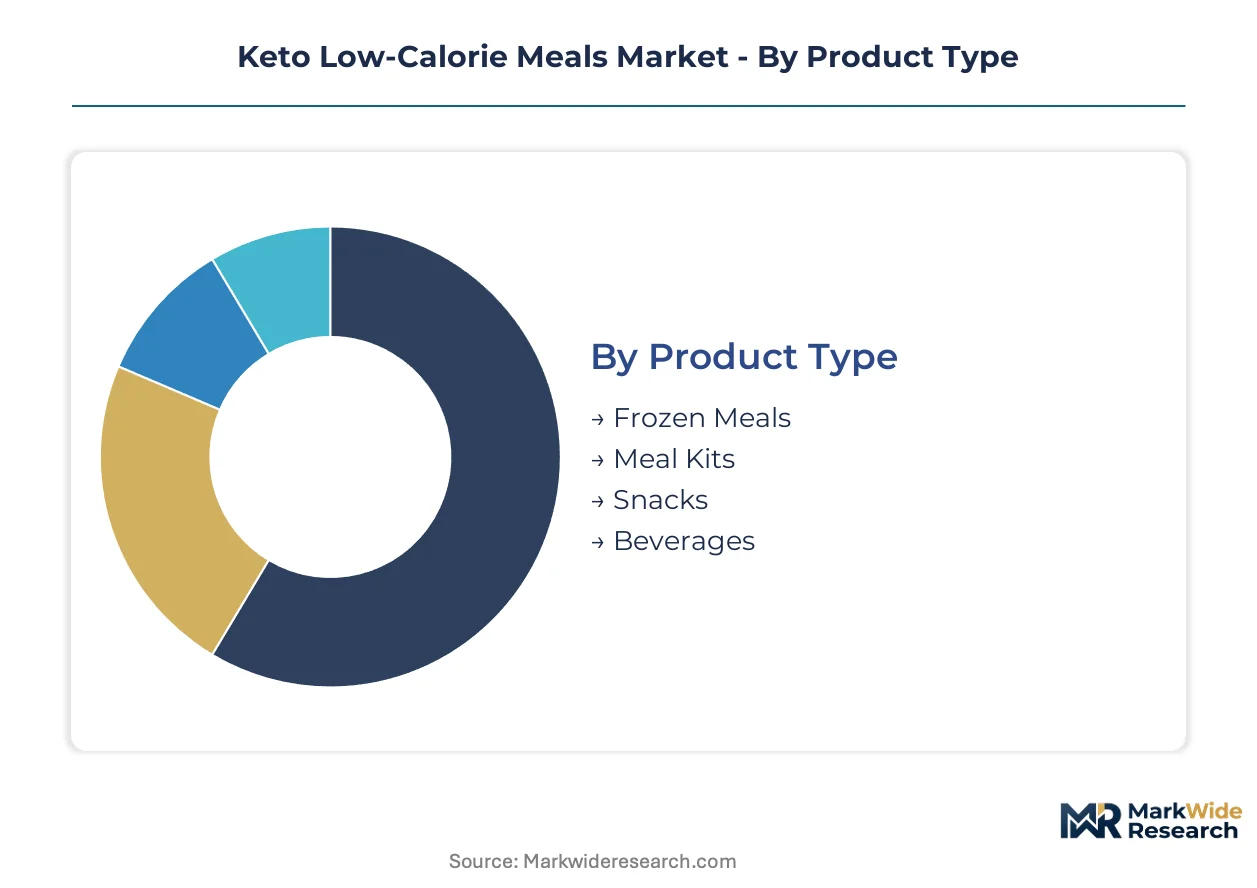
Segmentation in the Keto Low-Calorie Meals Market reveals how formulation choices, procurement channels, and metabolic use cases partition purchasing behavior. Distinct customer motivations—glycemic control versus athletic performance—create non-overlapping product requirements that manufacturers must address through targeted SKUs.
Product Type:
Volume concentration across prepared formats reflects divergent consumer time constraints and preparation skill levels, with shelf stability and subscription logistics driving channel economics.
- Frozen Meals:Cryogenically preserved complete dishes maintain ketogenic macro ratios through controlled portioning of proteins and fats. Demand clusters among working professionals in United States metropolitan corridors seeking convenience without carbohydrate exposure. Extended shelf stability enables batch production economics that support aggressive retail freezer placement.
- Meal Kits:Pre-portioned ingredients with preparation instructions target home cooks pursuing metabolic ketosis through fresh-cooked meals. United States coastal markets show highest subscription retention as consumers balance customization desires with time scarcity. Recurring revenue predictability attracts inventory financing that accelerates ingredient sourcing scale.
- Snacks:Portable low-carbohydrate items address between-meal satiety needs for adherents maintaining ketosis throughout workday schedules.
- Beverages:Ready-to-drink formulations deliver fat and protein in liquid form for consumers prioritizing consumption speed over textural variety.
Frozen Meals holds installed capacity. Meal Kits is rotating up the share rankings.
Ingredient Type:
Margin capture across input categories tracks protein commodity cycles and organic certification premiums that reshape supplier power dynamics.
- Protein Sources:Grass-fed beef, wild-caught fish, and pastured poultry constitute the caloric and satiety anchor of ketogenic formulations. United States health-conscious consumers demonstrate willingness to pay certification premiums for animal welfare and hormone-free claims. USDA Organic status commands dedicated freezer placement that expands addressable shelf space.
- Vegetables:Low-glycemic leafy greens and cruciferous selections provide micronutrient density and fiber within carbohydrate constraints. Demand concentrates in meal kit formats where visual freshness signals quality to United States subscribers evaluating unboxing experiences.
- Fats:Avocado oil, coconut oil, and specialty dairy derivatives supply the caloric majority required for ketogenic metabolic state.
- Seasonings:Sugar-free spice blends and herb formulations enable flavor differentiation without carbohydrate penalty.
Protein Sources holds installed capacity. Vegetables is rotating up the share rankings.
Distribution Channel:
Customer acquisition cost structures and data capture capabilities vary dramatically across physical and digital touchpoints, determining margin retention for brand operators.
- Online Retail:Direct-to-consumer platforms capture recurring subscription revenue and first-party behavioral data that enables macro personalization algorithms. United States metropolitan markets generate highest lifetime value through auto-renewal retention. Vertically integrated fulfillment infrastructure concentrates margin pools with operators controlling cold-chain logistics.
- Supermarkets:National retail chains provide trial access and impulse purchase velocity for frozen meal formats. United States suburban locations with established keto diet communities sustain repeat purchase patterns through dedicated dietetic aisle placement.
- Health Stores:Specialty retailers cater to supplement-adjacent consumers seeking functional nutrition positioning and staff consultation.
- Direct Sales:Employer and institutional procurement channels bypass retail markup through corporate wellness program integration.
Supermarkets holds installed capacity. Online Retail is rotating up the share rankings.
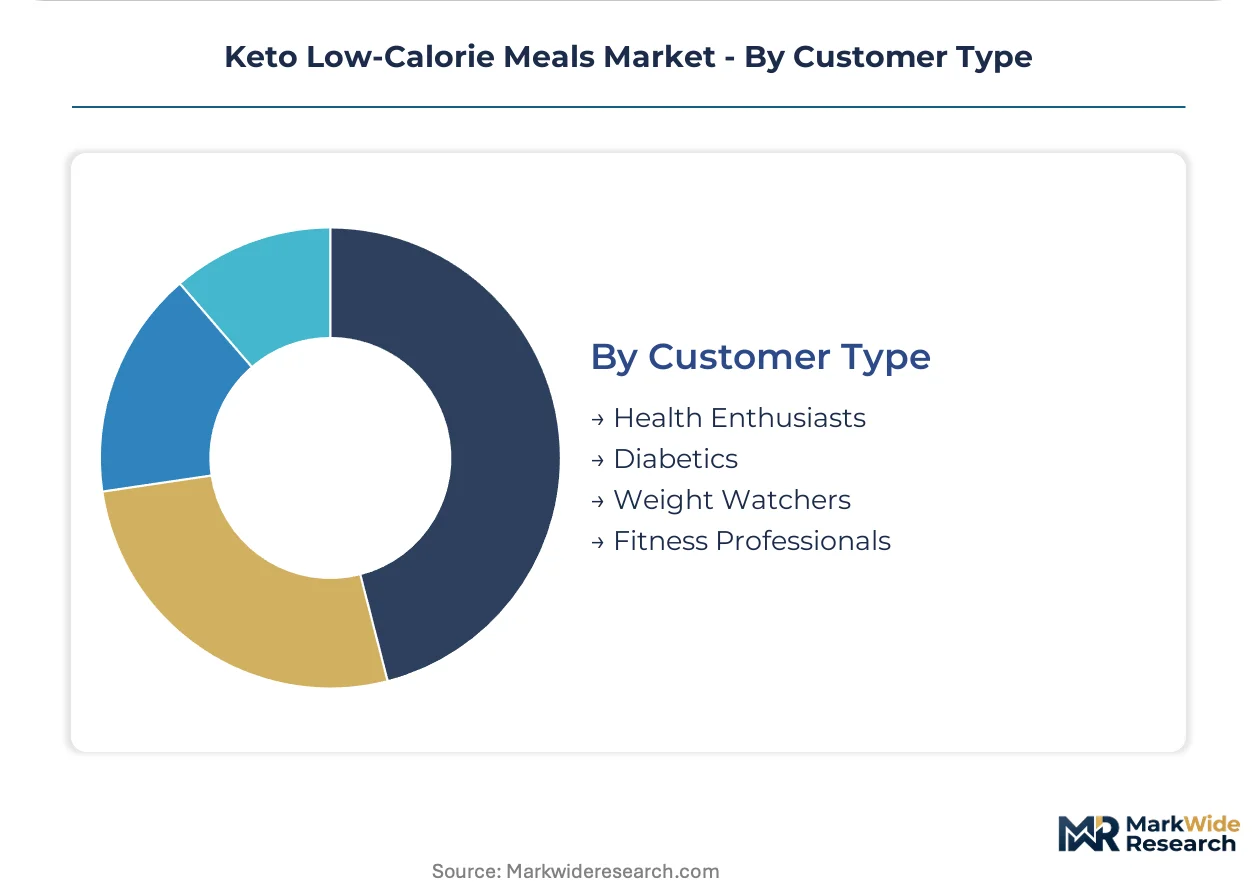
Customer Type:
Metabolic objectives and adherence strictness create distinct purchasing patterns that manufacturers address through formulation intensity and educational marketing investment.
- Health Enthusiasts:Preventive wellness seekers adopt ketogenic eating patterns for cognitive clarity and sustained energy without clinical necessity. United States coastal metropolitan clusters drive premium positioning for organic and clean-label variants. Social media influence accelerates trial conversion through peer endorsement networks.
- Diabetics:Glycemic control requirements mandate strict carbohydrate limitation under medical supervision, creating demand for precisely labeled macro disclosures. United States endocrinology clinic partnerships and insurance-subsidized meal programs expand institutional procurement volumes.
- Weight Watchers:Caloric restriction goals combined with ketogenic macro targets prioritize portion-controlled frozen formats with explicit calorie callouts.
- Fitness Professionals:Body composition optimization drives protein-forward formulations supporting lean mass preservation during fat loss phases.
Health Enthusiasts holds installed capacity. Diabetics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States coastal metros where health-conscious consumers absorb organic certification premiums, while German retail infrastructure constrains margin capture despite carbohydrate-aware demographic expansion. This asymmetry reshapes capital allocation across production networks and distribution partnerships.
United States
Corporate wellness procurement and established keto diet communities in California and New York Metro drive institutional volume and subscription retention. FDA Nutrition Facts labeling requirements for restaurant chains mandate transparent macronutrient disclosure, reshaping brand communication strategies. Austin and Denver clusters host meal kit fulfillment centers leveraging flash-freezing infrastructure for national cold-chain distribution.
Germany
Underdeveloped ketogenic retail infrastructure creates first-mover positioning for frozen meal entrants targeting carbohydrate-aware consumers in DACH markets. ECHA REACH chemical safety protocols restrict certain food-contact plastics, accelerating fiber-based compostable packaging migration. Berlin and Munich metropolitan areas concentrate early-adopter demand through fitness-oriented consumer segments and functional nutrition retail expansion.
Canada
Health Canada oversight of nutritional labeling and organic certification aligns procurement standards with United States export requirements, simplifying cross-border supply integration. Toronto and Vancouver corridors sustain demand through health-conscious professional demographics and corporate wellness program adoption. Pacific Northwest logistics networks extend into British Columbia, reducing cold-chain costs for frozen meal distribution.
United Kingdom
Post-Brexit regulatory divergence from EU food standards creates compliance complexity for multi-national meal kit operators serving British subscribers. London and Southeast England concentrate demand through high-income health enthusiasts and diabetes management programs. Midlands manufacturing clusters develop sous-vide production capacity serving both domestic retail and export channels.
Australia
TGA therapeutic food regulations and strict import biosecurity protocols limit foreign supplier penetration, protecting domestic keto meal manufacturers. Sydney and Melbourne metropolitan markets generate premium pricing for grass-fed protein sourcing and clean-label positioning. Queensland agricultural regions supply specialty dairy inputs for high-fat meal components with reduced supply-chain vulnerability.
Keto Low-Calorie Meals Market Competitive Landscape
Quick-service restaurant chains and specialized meal kit operators split the market between immediate convenience and metabolic customization. Consolidation pressure intensifies as subscription economics favor vertically integrated fulfillment networks over third-party marketplace dependence. Three archetypes dominate: customizable bowl platforms, protein-focused menu engineers, and direct-to-consumer subscription specialists. Dominant competitive moves include corporate wellness partnership procurement and flash-freezing capacity expansion for extended shelf stability.
Within the quick-service tier, Chipotle Mexican Grill anchors customizable bowl positioning across urban United States markets, while Wendy's exemplifies protein-focused menu engineering targeting carbohydrate-restricted diets. Subway occupies a distinct position through transparent macro labeling and vegetable-forward customization protocols. These three represent how legacy restaurant infrastructure adapts to ketogenic demand without dedicated brand repositioning.
| Leading Market Players |
|---|
| Chipotle Mexican Grill |
| Wendy's |
| Chick-fil-A |
| Taco Bell |
| Subway |
| KFC |
| Red Lobster |
| P.F. Chang's |
| Outback Steakhouse |
| Others |
Value Network & Pricing Analysis
Midwest dairy processing clusters in Wisconsin anchor specialty cheese supply for ketogenic formulations, concentrating upstream fat sourcing and transmitting cost volatility into downstream frozen meal pricing. Contract manufacturers in this corridor leverage captive supply relationships to defend margin positions against avocado oil price swings that compress gross margins elsewhere in the category.
Pricing Analysis
The customization-premium spread separates configured-to-order meal kit subscriptions from standard frozen retail SKUs, with subscription tiers commanding sustained premiums through macro personalization algorithms. Price differentiation hinges on organic certification status and cold-chain delivery infrastructure, with USDA Organic placement securing dedicated freezer positioning. Pricing pressure intensifies in the standard frozen tier as retail velocity competition drives promotional depth. Health enthusiasts demonstrate lowest price sensitivity through subscription auto-renewal retention, while weight watchers concentrate price-driven trial in supermarket promotional windows.
Supply Chain Analysis
Upstream feedstock flows from California avocado orchards, Midwest dairy cooperatives, and Australian grass-fed beef operations concentrate critical fat and protein inputs across three continents. Specialty cheese derivatives and cryogenic freezing equipment draw from limited supplier bases, creating single-source vulnerability for high-fat meal components. Tariff exposure on imported avocado oil generates margin compression during supply contractions. Distribution runs through vertically integrated cold-chain networks for subscription fulfillment, while supermarket channels rely on third-party frozen logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against whole-food meal preparation and intermittent fasting protocols that threaten prepared ketogenic meal adherence. Incumbents must navigate homemade keto cooking resurgence driven by macro-tracking app proliferation.
For Market Incumbents: Entrench subscription retention through biometric data integration that personalizes macro ratios beyond generic ketogenic templates. Deepen backward integration into flash-freezing capacity in Austin and Denver corridor facilities to reduce third-party co-manufacturer dependence. Defend against homemade meal prep substitution by embedding IoT-enabled quality verification that demonstrates HACCP compliance to corporate procurement officers.
For New Entrants and Emerging Players: Corporate cafeteria direct distribution in Germany represents the most penetrable entry point, bypassing underdeveloped retail freezer infrastructure in DACH markets. AI-driven personalization platforms targeting diabetic glycemic management protocols offer differentiated positioning against commodity frozen meal competitors. Pursue employer benefits platform integration as the primary go-to-market vector, capturing institutional procurement budgets before retail shelf space consolidation hardens.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription auto-renewal economics concentrate lifetime value with vertically integrated operators controlling fulfillment networks. Target acquisition profiles emphasize meal kit providers with captive cold-chain logistics and first-party data assets. Monitor FDA carbohydrate disclosure methodology evolution as the critical inflection signal for label redesign cost exposure and consumer confusion friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Flash-Freezing Capacity Expansion | Cryogenic infrastructure in Austin and Denver corridors extends product integrity windows for national distribution. |
| Corporate Wellness Partnership | Direct-to-employer procurement bypasses retail markup and captures institutional metabolic health budgets. |
| AI-Driven Personalization Platform | Machine learning algorithms analyzing biometric data enable customized macro ratios for diabetic subscribers. |
| USDA Organic Certification Investment | Organic status commands dedicated freezer placement that expands addressable shelf space in United States retail. |
| Fiber-Based Packaging Migration | REACH-compliant compostable alternatives maintain EU market access and reduce regulatory compliance risk. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with meal kit operations directors, frozen food procurement managers at national retail chains, corporate wellness benefits administrators, and contract manufacturing executives; and secondary validation through FDA nutrition labeling guidance documents, USDA organic certification databases, SEC filings from publicly traded restaurant operators, and Nielsen retail audit data. Bottom-up SKU-level volume aggregation was triangulated against top-down category spend estimates from foodservice distribution channels.
Forecast inputs considered product type segmentation across frozen meals, meal kits, snacks, and beverages; ingredient type splits between protein sources, vegetables, fats, and seasonings; and distribution channel dynamics spanning online retail, supermarkets, health stores, and direct sales. CAGRs were derived through regression analysis of historical subscription retention rates and corporate procurement adoption curves, with flash-freezing technology penetration and AI personalization adoption serving as industry-specific demand modifiers across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices and employer healthcare benefit contribution rates would shift the trajectory. Forecasts reflect assumptions around sustained ketogenic diet adherence rates and corporate wellness program expansion. Cross-checking against Health Canada and TGA regulatory filing patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
Grain Free Dog Food Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Space Food Market
Specialty Foods
Dong Quai Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Chamomile Market
Specialty Foods
Hairball Cat Food Market
Specialty Foods
Superfood Bars Market