
 North America Turboprop Aircraft Market | 2026-2036
North America Turboprop Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
North America Turboprop Aircraft Market Analytics
Composite materials is rebalancing airframe economics across the North America turboprop segment. Textron Aviation Inc. leverages its Wichita manufacturing base to control single-engine production costs. De Havilland Aircraft of Canada Limited anchors regional turboprop supply through its Downsview assembly footprint. ATR competes in the multi-engine category with established North American operator relationships.
North America turboprop aircraft are fixed-wing propeller-driven machines powered by gas turbine engines, typically operating at cruise speeds below 400 knots with maximum takeoff weights ranging from 4,000 to 75,000 pounds, serving short-haul connectivity and specialized mission profiles. The product-type dimension shows multi-engine configurations commanding established margin pools in scheduled passenger service while utility variants sustain replacement cycles in firefighting and agricultural spraying. End-user segmentation reveals cargo operators expanding freighter conversions as e-commerce logistics reshape feeder-network economics across the continent.
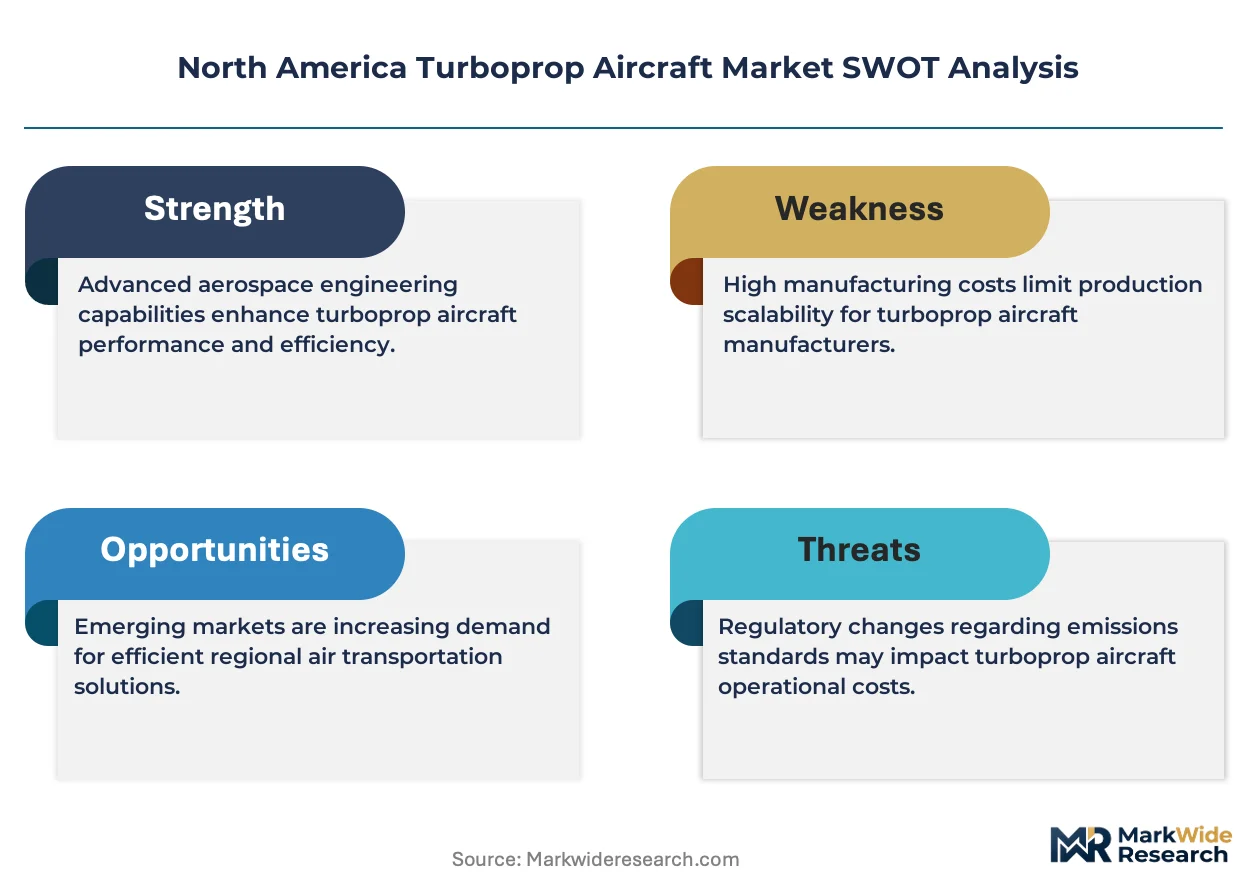
FAA airworthiness directives and EPA Tier 4 emission benchmarks shape powerplant certification pathways for new turboprop platforms entering North American service. Transport Canada certification reciprocity with FAA standards streamlines cross-border fleet homogeneity for operators spanning both jurisdictions. Stakeholders must monitor sustainable aviation fuel compatibility thresholds as regulatory pressure tightens on regional-aviation carbon intensity.
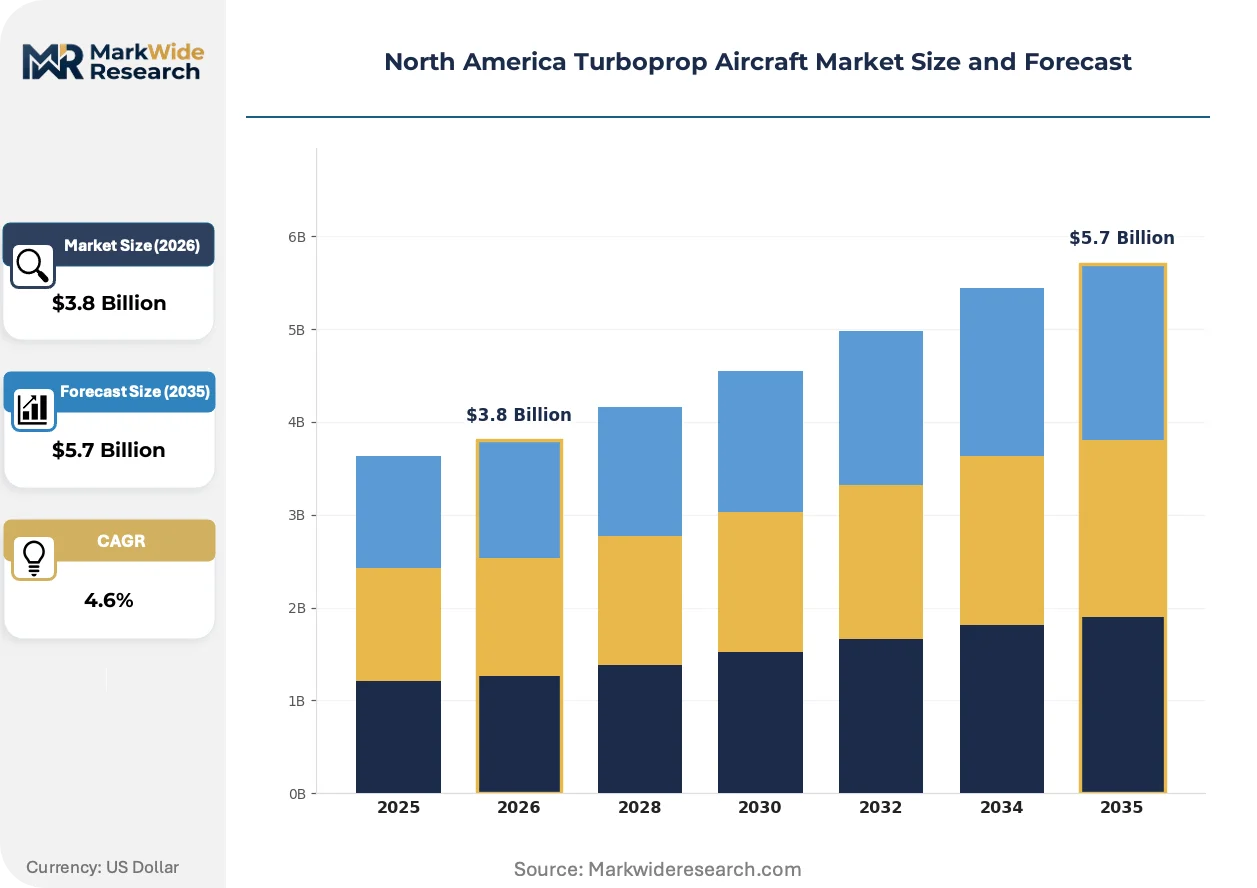
Market Dynamics
FAA NextGen mandates and EPA aviation emission standards are compressing replacement cycles across the North America turboprop fleet. Regional carriers face simultaneous pressure to modernize avionics suites and powerplant efficiency while maintaining thin margin operations on short-haul routes.
Growth Catalysts
- FAA NextGen Mandates:Required ADS-B Out and PBN capability upgrades force fleet turnover at Part 135 operators serving secondary airports. Carriers cannot extend legacy airframe service lives without prohibitively expensive retrofit programs.
- Composite Airframe Adoption:Carbon fiber reinforced polymer structures reduce empty weight by fifteen percent versus aluminum predecessors. Agricultural operators in Texas and the Great Plains capture payload-range improvements for aerial application missions.
- E-commerce Feeder Networks:Amazon Air and UPS contract carriers expand turboprop freighter conversions to serve markets below jet threshold economics. Cargo operators prioritize 19-seat platforms with quick-change interior configurations.
Market Restraints
- Pratt & Whitney Canada PT6 Supply Concentration:Single-source dependency for the dominant regional turboprop powerplant creates delivery timeline risk. Operators face eighteen-month engine backlog queues during production surges.
- Jet-A Price Volatility:Fuel represents forty percent of direct operating costs for turboprop fleet operators. Price spikes compress already thin margins on Essential Air Service subsidized routes.
- Electrification Substitution Threat:Battery-electric and hydrogen fuel cell prototypes under development by NASA and private ventures target sub-500 nautical mile missions currently served by turboprops.
Strategic Opportunities
- Sustainable Aviation Fuel Infrastructure:FAA SAF Grand Challenge creates production incentives that lower carbon intensity for regional operators. Early adopters gain emissions reporting advantages under emerging corporate travel procurement standards.
- Advanced Air Mobility Convergence:Hybrid-electric distributed propulsion systems developed for eVTOL applications transfer to conventional turboprop architectures. Textron and De Havilland engineering teams evaluate motor-generator integration for range extension.
- Mexico Market Underpenetration:Cross-border charter and cargo operators lack modern turboprop fleet depth for Pacific coast and Yucatan connectivity. Transport Canada-FAA certification reciprocity simplifies fleet standardization for binational operators.
Industry Challenges
- Airframe Mechanic Shortage:A&P certificate holders with turboprop-specific experience concentrate at major MRO hubs. Rural operators in Montana and Alaska face six-month recruitment timelines for qualified maintenance personnel.
- Type Certificate Amendment Timelines:FAA Part 25 and Part 23 modification approvals for avionics upgrades average fourteen months. Operators defer capability enhancements rather than absorb revenue-removed aircraft downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Turboprop Aircraft Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Engine, Multi-Engine, Regional, Utility End User: Commercial Airlines, Charter Services, Cargo Operators, Government Agencies Technology: Analog, Digital, Fly-by-Wire, Avionics Application: Passenger Transport, Cargo Transport, Medical Evacuation, Surveillance |
| Companies Covered | ATR, Air Tractor Inc., Textron Aviation Inc., Embraer S.A., De Havilland Aircraft of Canada Limited, Lockheed Martin Corporation, Pilatus Aircraft Ltd., Safran S.A., Airbus SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Turboprop Aircraft Market Evolving Landscape
Digital engine monitoring and predictive maintenance systems are displacing scheduled overhaul intervals across the North America turboprop installed base. Power-by-the-hour contracts and health usage monitoring systems rewrite traditional aftermarket economics.
Composite primary structures are rewriting airframe lifecycle economics for new production turboprops. Textron Aviation's Denali and De Havilland's DHC-6 Twin Otter Guardian 400 variants incorporate carbon fiber wings and empennage. Agricultural operators in California's Central Valley and firefighting contractors in the Pacific Northwest adopt these platforms for corrosion resistance in chemical exposure environments. Maintenance intervals extend from six years to twelve years for composite control surfaces.
EPA Tier 4 emission benchmarks for non-road engines are compressing powerplant certification pathways for new turboprop entrants. The agency's 2024 final rule applies oxides of nitrogen and particulate matter standards previously exempted from aviation applications. Pratt & Whitney Canada and GE Aerospace accelerate clean-sheet engine architectures with single-crystal turbine blades and advanced combustor designs. Regional carriers operating EAS routes face 2027 compliance deadlines for fleet replacement or engine retrofit.
Freighter conversion demand is fragmenting traditional passenger-focused production schedules. Cargo operators now specify factory-new turboprops with reinforced floors and large cargo doors rather than accepting converted passenger airframes. Amazon Air's contractor network in the Ohio River Valley and Great Lakes corridors drives this specification shift. De Havilland and ATR adjust assembly line configurations to accommodate mixed passenger-cargo production runs without changeover delays.
North America Turboprop Aircraft Market Segmentation
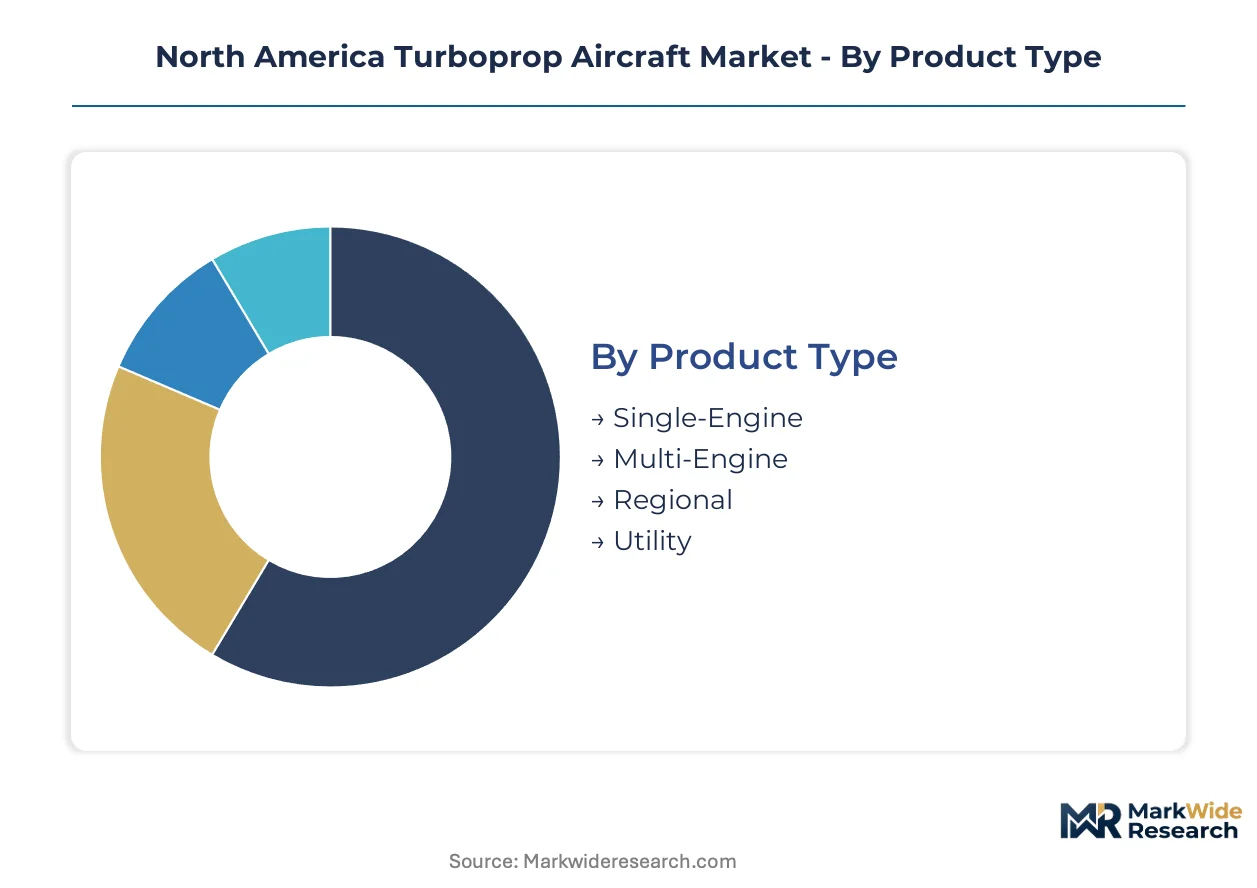
Turboprop segmentation reveals distinct capital requirements and operational economics across configurations. Fleet planners match airframe specifications to route profiles and payload demands.
Product Type:
Capital intensity varies sharply across configurations, with multi-engine platforms demanding substantially higher acquisition outlays and maintenance reserves than single-engine alternatives.
- Single-Engine:Lightweight airframes powered by one turbine, typically below 12,500 pounds MTOW. Agricultural operators in Texas and the Great Plains favor these for aerial application missions where payload efficiency outweighs redundancy requirements.
- Multi-Engine:Twin-turbine configurations with redundant systems and Part 135 certification capability. Scheduled passenger carriers serving Essential Air Service routes concentrate procurement here, driven by FAA safety requirements for commercial operations.
- Regional:Pressurized cabins with 19-50 seat capacity and integrated weather radar. These platforms absorb the heaviest avionics upgrade costs under NextGen mandates.
- Utility:Unpressurized structures with reinforced landing gear for unimproved strips. Firefighting contractors in the Pacific Northwest and Alaska prioritize these for short-field performance.
Multi-engine configurations absorb the bulk of installed capacity; single-engine platforms are expanding most quickly in specialized agricultural applications.
End User:
Customer procurement patterns diverge between subsidized route operators and self-funding cargo carriers, with government agencies introducing distinct compliance requirements.
- Commercial Airlines:Part 121 and Part 135 certificate holders operating scheduled service. These carriers face simultaneous FAA NextGen and EPA Tier 4 compliance deadlines that compress fleet replacement timelines.
- Charter Services:On-demand operators serving remote communities and resource extraction sites. Demand concentrates in Alaska and northern Canada where surface infrastructure remains sparse.
- Cargo Operators:Feeder network contractors for integrated logistics providers. Amazon Air and UPS contract carriers in the Ohio River Valley drive freighter conversion specifications.
- Government Agencies:Federal, state, and provincial operators with mission-specific configuration requirements. These buyers prioritize interoperability with existing fleet standards over acquisition cost minimization.
Commercial airlines field the largest active fleet; cargo operators are climbing the fastest as e-commerce logistics reshape feeder economics.
Technology:
Avionics architecture determines retrofit viability and resale value, with digital platforms commanding substantial premiums in secondary markets.
- Analog:Electromechanical flight instruments with minimal integration. Legacy operators in rural Montana and Alaska maintain these for simplicity in austere maintenance environments.
- Digital:Glass cockpit displays with GPS navigation and terrain awareness. This configuration dominates current production as carriers seek ADS-B Out compliance without supplemental type certificate delays.
- Fly-by-Wire:Electronic flight control systems with envelope protection. Emerging platforms incorporate these for reduced pilot workload in high-frequency operations.
- Avionics:Modular communication and surveillance suites with software-defined radio capability. These systems enable rapid certification updates as FAA mandates evolve.
Digital platforms represent the dominant installed base; fly-by-wire architectures show the steepest expansion trajectory in new production programs.
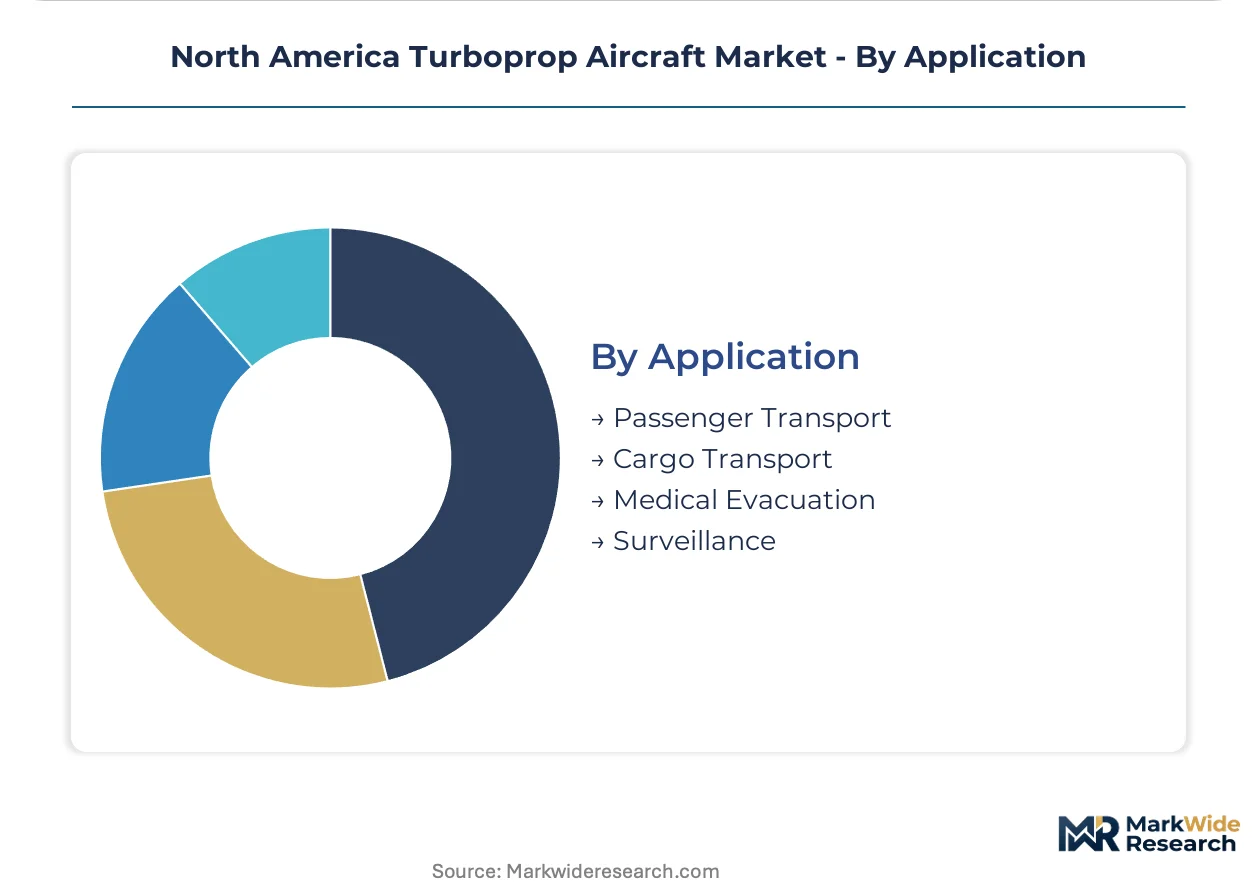
Application:
Mission profile dictates airframe configuration, with passenger and cargo transport representing fundamentally different payload-floor specifications.
- Passenger Transport:Configured with quick-change interiors and pressurization for altitude operations. Regional carriers in the Great Plains corridor prioritize these for thin-route economics.
- Cargo Transport:Reinforced floors, large cargo doors, and roller conveyor systems. These specifications now dominate factory orders from Amazon Air contractor networks.
- Medical Evacuation:Dedicated life-support installations and stretcher mounting provisions. Operators serving the Mountain West and northern Canada concentrate procurement here.
- Surveillance:Sensor hardpoints, extended endurance fuel systems, and stabilized camera mounts. Border patrol and fisheries enforcement agencies drive this segment.
Passenger transport retains the largest fleet share; cargo transport is gaining share fastest as e-commerce volumes reshape feeder network specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kansas Aviation Tax Credit zones and Wichita's Air Capital designation concentrate manufacturing infrastructure and operator procurement decisions across the Great Plains corridor.
United States
Essential Air Service subsidies sustain turboprop operations at 115 rural communities while FAA NextGen mandates force avionics upgrades. EPA Tier 4 emission benchmarks apply to new powerplant certifications from 2027. Agricultural operators in Texas and the Great Plains maintain dense single-engine utilization for aerial application missions.
Canada
Remote community connectivity requirements and resource extraction logistics drive multi-engine procurement in northern territories. Transport Canada certification reciprocity with FAA standards streamlines cross-border fleet standardization. De Havilland's Downsview assembly footprint anchors regional turboprop supply for operators spanning both jurisdictions.
Mexico
Cross-border cargo corridors and Pacific coast connectivity gaps create underpenetrated demand for modern turboprop fleet depth. Mexico's civil aviation authority aligns type certification with FAA standards under bilateral agreements. Yucatan Peninsula charter operators lack pressurized regional platforms for tourism and business travel segments.
North America Turboprop Aircraft Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated airframers controlling proprietary platforms while component suppliers capture aftermarket value pools. The vendor base concentrates around three powerplant-airframe pairings that dominate installed capacity. Strategic archetypes include full-stack airframers with in-house propulsion, specialized agricultural airframe builders, and European regional platform exporters. Competitive moves center on composite airframe investments and freighter conversion line reconfigurations.
Within the full-stack airframer tier, Textron Aviation Inc. and De Havilland Aircraft of Canada Limited occupy positions spanning single-engine utility through multi-engine regional categories. ATR exemplifies the European regional platform exporter archetype with established operator relationships. These three anchors represent distinct geographic manufacturing concentrations—Wichita, Downsview, and Toulouse-Blagnac corridor respectively—each serving overlapping but differentiated mission profiles across the North American installed base.
| Leading Market Players |
|---|
| ATR |
| Air Tractor Inc. |
| Textron Aviation Inc. |
| Embraer S.A. |
| De Havilland Aircraft of Canada Limited |
| Lockheed Martin Corporation |
| Pilatus Aircraft Ltd. |
| Safran S.A. |
| Airbus SE |
| Others |
Value Network & Pricing Analysis
Family-owned agricultural airframe specialists in Texas and Kansas anchor production economics through captive fabrication shops and long-dated supplier relationships, translating vertical control into pricing discipline that resists spot-market volatility. Their ownership structure insulates contract negotiations from quarterly earnings pressure, allowing multi-year procurement commitments that stabilize input costs across the production cycle.
Pricing Analysis
Short lead-time premiums command substantial markups in the regional turboprop segment, with operators paying escalated rates to bypass Pratt & Whitney Canada PT6 engine backlogs stretching eighteen months. Contract-based long-term offtake agreements dominate fleet procurement, though price differentiation hinges on avionics certification tier and after-sales service bundling. Cost compression in the single-engine utility tier intensifies as agricultural operators prioritize payload efficiency over brand premium, while Part 135 carriers show lowest price sensitivity due to FAA safety mandates. Margins are tightening in the freighter conversion market as Amazon Air contractors consolidate purchasing power.
Supply Chain Analysis
Domestic-content thresholds in FAA Buy American provisions reshape sourcing for avionics and airframe components, pressuring assemblers to qualify alternative vendors. Manufacturing gravity centers on the United States, Canada, and France, with carbon fiber prepregs drawing from specialized chemical suppliers in Japan and Germany. Single-source vulnerability concentrates in turbine blade castings and advanced avionics modules, while distribution runs through authorized dealer networks serving rural operators in Montana and Alaska. Logistics chokepoints at Wichita and Downsview assembly hubs amplify delivery risk during production surges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around airframers with composite manufacturing depth and powerplant integration capabilities, as EPA Tier 4 compliance deadlines eliminate capital-constrained competitors unable to fund clean-sheet engine architectures.
For Market Incumbents: Anticipate electrification substitution threats by accelerating hybrid-electric distributed propulsion partnerships with NASA and private ventures. Secure backward integration into carbon fiber wing fabrication to capture margin pools escaping to composite suppliers. Defensive consolidation through MRO network expansion in the Great Plains corridor locks in aftermarket revenue from aging PT6 fleets. For New Entrants and Emerging Players: Capture white-space demand in Mexico's Yucatan Peninsula charter market, where pressurized regional platform availability lags tourism growth. Target cargo operators in the Ohio River Valley with quick-change interior configurations optimized for Amazon Air contractor specifications. Go-to-market leverage rests on Transport Canada-FAA certification reciprocity that accelerates cross-border fleet standardization. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with established Part 135 operator relationships in underserved Mountain West corridors. Long-term viability hinges on sustainable aviation fuel compatibility engineering and predictive maintenance software integration. Watch FAA SAF Grand Challenge production incentives as the inflection signal for regional operator procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Airframe Manufacturing Scale-Up | Textron and De Havilland expand carbon fiber wing production to capture fifteen percent weight reduction premiums. |
| Freighter Conversion Line Reconfiguration | Factory-new cargo specifications displace passenger-to-freighter retrofits in Amazon Air contractor procurement. |
| Powerplant Certification Investment | Pratt & Whitney Canada and GE Aerospace accelerate clean-sheet architectures to meet EPA Tier 4 benchmarks. |
| Predictive Maintenance Platform Deployment | Health usage monitoring systems displace scheduled overhaul intervals across the installed base. |
| Cross-Border Fleet Standardization | Transport Canada-FAA reciprocity simplifies binational operator procurement in Pacific coast corridors. |
Research Methodology
Independent corroboration across FAA type certificate databases, EPA regulatory filings, and Transport Canada certification records underwrites the qualitative findings on compliance-driven fleet turnover. Primary interviews with fleet planners at Part 135 operators, MRO facility managers in Wichita and Downsview, and procurement leads at agricultural spraying contractors combined with secondary validation from Essential Air Service subsidy disclosures, customs import records for turbine components, and SEC filings from listed airframers. Bottom-up triangulation across operator fleet plans and top-down reconciliation with manufacturing capacity announcements anchor the demand assessment.
Rate-of-change decomposition across the analysis window segments volume trajectories by product type, end-user category, and application mission, with CAGRs derived from installed base replacement cycles and net new demand from e-commerce feeder network expansion. The modeling framework incorporates EPA Tier 4 compliance deadlines, FAA NextGen avionics mandate phase-ins, and sustainable aviation fuel infrastructure buildout assumptions as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery-electric propulsion breakthroughs and hydrogen fuel cell certification pathways. Forecasts reflect documented assumptions on fuel price volatility, engine delivery timelines, and mechanic labor availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Afterburner Market
Aircraft
Regional Jet Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Civil Helicopter Market
Aircraft
Aircraft Seals Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Military Trainer Aircraft Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Commercial Aircraft Market
Aircraft
Aviation Market
Aircraft
Commercial Helicopter Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Aircraft Galley Equipment Market