
 Commercial Aircraft Lavatory System Market | 2026-2036
Commercial Aircraft Lavatory System Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Lavatory System Market Outlook
North American aerospace manufacturing capacity is reconfiguring around next-generation narrow-body programs. Safran leverages its integrated propulsion-to-cabin portfolio to cross-sell lavatory modules with landing gear contracts. Collins Aerospace sustains engineering density in Iowa and North Carolina facilities that design vacuum waste architectures. Diehl Stiftung & Co. KG anchors European supply through its Hamburg-based interiors division serving A320 family programs.
A commercial aircraft lavatory system comprises vacuum waste collection assemblies, odor-control chemical dosing units, flush valves rated to 35,000 cycle lifetimes, and lightweight composite enclosures engineered to FAR 25.853 flammability standards. These systems serve the essential function of managing human waste and greywater containment across multi-hour flight profiles while minimizing weight penalty and servicing turnaround time. Vacuum Systems dominate product type revenue due to their near-universal fitment on jets above fifty seats, while Smart Toilets represent the fastest-expanding technology segment as carriers pursue predictive maintenance and passenger experience differentiation. Retrofit installations lag New Installation volumes but command higher per-unit pricing as engineering change orders accumulate on aging Boeing 737NG and A320ceo fleets.
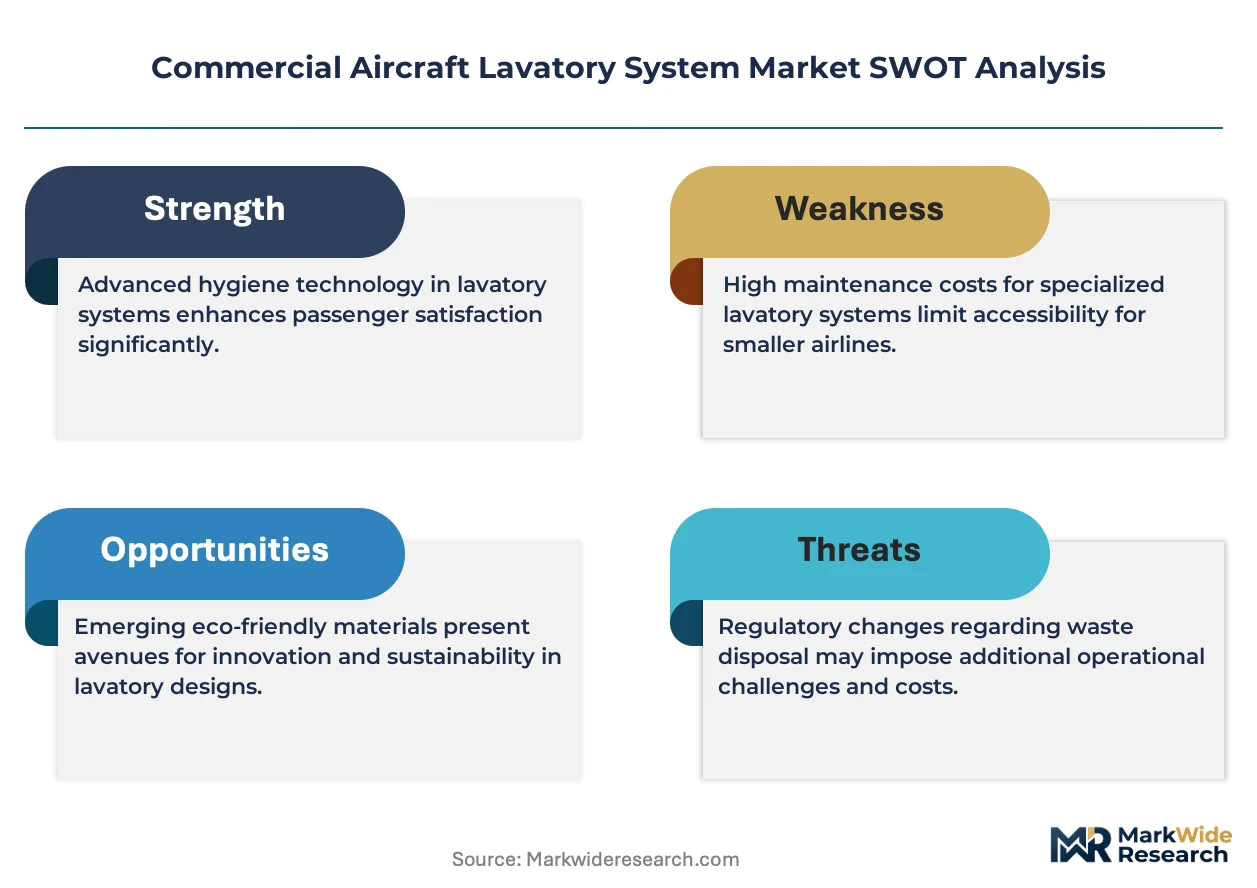
FAA airworthiness directives and EASA CS-25 certification requirements govern waste system structural integrity, fire resistance, and electromagnetic interference shielding, forcing suppliers to maintain dual-continent testing capabilities. The EU Green Deal's emerging aircraft circularity framework pressures OEMs to design lavatory modules for disassembly and material recovery at end-of-life. Stakeholders must weigh whether to deepen captive production of smart toilet electronics or partner with avionics specialists as cabin digitization accelerates.
Market Dynamics
FAA airworthiness directives on waste containment standards are compressing supplier certification timelines while narrow-body fleet expansion in Southeast Asia concentrates procurement decisions around single-aisle retrofit programs. This regulatory-demand intersection is forcing lavatory system manufacturers to reconfigure engineering resources across dual-continent testing facilities.
Growth Catalysts
- EU Green Deal circularity mandates:End-of-life disassembly requirements for aircraft interiors are accelerating demand for modular lavatory architectures designed for material recovery and component remanufacturing.
- Budget carrier fleet densification:Southeast Asian low-cost airlines are expanding narrow-body orders that specify higher lavatory-to-passenger ratios to minimize turnaround times at secondary airports.
- Predictive maintenance integration:Smart toilet sensor networks enabling real-time waste system monitoring are migrating from premium long-haul configurations to standard narrow-body specifications.
Market Restraints
- Titanium alloy input volatility:Flush valve assemblies and vacuum pump housings rely on aerospace-grade titanium whose spot pricing fluctuates with defense sector demand cycles.
- Dual-continent certification burden:FAA Part 25 and EASA CS-25 testing redundancy forces suppliers to maintain parallel fire-resistance and EMI shielding validation facilities in the US and Germany.
- Service life extension of legacy fleets:Boeing 737NG and A320ceo operators are deferring lavatory retrofits through heavy maintenance intervals, compressing near-term aftermarket revenue.
Strategic Opportunities
- India civil aviation expansion:DGCA regulatory harmonization with EASA standards is opening procurement pathways for vacuum waste system suppliers on IndiGo and Air India narrow-body orders.
- Cabin digitization convergence:Integration of lavatory occupancy sensors with in-flight entertainment networks enables passenger queue management and differentiated service tiering.
- Alternative distribution via MRO consolidation:Independent maintenance providers are bundling lavatory module replacement with heavy check intervals, bypassing traditional OEM channel structures.
Industry Challenges
- Electromagnetic compatibility engineering scarcity:Vacuum waste system controllers must meet DO-160G Section 21 emissions standards, yet qualified avionics integration specialists remain concentrated at tier-one suppliers.
- Legacy fleet documentation fragmentation:Engineering change orders for aging Boeing and Airbus platforms require reconstruction of original flammability certification data that predates digital archiving protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Lavatory System Market |
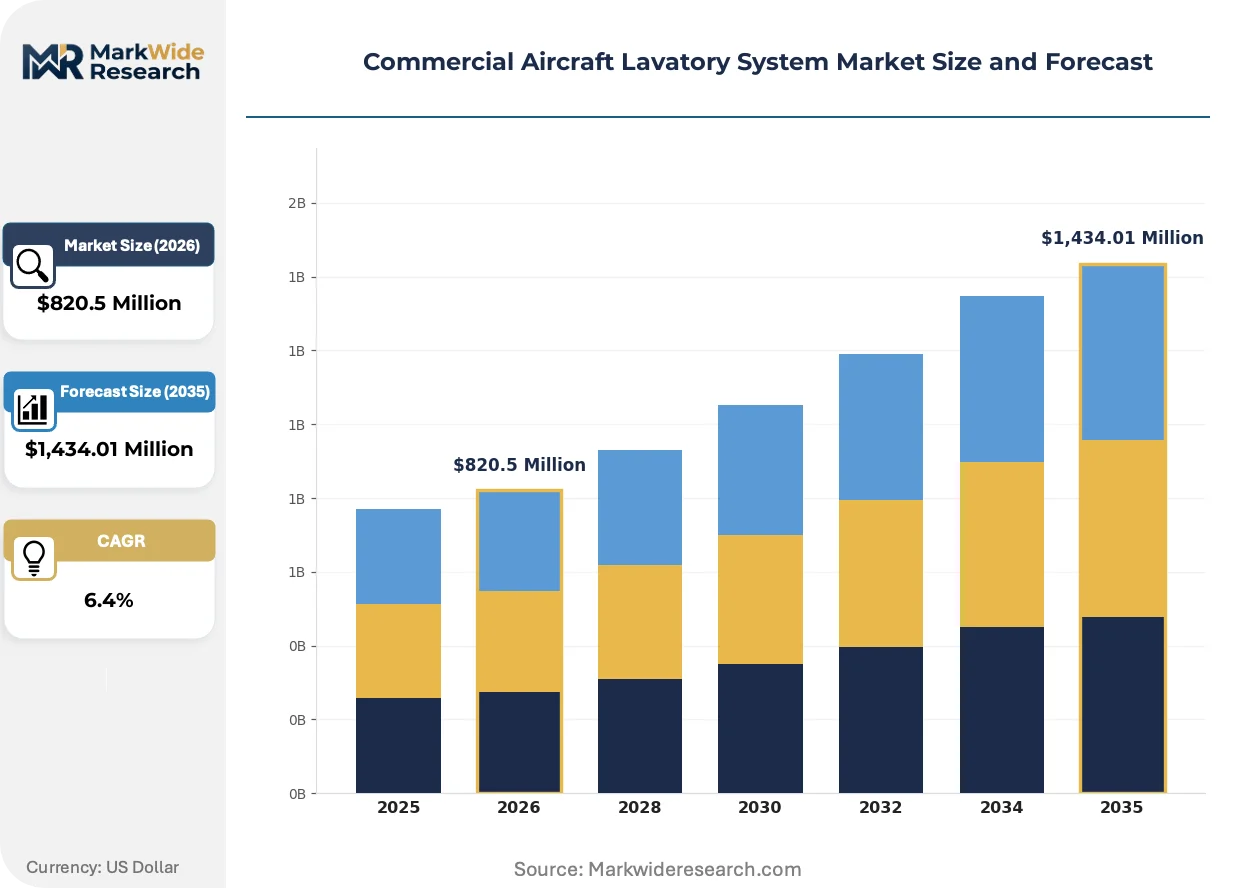
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,434.01 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Systems, Chemical Toilet Systems, Portable Toilet Solutions, Waste Management Systems End User: Commercial Airlines, Cargo Carriers, Military Aviation, Private Aviation Installation Type: Retrofit, New Installation, Modular System, Custom Solution Technology: Manual Systems, Automated Systems, Smart Toilets, Eco-Friendly Solutions |
| Companies Covered | JAMCO Corporation, Safran, Collins Aerospace, Diehl Stiftung & Co. KG, RTX Corporation, Geven SpA, THE YOKOHAMA RUBBER CO., LTD., CIRCOR Aerospace, FACC AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Lavatory System Market Strategic Shifts
Active cabin digitization is compressing the traditional boundaries between waste management hardware and passenger-facing software systems. This convergence is generating three distinct vectors of technical and commercial change across the lavatory system value chain.
Smart toilet architectures incorporating pressure transducers, fill-level sensors, and predictive analytics modules are migrating from flagship long-haul configurations to standard narrow-body specifications. Low-cost carriers in Southeast Asia are specifying these systems to reduce unscheduled maintenance events at outstations with limited technical support. The technology is migrating from passenger experience differentiation toward operational reliability infrastructure.
EASA CS-25 Amendment 25-157 tightened fire resistance requirements for thermoplastic lavatory enclosures, compelling suppliers to validate new composite formulations against oil-burner test protocols. German and French testing houses have expanded capacity to handle the resulting certification backlog from Hamburg and Toulouse-based interiors divisions. Vacuum waste system OEMs are responding by qualifying alternative phenolic resin matrices that maintain FAR 25.853 compliance at reduced panel thickness.
Airline technical procurement departments are consolidating lavatory module purchasing with landing gear and engine nacelle contracts to leverage Safran's integrated propulsion-to-cabin portfolio. This bundling behavior is displacing standalone lavatory system vendors from narrow-body original equipment competitions. The pattern is most visible at Airbus A320 family final assembly lines in Toulouse and Mobile, where single-source interior package awards are becoming standard practice.
Commercial Aircraft Lavatory System Market Segmentation
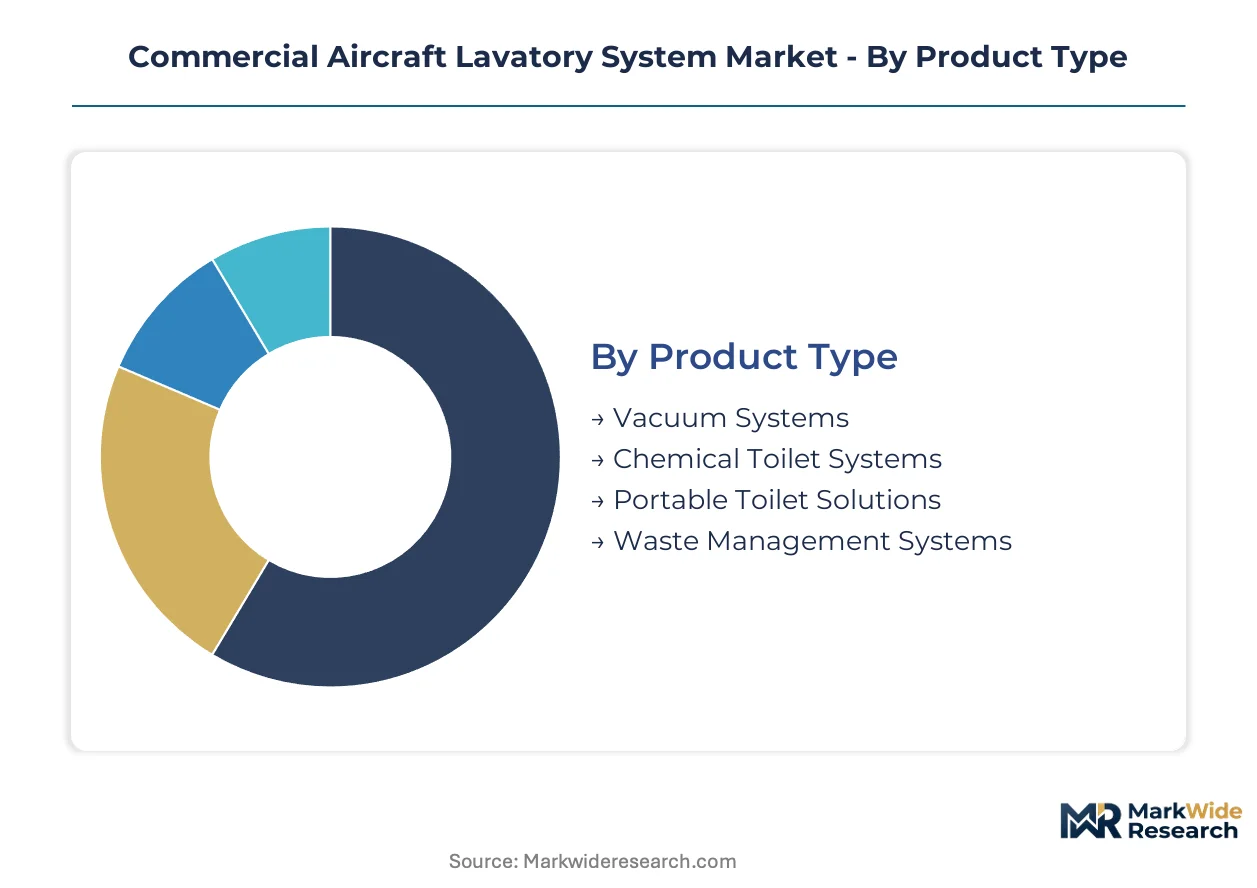
Segmentation in the commercial aircraft lavatory system market reveals distinct procurement rhythms across product architectures and customer types. Replacement cycles for vacuum waste hardware diverge sharply from smart toilet electronics, while retrofit demand patterns differ materially from line-fit specifications on new narrow-body programs.
Product Type:
Vacuum Systems and Chemical Toilet Systems turn over fastest on aging single-aisle fleets, while Portable Toilet Solutions and Waste Management Systems follow slower replacement cadences tied to heavy maintenance intervals.
- Vacuum Systems:These assemblies deploy differential pressure to transport waste to holding tanks, eliminating water-weight penalties on fuel-burn-sensitive routes. Demand concentrates on Boeing 737MAX and A320neo production lines in Renton and Hamburg, driven by FAA Part 25 vacuum containment directives tightening compliance windows for line-fit specifications.
- Chemical Toilet Systems:Recirculating blue-fluid architectures persist on regional turboprops and legacy narrow-bodies below 70 seats. Procurement activity clusters with ATR 72-600 and De Havilland Canada Dash 8 operators in Southeast Asia, constrained by EASA CS-25 Amendment 25-157 fire-resistance retrofits that accelerate replacement timelines.
- Portable Toilet Solutions:Self-contained units serve freighter conversions and temporary cabin reconfigurations.
- Waste Management Systems:Integrated tankage and servicing panel assemblies align with long-haul wide-body specifications.
Vacuum Systems dominate installed base. Smart toilet-enabled product variants are where expansion concentrates.
End User:
Cost tier separation is pronounced: commercial airlines absorb premium pricing for predictive maintenance integration, while cargo carriers and military operators prioritize acquisition cost over sensor-enabled architectures.
- Commercial Airlines:Full-service and low-cost carriers specify lavatory modules as part of interior package competitions. IndiGo and Air India narrow-body orders in India illustrate procurement concentration where DGCA-EASA regulatory harmonization opens supplier pathways.
- Cargo Carriers:Freighter operators prioritize minimal crew lavatory configurations on converted wide-bodies.
- Military Aviation:Tanker and transport platforms require hardened vacuum architectures for austere field operations.
- Private Aviation:Business jet completion centers specify custom enclosures with premium finishes and reduced noise signatures.
Commercial Airlines anchor procurement volume. Cargo conversion programs are climbing the fastest.
Installation Type:
Volume concentration favors New Installation on production rate surges, yet margin accretion concentrates in Retrofit and Custom Solution categories where engineering change orders accumulate.
- Retrofit:Aging 737NG and A320ceo fleets drive aftermarket replacement as operators defer full interior overhauls through heavy check intervals. FAA airworthiness directives on waste containment compress supplier certification timelines for these programs.
- New Installation:Line-fit specifications at Airbus Toulouse and Boeing Renton facilities follow narrow-body production rate schedules.
- Modular System:Pre-certified lavatory pods enable rapid cabin reconfiguration for seasonal capacity adjustments.
- Custom Solution:VIP and head-of-state completions require bespoke enclosure geometries and material finishes.
New Installation captures highest unit volumes. Retrofit commands superior per-unit economics.
Technology:
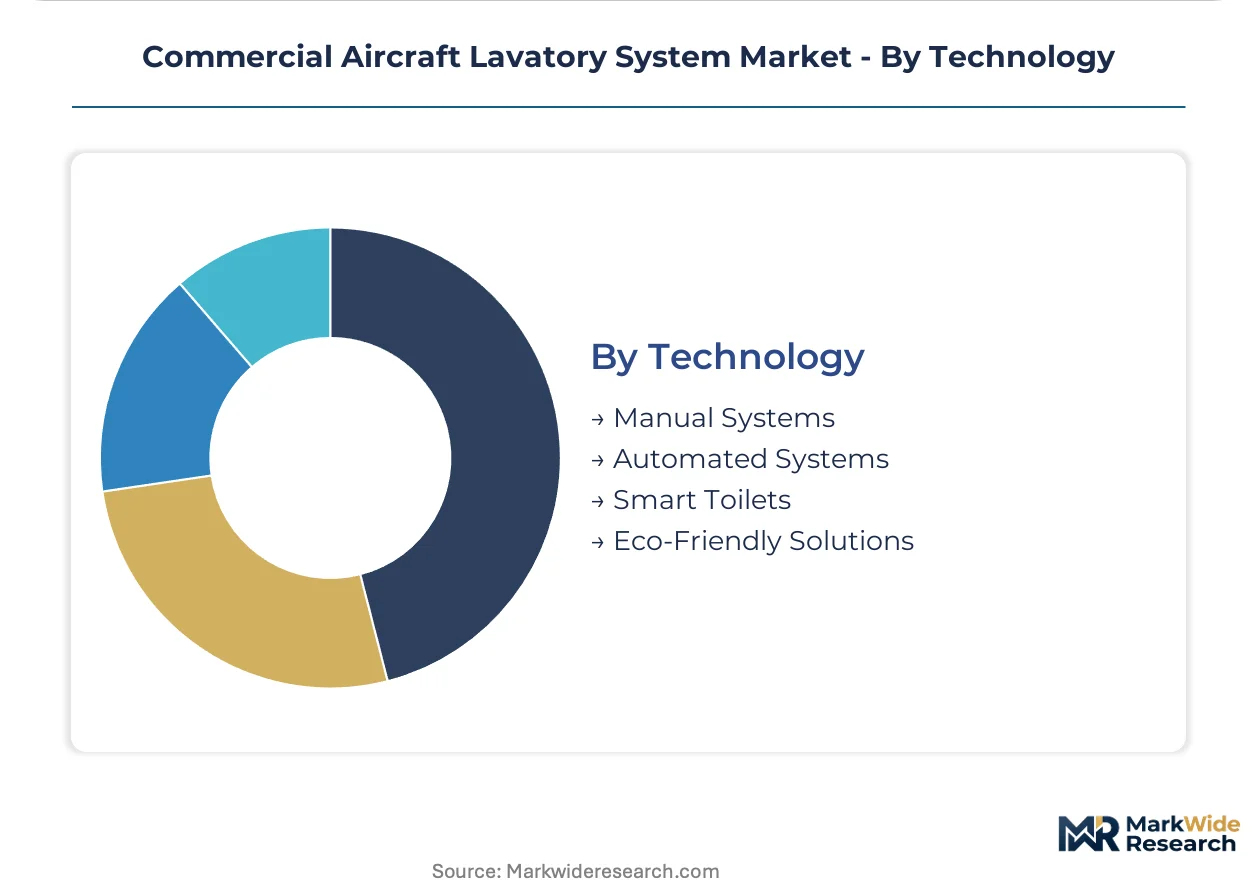
Technology maturity separates Manual Systems as legacy infrastructure from Automated Systems and Smart Toilets where sensor integration and predictive analytics are reshaping supplier capability requirements.
- Smart Toilets:Pressure transducers, fill-level sensors, and edge-computing modules enable real-time waste system monitoring and unscheduled maintenance avoidance. Southeast Asian budget carriers are specifying these systems for outstation reliability, migrating the technology from premium long-haul differentiation toward operational infrastructure.
- Automated Systems:Sensor-activated flush and faucet mechanisms reduce touchpoints and water consumption.
- Manual Systems:Mechanical flush valves and basic enclosures persist on regional aircraft and legacy fleets.
- Eco-Friendly Solutions:Waterless or ultra-low-flush architectures address airline sustainability reporting requirements.
Manual Systems retain largest legacy footprint. Smart Toilets are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives on waste containment standards anchor procurement compliance in the United States, while narrow-body fleet expansion in Southeast Asia and regulatory harmonization in India reshape supplier geographic priorities across the analysis window.
United States
Boeing 737MAX production rates at Renton drive line-fit vacuum system demand. FAA Part 25 certification requirements compress supplier timelines for fire-resistance and EMI shielding validation. Wichita, Kansas clusters aerospace interiors engineering alongside landing gear manufacturing, enabling bundled procurement contracts.
Germany
Airbus A320 family final assembly in Hamburg concentrates lavatory module specifications. EASA CS-25 Amendment 25-157 tightened thermoplastic fire-resistance standards, forcing composite formulation recertification. Diehl Stiftung & Co. KG anchors European supply through its Hamburg-based interiors division.
France
Toulouse final assembly lines see single-source interior package awards becoming standard practice. Safran leverages integrated propulsion-to-cabin portfolios to cross-sell lavatory modules with engine contracts. EU Green Deal circularity mandates pressure OEMs toward modular architectures designed for end-of-life disassembly.
India
DGCA regulatory harmonization with EASA standards opens procurement pathways for IndiGo and Air India narrow-body orders. Budget carrier fleet densification specifies higher lavatory-to-passenger ratios. Bengaluru and Hyderabad clusters concentrate MRO capabilities for regional retrofit programs.
Singapore
Southeast Asian low-cost airline expansion concentrates procurement decisions around single-aisle specifications. Smart toilet sensor networks migrate from premium long-haul to standard narrow-body configurations for outstation reliability. Changi aerospace precinct hosts regional technical support infrastructure.
Commercial Aircraft Lavatory System Market Competitive Environment
Capability concentration sits with tier-one aerospace conglomerates possessing integrated propulsion-to-cabin portfolios; scale advantage sits with specialized interiors divisions embedded within broader aviation groups. The market structures around three archetypes: full-service system integrators, component specialists, and diversified rubber/polymer houses extending into cabin hardware. Dominant competitive moves include strategic bundling of lavatory modules with adjacent aircraft systems and geographic co-location with final assembly lines.
Within the full-service integrator tier, Safran and Collins Aerospace exemplify portfolio breadth spanning propulsion through cabin environments. Diehl Stiftung & Co. KG anchors European supply positioning through its Hamburg-based interiors division. JAMCO Corporation represents the specialized component archetype with concentrated aerospace manufacturing heritage. These three entities collectively illustrate how supplier positioning stratifies between bundled system offerings and focused component excellence.
| Leading Market Players |
|---|
| JAMCO Corporation |
| Safran |
| Collins Aerospace |
| Diehl Stiftung & Co. KG |
| RTX Corporation |
| Geven SpA |
| THE YOKOHAMA RUBBER CO., LTD. |
| CIRCOR Aerospace |
| FACC AG |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Southeast Asian aerospace component manufacturing is compressing supplier margins while simultaneously concentrating procurement leverage among narrow-body fleet operators in that corridor. This utilization imbalance forces tier-two lavatory system vendors to accept extended payment terms from Airbus and Boeing tier-one integrators, reshaping working capital requirements across the supplier base.
Pricing Analysis
Geographic price spreads between Hamburg and Renton specifications exceed fifteen percent on equivalent vacuum waste assemblies, reflecting EASA CS-25 fire-resistance certification premiums against FAA Part 25 baseline compliance. Three-tier pricing structure across line-fit, retrofit, and custom VIP configurations separates procurement economics, with retrofit commanding highest per-unit realization due to engineering change order accumulation. Cost compression in narrow-body line-fit segments is intensifying because Safran and Collins Aerospace bundle lavatory modules with landing gear and propulsion contracts. Cargo carriers exhibit greatest price sensitivity, deferring smart toilet sensor specifications to minimize acquisition outlays on freighter conversions.
Supply Chain Analysis
Contract manufacturing concentration rests with Diehl Stiftung's Hamburg interiors division and Safran's Toulouse-based cabin systems facilities, which retain captive production of composite enclosures and vacuum pump housings. Geographic supply concentration draws from Germany, France, and the United States, with titanium alloy flush valve forgings sourcing from aerospace-grade foundries in the US and Japan. Raw material dependencies hinge on aerospace titanium billet, phenolic resin matrices for thermoplastic panels, and precision-machined aluminum servo housings. Single-source vulnerability concentrates in FAA-certified fire-resistance testing capacity, where limited US and German facilities create certification bottlenecks. Distribution runs through Airbus and Boeing tier-one integrators, with aftermarket channels fragmenting toward consolidated MRO providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defensive structure where EASA and FAA certification entrenchment creates switching costs that lock airframe OEMs into validated supplier relationships. Dual-continent testing requirements and airworthiness directive compliance timelines erect barriers that compound incumbent advantage.
For Market Incumbents: Entrench certification density by expanding parallel FAA Part 25 and EASA CS-25 testing capabilities in Wichita and Hamburg, preempting competitor validation pathways. Deepen backward integration into smart toilet sensor electronics to capture cabin digitization value pools, countering emerging avionics specialist entrants. Lock in narrow-body line-fit positions through propulsion-to-cabin bundling contracts with Airbus and Boeing platform teams.
For New Entrants and Emerging Players: Establish a beachhead in India DGCA-regulated retrofit programs where EASA harmonization creates certification pathway efficiency for vacuum waste system specialists. Target cargo carrier freighter conversion specifications, where minimal sensor requirements and price-sensitive procurement open penetration opportunities. Pursue MRO channel partnerships with consolidated maintenance providers bypassing traditional OEM distribution structures.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart toilet electronics sub-segments, as edge-computing module development and DO-160G avionics integration expand R&D burn rates. Focus acquisition screening on tier-two lavatory component specialists possessing EASA CS-25 Amendment 25-157 fire-resistance validation, whose certification assets command scarcity premiums. Monitor titanium spot pricing volatility as inflection indicator for flush valve assembly margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Continent Certification Investment | Parallel FAA and EASA testing capacity secures narrow-body line-fit eligibility at Renton and Hamburg. |
| Smart Toilet Sensor Integration | Predictive maintenance modules differentiate specifications for Southeast Asian budget carrier fleets. |
| Modular Architecture Development | EU Green Deal disassembly compliance positions suppliers for end-of-life material recovery mandates. |
| MRO Channel Partnership | Independent maintenance bundling bypasses Safran and Collins Aerospace integrated portfolio dominance. |
| India Regulatory Harmonization Entry | DGCA-EASA alignment opens procurement pathways for IndiGo and Air India narrow-body programs. |
Study Parameters
Desk research of FAA airworthiness directive filings, EASA certification databases, and Airbus Boeing production rate disclosures preceded structured interviews with procurement directors at narrow-body operators, vacuum waste system engineering leads, MRO contract managers, and composite materials specialists at tier-one interiors divisions. Secondary validation drew from customs trade data for aerospace titanium imports, SEC 10-K segment disclosures from diversified aerospace conglomerates, and production sequence reports from Toulouse and Hamburg final assembly lines. Bottom-up unit economics on flush valve lifecycles and top-down fleet projection models were triangulated against OEM delivery schedules.
Assumptions held fixed include FAA Part 25 and EASA CS-25 regulatory stability, Boeing 737MAX and A320neo production rate trajectories, and titanium alloy pricing within historical volatility bands. Variables tested encompass smart toilet sensor adoption curves across low-cost carrier segments, EU Green Deal circularity mandate implementation timelines, and India DGCA harmonization completion sequencing. CAGRs were derived from segment-level unit projections weighted by technology tier mix across the analysis window. Forecast inputs incorporated narrow-body fleet age profiles, heavy maintenance interval scheduling patterns, and aftermarket retrofit deferral propensities.
Sensitivities concentrate around FAA airworthiness directive acceleration on waste containment standards, EASA fire-resistance amendment scope expansion, and titanium defense sector demand spikes disrupting aerospace grade supply. Cross-checking against IATA fleet forecasts and OEM delivery guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Aircraft Cables Market
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
US Military Aviation Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
Aircraft Jack Market
Aircraft
Evtol Aircraft Market
Aircraft
France Aviation Market
Aircraft
Japan Aviation Market
Aircraft
Aircraft Flight Control System Market