
 Aircraft Manufacturing Market | 2026-2036
Aircraft Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Manufacturing Market Analysis
The gap between premium long-haul platforms and single-aisle commodity aircraft is recalibrating production priorities across the industry. Airbus SE leverages its A320 family dominance to sustain backlog advantages in the narrow-body segment. The Boeing Company anchors wide-body engineering expertise while navigating quality-control reinvestment. Lockheed Martin dominates defense-aerospace integration, occupying a separate margin pool from commercial rivals.
Aircraft manufacturing encompasses the design, fabrication, and assembly of fixed-wing and rotary-wing vehicles with maximum takeoff weights ranging from light-sport categories to wide-body transports exceeding 575 tonnes. The process integrates aluminum-lithium alloys, carbon-fiber reinforced polymers, and titanium structures through automated fiber placement and robotic riveting to produce platforms certified for passenger, cargo, or military missions. Commercial aircraft commands the largest revenue footprint due to fleet renewal cycles and emerging-market airline expansion. Composite materials technology attracts disproportionate engineering investment as airframers pursue weight reduction targets. Defense contractors represent a concentrated end-user segment with multi-year procurement contracts and stringent security classifications.
FAA certification under Part 25 airworthiness standards and EASA CS-25 requirements govern structural integrity, emissions, and noise thresholds for commercial entry. EPA and ICAO carbon-offset mechanisms are tightening CO2 limits, forcing propulsion redesigns and sustainable aviation fuel compatibility. MEE in China enforces domestic content rules that shape COMAC's supplier localization. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment platform economics and determine market access eligibility.
Market Dynamics
The Aircraft Manufacturing Market is experiencing a fundamental recalibration as carbon-fiber reinforced polymers displace aluminum-lithium alloys in primary structures, forcing airframers to retool assembly lines and retrain workforces for automated fiber placement processes.
Growth Catalysts
- Sustainable Aviation Fuel Mandates:ICAO carbon-offset mechanisms and EPA emissions standards are compelling airlines to prioritize next-generation propulsion compatibility, accelerating fleet renewal cycles.
- Southeast Asian Low-Cost Carriers:Airlines in Indonesia, Vietnam, and Thailand are expanding narrow-body orders to replace aging aircraft and capture emerging middle-class passenger traffic.
- Composite Manufacturing Automation:Robotic riveting and automated fiber placement systems are reducing airframe assembly labor hours while improving structural consistency.
Market Restraints
- Titanium Supply Concentration:Russian and Chinese suppliers dominate sponge titanium production, creating input cost volatility and geopolitical sourcing risk for Western airframers.
- Certification Timeline Friction:FAA Part 25 and EASA CS-25 standards for new propulsion architectures are extending type certification cycles, delaying platform entry and freezing capital.
- Skilled Technician Scarcity:Composite repair certification programs and automated systems engineering expertise are concentrated among a shrinking pool of qualified personnel.
Strategic Opportunities
- Urban Air Mobility Infrastructure:Electric vertical takeoff and landing platforms require new manufacturing competencies in battery integration and distributed propulsion.
- India's Defense Procurement:The country's offset policies and indigenization mandates are creating openings for component suppliers to establish domestic production facilities.
- Digital Thread Integration:Model-based engineering and digital twins are converging with additive manufacturing to compress design-to-production timelines.
Industry Challenges
- Quality Control Reinvestment:Airframers must rebuild supplier audit protocols and in-process inspection systems after recent production defect revelations.
- Workforce Transition Complexity:Shifting from aluminum riveting to composite bonding requires retraining thousands of mechanics without disrupting existing output.
- Legacy Platform Support:Maintaining parts availability for out-of-production aircraft strains supplier capacity while new programs demand engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Manufacturing Market |
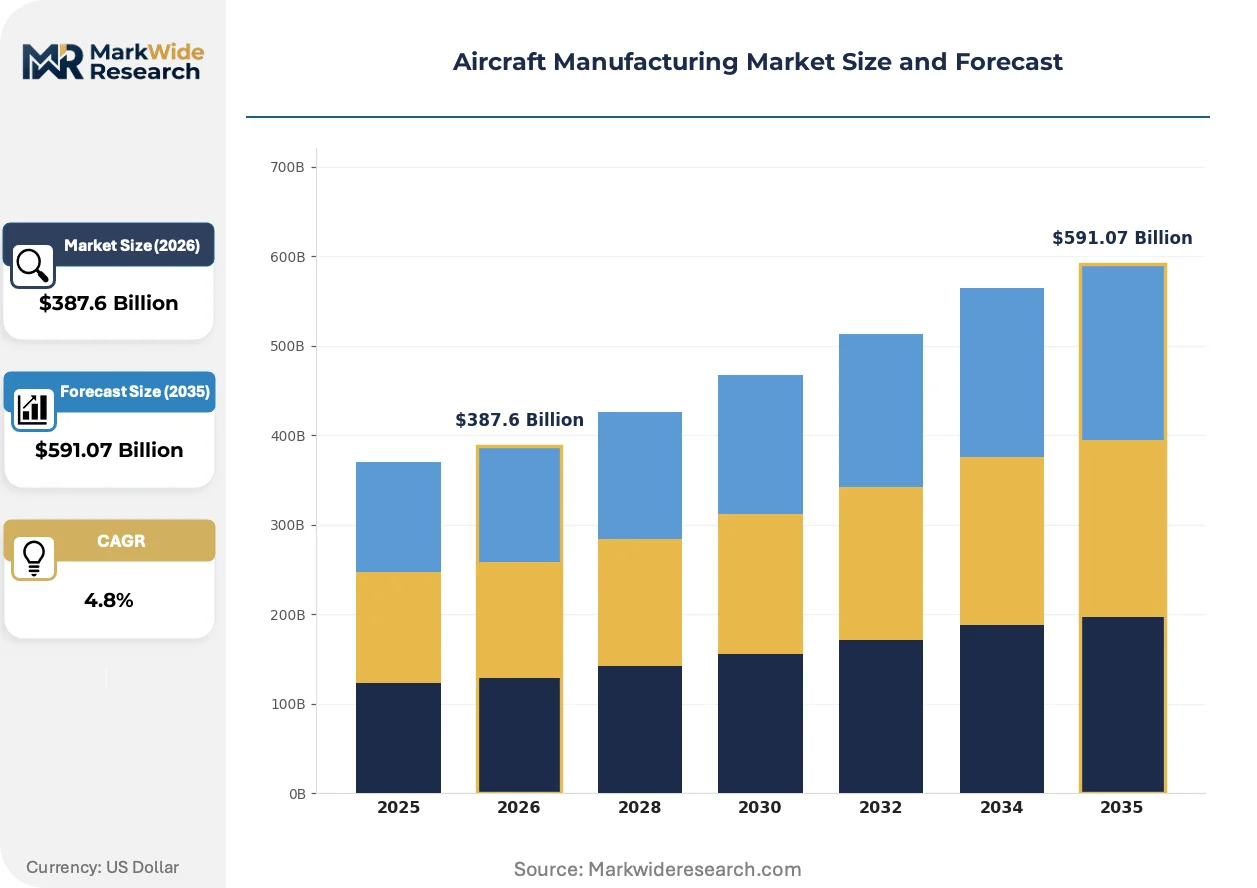
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Aircraft, Business Jets, Military Aircraft, Helicopters Technology: Composite Materials, Avionics, Propulsion Systems, Aerodynamics End User: Aerospace OEMs, Defense Contractors, Airline Operators, Leasing Companies Component: Airframe, Engine, Landing Gear, Electrical Systems |
| Companies Covered | Airbus SE, The Boeing Company, Lockheed Martin, Embraer S.A., Bombardier Inc., Dassault Aviation, Textron Aviation, COMAC, Hindustan Aeronautics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Manufacturing Market Emerging Trajectories
Propulsion electrification and digital manufacturing are converging to transform how aircraft are designed, certified, and produced, with implications rippling through supply chains and regulatory frameworks.
Thermoplastic composites are rewriting structural fabrication economics by enabling welding rather than fastening, reducing assembly touch labor. Regional jet manufacturers and emerging airframers are adopting these materials faster than legacy wide-body producers. The technology is compressing the traditional aluminum-to-composite transition timeline from decades to single program cycles.
EU F-Gas Regulation and the EU Green Deal are tightening hydrofluorocarbon restrictions that affect cabin cooling systems and manufacturing processes. Airframers must redesign environmental control systems or source alternative refrigerants with lower global warming potential. Narrow-body platforms serving European routes face the most immediate compliance deadlines and retrofit obligations.
Airlines are consolidating maintenance, repair, and overhaul procurement through long-term flight-hour agreements rather than transactional parts purchases. This shifts revenue timing and risk allocation to original equipment manufacturers and their tier-one partners. The model is most visible among low-cost carriers in Southeast Asia and Middle Eastern network carriers seeking operational predictability.
Aircraft Manufacturing Market Segmentation
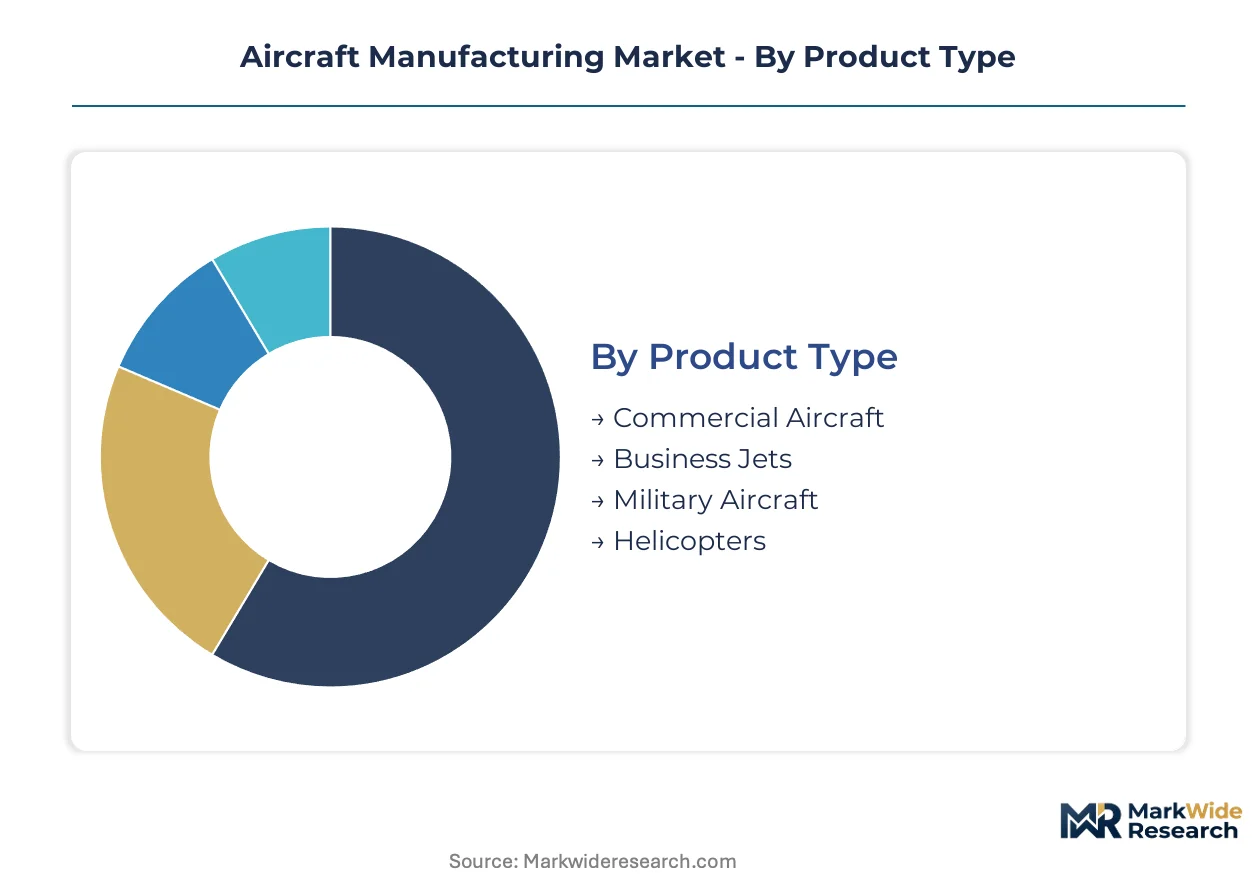
Aircraft manufacturing segmentation reveals how capital allocation, certification requirements, and fleet renewal cycles concentrate value across distinct technical and commercial boundaries. Understanding these divisions exposes where procurement power resides and which technologies command premium positioning.
Product Type:
Buyers in this category separate by mission duration, passenger capacity, and regulatory certification pathway rather than unit economics alone.
- Commercial Aircraft:Narrow-body and wide-body platforms certified under FAA Part 25 and EASA CS-25 standards dominate production backlogs. Fleet replacement cycles in Southeast Asia and China concentrate demand for single-aisle configurations that balance route flexibility with fuel efficiency mandates.
- Military Aircraft:Fixed-wing combat and transport platforms operate under national security classifications with multi-year procurement contracts. Defense contractors in the US and Europe anchor this segment through classified development programs and offset agreement structures.
- Business Jets:Light, mid-size, and long-range configurations serve fractional ownership fleets and high-net-worth individuals.
- Helicopters:Civil and military rotary-wing platforms address vertical lift requirements in offshore energy and emergency medical services.
Commercial aircraft leads volumes today; military aircraft is gaining share fastest through Indo-Pacific defense procurement acceleration.
Technology:
Investment intensity and patent density distinguish segments where engineering differentiation creates sustainable margin pools.
- Composite Materials:Carbon-fiber reinforced polymers and thermoplastic composites displace aluminum-lithium alloys in primary structures. Automated fiber placement systems reduce airframe assembly labor hours while Boeing and Airbus retrain workforces for bonding rather than riveting processes.
- Propulsion Systems:Turbofan architectures face ICAO and EPA emissions redesigns for sustainable aviation fuel compatibility. Geared turbofan and open-rotor concepts attract engineering investment as airframers pursue CO2 reduction targets without sacrificing thrust performance.
- Avionics:Flight management systems and sensor fusion architectures integrate model-based engineering approaches.
- Aerodynamics:Winglet designs and laminar flow surfaces optimize fuel burn across mission profiles.
Composite materials leads volumes today; propulsion systems is climbing the fastest as certification timelines extend for next-generation architectures.
End User:
Contract structure and risk allocation separate buyers operating on flight-hour agreements versus transactional procurement models.
- Aerospace OEMs:Boeing, Airbus, and COMAC integrate tier-one and tier-two suppliers through long-term partnership frameworks. These manufacturers consolidate subsystem procurement while retaining final assembly and type certification authority under FAA and EASA jurisdiction.
- Airline Operators:Full-service and low-cost carriers in Indonesia, Vietnam, and Thailand drive narrow-body order concentration. These operators shift toward power-by-the-hour maintenance contracts that transfer component risk to original equipment manufacturers.
- Defense Contractors:Lockheed Martin and national champions execute classified programs with security-cleared supply chains.
- Leasing Companies:Aircraft lessors manage residual value exposure through specification standardization and portfolio diversification.
Aerospace OEMs leads volumes today; airline operators is expanding most quickly through Southeast Asian fleet renewal cycles.
Component:
Subassembly complexity and supplier certification requirements determine where manufacturing value concentrates across the production chain.
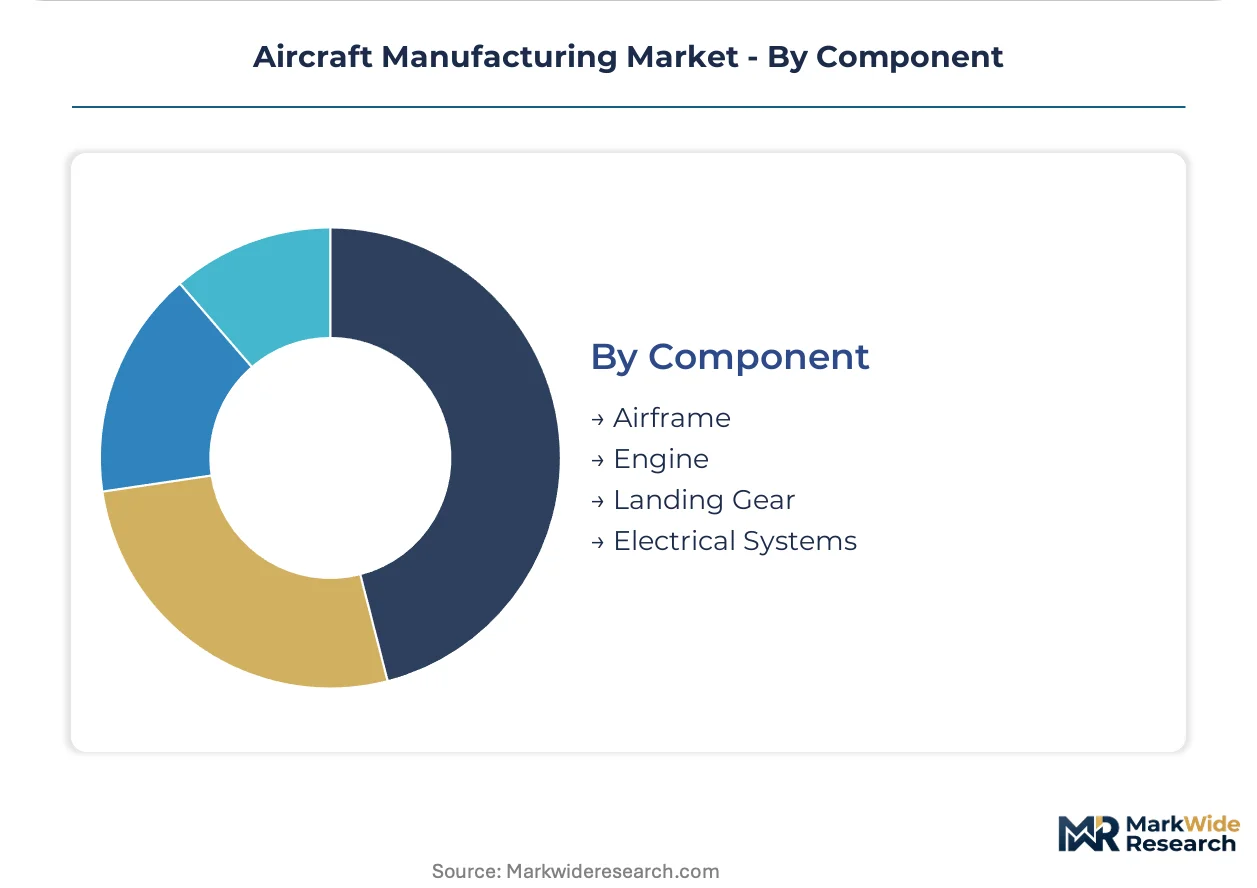
- Airframe:Fuselage sections, wings, and empennage structures integrate aluminum-lithium alloys with carbon-fiber reinforced polymers. Robotic riveting and automated fiber placement systems compress assembly timelines while FAA and EASA structural integrity standards govern material qualification.
- Engine:Turbofan propulsion systems from GE Aerospace, Pratt & Whitney, and Rolls-Royce represent the largest single component value share. These powerplants face tightening EPA and ICAO emissions standards that force thermal efficiency redesigns and sustainable aviation fuel compatibility testing.
- Landing Gear:Oleo-pneumatic shock absorption and carbon brake systems address weight reduction targets.
- Electrical Systems:Power distribution and environmental control architectures support more-electric aircraft initiatives.
Airframe leads volumes today; engine is gaining share fastest through propulsion electrification investment and emissions compliance redesigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's narrow-body production scales faster than France's wide-body engineering centers, while Indonesia and Vietnam concentrate fleet renewal demand from low-cost carriers. Regulatory divergence between FAA, EASA, and MEE certification pathways fragments platform economics across jurisdictions.
United States
Defense procurement and commercial wide-body engineering anchor manufacturing activity in Washington State and South Carolina clusters. FAA Part 25 certification standards govern structural integrity and emissions thresholds for domestic entry. Wichita, Kansas hosts concentrated business jet fabrication while Seattle-area facilities integrate carbon-fiber structures through automated fiber placement.
China
COMAC's C919 narrow-body program drives domestic supplier localization and fleet replacement demand from state-owned airlines. MEE enforces domestic content rules that reshape tier-one and tier-two procurement relationships. The Yangtze River Delta concentration around Shanghai integrates final assembly with Pudong-based avionics and propulsion subsystem manufacturing.
France
Airbus SE's A320 family dominance sustains Toulouse as a narrow-body engineering and final assembly hub. EASA CS-25 requirements and EU Green Deal emissions mandates force propulsion redesigns for sustainable aviation fuel compatibility. The Occitanie region concentrates composite wing fabrication and automated riveting process development.
Indonesia
Lion Air Group and Garuda Indonesia drive narrow-body order concentration to replace aging aircraft and capture emerging middle-class passenger traffic. The country's national aviation regulator aligns certification processes with EASA standards to accelerate fleet entry. Batam and Bintan industrial zones host maintenance, repair, and overhaul facilities serving Southeast Asian operators.
Vietnam
VietJet Air and Bamboo Airways expand fleet orders for single-aisle configurations balancing route flexibility with fuel efficiency mandates. The central bank's foreign exchange policies influence lease financing structures for imported platforms. Hanoi and Ho Chi Minh City concentrate airline headquarters procurement decisions and flight-hour agreement negotiations with original equipment manufacturers.
Aircraft Manufacturing Market Vendor Landscape
Top-tier vendors anchor wide-body and narrow-body platform certification, while mid-tier specialists concentrate on regional jets and business aviation segments. The vendor base organizes around three strategic archetypes: integrated airframers controlling final assembly and type certification, propulsion system specialists supplying turbofan architectures, and composite material innovators enabling weight reduction targets. Competitive moves center on supplier audit protocol reinvestment and workforce retraining programs for automated manufacturing processes.
Within the integrated airframer tier, Airbus SE and The Boeing Company occupy positions exemplifying divergent segment priorities—narrow-body backlog concentration versus wide-body engineering expertise. Lockheed Martin represents the defense-aerospace integration archetype with classified program execution and security-cleared supply chains distinct from commercial rivals. These three entities illustrate how certification authority, procurement scale, and mission classification separate margin pools across the manufacturing landscape.
| Leading Market Players |
|---|
| Airbus SE |
| The Boeing Company |
| Lockheed Martin |
| Embraer S.A. |
| Bombardier Inc. |
| Dassault Aviation |
| Textron Aviation |
| COMAC |
| Hindustan Aeronautics |
| Others |
Supply Flow & Price Mechanics
EU Green Deal emissions mandates and ICAO carbon-offset mechanisms gate qualified supply access for airframers seeking premium-tier platform positioning, with sustainable aviation fuel compatibility certification separating suppliers who capture long-term contracts from those relegated to spot-market titanium and aluminum-lithium alloy sales.
Pricing Analysis
Capacity additions in China's Yangtze River Delta cluster are reshaping price floors for carbon-fiber reinforced polymers and automated fiber placement equipment. Three-tier pricing structure across premium, standard, and economy levels reflects FAA Part 25 certification tier, composite material qualification status, and after-sales service bundling. Pricing pressure stems from Russian titanium supply disruption forcing Western airframers toward higher-cost sponge alternatives. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, while defense contractors absorbing multi-year procurement contracts show lowest.
Supply Chain Analysis
Regional distribution centers in Toulouse, Hamburg, and Charleston anchor hub-and-spoke patterns for airframe subassemblies and engine modules. Supply concentrates in China for rare-earth magnet processing, Russia for sponge titanium, and Japan for carbon-fiber precursor chemicals. Robotic riveting systems, thermoplastic composite welding equipment, and avionics sensor fusion architectures draw from concentrated vendor pools. Single-source vulnerability in qualified composite repair certification programs threatens aftermarket service continuity. Distribution runs through tier-one integrators holding EASA CS-25 and FAA Part 25 supplier approval status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through composite manufacturing automation compressing airframe assembly labor hours, while premium-tier positioning accrues to suppliers with dual FAA-EASA certification and sustainable aviation fuel compatibility credentials.
For Market Incumbents: Anchor wide-body engineering expertise through supplier audit protocol reinvestment after recent production defect revelations. Lock in titanium sponge alternatives from Japanese and Kazakh sources to mitigate Russian supply concentration. Prioritize automated fiber placement capacity expansion in Charleston and Toulouse clusters to capture narrow-body backlog advantages from Airbus A320 family dominance. For New Entrants and Emerging Players: Digital-channel routes through model-based engineering platforms offer lowest-friction entry into tier-two composite subassembly supply. Target India's defense procurement offset policies requiring domestic component production facilities. Urban air mobility battery integration and distributed propulsion manufacturing represent most penetrable white-space segments. Pursue power-by-the-hour maintenance contract partnerships with Vietnamese and Indonesian low-cost carriers seeking operational predictability. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier composite material innovators lacking EASA CS-25 qualification but holding automated fiber placement process patents. Five-to-ten-year viability hinges on successful workforce retraining from aluminum riveting to thermoplastic welding without disrupting existing output. Acquisition target archetype: specialists in thermoplastic composite wing fabrication with pending FAA certification. Signal to watch: MEE domestic content rule enforcement accelerating COMAC supplier localization and foreign joint venture mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Manufacturing Automation | Automated fiber placement reduces airframe assembly labor hours while Boeing and Airbus retrain workforces for bonding processes. |
| Sustainable Aviation Fuel Certification | ICAO and EPA emissions standards force turbofan redesigns that freeze capital until compatibility testing completes. |
| Supplier Audit Protocol Reinvestment | Airframers rebuild in-process inspection systems after quality-control failures revealed in recent production defect investigations. |
| Urban Air Mobility Infrastructure | Electric vertical takeoff platforms require battery integration competencies outside traditional aerospace supplier capabilities. |
| India Defense Offset Localization | Indigenization mandates create openings for component suppliers to establish domestic production facilities under classified program security clearance. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airframe program managers, propulsion system procurement leads, composite material R&D directors, and EASA certification engineers with secondary validation against FAA Part 25 type certificate databases, EASA CS-25 airworthiness directives, ICAO emissions compliance filings, and customs records for titanium sponge and carbon-fiber precursor trade flows. Bottom-up platform delivery forecasts triangulated against top-down fleet renewal cycle projections.
Segment-weighting approaches applied product type, technology, end user, and component dimensions across the modeling period, with narrow-body and wide-body platform splits, composite versus aluminum-lithium material shares, and commercial versus military procurement channels driving value allocation. CAGRs derived from regression analysis against airline fleet order backlogs, defense procurement appropriations, and sustainable aviation fuel mandate implementation timelines. Forecast inputs incorporated robotic riveting adoption curves and thermoplastic composite welding process maturation.
Geopolitical supply disruption, certification timeline extensions for next-generation propulsion architectures, and workforce retraining bottlenecks are the dominant revision risks that could compress or extend projected value trajectories. Forecasts reflect documented assumptions around FAA-EASA regulatory convergence and COMAC production scaling. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Latin America Business Jet Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
Light and Very Light Jets Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Aircraft Radome Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Winglets Market
Aircraft
Commercial Aircraft Leasing Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Aviation Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Supersonic Jet Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market