
 America Attack Helicopter Market | 2026-2036
America Attack Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
America Attack Helicopter Market Outlook
The defense procurement channel is narrowing as Pentagon acquisition reform consolidates vendor pools. Lockheed Martin Corporation leverages its Sikorsky lineage to sustain dominance in heavy-lift attack platforms. Boeing anchors Navy and Marine Corps rotary programs through the AH-1Z Viper lineage. Bell Textron competes aggressively in the light-to-medium segment with its 360 Invictus proposal for Future Attack Reconnaissance Aircraft.
America attack helicopters are rotary-wing military aircraft designed for close air support, anti-armor strikes, and armed reconnaissance, typically featuring tandem crew seating, stub-wing weapon stations, and integrated target acquisition systems. These platforms serve primarily to deliver precision fires in contested airspace while operating from austere forward locations. Multi-role helicopters represent the fastest-expanding product category as operators demand modular mission systems over single-purpose designs. Advanced avionics segments command premium positioning due to sensor fusion and manned-unmanned teaming requirements. Heavy attack helicopters remain the most mature margin pool, sustained by Congressional funding for Apache fleet recapitalization.
The U.S. Department of Defense shapes demand through Future Vertical Lift directives, while FAA regulations govern civilian airspace integration for dual-use platforms. Brazil's Department of Aerospace Science and Technology and Colombia's Ministry of National Defense influence regional procurement through offset requirements and technology transfer mandates. Stakeholders must monitor how congressional appropriations align with platform retirement timelines and next-generation development milestones.
Market Dynamics
The U.S. Army's Future Vertical Lift program is compressing procurement timelines and forcing incumbent suppliers to revalidate airframe designs against modular open systems architecture requirements.
Growth Catalysts
- Counter-Insurgency Doctrine:Military organizations across the Americas are expanding rotary-wing fleets for border security missions, creating sustained demand for armed reconnaissance platforms.
- FAA Airspace Integration:Regulatory pathways for dual-use helicopter certification are enabling civilian technology spinbacks into military avionics upgrades.
- Sensor Fusion Architectures:Manned-unmanned teaming requirements are mandating interoperable targeting systems across fleet modernization programs.
Market Restraints
- Turboshaft Engine Concentration:Supply bottlenecks in specialized powerplant manufacturing limit production scalability for next-generation platforms.
- Congressional Appropriation Cycles:Multi-year funding authorization gaps create procurement uncertainty for fleet recapitalization timelines.
- Unmanned Combat Aerial Vehicles:Armed drone proliferation presents mission overlap risk for traditional attack helicopter strike roles.
Strategic Opportunities
- Brazilian Offset Requirements:Technology transfer mandates from the Department of Aerospace Science and Technology create local assembly partnerships for regional fleet expansion.
- Modular Mission Systems:Convergence of digital backbone standards with swappable payload modules enables single-airframe multi-role configurations.
- Marine Corps Distributed Operations:Expeditionary basing concepts demand ship-compatible attack platforms with reduced logistical footprints.
Industry Challenges
- Rotorcraft Engineering Talent:Specialized aeromechanics and flight control expertise shortages delay development program milestones.
- Legacy Fleet Integration:New avionics architectures must maintain backward compatibility with existing Apache and Viper maintenance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | America Attack Helicopter Market |
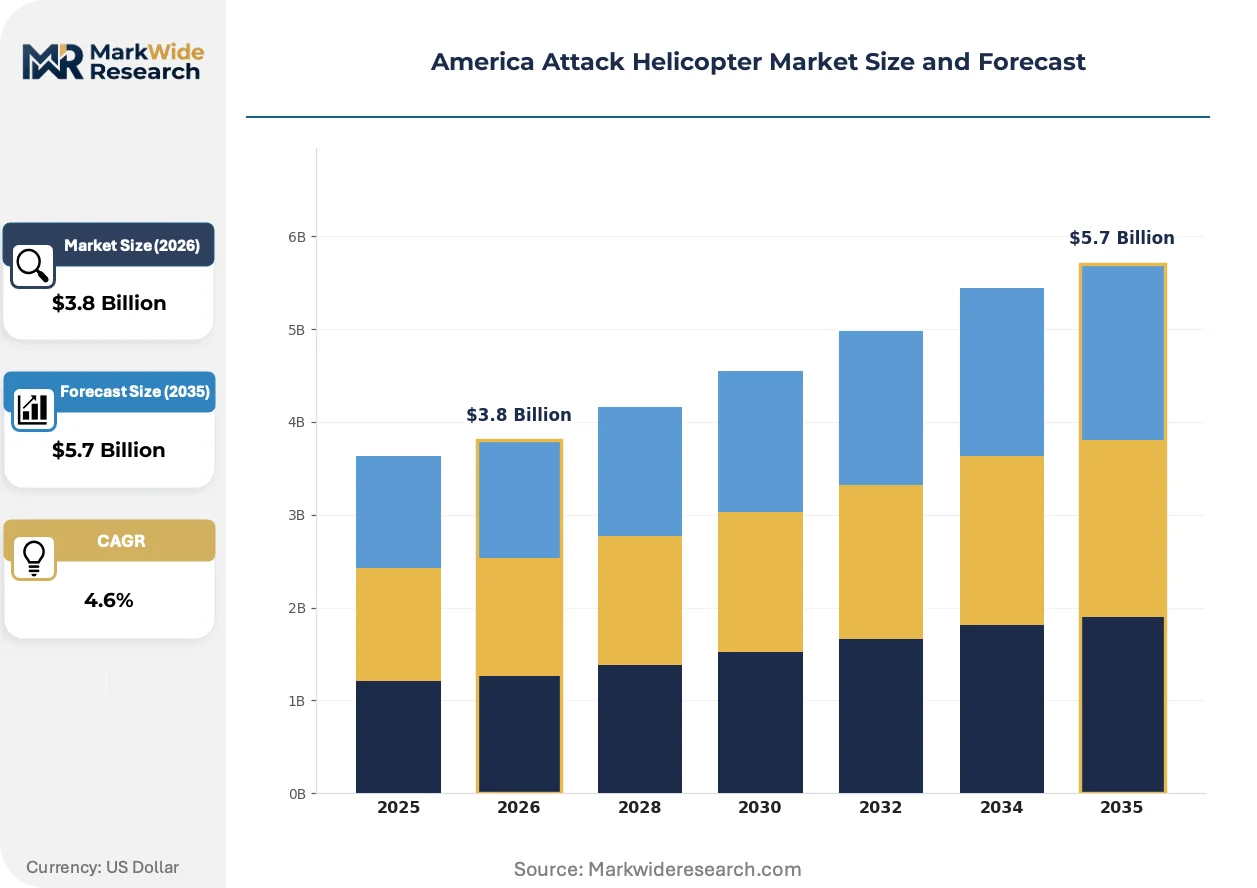
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Attack Helicopters, Heavy Attack Helicopters, Medium Attack Helicopters, Multi-role Helicopters End User: Military Organizations, Government Agencies, Defense Contractors, Private Security Firms Technology: Advanced Avionics, Stealth Technology, UAV Integration, Weapon Systems Deployment: Onshore, Offshore, Forward Operating Bases, National Defense Operations |
| Companies Covered | The Boeing Company, Lockheed Martin Corporation, Bell Textron Inc., Textron Inc., Airbus SE, MD Helicopters Inc., Sikorsky Aircraft Corporation, Leonardo S.p.A., Rostec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
America Attack Helicopter Market Strategic Shifts
Digital engineering practices are compressing design-validation cycles while open systems mandates are fragmenting traditional supplier hierarchies across the attack helicopter industrial base.
Digital mission management software is virtualizing cockpit workload distribution and sensor control interfaces. Army Aviation units are fielding these architectures through iterative block upgrades rather than platform replacement. This virtualization is collapsing the traditional separation between flight-critical and mission-critical computing domains.
The FAA's updated airworthiness criteria for optionally piloted aircraft are creating certification precedents for autonomous flight modes in military derivatives. These standards are forcing manufacturers to document safety cases for degraded-vision autonomy. Heavy attack helicopter programs are absorbing these compliance costs through dedicated flight test budgets.
Service contract unbundling is separating platform sustainment from original equipment manufacturer control. Defense agencies are fragmenting maintenance execution across regional depots and third-party logistics providers. Colombia's Ministry of National Defense has pioneered this approach through performance-based logistics pilots for its rotary fleet.
America Attack Helicopter Market Segmentation
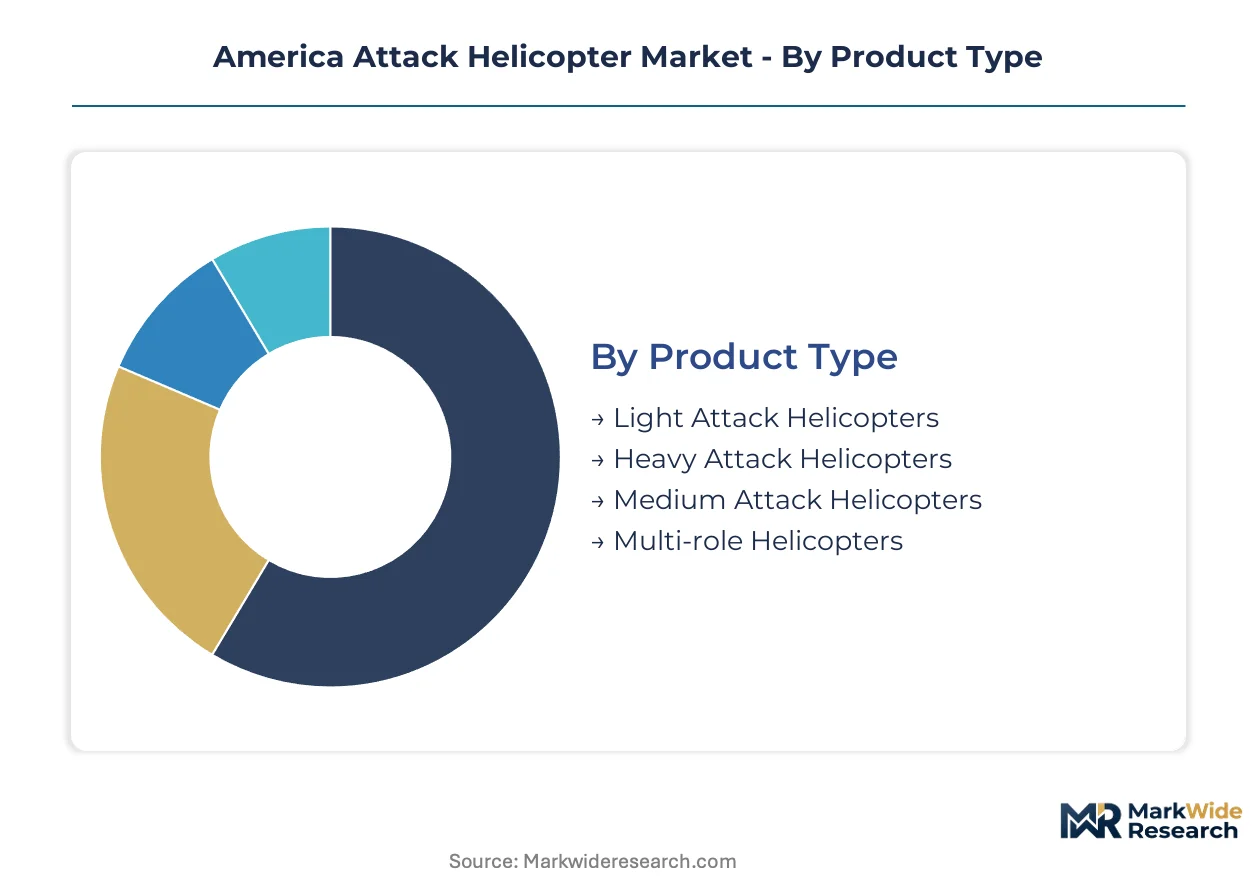
Attack helicopter procurement patterns diverge sharply across product weight classes and mission profiles. After-sales service intensity varies by segment, with heavy platforms demanding depot-level overhaul infrastructure while light variants rely on field-replaceable modules.
Product Type:
After-sales service intensity escalates with airframe weight and powerplant complexity, driving divergent support strategies across the product spectrum.
- Multi-role Helicopters:Modular mission system architectures enable rapid reconfiguration between armed reconnaissance, close air support, and medical evacuation roles. United States Army Aviation units prioritize these platforms for Future Vertical Lift compatibility, trading single-mission optimization for operational flexibility across contested environments.
- Heavy Attack Helicopters:Tandem-seat designs with integrated fire-control radars and long-range anti-armor missile carriage define this category. Congressional appropriations for Apache fleet recapitalization anchor demand concentration, though turboshaft engine supply constraints limit production scaling.
- Light Attack Helicopters:Single-engine configurations optimized for urban operations and austere forward basing.
- Medium Attack Helicopters:Balanced payload-range profiles serving Marine Corps expeditionary requirements.
By volume, Heavy Attack Helicopters leads. By growth pace, Multi-role Helicopters is expanding most quickly.
End User:
Customer type determines contracting mechanisms, with military organizations driving multi-year procurement while private actors favor lease-to-own structures.
- Military Organizations:Department of Defense budget cycles shape platform selection through Program Objective Memorandum processes. United States Army and Marine Corps modernization accounts concentrate regional demand, with service-specific requirements for shipboard compatibility and network-centric warfare integration.
- Defense Contractors:Lease arrangements and performance-based logistics contracts dominate this segment. Colombian Ministry of National Defense pilots have established precedent for contractor-operated maintenance, unbundling sustainment from manufacturer control.
- Government Agencies:Border security and counter-narcotics missions drive rotary-wing fleet expansion.
- Private Security Firms:Limited procurement volumes constrained by FAA dual-use certification pathways.
By fleet size, Military Organizations dominates. By contract innovation velocity, Defense Contractors is gaining share fastest.
Technology:
Technology tier dictates pricing architecture, with sensor fusion packages commanding substantial premiums over baseline avionics configurations.
- Advanced Avionics:Integrated helmet-mounted displays, multi-spectral sensors, and digital backbone architectures enable manned-unmanned teaming. Future Vertical Lift mandates for open systems interoperability are fragmenting traditional supplier hierarchies, forcing incumbents to revalidate designs against modular standards.
- UAV Integration:Data link terminals and cooperative engagement protocols transform attack helicopters into aerial command nodes. United States Army experimentation with attritable wingman concepts concentrates development resources on this capability layer.
- Weapon Systems:Precision-guided munitions and modular stub-wing stations.
- Stealth Technology:Acoustic signature reduction and infrared suppression for contested airspace penetration.
By installed base, Weapon Systems leads. By development priority, UAV Integration shows the steepest expansion trajectory.
Deployment:
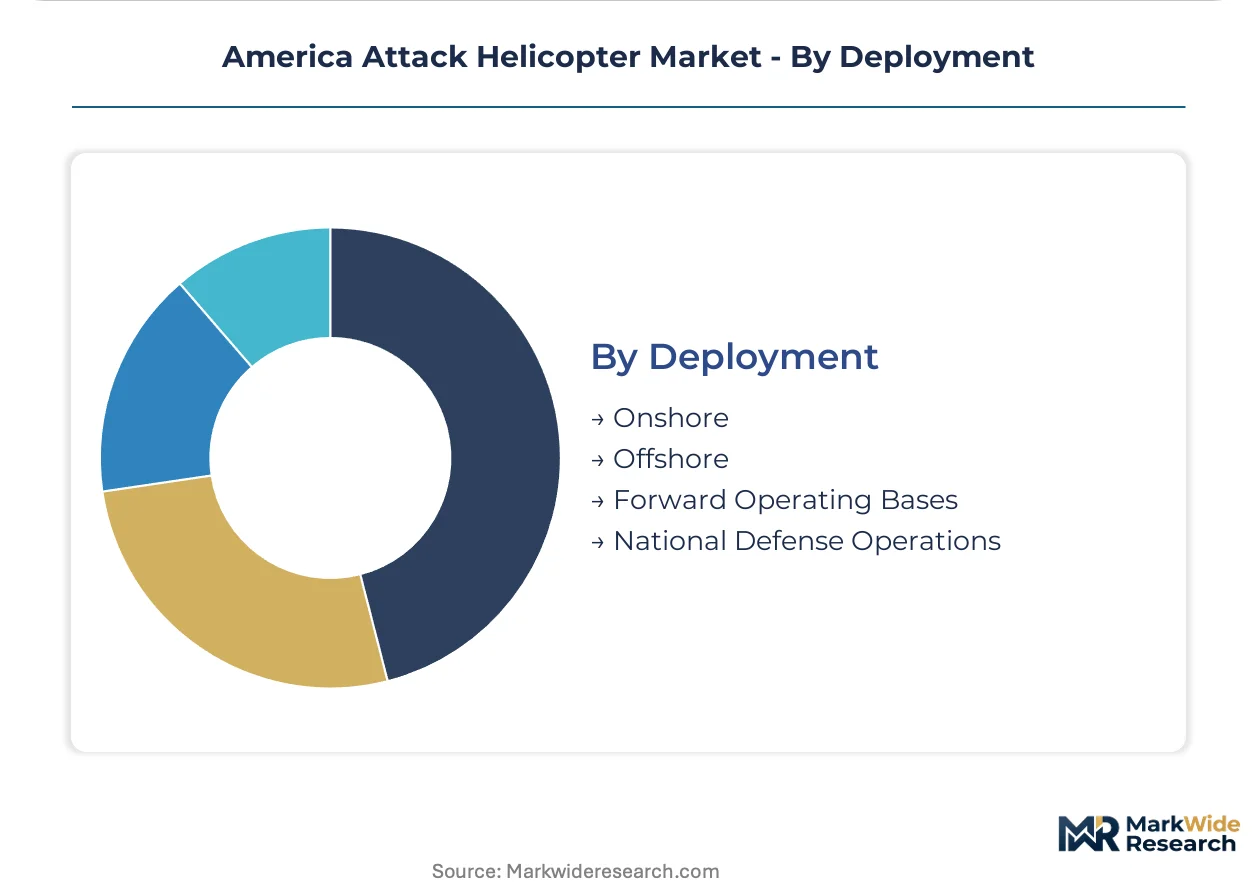
Deployment mode shapes logistics footprint requirements, with forward operating base configurations demanding reduced maintenance intervals and austere environment tolerance.
- Forward Operating Bases:Expeditionary basing concepts require ship-compatible platforms with collapsible rotor systems and reduced fuel consumption profiles. Marine Corps distributed operations doctrine prioritizes these specifications, compressing procurement timelines for expeditionary variants.
- National Defense Operations:Continental United States basing supports training, readiness, and rapid response missions. Army National Guard units concentrate rotary-wing assets under this deployment mode, with state-level emergency response requirements influencing platform selection.
- Onshore:Permanent installation support for homeland defense and training pipelines.
- Offshore:Maritime prepositioning and amphibious assault platform integration.
By mission tempo, National Defense Operations leads. By doctrinal emphasis, Forward Operating Bases is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA governs airspace integration pathways that shape dual-use platform development across the Americas. Military procurement concentrates in sovereign defense budgets with distinct offset and technology transfer requirements. Regional fleet modernization cycles vary by threat perception and fiscal capacity.
United States
The U.S. Army and Marine Corps anchor regional demand through Future Vertical Lift program mandates. Congressional appropriations for Apache recapitalization sustain heavy attack helicopter production lines. The Sikorsky facility in Connecticut and Boeing's Mesa, Arizona operations concentrate airframe final assembly and systems integration capacity.
Brazil
The Department of Aerospace Science and Technology imposes local content thresholds on foreign suppliers seeking naval and army aviation contracts. Counter-narcotics missions along Amazon borders drive armed reconnaissance platform requirements. São Paulo state hosts Embraer defense subsidiaries that partner with international primes on technology transfer arrangements.
Canada
The Royal Canadian Air Force rotary-wing recapitalization emphasizes Arctic operating envelope specifications. Defence Procurement Strategy guidelines mandate industrial and technological benefits from foreign vendors. Montreal aerospace clusters sustain subsystem engineering for platform modifications and avionics integration.
Colombia
The Ministry of National Defense pioneered performance-based logistics contracts that unbundle sustainment from manufacturer control. Counter-insurgency operations in mountainous terrain demand high-hot performance characteristics. Bogotá serves as the administrative hub for regional fleet management and contractor-operated maintenance pilots.
Mexico
The Secretariat of National Defense expands rotary assets for border security and internal security missions. Federal procurement regulations emphasize domestic assembly partnerships for fleet expansion programs. Querétaro aerospace manufacturing corridors attract subsystem suppliers serving both military and civilian helicopter programs.
America Attack Helicopter Market Competitive Environment
Legacy defense primes and specialized rotorcraft houses split the market along platform weight-class lines. Incumbents with established military airworthiness certifications command structural advantages in Pentagon program competitions. Two archetypes dominate: vertically integrated aerospace conglomerates with multi-domain portfolios, and rotorcraft specialists with focused engineering depth. Competitive moves concentrate on modular open systems architecture compliance and strategic partnerships for foreign market access.
Within the integrated prime tier, Lockheed Martin Corporation and The Boeing Company exemplify contrasting platform legacies. Lockheed Martin leverages its Sikorsky lineage in heavy-lift segments, while Boeing anchors Marine Corps programs through the AH-1Z lineage. Bell Textron Inc. occupies a position bridging light-to-medium attack categories with Future Attack Reconnaissance Aircraft proposals. These three entities represent the full spectrum of incumbent positioning against Future Vertical Lift requirements.
| Leading Market Players |
|---|
| The Boeing Company |
| Lockheed Martin Corporation |
| Bell Textron Inc. |
| Textron Inc. |
| Airbus SE |
| MD Helicopters Inc. |
| Sikorsky Aircraft Corporation |
| Leonardo S.p.A. |
| Rostec |
| Others |
Value Chain & Pricing Dynamics
Mesa, Arizona and Stratford, Connecticut anchor final assembly capacity for heavy attack helicopter platforms, concentrating pricing power with incumbents holding FAA military airworthiness certifications. Congressional appropriation cycles compress procurement timelines, forcing buyers into multi-year commitments that lock in premium positioning for certified suppliers.
Pricing Analysis
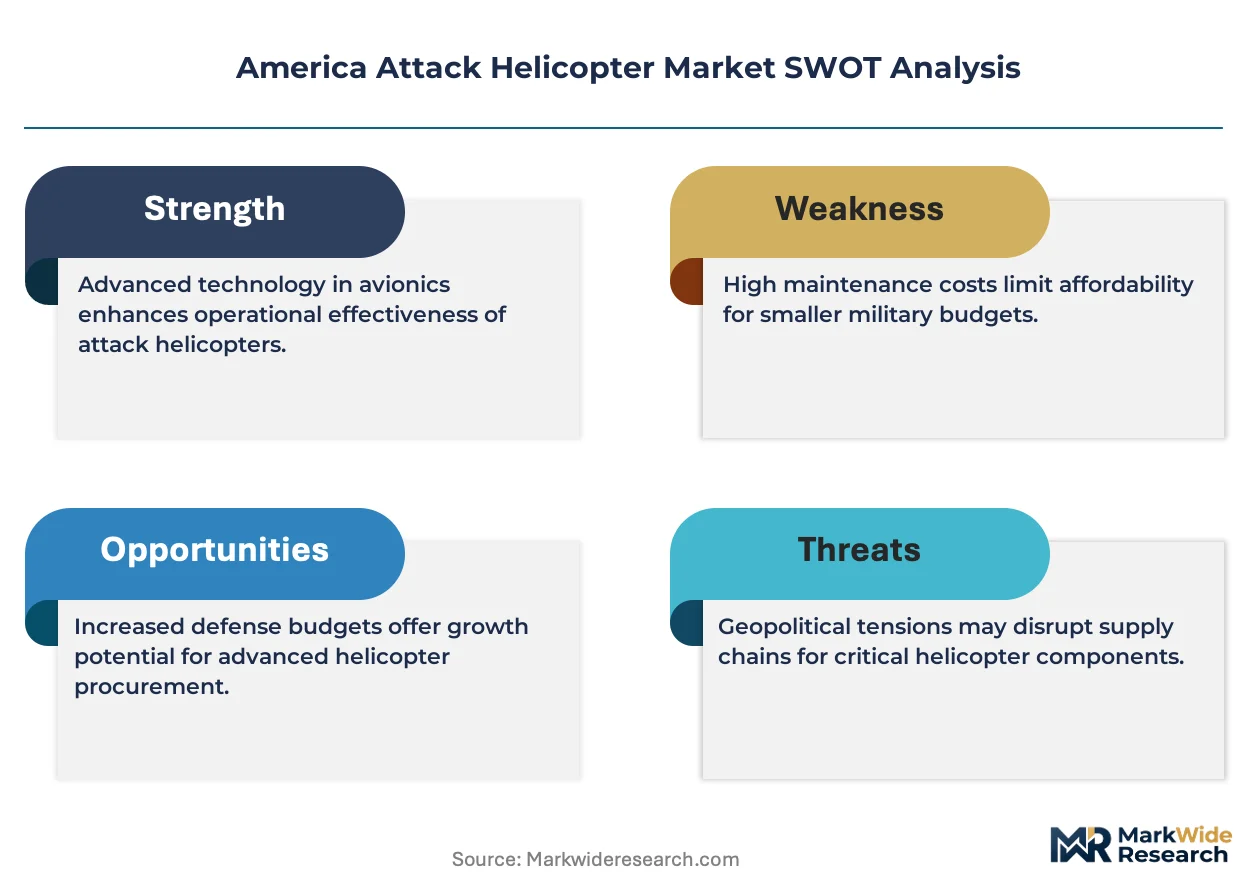
Domestic U.S. pricing for heavy attack helicopters commands substantial premiums over Latin American procurement, reflecting FAA certification compliance costs and congressional funding authorization requirements. Three-tier pricing structure across advanced avionics packages, baseline configurations, and legacy refurbishment programs separates mission-capable premiums from economy-tier sustainment options. Cost compression in light attack segments is intensifying because Brazilian offset requirements mandate local assembly partnerships that fragment volume scale. Government agencies exhibit highest price sensitivity due to fixed budget cycles, while Marine Corps expeditionary requirements prioritize capability over unit cost.
Supply Chain Analysis
Lockheed Martin's Sikorsky operations, Boeing's Mesa facility, and Bell Textron's Amarillo plant hold concentrated airframe integration capacity for the Americas market. Turboshaft engine manufacturing draws from specialized suppliers in the United States, United Kingdom, and France, with rotor system composites resting on carbon fiber precursors from Japan and Germany. Single-source vulnerability in advanced turbine blade casting creates production bottlenecks when military procurement surges align across multiple programs. Distribution runs through defense logistics agency depots and contractor-operated regional maintenance centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based logistics contracts now expand faster than hardware procurement, transforming attack helicopter economics toward service-attach revenue models. Colombian Ministry of National Defense pilots demonstrate how unbundled sustainment creates recurring revenue streams exceeding original platform margins.
For Market Incumbents: Build regulatory certification moats through accelerated FAA military derivative approvals for optionally piloted flight modes. Deepen backward integration into turboshaft engine component manufacturing to offset single-source casting vulnerabilities. Secure congressional multi-year funding commitments before Apache recapitalization peaks shift procurement toward Future Vertical Lift platforms. For New Entrants and Emerging Players: Build out modular mission system partnerships with Brazilian Department of Aerospace Science and Technology offset programs, where technology transfer mandates create accessible entry points. Target Colombian performance-based logistics pilots as the most penetrable contract innovation segment. Pursue ship-compatible lightweight platform development aligned with Marine Corps distributed operations doctrine. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor fusion and UAV integration specialists over legacy airframe manufacturers. Long-term viability hinges on open systems architecture compliance rather than proprietary platform lock-in. Acquisition targets should demonstrate manned-unmanned teaming software stacks and modular payload certification pathways. Watch Future Vertical Lift downselect announcements as inflection signals for supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Open Systems Certification | FAA airworthiness precedents for autonomous flight modes accelerate military derivative approvals. |
| Performance-Based Logistics Expansion | Colombian Ministry pilots establish contractor-operated maintenance as standard regional practice. |
| Turboshaft Supply Diversification | Backward integration into blade casting reduces single-source exposure during procurement surges. |
| Brazilian Offset Partnership | Department of Aerospace Science and Technology mandates create local assembly joint ventures. |
| Marine Expeditionary Platform Development | Ship-compatible rotor systems capture distributed operations doctrine procurement priority. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of Department of Defense budget justifications, FAA certification databases, and congressional appropriation records. Program managers at Army Aviation and Marine Corps rotary-wing commands, procurement officers at the Colombian Ministry of National Defense, and sustainment directors at defense logistics depots provided operational perspective. Bottom-up platform delivery data triangulates against top-down defense expenditure analysis across the Americas.
Forecast inputs include Future Vertical Lift program milestone schedules, congressional authorization timelines, and regional offset requirement evolution. Segmentation dimensions span product weight class, end-user contracting mechanism, technology tier, and deployment mode. CAGRs derive from regression analysis of historical procurement cycles projected across the modeling period. Turboshaft engine production capacity and manned-unmanned teaming technology maturation curves inform scenario weighting.
Sensitivities concentrate around congressional appropriation delays, FAA certification timeline extensions, and unmanned combat aerial vehicle mission overlap acceleration. Forecasts reflect assumptions about Future Vertical Lift program continuity and Brazilian local content threshold stability. Quarterly review of Program Objective Memorandum submissions and congressional defense subcommittee markups is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Heavy-Lift Helicopter Market
Aircraft
France Aviation Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Aircraft Cables Market
Aircraft
Hybrid Aircraft Market
Aircraft
Manned Evtol Crafts Market
Aircraft
United States Aerospace and Defense Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Aircraft Fairings Market
Aircraft
Europe Aircraft Manufacturing Market
Aircraft
Global Aircraft Towbars Market
Aircraft
Australia Aviation Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Commercial Aircraft Landing Gear Market