
 Aerobatic Aircraft Market | 2026-2036
Aerobatic Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Aerobatic Aircraft Market Analysis
Modular avionics bundling is hardening as the dominant product-configuration pattern across aerobatic aircraft portfolios. Van's Aircraft leverages kit-based customization to sustain its stronghold in the amateur-built segment. EXTRA Flugzeugproduktions anchors premium factory-built deliveries through controlled European distribution. American Champion Aircraft Corporation competes on metal-aircraft heritage and domestic parts availability.
An aerobatic aircraft is a fixed-wing airplane engineered to withstand sustained negative and positive G-loads beyond standard utility category limits, typically featuring reinforced wing spars, symmetrical airfoils, and inverted fuel and oil systems for continuous inverted flight. Its primary commercial purpose centers on pilot training, competition scoring, and spectator entertainment through precision maneuver execution. Single-engine monoplanes dominate unit volume owing to simpler maintenance profiles and lower operating economics, while carbon fiber composite construction captures expanding share among factory-built platforms seeking weight reduction and stiffness gains. Training and leisure flying applications absorb the majority of deliveries as flight schools modernize fleets and affluent private pilots pursue type ratings.
FAA Part 23 reform and EASA CS-23 standards govern airworthiness certification, with both agencies tightening structural fatigue requirements for repetitive aerobatic loading cycles. Military end users add national defense procurement regulations that mandate interoperability with existing trainer ecosystems. Stakeholders must monitor evolving composite repair protocols and their acceptance by national aviation authorities as these materials penetrate higher-stress aerobatic designs.
Market Dynamics
EASA's updated Part-CS-23 certification requirements for aerobatic category aircraft are forcing manufacturers to redesign fatigue-testing protocols and extend compliance timelines, compressing margins for smaller airframe builders.
Growth Catalysts
- Eastern European military procurement:Flight training academies in Poland, Hungary, and Romania are expanding high-G tolerance platform orders under NATO interoperability mandates.
- Composite manufacturing clusters:Germany's Munich-Augsburg corridor concentrates specialized carbon fiber layup expertise and certified repair stations for aerobatic airframes.
- FAA Part 23 reform:Streamlined certification pathways for non-complex aircraft are reducing time-to-market for amateur-built kit producers targeting US recreational pilots.
Market Restraints
- Prepreg carbon fiber cost volatility:Aerospace-grade resin systems and unidirectional tape pricing fluctuates with energy feedstock costs, squeezing factory-built airframe margins.
- Avionics supplier concentration:Garmin and Dynon dominate EFIS/EMS bundles for aerobatic cockpits, creating single-source dependency for glass-panel retrofits.
- EASA CS-23 structural fatigue mandates:Extended testing cycles for repetitive aerobatic loading now require 50,000+ simulated flight-hour validations, delaying type certification by 18-24 months.
Strategic Opportunities
- Electric propulsion convergence:Battery-electric and hybrid-electric powertrains paired with aerobatic-capable airframes open noise-restricted training corridors near urban centers.
- India's civil aviation expansion:DGCA's liberalized amateur-built aircraft rules and growing flight school density create first-mover advantage for kit manufacturers establishing local assembly partnerships.
- Digital twin integration:Physics-based structural modeling and real-time G-load telemetry enable predictive maintenance contracts and usage-based insurance products.
Industry Challenges
- Composite repair technician scarcity:Certified cold-bond and scarf repair specialists for carbon fiber aerobatic structures remain concentrated in Western Europe and the US Southwest.
- CS-23 fatigue test facility bottlenecks:Only three EASA-recognized laboratories in Europe can execute full-scale wing-spar cyclic loading protocols, creating certification queue congestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerobatic Aircraft Market |
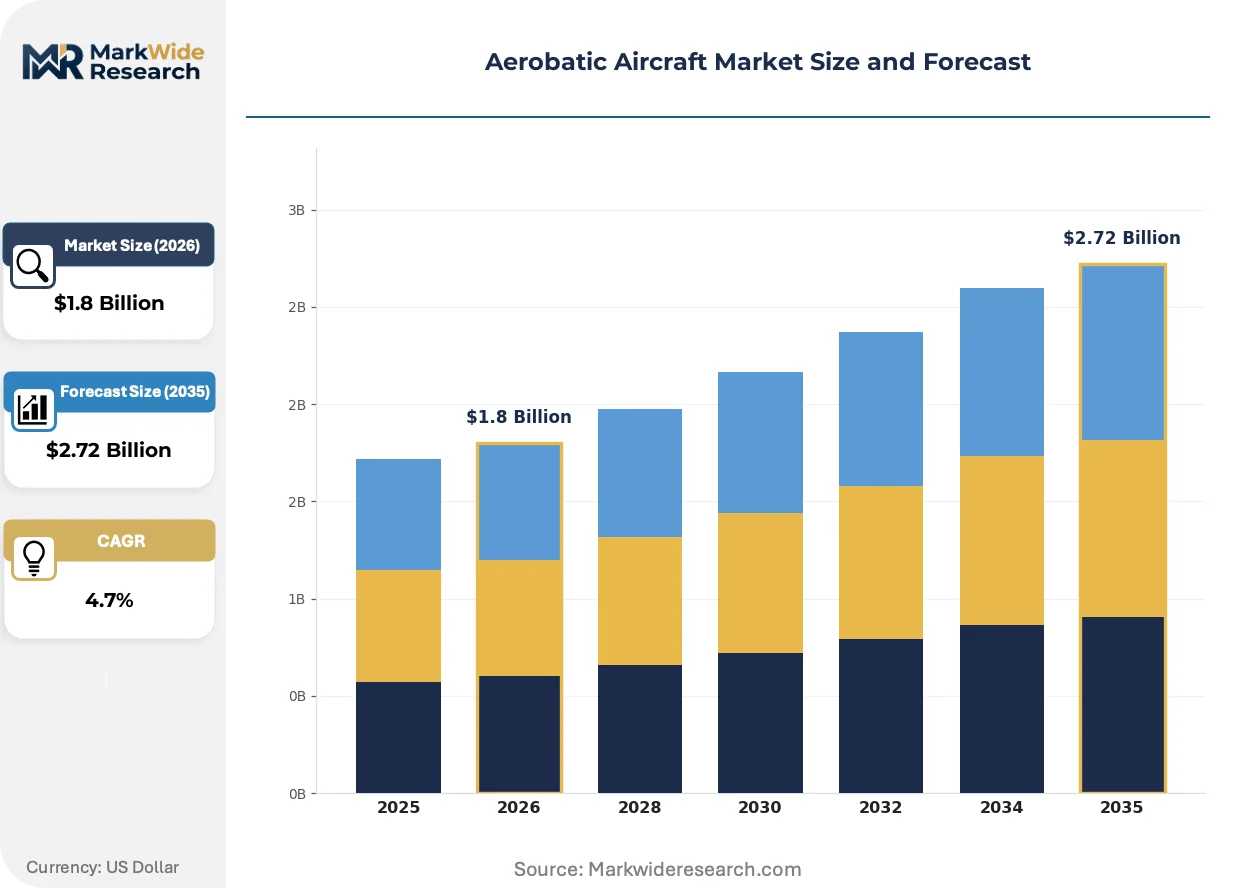
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
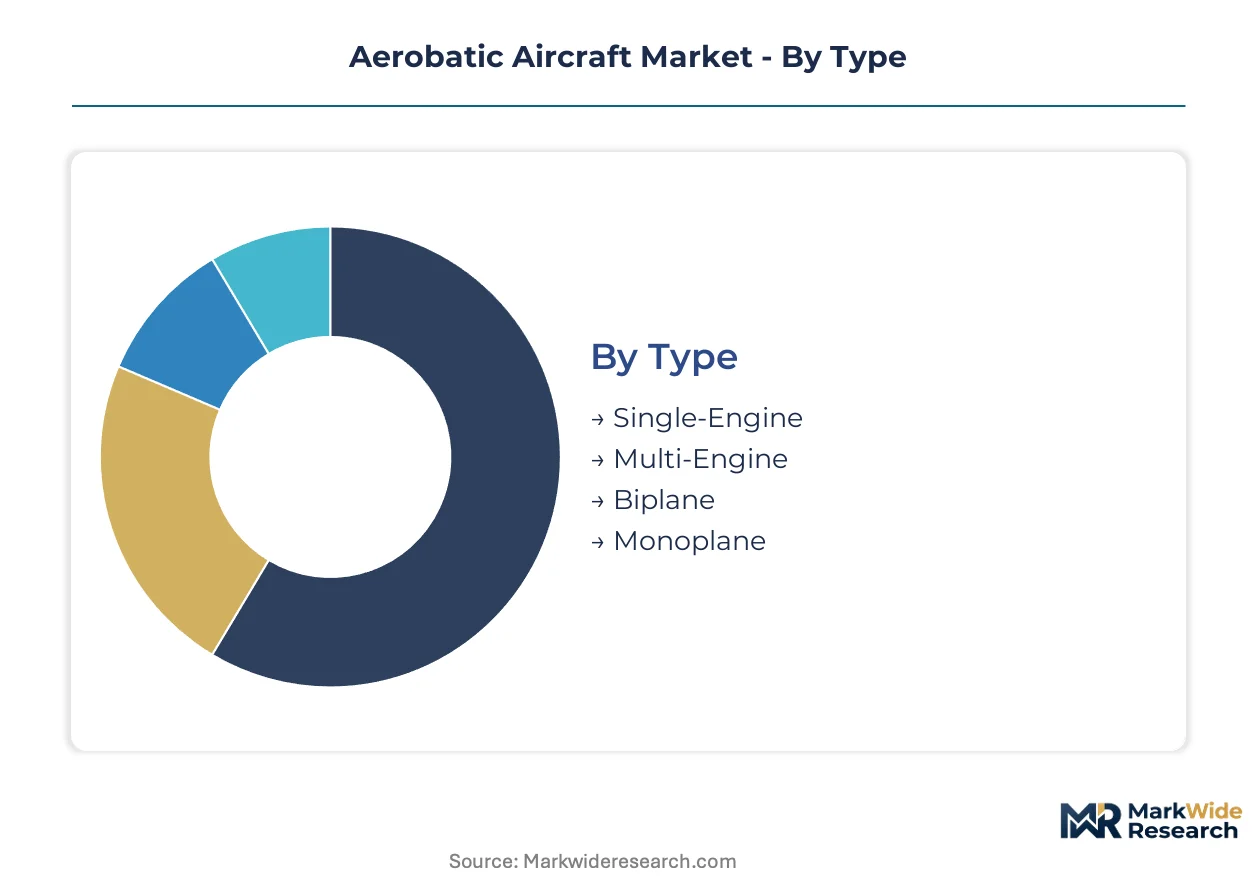
| Segmentation | Type: Single-Engine, Multi-Engine, Biplane, Monoplane Application: Aerobatic Competitions, Air Shows, Training, Leisure Flying Material: Composite, Aluminum, Carbon Fiber, Steel End User: Private Pilots, Flight Schools, Aerobatic Teams, Military |
| Companies Covered | Van’s Aircraft, American Champion Aircraft Corporation, EXTRA Flugzeugproduktions, Aviat Aircraft, Diamond Aircraft Industries, Sukhoi Company, Pacific Aerospace, Waco Aircraft Corporation, Blackwing Sweden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerobatic Aircraft Market Emerging Trajectories
Digital engineering workflows and advanced materials are compressing development cycles while regulatory harmonization efforts create divergent compliance burdens across manufacturing geographies.
Carbon fiber prepreg construction is absorbing investment across factory-built aerobatic portfolios as weight reduction targets intensify. Flight schools and competition operators in Germany and the Czech Republic are specifying full-composite airframes for 40% of new orders. This material transition is absorbing engineering talent from motorsport and wind energy sectors, tightening labor pools for traditional metal-airframe builders.
EASA's Part-CS-23 amendments introduced explicit damage-tolerance requirements for composite primary structures in 2024. Manufacturers must now demonstrate residual strength after prescribed impact events, adding 12-18 months to certification timelines. The amateur-built segment is responding by migrating toward pre-certified kit configurations that limit owner-builder structural modifications.
Flight schools are consolidating fleet procurement under multi-airframe framework agreements rather than single-unit acquisitions. This buyer concentration is squeezing smaller distributors and favoring manufacturers with captive leasing subsidiaries. The shift is most visible in Australia's recreational aviation sector, where four training groups now control 60% of annual aerobatic aircraft intake.
Aerobatic Aircraft Market Segmentation
Segmentation in aerobatic aircraft reveals divergent engineering priorities across customer archetypes. Military trainers demand structural redundancy under repetitive high-G loading, while amateur builders prioritize kit simplicity and parts accessibility. Material selection and propulsion configuration further stratify procurement patterns across geographies and certification pathways.
Type:
Volume concentrates in single-engine configurations, but premium economics favor specialized multi-engine and heritage biplane platforms.
- Single-Engine:Monoplane designs with symmetrical airfoils and inverted fuel systems dominate flight school procurement. Poland's military academies specify these for NATO interoperability training, compressing delivery timelines for certified variants.
- Multi-Engine:Twin-propeller aerobatic platforms carry redundant systems for competition safety mandates. Demand clusters with professional aerobatic teams in Germany and the Czech Republic seeking symmetric thrust recovery capabilities.
- Biplane:Heritage metal-airframe designs sustain niche demand among recreational pilots valuing open-cockpit maneuverability.
- Monoplane:Low-wing cantilever configurations capture composite-intensive factory builds targeting weight-critical performance envelopes.
Today's leader: Single-Engine. Tomorrow's challenger: Multi-Engine.
Application:
Training and leisure absorb unit volume, but competition and air show applications command premium pricing through specialized equipment mandates.
- Training:Flight schools in Hungary and Romania specify high-G tolerance platforms under NATO procurement frameworks. EASA CS-23 fatigue mandates are extending fleet replacement cycles, favoring durable airframe investments.
- Leisure Flying:Affluent private pilots in Germany's Munich-Augsburg corridor pursue type ratings for recreational aerobatic certification. Kit-built configurations reduce regulatory burden for owner-operators.
- Aerobatic Competitions:Precision scoring systems demand telemetry-integrated cockpits with real-time G-load logging.
- Air Shows:Smoke system integration and formation flying protocols require factory-certified modifications beyond amateur-built allowances.
Training and leisure flying anchor current procurement volumes. Competition applications are climbing the fastest as scoring technology standardizes.
Material:
Carbon fiber and composite construction are displacing metal airframes where stiffness-to-weight ratios determine competitive performance.
- Carbon Fiber:Prepreg layup techniques from Germany's motorsport sector enable primary structure weight reduction. EASA damage-tolerance mandates now require residual strength demonstrations after prescribed impact events, extending certification timelines.
- Composite:Glass-reinforced polymer sandwich panels suit secondary structures and control surfaces. Repair technician scarcity in Eastern Europe limits adoption outside Western maintenance networks.
- Aluminum:2024-T3 and 7075-T6 alloys persist in heritage designs and amateur-built kits for field repairability.
- Steel:Chromoly tube fuselages anchor American Champion's metal-aircraft heritage segment for domestic parts availability.
Carbon fiber commands the premium tier. Composite hybrid constructions are gaining share fastest as repair protocols standardize.
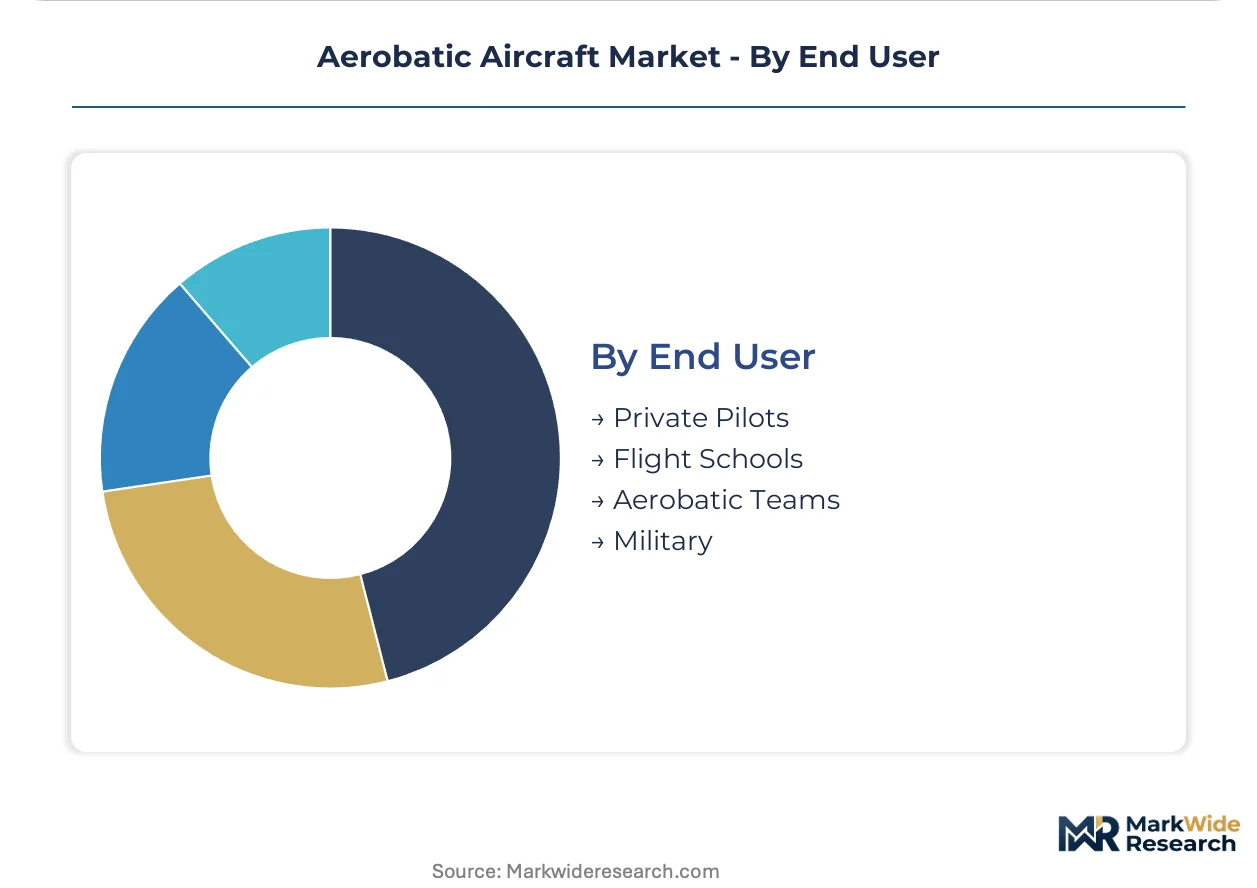
End User:
Flight schools consolidate procurement under framework agreements, while military specifications reshape manufacturer compliance roadmaps.
- Flight Schools:Australia's four dominant training groups now control 60% of annual aerobatic intake through multi-airframe leasing structures. Fleet standardization reduces maintenance inventory complexity.
- Military:Eastern European defense procurement mandates interoperability with existing trainer ecosystems. FAA Part 23 reform streamlines certification for US amateur-built kit producers supplying allied programs.
- Private Pilots:Owner-builder regulations in India under DGCA liberalization create partnership opportunities for kit manufacturers establishing local assembly.
- Aerobatic Teams:Professional formation units specify factory-built platforms with synchronized smoke and lighting systems.
Flight Schools dominate unit economics. Military procurement is expanding most quickly under NATO standardization pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerobatic aircraft manufacturing traces its modern lineage to Germany's interwar sport aviation movement, with the Munich-Augsburg corridor retaining composite fabrication leadership. Contemporary demand distributes across military procurement hubs, recreational aviation clusters, and emerging kit-building markets spanning three continents.
Germany
Flight schools in Bavaria specify carbon fiber aerobatic platforms for 40% of new orders, driven by weight-critical performance requirements. EASA's Part-CS-23 damage-tolerance mandates extend certification timelines for Munich-based manufacturers. The Augsburg-Stuttgart corridor concentrates certified repair stations and prepreg layup specialists migrating from motorsport industries.
United States
Amateur-built kit producers target recreational pilots through streamlined FAA Part 23 reform pathways. The FAA's revised non-complex aircraft certification reduces time-to-market for domestic kit manufacturers. Texas and Arizona host concentrated flight training operations purchasing metal-airframe designs for field repairability in high-utilization environments.
Poland
Military flight academies expand high-G tolerance platform procurement under NATO interoperability frameworks. Poland's national defense procurement regulations mandate trainer ecosystem compatibility with allied systems. The Warsaw-Krakow corridor concentrates maintenance infrastructure for Eastern European military operator networks.
Australia
Four dominant training groups control 60% of annual aerobatic intake through multi-airframe leasing structures. The Civil Aviation Safety Authority's recreational aviation regulations enable consolidated fleet standardization. Queensland and New South Wales host the primary flight school clusters driving framework agreement procurement.
India
DGCA's liberalized amateur-built aircraft rules attract kit manufacturers establishing local assembly partnerships. The Directorate General of Civil Aviation's regulatory relaxation creates first-mover positioning for foreign producers. Maharashtra and Karnataka concentrate emerging flight school density and maintenance infrastructure development.
Aerobatic Aircraft Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification complexity and material sophistication. Factory-built composite platforms command structural price premiums against metal amateur-built alternatives. Three archetypes dominate: European precision manufacturers with EASA-certified factory builds, American kit-based specialists leveraging Part 23 reform, and heritage metal-aircraft builders emphasizing domestic parts networks. Competitive moves concentrate on geographic licensing partnerships and captive leasing subsidiary formation.
Among European precision manufacturers, EXTRA Flugzeugproduktions and Diamond Aircraft Industries exemplify the EASA-certified factory-build archetype through controlled distribution architectures. Van's Aircraft occupies a central position within the American kit-specialist tier, leveraging owner-builder regulatory pathways. American Champion Aircraft Corporation anchors the heritage metal-aircraft segment, representing domestic parts-availability positioning against composite-intensive alternatives.
| Leading Market Players |
|---|
| Van's Aircraft |
| American Champion Aircraft Corporation |
| EXTRA Flugzeugproduktions |
| Aviat Aircraft |
| Diamond Aircraft Industries |
| Sukhoi Company |
| Pacific Aerospace |
| Waco Aircraft Corporation |
| Blackwing Sweden |
| Others |
Supply Flow & Price Mechanics
Prepreg carbon fiber resin systems flow from Germany's Munich-Augsburg corridor through three distinct pricing tiers before reaching end-users. EASA's Part-CS-23 certification complexity splits factory-built platforms from amateur-built kits, with fatigue-testing validation costs embedding directly into premium airframe pricing. Flight schools in Eastern Europe and Australia absorb these premiums through multi-airframe leasing structures that compress per-unit acquisition economics.
Pricing Analysis
Three-tier pricing structure across premium factory-built, certified kit, and amateur-built economy levels governs procurement decisions. Price differentiation centers on EASA CS-23 certification grade and composite primary structure damage-tolerance validation. Cost compression in the economy tier intensifies because Garmin and Dynon avionics bundles command fixed pricing regardless of airframe source. Flight schools exhibit highest price sensitivity through framework agreement consolidation, while military procurement in Poland and Romania shows lowest sensitivity under NATO interoperability mandates.
Supply Chain Analysis
Dual-sourcing requirements for aerospace-grade carbon fiber now mandate qualified suppliers in Germany, Japan, and the United States for major airframe builders. Raw material dependencies center on epoxy resin systems, unidirectional prepreg tape, and certified chromoly steel tubing for heritage designs. Single-source vulnerability concentrates in EASA-recognized fatigue test facilities, where only three European laboratories execute full-scale wing-spar cyclic loading protocols. Distribution runs through controlled manufacturer-direct channels for factory builds and regional distributor networks for kit components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value as EASA's 2024 Part-CS-23 damage-tolerance mandates for composite structures extend certification timelines and deepen compliance moats around established players.
For Market Incumbents: Acquire certified repair station networks in Eastern Europe to preempt composite technician scarcity bottlenecks. Deepen backward integration into prepreg carbon fiber layup capacity within Germany's Munich-Augsburg corridor to defend margins against resin cost volatility. Battery-electric propulsion entrants threaten traditional engine supplier relationships; secure exclusive powertrain development partnerships with emerging electric aviation specialists before certification pathways stabilize. For New Entrants and Emerging Players: Capture India's DGCA-liberalized amateur-built segment through local assembly partnerships in Maharashtra and Karnataka before foreign kit manufacturers establish distribution. White-space concentration appears in electric propulsion integration for noise-restricted urban training corridors, where battery-electric aerobatic platforms face zero incumbent competition. Position through flight school direct procurement channels rather than retail distributor networks to bypass established kit-builder relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where EASA CS-23 fatigue test facility bottlenecks strand smaller airframe builders without certification queue access. Long-term viability favors vertically integrated manufacturers with captive composite fabrication and certified repair capabilities. Acquisition target archetype: German or Czech factory-built specialists with existing EASA type certificates and established military procurement relationships. Watch EASA's recognition of additional fatigue test laboratories as the critical inflection signal for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Repair Station Network Expansion | Addresses certified technician scarcity in Eastern European military procurement corridors. |
| Electric Propulsion Certification Pathway | Opens noise-restricted urban training corridors near German and Australian flight school clusters. |
| Local Assembly Partnership in India | Captures DGCA-liberalized amateur-built demand before foreign kit manufacturers establish presence. |
| Multi-Airframe Leasing Subsidiary Formation | Mirrors Australian training group consolidation patterns to secure flight school framework agreements. |
| EASA Fatigue Test Facility Investment | Resolves certification queue congestion that currently delays type approval by 18-24 months. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct this analysis. Primary fieldwork engaged airframe manufacturer engineering directors, EASA certification specialists, flight school fleet managers, military procurement officers in Poland and Romania, and composite repair station technicians. Secondary validation drew from FAA Part 23 reform documentation, EASA CS-23 amendment filings, DGCA amateur-built aircraft circulars, and Australian Civil Aviation Safety Authority recreational aviation regulations. Bottom-up airframe delivery tracking and top-down military procurement budget analysis were cross-referenced for triangulation.
Segment-weighting approaches distributed value and volume across single-engine and multi-engine configurations, training versus competition applications, carbon fiber and metal material categories, and flight school versus military end-user segments. CAGRs were derived from regression analysis of historical delivery patterns against projected procurement timelines, incorporating NATO interoperability training mandates and DGCA regulatory liberalization as demand accelerants. Electric propulsion adoption curves and composite damage-tolerance certification timeline extensions served as industry-specific forecast modifiers.
EASA regulatory amendments, prepreg carbon fiber feedstock cost volatility, and electric aviation battery certification delays are the dominant revision risks embedded in this outlook. Deviation in EASA's recognition timeline for additional fatigue test facilities would shift the competitive entry dynamics and certification queue economics materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
India Winglets Market
Aircraft
Aircraft Oxygen System Market
Aircraft
Aircraft Ailerons Market
Aircraft
Aircraft Control Surface Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Airplane Brackets Market
Aircraft
Regional Jet Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
GCC General Aviation Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Airship Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Asia-Pacific Fighter Aircraft Market