
 Aeronautic Propeller Market | 2026-2036
Aeronautic Propeller Market Size, Share, and Industry Trends Forecast 2026-2036
Aeronautic Propeller Market Analysis
Multi-source procurement for composite blade assemblies is realigning how tier-one suppliers manage risk across their vendor networks. Hartzell Propeller Inc. leverages in-house forging capabilities to control aluminum alloy supply quality from ingot to finished hub. MT-Propeller Entwicklung GmbH anchors its position through German-engineered natural composite laminates that reduce vibration fatigue in high-cycle operations. Dowty Propellers competes on scale, operating one of Europe's largest integrated propeller test facilities for military and commercial validation programs.
An aeronautic propeller is a rotating airfoil assembly that converts engine torque into aerodynamic thrust, typically manufactured from aluminum alloys, woven carbon fiber prepregs, or hybrid composite stacks with specified pitch angles ranging from fixed settings to hydraulically actuated variable geometry. Its primary purpose is to optimize propulsive efficiency across diverse flight regimes from low-speed general aviation climb profiles to high-altitude turboprop cruise segments. Constant speed propeller systems command the widest installed base among product types, reflecting their fuel efficiency advantages in commercial aviation routes with frequent altitude changes. Carbon fiber material adoption is outpacing aluminum in new platform designs, driven by weight reduction targets and extended inspection intervals that shift lifetime value calculations toward composite stacks despite higher initial procurement costs.
FAA Part 35 airworthiness standards and EASA CS-P certification frameworks govern blade retention, fatigue life, and ice protection system performance, creating compliance barriers that favor established manufacturers with sustained type certificate holdings. EPA and ICAO noise chapter limits are forcing acoustic redesigns, pushing OEMs toward swept-tip geometries and reduced tip speed architectures that alter tooling investments and aftermarket spare part economics. Stakeholders must monitor how emerging electric propulsion architectures with distributed motor-propeller units reshape certification pathways and supplier qualification timelines for conventional turboprop incumbents.
Market Dynamics
Composite blade architectures are compressing inspection intervals and reshaping aftermarket economics for turboprop operators. FAA Part 35 and EASA CS-P fatigue standards now favor manufacturers with captive material science capabilities.
Growth Catalysts
- EASA CS-P Certification Alignment:Harmonized blade retention standards across European Union member states reduce duplicate testing costs for multi-national fleet operators.
- Regional Route Expansion:Civil aviation operators in the United States, Germany, and China are adding turboprop capacity to serve thin-density corridors where jet economics fail.
- Carbon Fiber Prepreg Stacks:Woven composite laminates with extended fatigue life are displacing aluminum in new platform designs, shifting lifetime value calculations toward higher initial procurement thresholds.
Market Restraints
- Aluminum Alloy Volatility:Aerospace-grade 7075-T6 and 2024-T3 ingot prices fluctuate with energy costs, squeezing margin on legacy hub forgings.
- Test Facility Concentration:Europe hosts only three integrated propeller validation centers capable of military certification cycles, creating queue bottlenecks for new entrants.
- Tip Speed Physics:Acoustic redesigns for ICAO Chapter 14 noise limits impose hard aerodynamic ceilings on conventional blade architectures.
Strategic Opportunities
- Urban Air Mobility Integration:Distributed electric propulsion architectures with motor-propeller units require entirely new certification pathways that favor agile suppliers over incumbents.
- Aftermarket Service Unbundling:Independent MRO networks in the United States are capturing blade overhaul volumes previously captive to OEM channels.
- China General Aviation Clusters:Provincial manufacturing zones in Shaanxi and Sichuan provinces offer co-location incentives for propeller assembly operations serving domestic light aircraft demand.
Industry Challenges
- Composite Repair Technician Scarcity:Natural laminate and carbon fiber damage assessment requires specialized NDT certification that outpaces vocational training pipeline output.
- Dual Certification Timelines:Simultaneous FAA Part 35 and EASA CS-P approval processes extend time-to-revenue for new blade designs by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aeronautic Propeller Market |
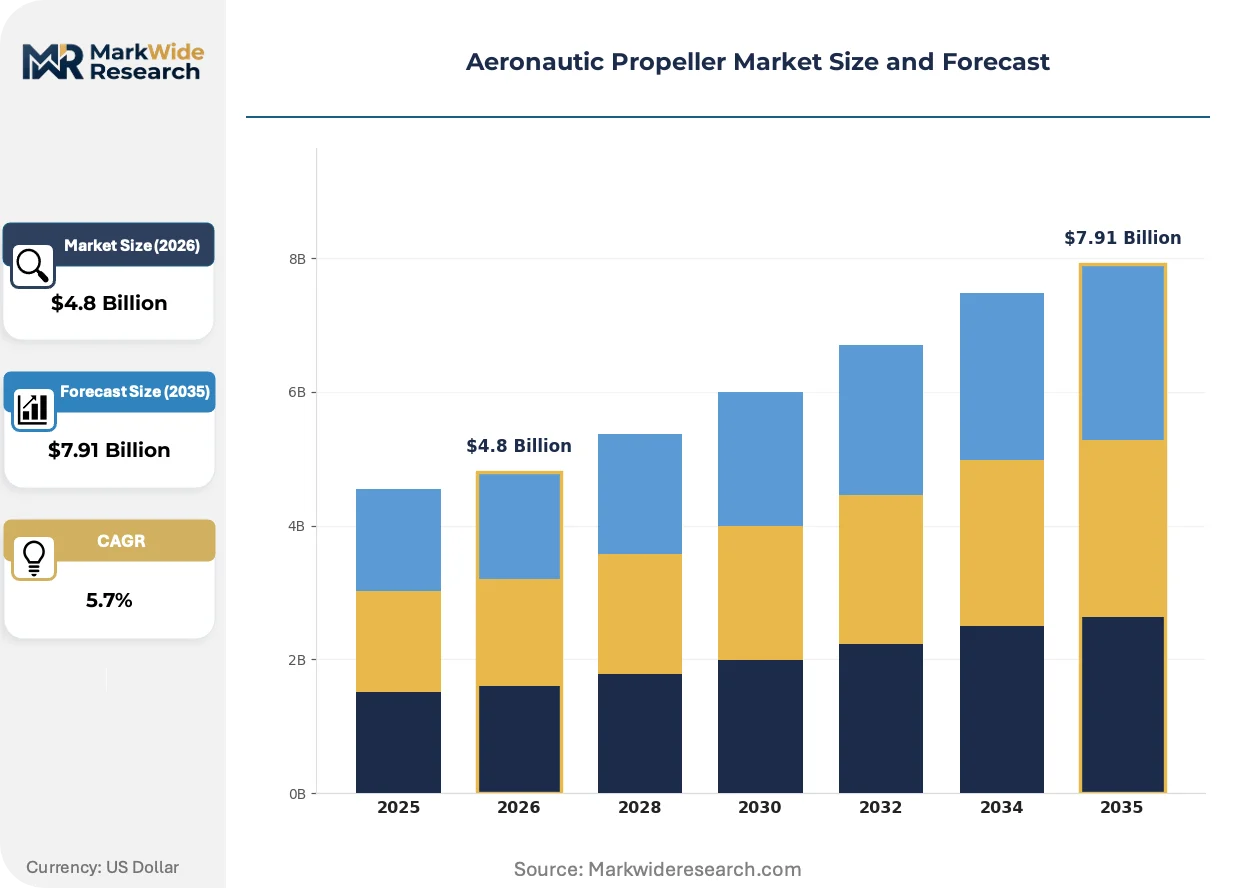
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Pitch, Variable Pitch, Controllable Pitch, Constant Speed End User: Civil Aviation, Military Aviation, Drone Manufacturing, Aerospace Research Material: Aluminum, Composite, Steel, Carbon Fiber Application: General Aviation, Commercial Aviation, Military Operations, Racing |
| Companies Covered | Hartzell Propeller Inc., MT-Propeller Entwicklung GmbH, McCauley Propeller Systems, Dowty Propellers, Collins Aerospace, Sensenich Propeller Manufacturing Co., Hoffmann Propeller GmbH & Co. KG, Hercules Propellers Ltd., UTC Aerospace Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aeronautic Propeller Market Emerging Trajectories
Swept-tip geometries and variable-pitch hydraulics are converging with electric propulsion research to redefine propulsive efficiency benchmarks. Material science advances and regulatory pressure are accelerating platform redesign cycles.
Modular blade architectures with field-replaceable leading edge segments are modularizing maintenance economics for high-cycle regional operators. Turboprop fleets in the United States and Germany are adopting these systems to compress ground time between revenue flights. The technology is modularizing the traditional OEM-aftermarket relationship by enabling component-level sourcing from non-original suppliers.
EPA noise emission thresholds and ICAO Chapter 14 acoustic limits are forcing reduced tip speed designs that alter forging investments and spare part forecasting. Manufacturers must retool swept-tip production lines to meet decibel targets at approach configurations. Military procurement programs in the United States face the steepest compliance curves due to legacy fleet replacement timelines.
Operator purchasing committees now unbundle propeller overhaul from airframe maintenance contracts, driving direct negotiations with specialized composite repair shops. This pattern disrupts traditional OEM service bundling in European and North American markets. Regional carriers with turboprop-heavy fleets are leading the unbundling shift to capture labor rate arbitrage between in-house and third-party technical stations.
Aeronautic Propeller Market Segmentation
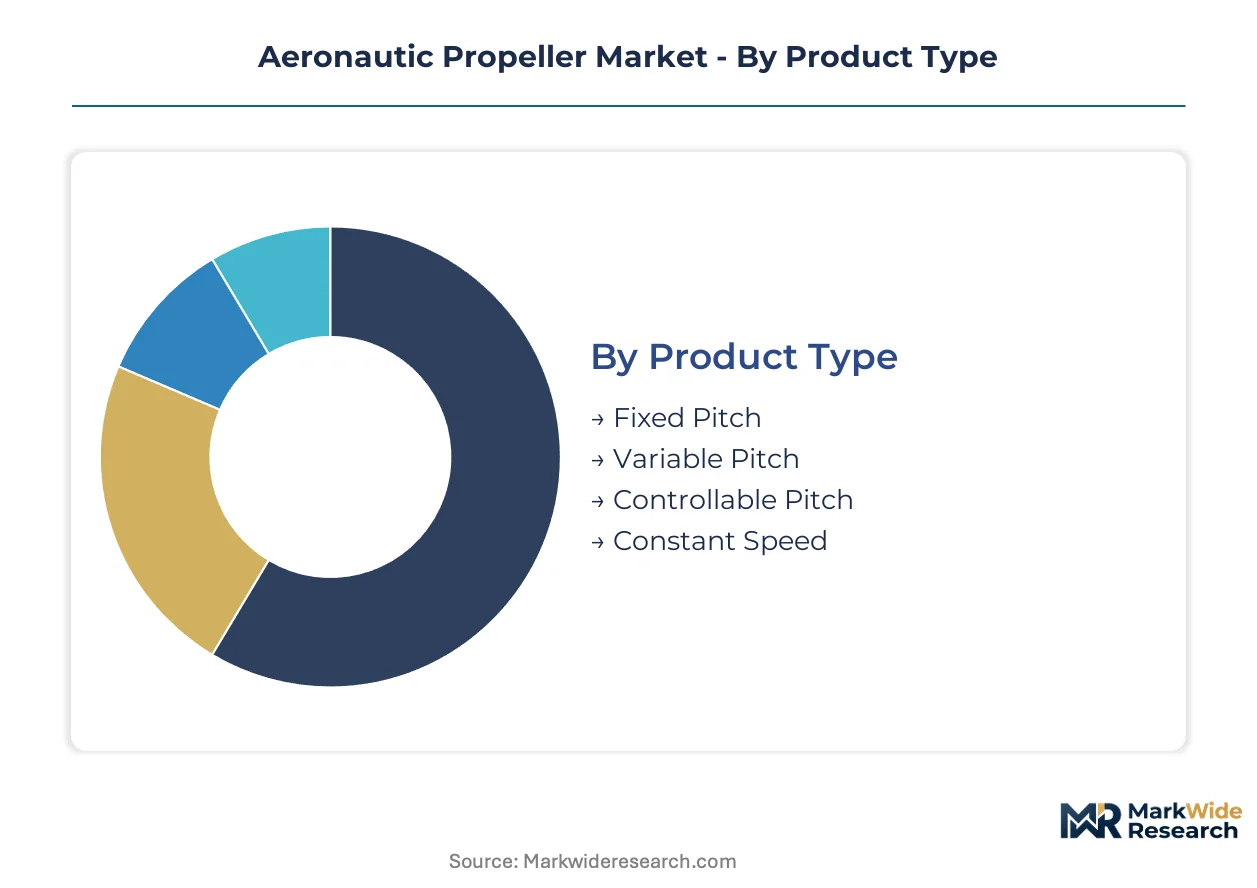
Propeller segmentation reveals how certification pathways, material science investments, and fleet replacement cycles concentrate demand across distinct technical tiers. Understanding these divisions exposes where FAA Part 35 and EASA CS-P compliance costs create barriers or competitive openings for suppliers.
Product Type:
FAA Part 35 fatigue standards and EASA CS-P blade retention requirements apply differentially across pitch control architectures, with constant speed systems facing the most intensive validation protocols.
- Constant Speed:Hydraulically actuated hub mechanisms maintain optimal blade angle across varying flight regimes, reducing fuel burn on climb and descent profiles. United States regional carriers operating thin-density routes favor these systems for their efficiency dividends on multi-segment days. EASA CS-P certification timelines for new constant speed designs stretch 24-36 months due to complex governor integration testing.
- Variable Pitch:Pilot-selectable blade angles enable manual optimization for takeoff, cruise, and reverse thrust operations without full automation. Military aviation procurement programs in Germany specify these systems for transport aircraft requiring unimproved field performance. The segment carries moderate certification burden relative to constant speed, attracting mid-tier suppliers seeking market entry.
- Controllable Pitch:Ground-adjustable or limited in-flight pitch range systems serve cost-sensitive general aviation platforms. Aluminum hub forgings dominate this segment's bill of materials.
- Fixed Pitch:Single-angle designs anchor the light sport and ultralight categories with minimal moving parts and inspection intervals measured in years rather than flight hours.
Constant Speed sits at the top of the volume ranking, with Variable Pitch climbing the fastest as military operators modernize tactical transport fleets.
End User:
Procurement patterns diverge sharply between commercial operators optimizing lifetime cost per flight hour and military buyers prioritizing field reliability under adverse conditions.
- Civil Aviation:Regional turboprop operators in the United States drive replacement demand as aging fleets approach structural life limits. These customers unbundle propeller overhaul from airframe contracts, negotiating directly with specialized MRO networks for blade refurbishment.
- Military Aviation:Defense procurement programs impose MIL-STD-810 environmental testing and extended fatigue certification beyond commercial requirements. German Air Force transport modernization and United States Navy maritime patrol replacements anchor this segment's project pipeline.
- Drone Manufacturing:Distributed electric propulsion architectures for urban air mobility platforms require entirely new blade geometries optimized for low Reynolds number flow regimes.
- Aerospace Research:NASA and university wind tunnel programs purchase specialized propeller assemblies for boundary layer and acoustic studies, representing low volume but high margin custom fabrication.
Civil Aviation commands the largest installed base, though Drone Manufacturing is expanding most quickly as electric vertical takeoff platforms advance toward type certification.
Material:
Material selection directly determines inspection interval economics, with composite stacks shifting lifetime value calculations despite premium initial procurement thresholds.
- Carbon Fiber:Woven prepreg laminates with tailored fiber orientations deliver weight reductions and extended fatigue life for high-cycle regional operations. China general aviation manufacturing clusters in Shaanxi province are adopting carbon fiber blades for domestic light aircraft production.
- Composite:Natural fiber and hybrid matrices from MT-Propeller's German engineering reduce vibration transmission in turboprop applications. These materials face longer EASA CS-P certification timelines due to limited historical service data relative to metallic alternatives.
- Aluminum:Aerospace-grade 7075-T6 forgings remain standard for legacy hub assemblies, though ingot price volatility squeezes margin on replacement part production.
- Steel:High-strength alloys anchor military propeller hubs requiring damage tolerance and ballistic resistance specifications.
Aluminum retains the widest installed footprint, while Carbon Fiber gains share fastest as new platform designs prioritize weight reduction targets.
Application:
Flight regime characteristics dictate blade loading spectra, with commercial operations imposing the most severe high-cycle fatigue demands on material selection.
- Commercial Aviation:Regional turboprop fleets accumulate 2,000-3,000 annual cycles, driving demand for composite blades with 12,000-hour inspection intervals. United States operators leading the unbundling of propeller maintenance from airframe contracts favor these extended-interval systems.
- General Aviation:Owner-flown piston singles and twins operate at lower utilization, tolerating aluminum blades with more frequent but less costly overhaul requirements.
- Military Operations:Tactical profiles including low-level ingress and unimproved field operations impose foreign object damage and vibration loads beyond commercial experience.
- Racing:Unlimited class air racing demands custom carbon fiber blades optimized for maximum power absorption at sustained high rpm, representing negligible volume but maximum performance engineering intensity.
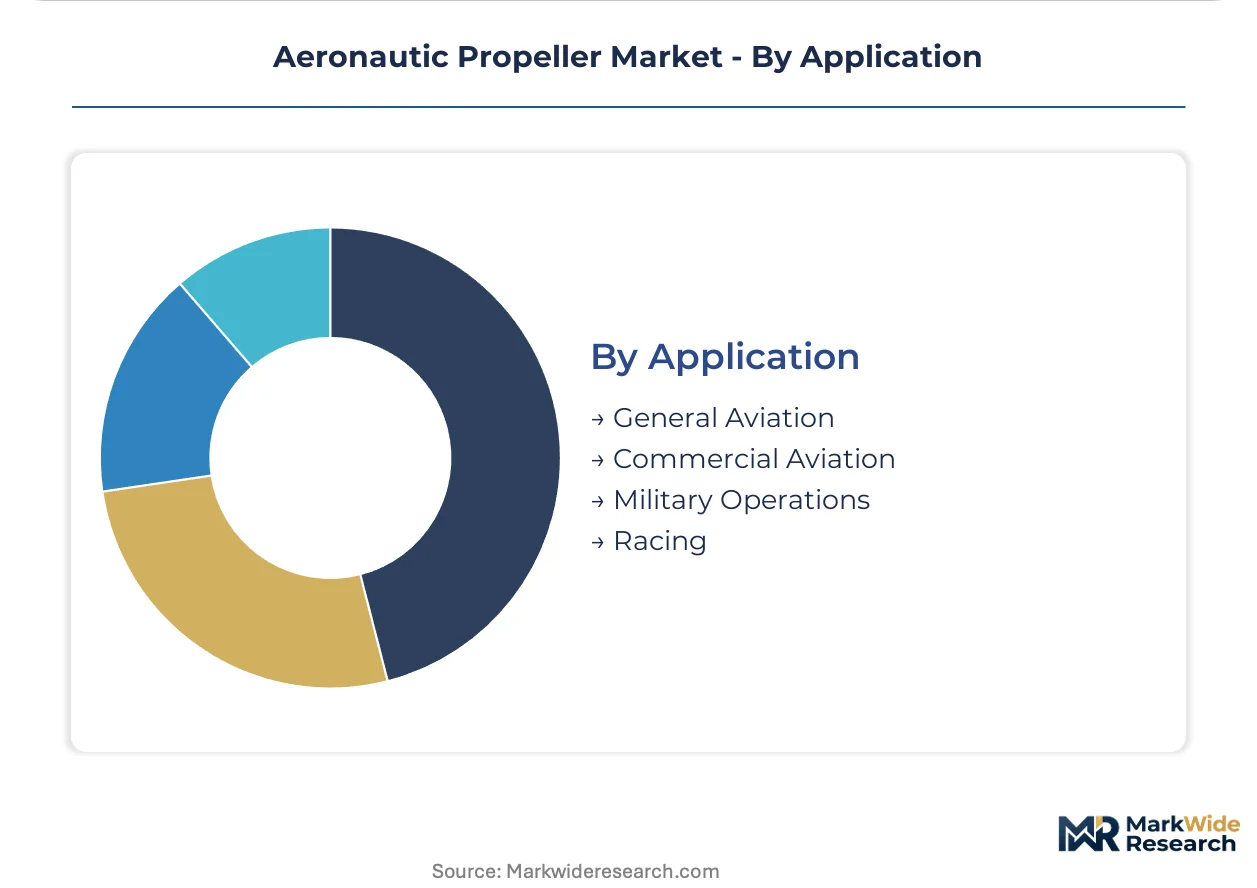
Commercial Aviation dominates revenue concentration, with Military Operations showing the steepest expansion trajectory as legacy fleet replacement programs accelerate in Germany and the United States.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita, Kansas anchors the United States general aviation manufacturing corridor where propeller OEMs cluster near airframe integrators. FAA Part 35 certification timelines and military procurement cycles shape competitive positioning across three continents.
United States
Regional turboprop operators at Dallas-Fort Worth and Chicago O'Hare hubs drive replacement demand for constant-speed propeller systems. FAA Part 35 airworthiness standards govern blade retention testing protocols that extend certification cycles for new designs. Wichita and Vero Beach manufacturing zones concentrate forging and composite layup operations serving domestic light aircraft and military maritime patrol programs.
Germany
Natural composite laminate technology from Bavarian engineering centers reduces vibration fatigue in high-cycle turboprop operations. EASA CS-P certification frameworks apply harmonized blade retention standards across EU member states, reducing duplicate testing costs. Augsburg and Straubing industrial corridors host integrated propeller test facilities serving German Air Force transport modernization contracts.
China
Provincial manufacturing incentives in Shaanxi and Sichuan provinces attract propeller assembly operations targeting domestic general aviation expansion. The country's national aviation regulator enforces airworthiness standards aligned with ICAO noise chapter limits. Xi'an and Chengdu aerospace clusters develop carbon fiber blade capabilities for light aircraft programs serving regional route networks.
United Kingdom
Specialist repair stations at Gloucestershire and Oxfordshire airfields capture blade overhaul volumes from unbundled maintenance contracts. The Civil Aviation Authority implements EASA-aligned certification requirements for composite damage assessment protocols. Southwest England manufacturing zones sustain legacy aluminum hub forging for owner-flown piston aircraft.
France
Aerospace research institutions at Toulouse and Paris-Saclay advance swept-tip acoustic geometries for ICAO Chapter 14 compliance. The national civil aviation authority enforces noise emission thresholds that reshape forging investments and spare part forecasting. Occitanie region engineering centers collaborate with turboprop OEMs on reduced tip speed architectures.
Aeronautic Propeller Market Vendor Landscape
Global majors compete with regional champions across certification-holding capacity and material science specialization. The vendor base stratifies into three tiers: established type certificate holders with captive forging operations, composite specialists leveraging natural laminate expertise, and emerging entrants targeting electric propulsion architectures. Strategic moves concentrate on backward integration into aluminum alloy supply chains and geographic expansion into Chinese provincial manufacturing zones.
Within the established certificate-holder tier, Hartzell Propeller Inc. and MT-Propeller Entwicklung GmbH occupy positions defined by in-house material capabilities. Dowty Propellers exemplifies scale-driven validation infrastructure. These three anchors represent distinct competitive vectors: North American forging integration, German-engineered natural composites, and European test facility concentration.
| Leading Market Players |
|---|
| Hartzell Propeller Inc. |
| MT-Propeller Entwicklung GmbH |
| McCauley Propeller Systems |
| Dowty Propellers |
| Collins Aerospace |
| Sensenich Propeller Manufacturing Co. |
| Hoffmann Propeller GmbH & Co. KG |
| Hercules Propellers Ltd. |
| UTC Aerospace Systems |
| Others |
Supply Flow & Price Mechanics
Captive forging operations at Hartzell Propeller Inc. anchor both supply security and pricing power for aluminum alloy hub assemblies, insulating tier-one manufacturers from aerospace-grade ingot volatility while compressing procurement premiums for regional operators.
Pricing Analysis
Aluminum alloy ingot costs pass through directly to hub forging quotations, with 7075-T6 and 2024-T3 price swings compressing margins on legacy replacement parts. Three-tier pricing structure across premium carbon fiber, standard composite, and economy aluminum tiers reflects certification grade and inspection interval differentiation. Pricing pressure stems from unbundled MRO contracts that expose OEM service bundles to independent blade overhaul shops. Regional turboprop operators exhibit highest price sensitivity, while military procurement programs absorb premium tiers for damage-tolerant specifications.
Supply Chain Analysis
FAA Part 35 and EASA CS-P qualification gates restrict blade material sourcing to certified prepregs and forgings, limiting supplier pools for composite laminates and aluminum alloys. Supply concentrates in the United States, Germany, and China, with Wichita forging clusters, Bavarian natural composite engineering, and Shaanxi carbon fiber layup operations anchoring production. Raw material dependencies span aerospace-grade aluminum ingots, woven carbon fiber prepregs, and hydraulic governor systems. Single-source vulnerability concentrates in European test facilities, where only three integrated validation centers queue military certification cycles. Distribution runs through OEM-direct channels for new platforms and unbundled MRO networks for aftermarket blade overhaul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite blade architectures are compressing inspection intervals and shifting lifetime value calculations toward premium procurement tiers, creating margin expansion for suppliers with captive material science capabilities.
For Market Incumbents: Deepen backward integration into aluminum alloy supply chains to insulate hub forging margins from energy-cost volatility. Expand carbon fiber prepreg qualification pipelines to capture replacement demand from regional turboprop operators unbundling maintenance contracts. Lock in EASA CS-P certification timelines ahead of German Air Force transport modernization awards.
For New Entrants and Emerging Players: Begin with urban air mobility electric propulsion architectures, where distributed motor-propeller units require entirely new certification pathways that favor agile suppliers over established type certificate holders. Target drone manufacturing segments with low Reynolds number blade geometries absent legacy turboprop competition. Pursue direct procurement relationships with Chinese general aviation clusters in Shaanxi and Sichuan provinces bypassing incumbent OEM channels.
For Investors and Strategic Acquirers: Roll-up economics work for composite repair specialists because EASA CS-P and FAA Part 35 certification scarcity constrains technician pipeline output. Five-to-ten-year viability hinges on carbon fiber adoption curves in regional turboprop replacement cycles. Watch for inflection when ICAO Chapter 14 noise limits force acoustic redesigns that retool swept-tip production lines and displace legacy blade inventories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Forging | Hartzell's in-house 7075-T6 hub production controls supply quality from ingot to finished assembly. |
| Natural Composite Laminate Certification | MT-Propeller's German-engineered materials reduce vibration fatigue in high-cycle turboprop operations. |
| Electric Propulsion Architecture Development | Distributed motor-propeller units for urban air mobility require new FAA certification pathways. |
| Unbundled MRO Network Expansion | Independent blade overhaul shops capture volumes from regional operators separating propeller and airframe contracts. |
| China Provincial Manufacturing Co-location | Shaanxi and Sichuan incentives attract assembly operations serving domestic light aircraft demand. |
Methodological Framework
Multiple input streams — primary interviews with propeller OEM engineering directors, regional airline procurement officers, and military aviation program managers; secondary validation through FAA type certificate databases, EASA CS-P certification registries, and aerospace trade customs data; plus proprietary production volume estimates — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the analysis window applied segment-level modeling for constant speed, variable pitch, controllable pitch, and fixed pitch architectures, cross-referenced with carbon fiber, composite, aluminum, and steel material tiers. CAGRs were derived from installed base replacement cycles, fleet expansion patterns in thin-density regional routes, and military procurement pipelines. Forecast inputs included ICAO noise chapter compliance timelines and electric propulsion certification pathway developments.
Several conditions sit outside the modeled scope, including unannounced military platform cancellations, abrupt aluminum alloy tariff regimes, and breakthrough solid-state propulsion technologies. Deviation in FAA or EASA certification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Fighter Aircraft Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
Aerobatic Aircraft Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Global Ultralight and Light Aircraft Market
Aircraft
US Military Aviation Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Aircraft Seals Market
Aircraft
Air Speed Indicator Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Latin America General Aviation Market