
 Middle-East and Africa Turboprop Aircraft Market | 2026-2036
Middle-East and Africa Turboprop Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Turboprop Aircraft Market Foresight
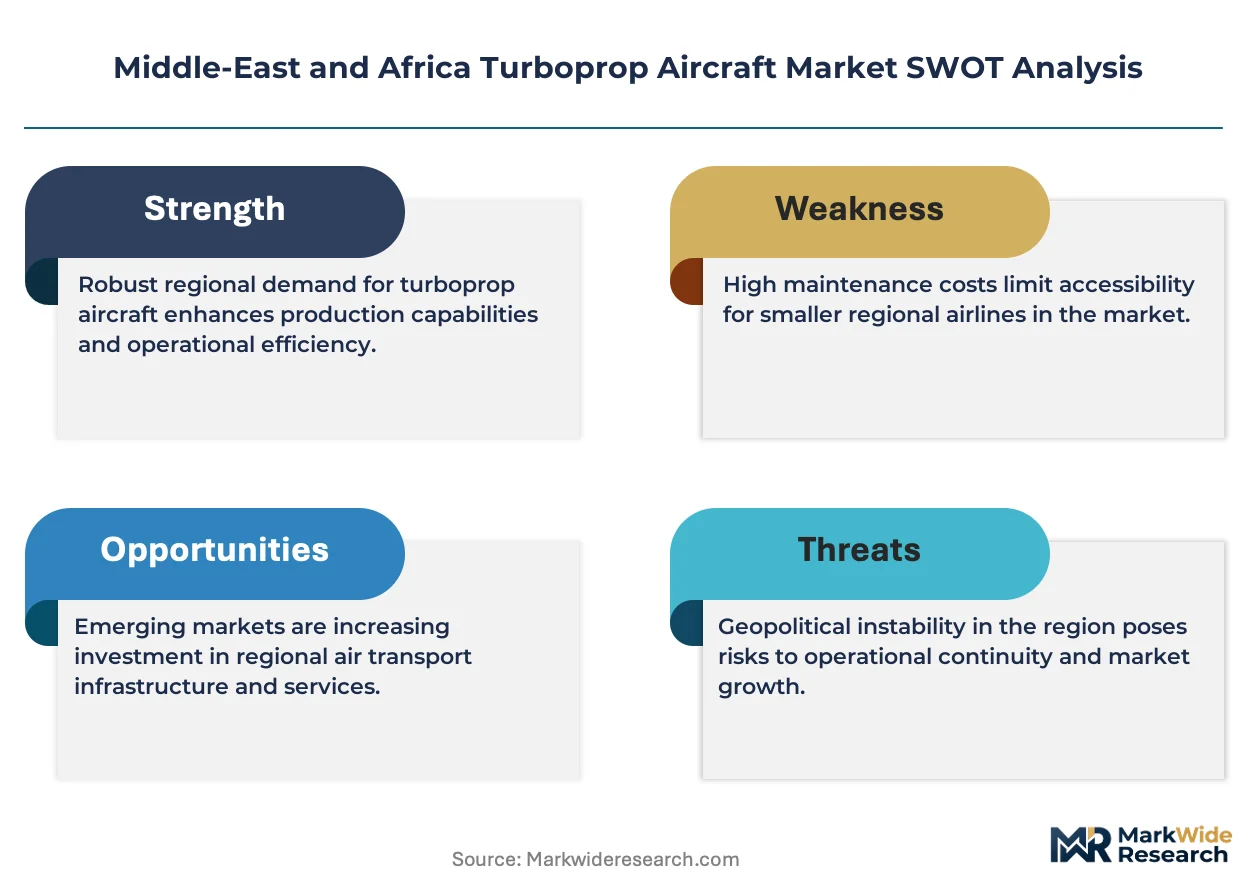
EASA CS-25 type certification is bifurcating the competitive landscape between legacy OEMs and emerging challengers in the Middle-East and Africa turboprop space. ATR leverages its established regional aircraft portfolio to sustain dominance on North African routes. Textron Inc. competes through its King Air franchise, which anchors private and government operator segments across Gulf Cooperation Council states. Pilatus Aircraft Ltd specializes in single-engine turboprops, differentiating its PC-12 platform for humanitarian and surveillance missions in remote African territories.
Turboprop aircraft utilize gas turbine engines driving propellers through reduction gearboxes, typically operating at cruise altitudes below 25,000 feet with fuel burn rates 20-30% below comparable regional jets. These characteristics suit short-haul routes, unimproved airstrips, and hot-and-high conditions prevalent across the Middle-East and Africa. Regional aircraft generate the dominant revenue pool given fleet renewal cycles at carriers such as Ethiopian Airlines and Royal Air Maroc, while cargo aircraft represent the fastest-expanding segment driven by e-commerce logistics into secondary African cities. Military aircraft applications concentrate in North Africa and the Sahel, where governments prioritize intelligence, surveillance, and reconnaissance platforms.
South Africa's Civil Aviation Authority enforces ICAO-aligned airworthiness directives that shape import eligibility for pre-owned turboprop fleets. The UAE's General Civil Aviation Authority coordinates with EASA on mutual recognition agreements, streamlining access for European-certified platforms. Saudi Arabia's General Authority of Civil Aviation implements GACA Part 121 operational rules that govern turboprop deployment in commercial service. Stakeholders must monitor how carbon offset mandates from the International Civil Aviation Organization reshape engine upgrade timelines and retrofit economics across operator fleets.
Market Dynamics
ICAO Chapter 14 noise compliance deadlines are forcing fleet renewal decisions across Middle-East and Africa operators, compressing residual values of older turboprop platforms while accelerating OEM upgrade program uptake.
Growth Catalysts
- Ethiopian Airlines fleet expansion:The carrier's regional connectivity mandate drives turboprop orders for short-haul routes into secondary East African cities with unimproved airstrips.
- Saudi GACA Part 121 operational rules:These regulations standardize commercial turboprop deployment, reducing regulatory friction for new market entrants in the Kingdom's domestic aviation sector.
- Hot-and-high performance envelope:Turboprop propulsion systems maintain thrust efficiency at elevated African airfields where jet engines suffer derating penalties.
Market Restraints
- PT6A engine overhaul cost volatility:Pratt & Whitney Canada's aftermarket pricing unpredictability squeezes operating margins for regional carriers dependent on mature turboprop fleets.
- European EASA CS-25 certification concentration:Type approval authority centralization in Toulouse and Cologne creates bottlenecks for emerging OEMs seeking market access.
- Regional jet substitution threat:Embraer E-Jet family encroachment on 500-800nm sectors erodes turboprop addressable market on paved runway routes.
Strategic Opportunities
- Nigerian domestic aviation liberalization:Air Operator Certificate issuance reforms under the Nigerian Civil Aviation Authority open fleet expansion pathways for indigenous carriers.
- Humanitarian logistics convergence:United Nations World Food Programme tender requirements favor STOL-capable platforms for Sahel relief operations.
- Surveillance payload integration:Electro-optical and signals intelligence sensor fusion creates new mission profiles for single-engine turboprops in maritime patrol roles.
Industry Challenges
- Type-rated flight crew scarcity:African aviation training organizations lack simulator capacity for ATR 72-600 and Dash 8 Q400 transition programs.
- Extended EASA validation timelines:Supplemental Type Certificate approval delays for avionics retrofits strand upgrade revenue for MRO providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Turboprop Aircraft Market |
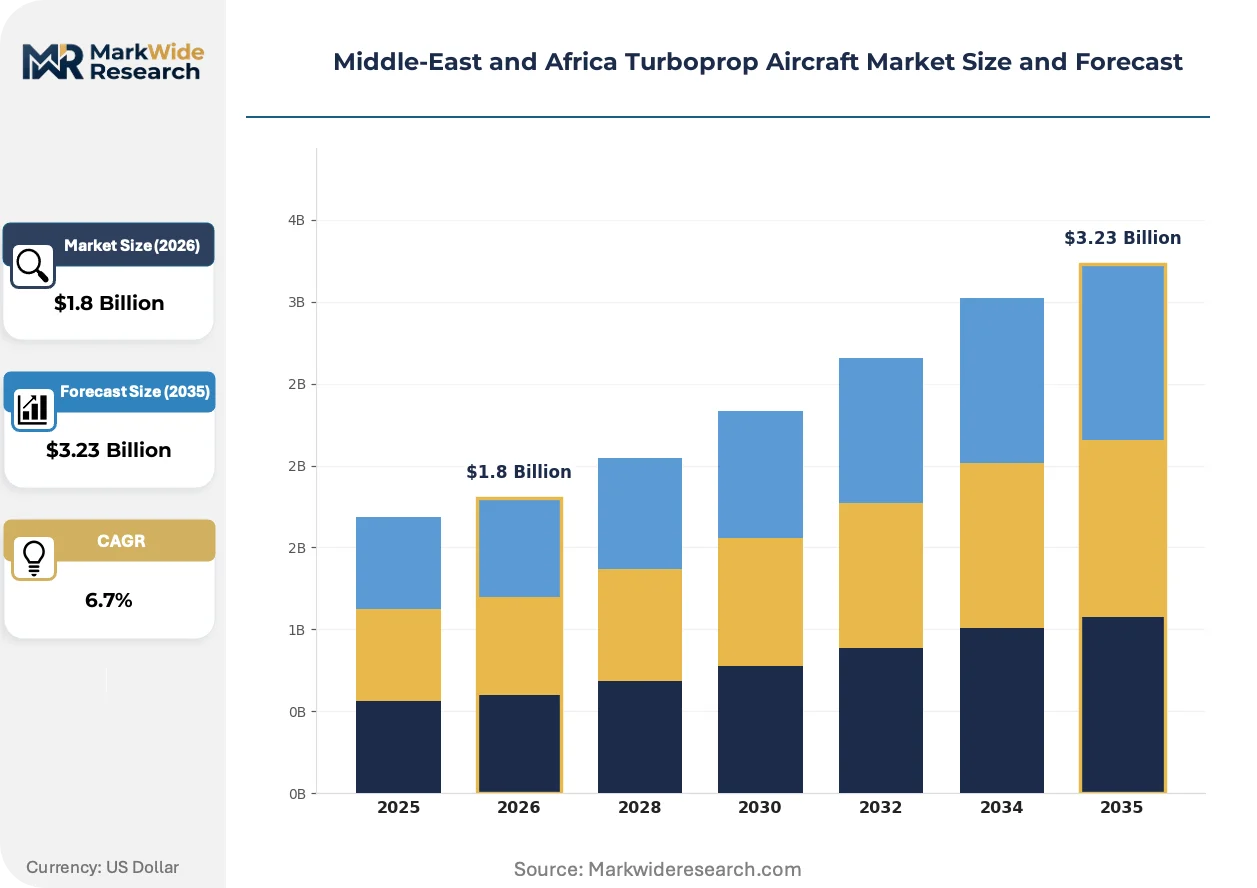
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regional Aircraft, Business Aircraft, Military Aircraft, Cargo Aircraft End User: Airlines, Government, Private Operators, Cargo Carriers Application: Passenger Transport, Freight Transport, Military Operations, Training Technology: Avionics, Engine Technology, Navigation Systems, Safety Systems |
| Companies Covered | Textron Inc., ATR, Pilatus Aircraft Ltd, DAHER, Lockheed Martin Corporation, Diamond Aircraft Industries GmbH, Viking Air Ltd, Air Tractor Inc., Piper Aircraft Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Turboprop Aircraft Market Shifts & Advancements
Digital engine monitoring and sustainable aviation fuel compatibility are converging to redefine turboprop operating economics across Middle-East and Africa route networks. These developments compress maintenance intervals while extending platform service lives.
Composite propeller blade technology is displacing traditional aluminum construction in regional turboprop retrofits. Operators including Royal Air Maroc are adopting these lighter assemblies to reduce fuel burn on North African sectors. The shift is displacing legacy metal blade aftermarket suppliers from the upgrade value chain.
South Africa's Civil Aviation Authority alignment with ICAO Annex 16 Volume I noise standards is tightening import eligibility for pre-owned turboprop fleets. This regulatory convergence forces foreign-registered aircraft to undergo costly acoustic treatment prior to South African Airworthiness Certificate issuance. Ethiopian and Kenyan operators are accelerating new-build procurement to preempt secondary market restrictions.
Power-by-the-hour contracts are capturing maintenance spend previously captured by independent MRO shops. Gulf Cooperation Council government operators now specify total support agreements in tender documentation. Nigeria's domestic carriers lag this transition, retaining component-by-component procurement that fragments supplier relationships.
Middle-East and Africa Turboprop Aircraft Market Segmentation
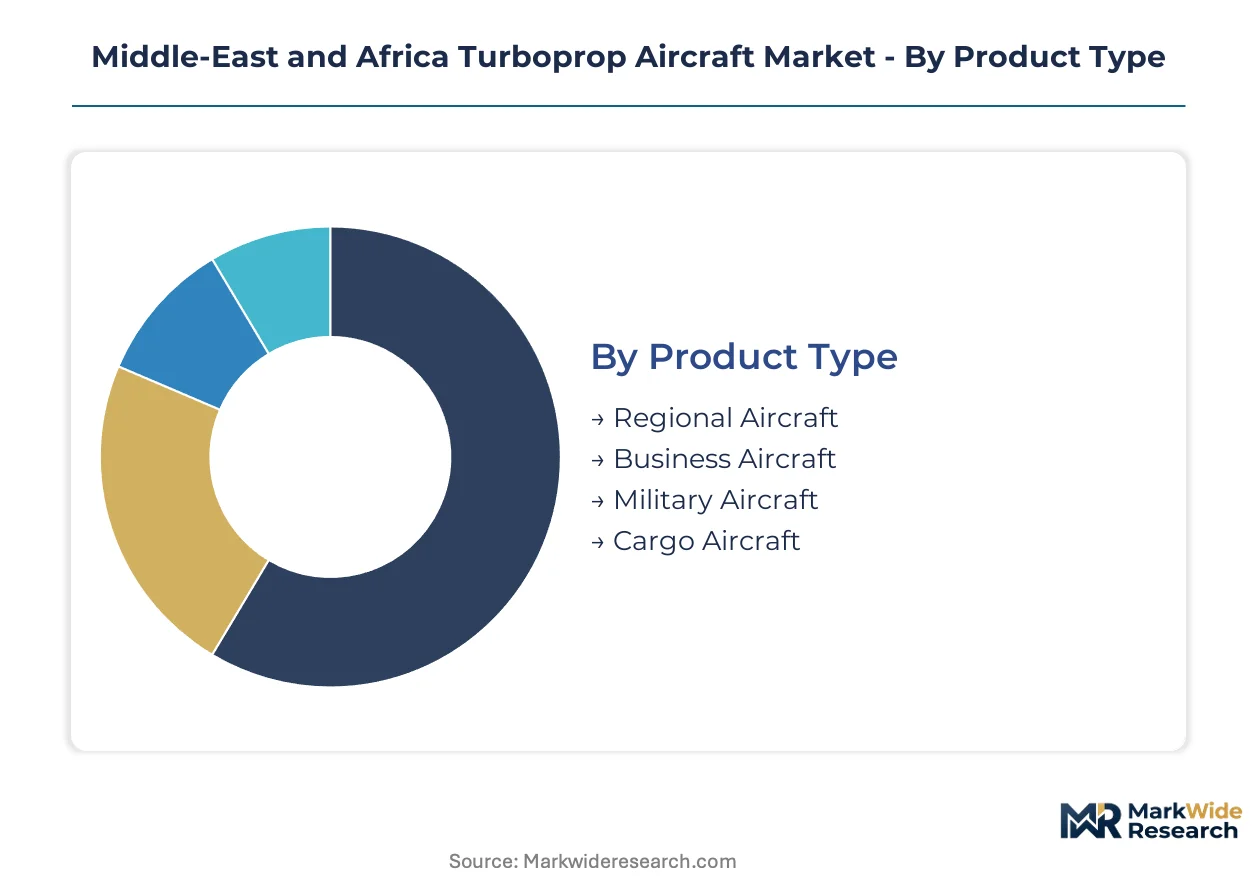
Turboprop aircraft segmentation in the Middle-East and Africa reveals distinct margin pools tied to operational intensity and regulatory exposure. Fleet operators prioritize segments where hot-and-high performance and short-field capability translate directly to route economics.
Product Type:
Margin concentration follows utilization cycles, with high-cycle commercial platforms commanding premium aftermarket value and military variants capturing long-term sustainment contracts.
- Regional Aircraft:Twin-turboprop platforms seating 50-78 passengers dominate fleet renewal programs at Ethiopian Airlines and Royal Air Maroc. East African carriers deploy these aircraft on thin routes into unimproved airstrips where jet operations face payload restrictions.
- Cargo Aircraft:Converted regional turboprops and factory freighters serve e-commerce logistics into secondary African cities. Nigerian cargo operators are expanding dedicated turboprop freighter fleets to bypass congested hub airports.
- Military Aircraft:Intelligence, surveillance, and reconnaissance configurations concentrate in North Africa and the Sahel. Governments prioritize single-engine platforms for maritime patrol and border surveillance missions.
- Business Aircraft:King Air and PC-12 platforms anchor private and government operator segments across Gulf Cooperation Council states. These aircraft serve executive transport and medical evacuation roles.
Regional Aircraft holds installed capacity. Cargo Aircraft is rotating up the share rankings.
End User:
Procurement authority splits between centralized government tenders and fragmented airline fleet decisions, shaping contract structures and payment terms.
- Airlines:Scheduled carriers in Ethiopia, Kenya, and Morocco drive new-build turboprop demand. Fleet standardization around ATR or Dash 8 families reduces pilot training and spare parts complexity.
- Cargo Carriers:Dedicated freight operators in Nigeria and South Africa are acquiring turboprop freighters for domestic and intra-regional networks. These operators favor older platforms with lower capital costs and established MRO support.
- Government:Military and paramilitary agencies procure surveillance-configured turboprops through defense procurement channels. Gulf Cooperation Council states specify total support agreements covering training and logistics.
- Private Operators:Corporate flight departments and charter operators value single-engine turboprops for operating cost control. Humanitarian organizations operating in remote African territories favor STOL-capable platforms.
Airlines command the dominant order backlog. Cargo Carriers are expanding most quickly as e-commerce logistics penetrate secondary markets.
Application:
Operational tempo and payload requirements determine technology specifications and maintenance intensity across mission profiles.
- Passenger Transport:Scheduled regional services account for the majority of turboprop flight hours in the Middle-East and Africa. Carriers optimize seat density and turn times for competitive positioning against road transport.
- Freight Transport:Express cargo and general freight operations utilize both converted passenger aircraft and factory-built freighters. Secondary city connectivity drives demand for turboprop payload-range economics.
- Military Operations:Intelligence, surveillance, and reconnaissance missions require integrated sensor suites and extended loiter capability. Maritime patrol applications favor platforms with endurance exceeding eight hours.
- Training:Flight schools and military training establishments operate turboprops for multi-engine and instrument rating instruction. South African and Egyptian training organizations maintain significant turboprop trainer fleets.
Passenger Transport holds installed capacity. Freight Transport is climbing the fastest as logistics networks expand.
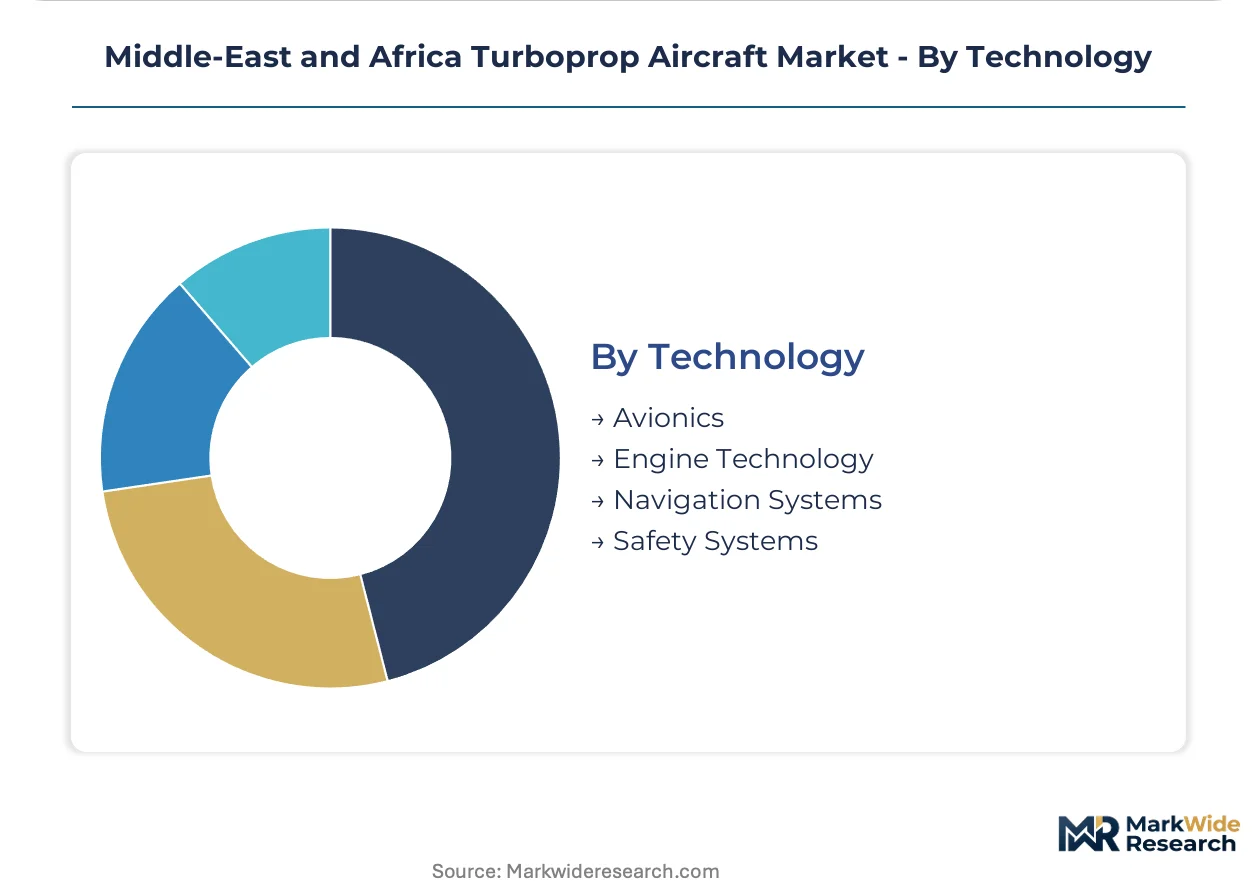
Technology:
Certification requirements and upgrade pathways concentrate value capture among OEM-authorized providers and designated engineering representatives.
- Engine Technology:Pratt & Whitney Canada PT6A and PW100 series power the majority of regional turboprop fleets. Hot-section refurbishment and life-limited component replacement dominate aftermarket spend.
- Avionics:Glass cockpit retrofits and performance-based navigation upgrades extend operational capability at aging airfields. EASA validation timelines for supplemental type certificates create bottlenecks for independent modifiers.
- Safety Systems:Terrain awareness and traffic collision avoidance systems are mandated for commercial operations under ICAO standards. Retrofit demand concentrates in pre-owned aircraft imports.
- Navigation Systems:Required navigation performance and satellite-based augmentation enable operations at airports lacking ground-based infrastructure. African ANSPs are deploying performance-based navigation procedures at secondary airports.
Engine Technology holds installed capacity. Avionics is rotating up the share rankings as retrofit cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's General Authority of Civil Aviation implements GACA Part 121 operational rules that standardize commercial turboprop deployment. These regulations reduce regulatory friction for new market entrants while compressing fleet renewal timelines across the Kingdom's domestic aviation sector.
Saudi Arabia
Domestic route liberalization drives turboprop procurement for short-haul connectivity between secondary cities. GACA Part 121 operational rules mandate specific equipment standards for commercial turboprop service. Riyadh anchors government fleet decisions through defense procurement channels prioritizing surveillance-configured platforms.
United Arab Emirates
Executive transport demand concentrates in Dubai and Abu Dhabi for King Air and PC-12 platforms serving corporate flight departments. The General Civil Aviation Authority coordinates EASA mutual recognition agreements streamlining European-certified aircraft access. Dubai International Airport hosts MRO facilities specializing in business turboprop maintenance.
South Africa
The Civil Aviation Authority enforces ICAO Chapter 14 noise compliance equivalents that reshape import eligibility for pre-owned turboprop fleets. Stricter airworthiness directives accelerate new-build procurement at regional carriers. Johannesburg concentrates MRO infrastructure serving sub-Saharan operator networks.
Nigeria
Domestic aviation liberalization under Air Operator Certificate issuance reforms opens fleet expansion pathways for indigenous carriers. Nigerian Civil Aviation Authority restructuring reduces regulatory processing delays for commercial turboprop registration. Lagos anchors cargo operator networks expanding dedicated turboprop freighter fleets.
Ethiopia
Ethiopian Airlines drives regional turboprop demand through fleet expansion targeting secondary East African cities with unimproved airstrips. The carrier's connectivity mandate prioritizes hot-and-high performance platforms. Addis Ababa serves as the operational hub for thin route deployment across the Horn of Africa.
Middle-East and Africa Turboprop Aircraft Market Competitive Landscape
Listed aerospace conglomerates compete with private specialists across certification authority and aftermarket support dimensions. Market structure concentrates around established type certificate holders with EASA CS-25 approval, while emerging challengers face validation bottlenecks at Toulouse and Cologne. Three archetypes dominate: legacy regional aircraft OEMs with full product portfolios, business turboprop specialists leveraging single-engine economics, and defense contractors integrating surveillance payloads. Competitive moves center on power-by-the-hour contract expansion and composite propeller blade retrofits displacing legacy metal aftermarket suppliers.
Within the legacy OEM tier, ATR and Textron Inc. occupy positions shaped by decades of regional aircraft type certificate accumulation. ATR exemplifies the twin-turboprop commercial specialist archetype through its established presence on North African routes. Textron Inc. anchors the business turboprop segment across Gulf Cooperation Council states through its King Air franchise. Pilatus Aircraft Ltd represents the single-engine specialist archetype, differentiating platforms for humanitarian and surveillance missions in remote African territories where STOL capability commands premium positioning.
| Leading Market Players |
|---|
| Textron Inc. |
| ATR |
| Pilatus Aircraft Ltd |
| DAHER |
| Lockheed Martin Corporation |
| Diamond Aircraft Industries GmbH |
| Viking Air Ltd |
| Air Tractor Inc. |
| Piper Aircraft Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day engine overhaul lead times at Pratt & Whitney Canada facilities concentrate pricing power among OEM-authorized service centers, compressing margins for independent MRO providers across Middle-East and Africa operator networks. This supply-chain rigidity translates directly into power-by-the-hour contract premiums that Gulf Cooperation Council government operators now accept as standard procurement terms.
Pricing Analysis
Certification level under EASA CS-25 creates the primary spread between factory-new turboprops and pre-owned imports requiring Supplemental Type Certificate validation. Three-tier pricing structure across EASA-certified, ICAO-compliant, and non-compliant equipment tiers reflects regulatory risk rather than performance differentiation. Pricing pressure stems from South Africa's Civil Aviation Authority noise compliance deadlines accelerating residual value compression on older platforms. Nigerian domestic carriers exhibit highest price sensitivity due to fragmented component-by-component procurement, while Gulf government operators prioritize total support agreements over unit economics.
Supply Chain Analysis
Strait of Hormuz transit underwrites composite propeller blade and avionics component flows from European suppliers to Gulf Cooperation Council assembly and MRO facilities. Manufacturing concentration in France, Switzerland, and Canada feeds final assembly lines, with hot-section turbine components drawing from specialized foundries in the United States and United Kingdom. Single-source vulnerability concentrates in Pratt & Whitney Canada PT6A engine production, where geopolitical friction could disrupt aftermarket parts availability. Distribution runs through Dubai International Airport's bonded warehousing and Johannesburg's sub-Saharan logistics hub, with Lagos emerging as Nigeria's cargo operator procurement center.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power-by-the-hour contracts and total support agreements are expanding faster than airframe sales across Middle-East and Africa operator fleets, repositioning aftermarket service attach as the dominant value capture mechanism. This service-layer acceleration rewards stakeholders who control MRO infrastructure and type-rated training capacity.
For Market Incumbents: Fortify aftermarket position by deepening vertical integration into hot-section refurbishment capabilities at Dubai and Johannesburg facilities, preempting independent MRO encroachment. Lock in multi-year total support agreements with Gulf Cooperation Council government operators before emerging challengers achieve EASA CS-25 validation, as type certificate concentration in Toulouse and Cologne creates defensible bottlenecks.
For New Entrants and Emerging Players: Anchor in Nigerian domestic aviation liberalization by targeting indigenous carriers underserved by legacy OEM power-by-the-hour programs. The humanitarian logistics segment offers lowest certification barriers for STOL-capable single-engine platforms, with United Nations World Food Programme tender requirements favoring new entrants who bundle surveillance payload integration with airframe supply.
For Investors and Strategic Acquirers: Carve-out targets emerge from European aerospace conglomerates seeking to divest non-core turboprop assets amid portfolio rationalization. Long-term viability hinges on aftermarket service density rather than airframe production scale, with EASA validation timeline compression serving as the critical inflection signal for platform economics improvement.
| Strategic Initiative | Industry Significance |
|---|---|
| Power-by-the-Hour Contract Expansion | Captures maintenance spend from independent MRO shops across Gulf operator fleets. |
| Composite Propeller Blade Retrofit | Displaces legacy aluminum suppliers from Royal Air Maroc upgrade value chains. |
| EASA CS-25 Certification Investment | Unlocks market access for emerging OEMs facing Toulouse validation bottlenecks. |
| Hot-Section Refurbishment Capacity | Secures aftermarket margin pools from PT6A engine overhaul demand concentration. |
| Surveillance Payload Integration | Creates mission profiles for Sahel maritime patrol and border security contracts. |
Research Methodology
Operator-level perspectives from fleet managers at Ethiopian Airlines and Royal Air Maroc, procurement officers at Nigerian cargo carriers, and MRO directors at Dubai International Airport facilities anchored the qualitative base. These primary interviews combined with secondary validation from EASA type certificate databases, ICAO Annex 16 noise compliance filings, and GACA Part 121 operational rule documentation. Customs records tracking turboprop imports into South Africa and Nigeria, alongside fleet databases from regional aviation authorities, supported bottom-up and top-down triangulation across the analysis window.
Sensitivity analysis tested forecast robustness against regulatory timeline acceleration, engine overhaul cost volatility, and regional jet substitution scenarios across the projection horizon. Segmentation dimensions modeled include product type, end user category, application mission profile, and technology upgrade pathway, with hot-and-high performance envelope requirements serving as an aviation-specific demand driver. CAGRs derived from fleet renewal cycle analysis and operator order backlog trajectories, incorporating EASA validation timeline assumptions and ICAO Chapter 14 compliance deadline impacts.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory convergence and stable engine aftermarket pricing; material deviation would warrant model refresh. Forecasts reflect documented assumptions regarding fleet expansion trajectories at named carriers and noise compliance enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Commercial Aircraft Market
Aircraft
Docking System Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Commercial Aerospace Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Aerospace Winglet System Market
Aircraft
Air Deflector Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Airplane Brackets Market
Aircraft
Airplane Ailerons Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
North America Business Jet Market