
 Ultra-Light Aircraft Market | 2026-2036
Ultra-Light Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Light Aircraft Market Analytics
Direct-to-consumer digital sales channels is tilting toward flight schools and recreational pilot networks, bypassing traditional dealer networks for kit-built and factory-complete deliveries. Textron Inc. leverages its established aviation distribution infrastructure to reach institutional buyers across North America. Evektor Aerotechnik competes through European manufacturing scale and Czech Republic export positioning. Autogyro GmbH specializes in gyroplane configurations that occupy a distinct niche within the broader ultralight category.
Ultra-light aircraft are fixed-wing or rotary-wing flying machines with maximum takeoff weights typically below 600 kilograms, constructed from aluminum alloys, carbon fiber composites, or fabric-covered steel tube frames, and designed for low-speed flight operations at altitudes generally under 10,000 feet. Their primary commercial purpose centers on recreational aviation, flight training, and specialized aerial work where operating costs must remain minimal. Piston engines dominate the power source landscape due to proven reliability and established maintenance networks, while electric motors represent the fastest-growing propulsion category as battery energy density improves. Weight-shift-controlled aircraft command concentrated margin pools in the trike segment owing to simpler construction and lower certification burdens.
The FAA's Part 103 framework governs unpowered and powered ultralight operations in the United States, while EASA's CS-LSA certification standard shapes product specifications across European markets; both frameworks directly determine design constraints, pilot licensing requirements, and market access conditions. The EU Green Deal and national decarbonization mandates are accelerating electric propulsion investment as manufacturers adapt product portfolios to emerging emissions standards. Stakeholders must monitor evolving battery certification protocols and airspace integration rules for low-altitude electric aircraft as regulatory divergence between jurisdictions intensifies competitive positioning requirements.
Market Dynamics
Electric propulsion systems are compressing the total cost of ownership gap against piston alternatives, forcing manufacturers to reconfigure supply chains around battery thermal management and motor integration rather than traditional engine sourcing.
Growth Catalysts
- Flight school network expansion:Training institutions in the United States are diversifying fleet composition to include weight-shift-controlled trikes, broadening the certified instructor base and normalizing ultralight operations within formal aviation education.
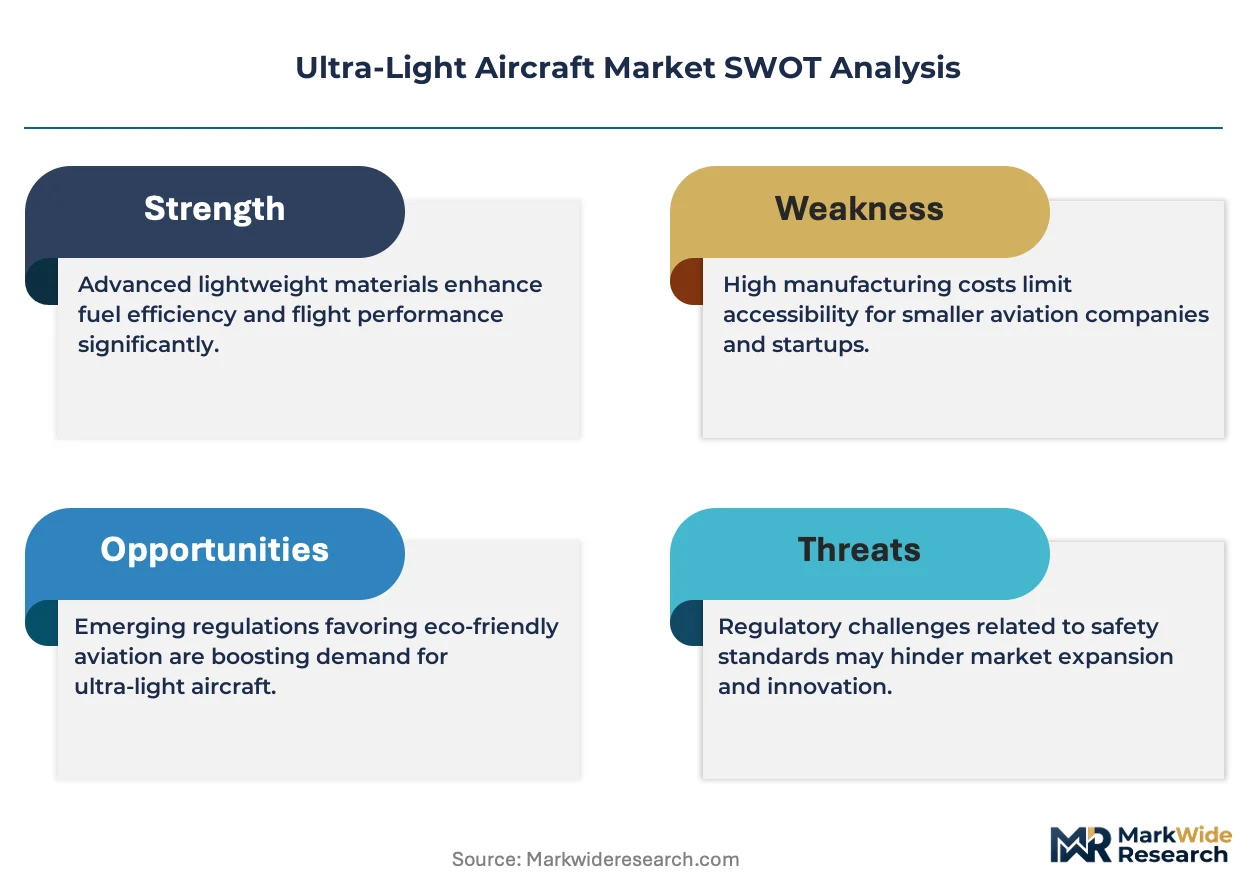
- FAA Part 103 operational flexibility:The regulatory framework permits single-seat recreational flight without pilot certification or aircraft registration, lowering barriers to entry for first-time buyers and hobbyist builders.
- Carbon fiber manufacturing scale:Automated layup processes and prepreg material cost reductions are enabling airframe producers to achieve strength-to-weight ratios previously reserved for certified light-sport aircraft.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack production for electric ultralights depends on cylindrical cell suppliers concentrated in East Asian manufacturing clusters, exposing airframers to raw material allocation volatility and shipping cost spikes.
- Airspace access fragmentation:Municipal zoning restrictions and controlled airspace proximity around urban centers limit viable operating locations for unregistered Part 103 aircraft, compressing addressable geography despite regulatory permissiveness.
- Certification pathway divergence:EASA CS-LSA requirements impose design standards incompatible with FAA ultralight exemptions, forcing European manufacturers to maintain parallel product lines and documentation systems.
Strategic Opportunities
- Aerial work services in precision agriculture:Ultralight gyroplanes equipped with multispectral sensors are penetrating crop monitoring contracts in Australia's wheat belt, displacing manned conventional aircraft and satellite subscriptions for mid-scale farming operations.
- EU Green Deal electrification mandates:National decarbonization targets for general aviation are channeling public R&D funding toward electric propulsion certification, creating subsidy-accessible pathways for battery-powered airframe development.
- Direct-to-builder kit distribution:Factory-complete and quick-build kit sales through manufacturer-operated digital portals are bypassing traditional dealer markups, capturing margin and shortening delivery timelines for experienced amateur constructors.
Industry Challenges
- Electric powertrain technician scarcity:Maintenance organizations lack personnel trained in high-voltage battery systems and permanent-magnet motor diagnostics, constraining aftermarket service network expansion for emerging electric fleets.
- Airworthiness directive compliance tracking:Kit-built aircraft operating under experimental amateur-built rules require owners to self-monitor safety bulletins and service letters, creating liability exposure and documentation gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Light Aircraft Market |
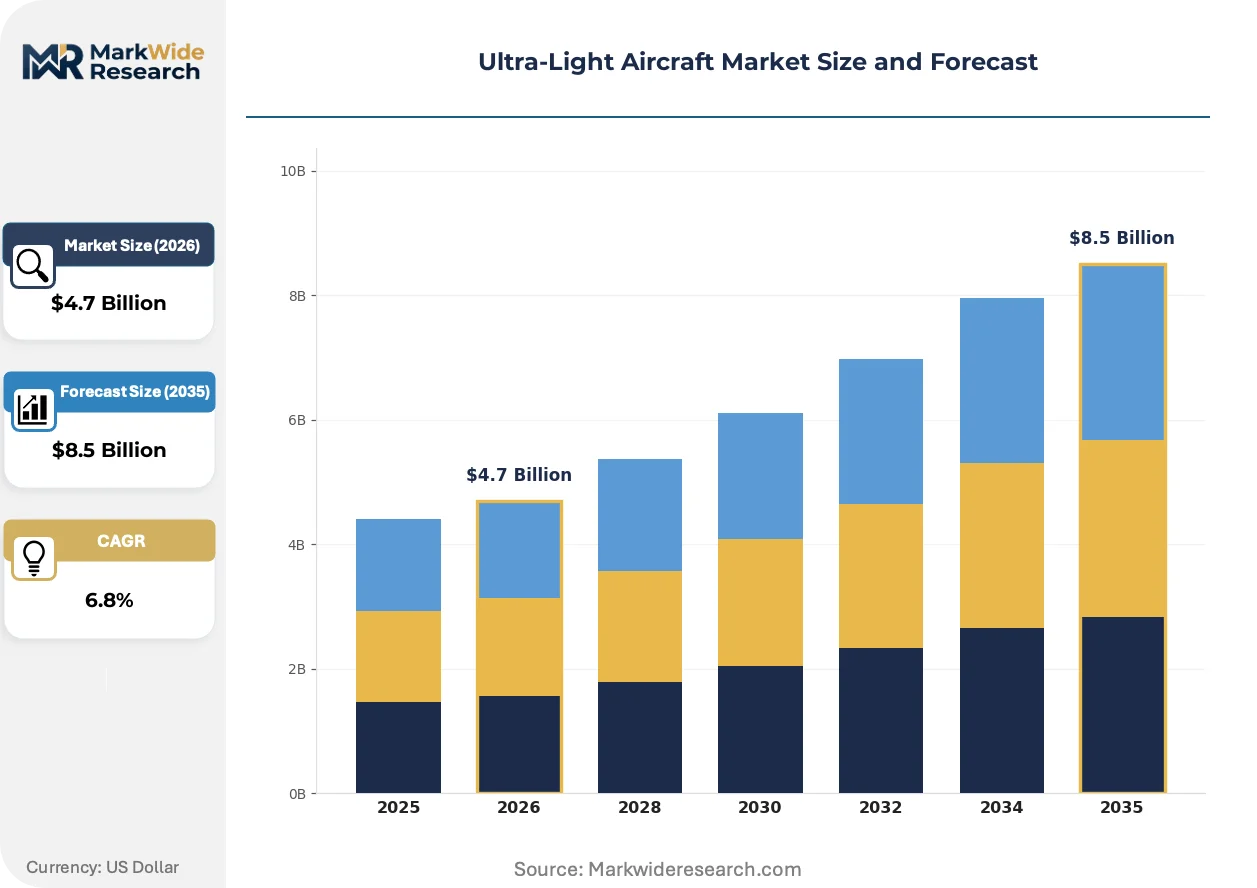
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Trikes, Powered Paragliders, Ultralight Gliders, Weight-Shift-Controlled Aircraft Power Source: Piston Engines, Electric Motors, Turbofan Engines, Hybrid Systems End User: Aviation Enthusiasts, Flight Schools, Recreational Pilots, Agricultural Services Application: Aerial Photography, Surveillance, Recreational Flying, Sports Aviation |
| Companies Covered | Pilatus Aircraft, Evektor Aerotechnik, Cirrus Aircraft, Flight Design General Aviation GmbH, Quicksilver Aircraft, Costruzioni Aeronautiche TECNAM SpA, Piper Aircraft, Inc., Autogyro GmbH, Textron Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Light Aircraft Market Evolving Landscape
Propulsion electrification and digital manufacturing are converging to compress development cycles and reshape how ultralight aircraft reach end users, with implications for certification strategy and aftermarket economics.
Solid-state battery chemistry with lithium-metal anodes is rendering obsolete the energy density limitations that previously confined electric ultralights to short-duration training circuits. Flight schools in California and Florida are trialing two-seat trainers with 90-minute endurance profiles, compressing the operational viability gap against Rotax-powered alternatives. This chemistry transition is rendering obsolete the range anxiety that suppressed early electric adoption.
EASA's CS-LSA amendment process for electric propulsion integration is forcing manufacturers to front-load certification documentation and establish formal design organization approvals earlier in product development. The industrial consequence is a bifurcation between airframers pursuing formal type certificates and those remaining in the uncertified kit market. European gyroplane specialists are most affected, with several Czech and German producers accelerating DOA establishment to maintain market access.
Buyers are consolidating purchases through recreational pilot cooperatives and flying club syndicates rather than individual ownership, particularly for higher-cost electric models where capital outlay and charging infrastructure requirements favor shared asset models. This collective purchasing is displacing traditional individual retail transactions and concentrating negotiation leverage with manufacturers. The pattern is most visible in France and Germany, where aero-club culture and dense airfield networks support fractional ownership structures.
Ultra-Light Aircraft Market Segmentation
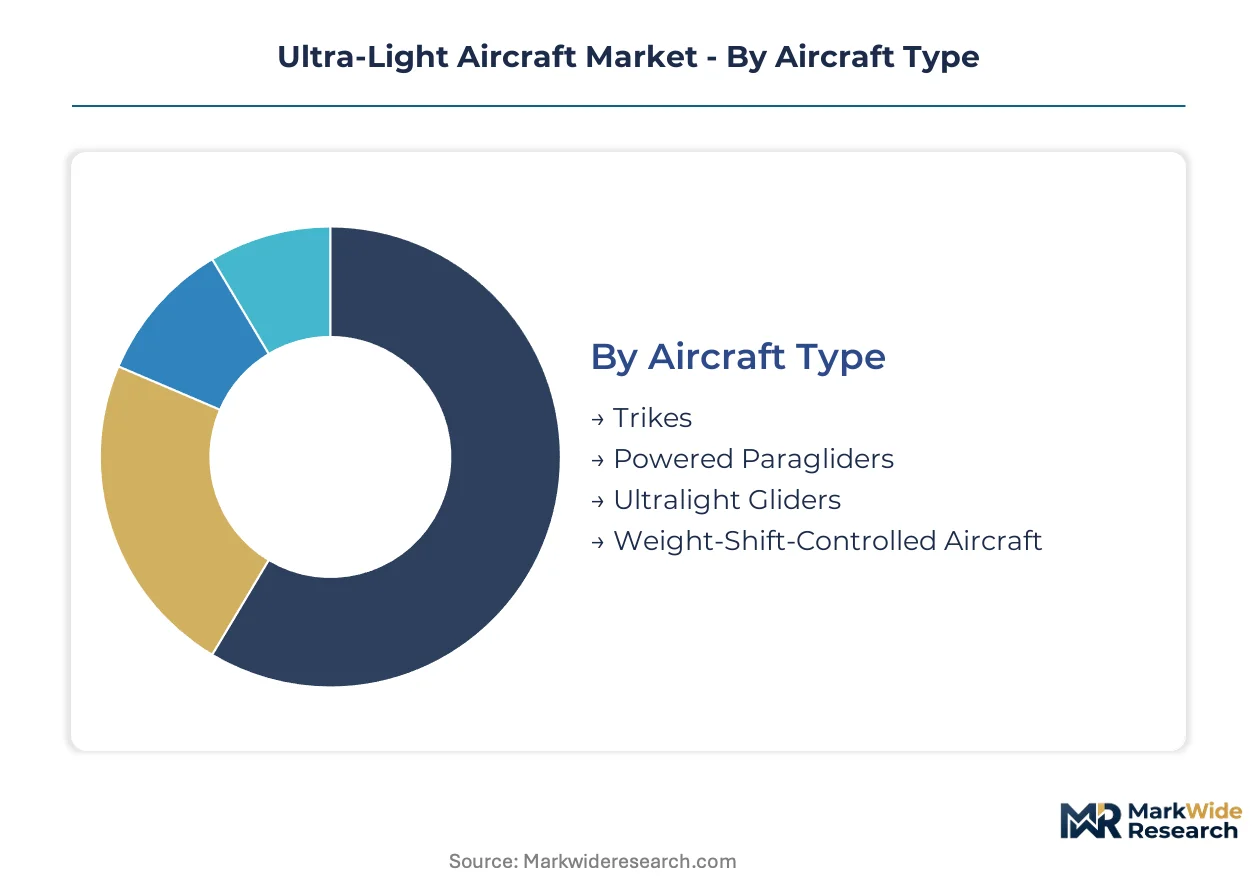
Segmentation in ultralight aviation reveals how regulatory boundaries, propulsion economics, and pilot certification pathways create distinct commercial territories with diverging replacement cycles and margin profiles. Understanding these divisions exposes where capital concentrates and where technology transitions accelerate fleet turnover.
Aircraft Type:
Weight-shift-controlled trikes turn over fastest as flight schools cycle training fleets aggressively, while gliders and powered paragliders exhibit decade-long replacement horizons tied to recreational owner loyalty.
- Trikes:Three-axis control systems with fabric-sail wings mounted on tubular aluminum frames, typically powered by two-stroke or four-stroke engines mounted pusher-style behind the pilot. Demand clusters in United States flight schools in Arizona and Florida where year-round training operations maximize airframe utilization and compress depreciation schedules.
- Weight-Shift-Controlled Aircraft:Pendulum-style control bars connected to flexible wings, constructed from corrosion-resistant alloys and UV-stabilized sailcloth. United States recreational pilot networks in the Southwest favor these for Part 103 compliance simplicity, driving kit-builder demand through direct manufacturer portals.
- Powered Paragliders:Backpack-mounted paramotor units with ram-air canopies, offering the lowest entry cost and minimal storage requirements.
- Ultralight Gliders:Rigid-wing or flex-wing unpowered aircraft designed for ridge soaring and aerotow launch, with airframes lasting 20+ years in private hands.
Trikes dominate installed base. Weight-Shift-Controlled Aircraft is where expansion concentrates.
Power Source:
Cost tiers separate established piston infrastructure from emerging electric systems where subsidy access and charging investment determine addressable buyer pools.
- Piston Engines:Air-cooled two-stroke and four-stroke reciprocating engines from Rotax and similar manufacturers, dominating current fleet composition through proven reliability and dense maintenance networks. Flight schools in Germany and France specify these for training continuity where electric charging infrastructure remains sparse.
- Electric Motors:Brushless DC permanent-magnet motors paired with lithium-ion battery packs, climbing the fastest as battery energy density crosses thresholds for 90-minute instructional flights. California and Florida training centers are trialing two-seat electric trainers where EU Green Deal funding offsets capital cost premiums.
- Turbofan Engines:Miniaturized jet propulsion for high-performance ultralight applications, occupying a narrow niche above typical weight limits.
- Hybrid Systems:Series or parallel architectures combining piston generators with electric traction motors, currently in experimental phases for extended-range agricultural surveillance missions.
Piston Engines anchor current revenue. Electric Motors represent the fastest-growing propulsion category.
End User:
Customer type determines purchase frequency, with institutional buyers cycling fleets every 3-5 years versus individual owners retaining airframes for 15+ years.
- Flight Schools:Certified training institutions operating under FAA Part 61 or EASA equivalents, requiring type-consistent fleets for standardized instruction. United States networks in Texas and California are expanding trike allocations to diversify beyond traditional fixed-wing training pipelines.
- Recreational Pilots:Individual owners operating under Part 103 exemptions or national equivalents, prioritizing acquisition cost and hangar footprint. German aero-clubs are consolidating purchases through cooperative structures to share charging infrastructure for electric models.
- Aviation Enthusiasts:Amateur builders and kit assemblers drawn to experimental amateur-built categories, with longer ownership horizons and higher maintenance self-sufficiency.
- Agricultural Services:Commercial operators deploying gyroplanes and fixed-wing ultralights for crop monitoring and precision spraying, particularly active in Australia's wheat belt and Brazil's soybean regions.
Recreational Pilots dominate installed base. Flight Schools is where expansion concentrates.
Application:
Application maturity varies dramatically, with recreational flying representing saturated legacy demand while aerial work applications penetrate new verticals.
- Recreational Flying:Pleasure and sport flying under visual flight rules, constituting the foundational demand layer. United States Part 103 operations in rural Midwest states maintain density through low regulatory barriers and abundant uncontrolled airspace.
- Aerial Photography:Camera and sensor platforms for real estate, surveying, and media production, expanding most quickly as stabilized gimbal technology reduces pilot workload. French and Italian operators are displacing helicopter charters for vineyard and coastal documentation.
- Surveillance:Border patrol, pipeline monitoring, and wildlife tracking missions where low operating cost offsets limited speed and endurance.
- Sports Aviation:Competitive and exhibition flying including aerobatics and precision landing contests, with concentrated demand in Eastern European manufacturing clusters.
Recreational Flying dominates installed base. Aerial Photography is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States recreational aviation infrastructure of over 5,000 public-use airports underwrites North American market dominance. Dense airfield networks in the Southwest and Southeast enable year-round Part 103 operations with minimal regulatory friction.
United States
Flight schools in Arizona and Florida cycle trike fleets aggressively to maximize training revenue per airframe. The FAA Part 103 framework permits single-seat recreational flight without pilot certification, attracting hobbyist builders to direct-to-manufacturer kit portals. The Mojave Desert corridor hosts concentrated weight-shift aircraft manufacturing and test-flight operations.
Germany
Aero-club cooperatives in Bavaria and Baden-Württemberg consolidate electric ultralight purchases to share charging infrastructure capital costs. EASA CS-LSA certification requirements shape product specifications distinct from FAA exemptions, forcing parallel documentation systems. The Stuttgart industrial zone anchors gyroplane component fabrication for export markets.
Czech Republic
Evektor Aerotechnik leverages Kunovice manufacturing scale to supply European flight schools with factory-complete light-sport aircraft. National export incentives support airframe shipments to Australia and Brazil. The Moravian aviation cluster concentrates composite fabrication and piston engine integration expertise.
Australia
Queensland and New South Wales agricultural operators deploy gyroplanes for wheat belt crop monitoring contracts. Civil Aviation Safety Authority regulations permit ultralight operations in uncontrolled airspace above pastoral regions. The Riverina district hosts concentrated aerial work service providers displacing conventional manned aircraft.
France
Aero-club syndicates in Provence-Alpes-Côte d'Azur fractionalize electric ultralight ownership to amortize charging infrastructure investments. EU Green Deal funding channels public R&D toward battery-powered airframe certification. The Toulouse aeronautics ecosystem supplies avionics and lightweight materials to domestic manufacturers.
Ultra-Light Aircraft Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in propulsion, avionics, and airframe materials. The vendor base organizes around three strategic archetypes: diversified aviation conglomerates with established distribution infrastructure, specialized European manufacturers leveraging export positioning, and gyroplane-focused niche producers. Competitive dynamics center on certification pathway selection and direct-to-builder digital channel development.
Among diversified aviation holding companies, Textron Inc. anchors the institutional buyer segment through North American distribution reach. Evektor Aerotechnik occupies a position within the European manufacturing tier, leveraging Czech Republic export infrastructure. Autogyro GmbH exemplifies the gyroplane specialization archetype, serving distinct aerial work and recreational pilot niches.
| Leading Market Players |
|---|
| Pilatus Aircraft |
| Evektor Aerotechnik |
| Cirrus Aircraft |
| Flight Design General Aviation GmbH |
| Quicksilver Aircraft |
| Costruzioni Aeronautiche TECNAM SpA |
| Piper Aircraft, Inc. |
| Autogyro GmbH |
| Textron Inc. |
| Others |
Value Network & Pricing Analysis
East Asian cylindrical cell manufacturing clusters concentrate lithium-ion battery supply for electric ultralight propulsion, anchoring margin capture with airframers who control thermal management integration and motor assembly rather than raw cell procurement.
Pricing Analysis
Volume-discount tiering structures separate factory-complete aircraft deliveries to flight schools from kit-builder sales through direct-to-manufacturer portals. Price differentiation rests on certification grade—FAA Part 103 exempt configurations command economy positioning while EASA CS-LSA type-certified models capture premium tiers. Cost compression in piston-powered trikes intensifies as flight schools consolidate fleet purchases and negotiate extended warranty bundles. Individual recreational pilots exhibit highest price sensitivity, deferring replacement decisions across decade-long ownership cycles.
Supply Chain Analysis
Supplier-financing facilities from Czech and German gyroplane component vendors extend payment terms to European airframers managing parallel FAA and EASA documentation systems. Manufacturing gravity centers on the Czech Republic for composite fabrication, Germany for precision machining, and China for battery cell supply. Raw material dependencies encompass carbon fiber prepreg, aluminum tubing, and permanent-magnet motor rare earth elements. Single-source vulnerability in cylindrical cell supply exposes producers to shipping cost volatility. Distribution runs through manufacturer-operated digital portals bypassing traditional dealer markups for kit-builder segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric propulsion is reshaping competitive positioning as solid-state battery chemistry crosses endurance thresholds for instructional flight, compressing the operational viability gap against Rotax-powered alternatives and forcing certification pathway decisions earlier in product development.
For Market Incumbents: Pre-empt electric technician scarcity by captive training program development and backward integration into battery thermal management systems. Threat from emerging electric-focused entrants with subsidy-accessible EU Green Deal funding demands accelerated design organization approval establishment to maintain EASA market access. Certification investment in CS-LSA electric amendments represents the priority defensive lever.
For New Entrants and Emerging Players: Pursue aerial photography service contracts in French and Italian vineyard regions where stabilized gimbal technology reduces pilot workload and displaces helicopter charters. Agricultural gyroplane monitoring in Australia's wheat belt offers penetrable white-space with lower regulatory barriers than flight school institutional sales. Go-to-market execution through aero-club cooperative structures captures shared charging infrastructure economics.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European gyroplane specialists holding established DOA credentials but limited electric propulsion integration. Long-term viability over the mid-decade horizon favors airframers with formal type certificate pathways rather than uncertified kit-market exposure. The signal to watch is EASA amendment finalization for electric CS-LSA integration, which will determine subsidy access and competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Certification Investment | EASA CS-LSA amendment alignment secures EU Green Deal subsidy access for battery-powered trainers. |
| Direct-to-Builder Digital Portal Expansion | Manufacturer-operated kit sales capture margin and compress delivery timelines for Arizona and Florida flight schools. |
| Aero-Club Cooperative Partnership Development | French and German fractional ownership structures amortize charging infrastructure capital across recreational pilot networks. |
| Aerial Work Service Vertical Penetration | Multispectral sensor integration for Australian wheat belt crop monitoring displaces conventional manned aircraft contracts. |
| Technician Training Program Establishment | High-voltage battery and permanent-magnet motor diagnostics capability unlocks aftermarket service network expansion. |
Research Methodology
Desk research of FAA regulatory filings, EASA certification databases, EU Green Deal implementation documents, and aviation trade association fleet surveys preceded structured interviews with flight school operators, gyroplane manufacturing executives, aero-club cooperative managers, and electric propulsion engineering leads. Secondary validation drew from customs export records, airframe registration databases, and battery supply chain disclosures. Bottom-up triangulation across individual airframe production volumes and top-down reconciliation against aggregate fleet estimates anchored market sizing.
Assumptions held fixed across the analysis window include current FAA Part 103 exemption stability, EASA CS-LSA amendment trajectory, and lithium-ion cell energy density improvement curves. Segmentation modeling incorporated aircraft type, power source architecture, end-user category, and application vertical. CAGRs derived from logistic diffusion curves fitted to electric propulsion penetration patterns and flight school fleet turnover rates. Industry-specific inputs encompassed charging infrastructure deployment timelines and subsidy program qualification thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by battery cell manufacturers into airframe assembly would shift outcomes. Macroeconomic deviation in raw material costs, regulatory acceleration of emissions mandates, or breakthrough solid-state battery commercialization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Zero-Emission Aircraft Market
Aircraft
GCC General Aviation Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Europe Business Jet Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Asia-Pacific Fighter Aircraft Market
Aircraft
Afterburner Market
Aircraft
Civil Helicopter Market
Aircraft
Middle-East Aviation Market
Aircraft
Aircraft Control Surface Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Aircraft Jack Market
Aircraft
Europe Commercial Aircraft Market