
 3D Printing Enabled Augmented Manufacturing Market | 2026-2036
3D Printing Enabled Augmented Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Enabled Augmented Manufacturing Market Insights
Contract manufacturers are unwinding legacy tooling contracts as OEMs bring augmented fabrication in-house. HP Development Company leverages its Multi Jet Fusion platform to dominate polymer production workflows. EOS GmbH anchors metal additive capacity across European automotive supply chains. General Electric Company sustains vertical control over aerospace turbine blade printing from design to post-processing.
3D Printing Enabled Augmented Manufacturing fuses layer-by-layer deposition with real-time sensor feedback, typically achieving tolerances of ±0.1 mm in metals and ±0.2 mm in thermoplastics, to produce geometrically complex parts without dedicated tooling. Selective Laser Sintering occupies the premium metals segment where aerospace buyers demand nickel superalloy performance. Fused Deposition Modeling leads prototyping volume due to low material waste and minimal setup overhead. Tooling applications capture expanding margin pools as moldmakers replace machined cavities with printed conformal cooling channels.
The EU AI Act and CE marking frameworks govern autonomous process monitoring in European production lines, while the FDA regulates patient-specific implants in US healthcare channels. ISO/ASTM standards for additive qualification create compliance barriers that favor certified equipment vendors. Stakeholders must decide whether to pursue multi-material certification or specialize in single-process dominance before regulatory fragmentation deepens.
Market Dynamics
Flight certification pathways for printed nickel superalloy turbine blades are compressing development cycles while fragmenting supplier qualification hierarchies across aerospace supply chains.
Growth Catalysts
- REACH compliance mandates:The EU Green Deal's material traceability requirements are forcing moldmakers toward printed conformal cooling channels that eliminate beryllium-copper alloys. German automotive clusters around Stuttgart now specify printed cavity inserts for injection tooling.
- Selective Laser Sintering maturation:Nickel superalloy performance thresholds in aerospace hot-section components now match wrought equivalents. Turbine blade repair depots are converting machining cells to additive refurbishment stations.
- Japan:METI's additive manufacturing roadmap prioritizes titanium medical implants and aerospace brackets. Osaka-based precision manufacturers are consolidating polymer and metal capabilities under single facility roofs.
Market Restraints
- Powder supply concentration:Spherical titanium and nickel superalloy feedstock production concentrates among three European gas atomization specialists. Aerospace buyers face 16-24 week lead times for certified powder lots.
- Post-processing bottleneck:Hot isostatic pressing and precision machining capacity for metal additive parts lags deposition throughput by 40% across industrial clusters.
- CE marking friction:The EU AI Act's conformity assessment procedures for autonomous process monitoring systems extend equipment validation timelines by 8-12 months.
Strategic Opportunities
- India:The PLI scheme for advanced manufacturing offers 4-6% output-linked incentives for domestic additive production. Medical device and aerospace component segments remain underpenetrated relative to global adoption curves.
- Digital inventory models:Spare part file repositories are displacing physical warehousing for legacy aircraft and industrial equipment. Airlines and power generation operators pay per-print licensing fees rather than holding castings in stock.
- Multi-material convergence:Polymer-ceramic and metal-polymer deposition systems enable integrated electrical, thermal, and structural functions in single builds. Satellite component manufacturers are qualifying these for RF and heat management combinations.
Industry Challenges
- Non-destructive inspection capacity:Computed tomography and ultrasonic validation of internal lattice structures requires specialized equipment scarce outside aerospace-certified facilities.
- ISO/ASTM qualification timelines:Material and process certification for flight-critical applications demands 18-36 month validation cycles with redundant build-test iterations.
- Legacy ERP integration:Additive workflow data formats lack standardization with SAP and Oracle manufacturing execution modules, forcing middleware development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Enabled Augmented Manufacturing Market |
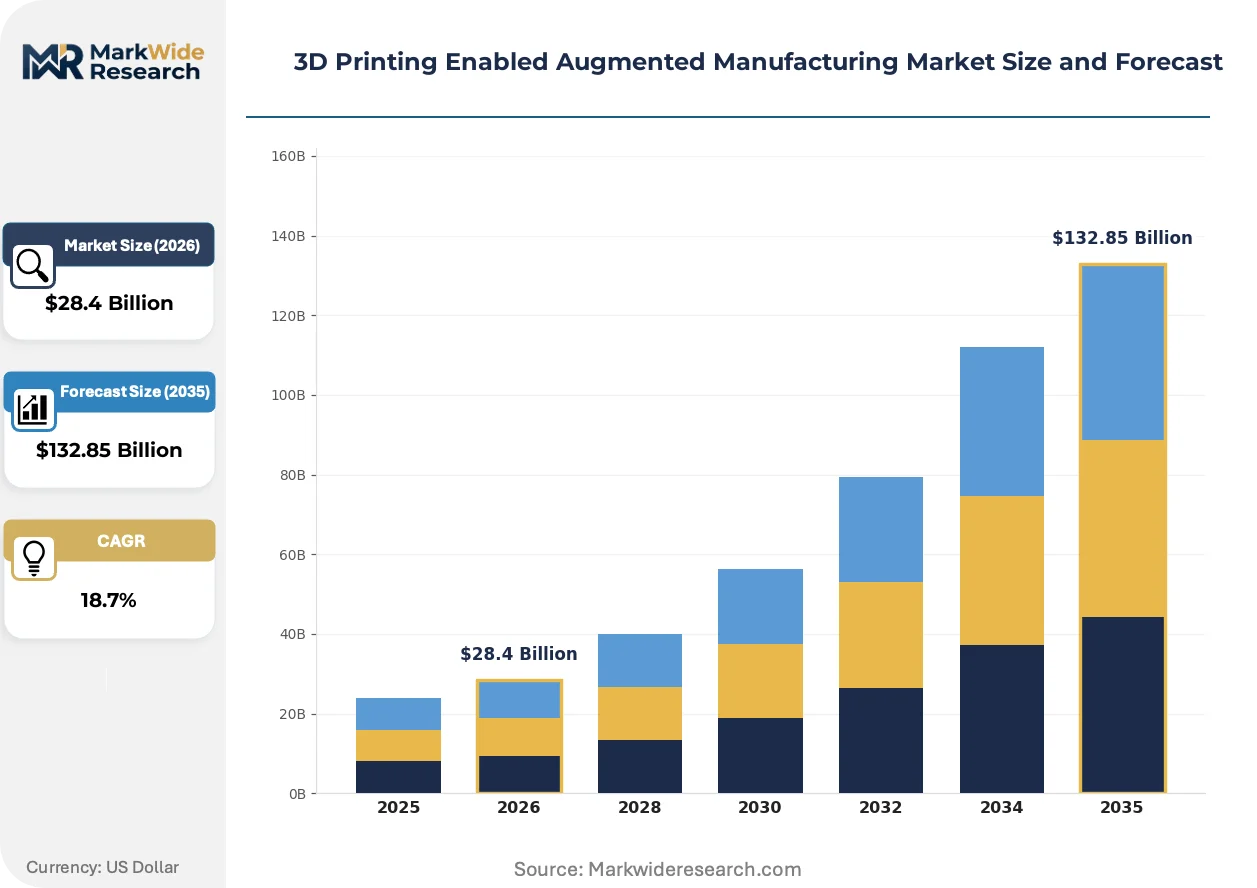
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $132.85 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User: Aerospace, Automotive, Healthcare, Consumer Goods Application: Prototyping, Tooling, Production Parts, Customized Solutions Material: Thermoplastics, Metals, Ceramics, Composites |
| Companies Covered | Stratasys Limited, 3D Systems Corporation, EOS GmbH, HP Development Company, General Electric Company, ExOne Company, Materialise NV, UnionTech, Voxeljet AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Enabled Augmented Manufacturing Market Trends and Innovations
Real-time melt pool monitoring and machine learning process control are separating production-grade additive systems from prototyping equipment, creating distinct vendor tiers and buyer expectations.
Directed Energy Deposition for repair and large-format near-net-shape builds is bifurcating from powder bed fusion precision applications. Marine and energy sector maintenance operations adopt wire-fed systems for shaft and impeller restoration at 3-5x deposition rates. The technology is bifurcating equipment vendor strategies between high-precision aerospace specialists and heavy-industry service bureaus.
The EU AI Act's risk classification framework for autonomous manufacturing systems now governs real-time defect detection algorithms in European production lines. Equipment vendors must submit technical documentation for conformity assessment before deploying closed-loop process control. Metal additive system sales into Germany, France, and Italy now bundle regulatory compliance consulting as standard.
Aerospace tier-one suppliers are consolidating purchase orders with single-source additive partners holding Nadcap and EASA Part 21G approvals simultaneously. Long-term throughput agreements replace spot orders for flight-certified components. This concentration is most visible in France and Germany, where Safran and MTU Aero Engines have captive-printed content targets exceeding 30% of structural components by weight.
3D Printing Enabled Augmented Manufacturing Market Segmentation
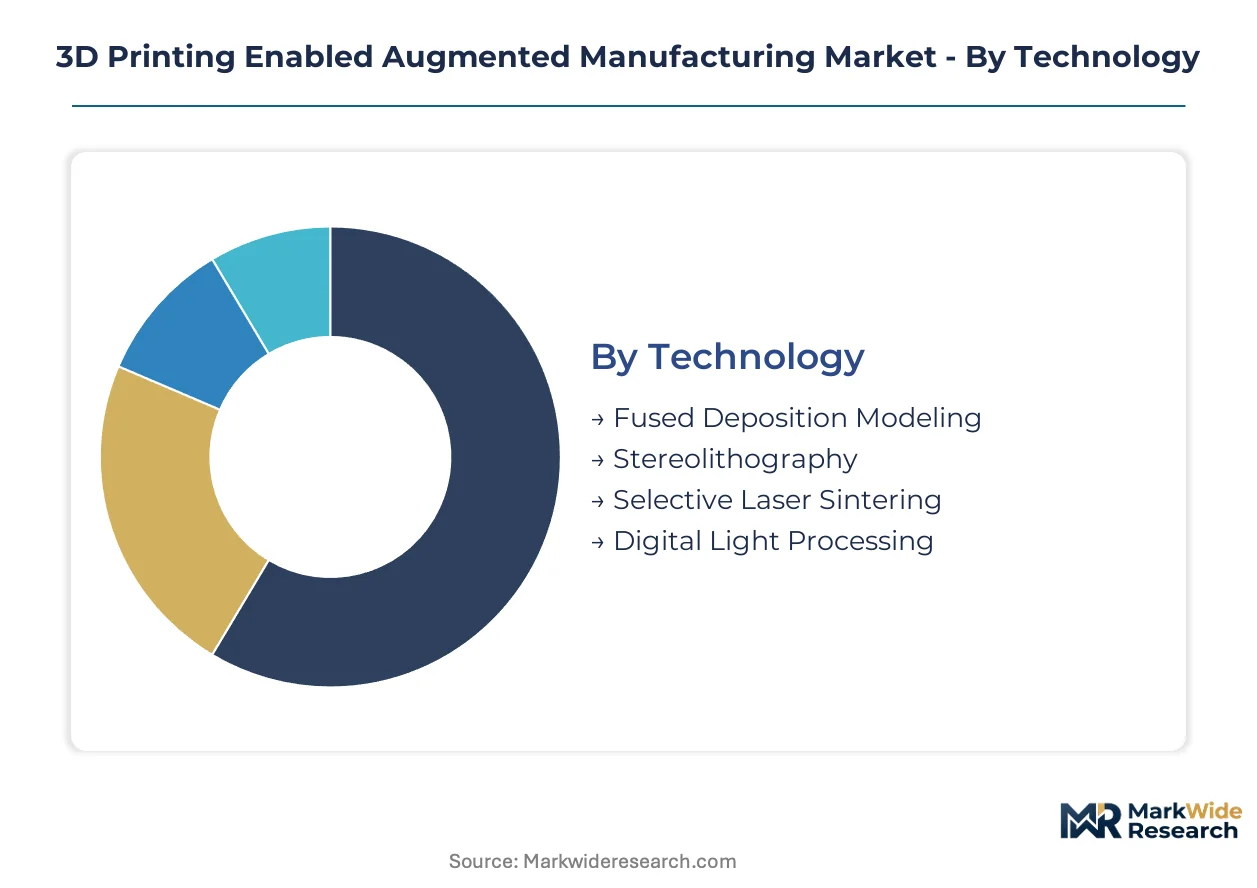
Segmentation in 3D Printing Enabled Augmented Manufacturing reveals divergent technology maturities and geographic demand clusters. Each dimension exposes distinct margin structures, certification barriers, and supply chain configurations that shape vendor positioning.
Technology:
Domestic production clusters in Germany and Japan dominate Selective Laser Sintering system output, while Fused Deposition Modeling hardware flows through export channels from US and Chinese manufacturing bases.
- Selective Laser Sintering:Powder bed fusion systems fuse polymer or metal particles with CO2 or fiber lasers, achieving layer resolutions down to 50 microns. Aerospace buyers in France and Germany specify these systems for nickel superalloy turbine blade qualification under EASA Part 21G frameworks. REACH-compliant powder handling adds 12-18% to total cost of ownership.
- Fused Deposition Modeling:Thermoplastic filament extrusion through heated nozzles builds parts layer-by-layer with minimal material waste. US-based automotive prototyping centers and Japanese consumer electronics manufacturers deploy desktop and industrial-scale systems for rapid iteration cycles. Open-source material compatibility lowers entry barriers for contract manufacturers.
- Stereolithography:UV laser polymerization of liquid resin delivers surface finishes unmatched by filament-based methods. Dental and medical device producers in Switzerland and the Netherlands favor these systems for surgical guide production.
- Digital Light Processing:Projected light engines cure entire resin layers simultaneously, compressing build times for small, intricate geometries. Italian jewelry and luxury goods manufacturers integrate these systems for direct casting pattern generation.
Selective Laser Sintering commands the established base. The steepest expansion runs through Fused Deposition Modeling.
End User:
Cost tier stratification separates flight-certified aerospace procurement from price-sensitive consumer goods volume, with healthcare occupying a premium-mid position defined by regulatory qualification.
- Aerospace:Nadcap-accredited suppliers produce flight-critical nickel superalloy components for hot-section applications. EASA and FAA certification pathways demand 18-36 month material qualification cycles. German and French tier-one suppliers now specify 30% minimum printed content by weight in new engine programs.
- Healthcare:Patient-specific implants and surgical instrumentation require FDA 510(k) or CE marking under MDR frameworks. Titanium cranial plates and acetabular cups dominate orthopedic applications, with Osaka and Stuttgart emerging as production clusters.
- Automotive:Tooling applications—conformal cooling inserts, jigs, fixtures—absorb capacity at German and US stamping and injection molding operations. BMW and Volkswagen captive print shops now supply internal cavity inserts.
- Consumer Goods:Eyewear frames, footwear midsoles, and electronics enclosures drive polymer volume. Italian and Spanish design houses leverage rapid iteration for seasonal product cycles.
Tooling and prototyping applications anchor automotive spend. The fastest volume gains are concentrating in healthcare patient-matched production.
Application:
Volume concentration shifts from prototyping toward production parts as flight certification and medical device pathways mature, with tooling capturing expanding margin pools in moldmaking.
- Tooling:Printed conformal cooling channels reduce injection cycle times by 20-40% while eliminating beryllium-copper alloys under REACH restrictions. German automotive clusters around Stuttgart specify printed cavity inserts as standard.
- Production Parts:Flight-certified turbine blades, orthopedic implants, and satellite brackets transition from qualification to serial output. Long-term throughput agreements replace spot orders for aerospace components.
- Prototyping:Design validation and fit-check models remain the entry point for Fused Deposition Modeling adoption. Consumer electronics and automotive styling studios compress development timelines.
- Customized Solutions:Patient-matched surgical guides, dental aligners, and luxury goods personalization command 3-5x material cost multiples. Swiss and Dutch medical device specialists dominate regulatory-qualified output.
Prototyping retains the largest installed base. Production parts are climbing the fastest as certification barriers fall.
Material:
Supply concentration in spherical metal powder atomization creates bottlenecks, while thermoplastic filament production disperses across broader geographic manufacturing bases.
- Metals:Spherical titanium Ti-6Al-4V and nickel superalloy IN718 powders command 60-80% of aerospace material spend. Three European gas atomization specialists control certified powder supply, extending lead times to 16-24 weeks.
- Thermoplastics:ABS, nylon PA12, and high-performance PEKK filaments serve prototyping through production applications. US and Asian compounders supply commodity and engineering grades with minimal certification overhead.
- Ceramics:Alumina and zirconia feedstocks target dental restorations and aerospace thermal barriers. Japanese and German specialty chemical producers dominate high-purity powder supply.
- Composites:Carbon fiber-reinforced nylon and continuous fiber deposition systems enable structural automotive and drone components. Italian and US sporting goods manufacturers drive adoption.
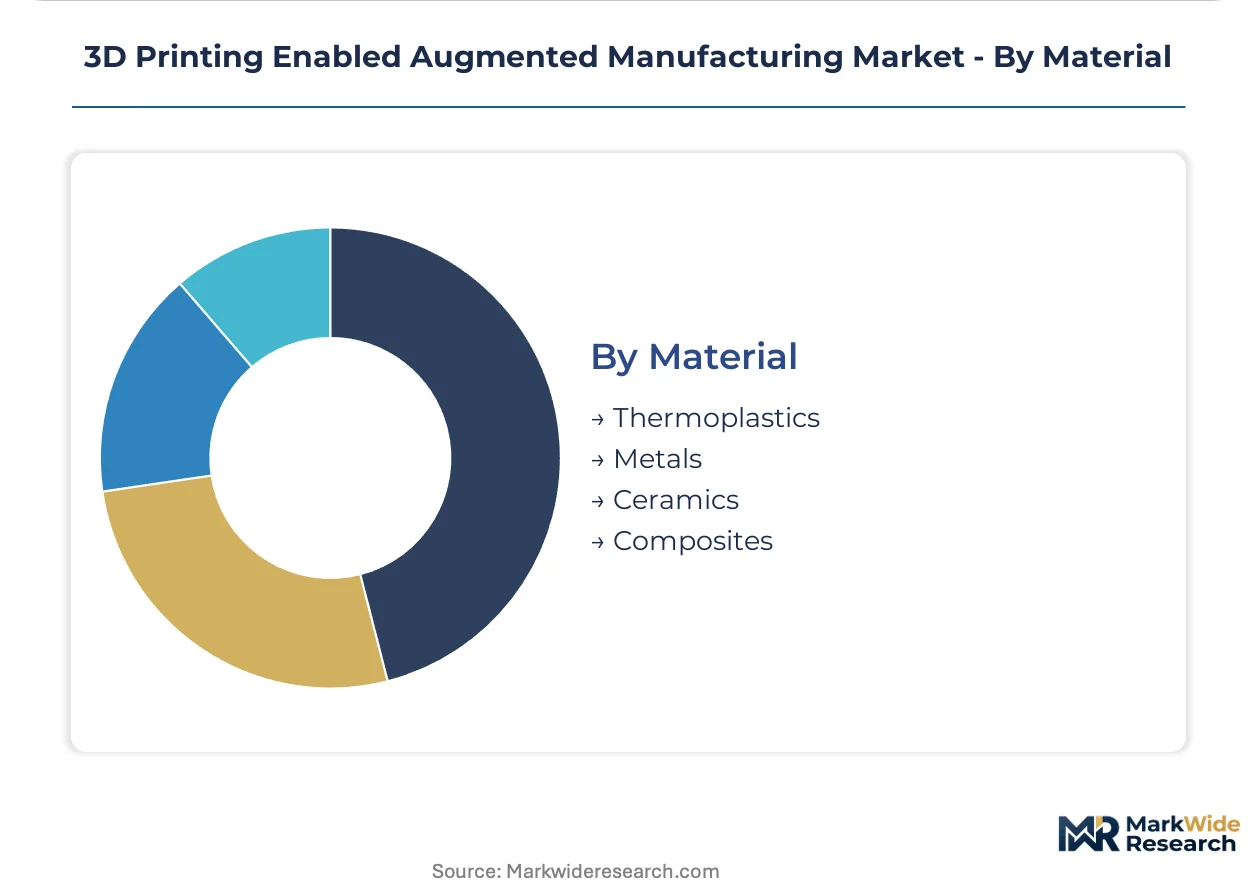
Thermoplastics anchor volume shipments. Metals are expanding most quickly as aerospace qualification completes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as the primary European entry point for industrial additive manufacturing equipment and spherical metal powder feedstock.
Germany
Automotive tooling demand and aerospace certification programs drive adoption. The EU Green Deal's REACH compliance mandates eliminate beryllium-copper alloys from injection molds. Stuttgart and Munich industrial clusters now specify printed conformal cooling inserts as standard procurement.
United States
Flight-critical turbine blade production and patient-specific medical implants absorb premium system capacity. FDA 510(k) pathways govern orthopedic device qualification. GE Aviation's Cincinnati and Auburn facilities sustain vertical control over nickel superalloy component supply chains.
Japan
Titanium medical implants and precision aerospace brackets concentrate demand. METI's additive manufacturing roadmap prioritizes domestic production autonomy. Osaka-based manufacturers consolidate polymer and metal capabilities under unified facility operations.
France
Aerospace tier-one suppliers consolidate long-term throughput agreements for flight-certified components. EASA Part 21G frameworks govern Nadcap-accredited production. Safran's Paris and Bordeaux operations target captive-printed content exceeding 30% of structural engine components.
India
Medical device and aerospace component segments remain underpenetrated relative to global adoption curves. The PLI scheme for advanced manufacturing offers output-linked incentives for domestic additive production. Bangalore and Hyderabad precision engineering clusters attract contract manufacturer investment.
3D Printing Enabled Augmented Manufacturing Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized additive equipment vendors competing across distinct technology tiers. Market structure fragments between polymer system specialists, metal powder bed fusion providers, and integrated aerospace manufacturers operating captive print shops. Strategic archetypes include platform-agnostic service bureaus, vertically integrated OEMs, and precision metal powder suppliers. Capacity expansion and regulatory certification partnerships constitute the dominant competitive moves.
Within the diversified industrial tier, General Electric Company and HP Development Company exemplify distinct strategic positions. EOS GmbH anchors metal additive capacity across European supply chains. These three entities represent the spectrum from captive aerospace production to platform-scale polymer workflows.
| Leading Market Players |
|---|
| Stratasys Limited |
| 3D Systems Corporation |
| EOS GmbH |
| HP Development Company |
| General Electric Company |
| ExOne Company |
| Materialise NV |
| UnionTech |
| Voxeljet AG |
| Others |
Pricing and Supply Chain Analysis
Sixteen-to-twenty-four week lead times for certified spherical titanium and nickel superalloy powder lots concentrate pricing power with three European gas atomization specialists, compressing margins for aerospace buyers while elevating feedstock premiums. This supply bottleneck interacts with REACH compliance mandates to force moldmakers toward printed conformal cooling channels, reshaping procurement economics across German automotive clusters.
Pricing Analysis
Volume-discount tiering structures separate aerospace procurement contracts from spot orders in medical and consumer segments. Three-tier pricing stratifies across flight-certified premium systems, industrial-standard production equipment, and desktop economy units, with EASA Part 21G and Nadcap accreditation commanding substantial premiums. Cost compression in polymer prototyping tiers intensifies as open-source material compatibility erodes hardware margins. Healthcare buyers exhibit lowest price sensitivity due to patient-matched regulatory requirements, while consumer goods manufacturers drive hardest bargain on per-kilogram filament costs.
Supply Chain Analysis
Just-in-time powder inventory strategies dominate aerospace-certified facilities, though strategic stockpiling of spherical nickel superalloy feedstock is emerging among tier-one suppliers facing atomization bottlenecks. Supply concentrates in Germany, Japan, and the United States for precision system manufacturing, with spherical metal powder production anchored in European gas atomization plants. Critical dependencies include titanium Ti-6Al-4V feedstock, fiber laser sources, and hot isostatic pressing capacity. Single-source vulnerability in certified powder lots exposes buyers to qualification delays. Distribution runs through direct OEM sales for metal systems and reseller networks for polymer hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as aerospace tier-one suppliers consolidate long-term throughput agreements with single-source additive partners, fragmenting vendor access for smaller moldmakers and medical device specialists.
For Market Incumbents: Compound certification advantages by pursuing simultaneous EASA Part 21G and Nadcap accreditation expansions before regulatory fragmentation deepens under the EU AI Act. Prioritize captive post-processing capacity additions in Germany and France to capture margin pools currently leaking to specialized hot isostatic pressing subcontractors. Defensive positioning against emerging polymer-ceramic convergence threats demands multi-material R&D investment ahead of satellite component qualification cycles. For New Entrants and Emerging Players: Post-processing service gaps in hot isostatic pressing and precision machining offer white-space entry points, as deposition throughput exceeds finishing capacity by substantial margins across industrial clusters. India's medical device and aerospace segments remain underpenetrated relative to global adoption curves, with PLI scheme incentives reducing effective market entry costs. Target contract manufacturing partnerships with Bangalore and Hyderabad precision engineering clusters as the go-to-market angle, bypassing direct equipment sales competition. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because ISO/ASTM qualification timelines and flight certification pathways create durable barriers against commodity competition. Acquisition targets should display dual aerospace-medical certification portfolios with established powder supply agreements. The signal to watch is consolidation of purchase orders with single-source partners among Safran and MTU Aero Engines operations, indicating captive-printed content targets are accelerating from qualification into serial production.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Certification Investment | EASA Part 21G frameworks for polymer-ceramic deposition systems unlock satellite RF-thermal integration contracts. |
| Post-Processing Capacity Expansion | Hot isostatic pressing additions in Stuttgart and Munich capture margin pools from aerospace blade refurbishment demand. |
| Digital Inventory Platform Launch | Per-print licensing models for legacy aircraft spare parts displace physical warehousing at airlines and power operators. |
| Regulatory Compliance Consulting Bundle | EU AI Act conformity assessment services extend equipment validation timelines but lock in long-term customer relationships. |
| Powder Supply Agreement Diversification | Dual-sourcing spherical titanium and nickel superalloy feedstock reduces 16-24 week lead time exposure for certified lots. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with additive manufacturing executives and secondary validation across regulatory filings and trade databases. Interview programs captured perspectives from aerospace procurement directors, moldmaking plant managers, medical device regulatory affairs leads, and powder metallurgy specialists at gas atomization facilities. Secondary sources encompassed EASA certification registries, FDA 510(k) databases, METI additive manufacturing roadmaps, and customs records for industrial equipment imports. Bottom-up equipment shipment tallies and top-down end-use spending estimates were triangulated to anchor market sizing.
Across the analysis window, forecast outputs were generated through segmented modeling of technology adoption curves, with Selective Laser Sintering, Fused Deposition Modeling, and Directed Energy Deposition tracked separately by end-use vertical and geographic cluster. Segmentation dimensions included technology tier, end-user industry, application type, and material category. CAGRs were derived from fitted diffusion curves calibrated to historical qualification timelines and regulatory approval patterns. Industry-specific inputs incorporated EASA Part 21G certification completion rates, REACH compliance transition schedules, and PLI scheme uptake trajectories in Indian manufacturing.
Underlying assumptions cover sustained aerospace qualification momentum, stable powder supply concentration, and gradual EU AI Act implementation, with deviation risk concentrated in regulatory timeline extensions and feedstock supply disruptions. Forecasts reflect these conditions without claiming predictive certainty. Revision becomes warranted when flight certification pathway compression accelerates beyond modeled rates or powder atomization capacity expands faster than aerospace demand absorption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Global 3D Printing in Medical Applications Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
Online 3D Printing Service Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
3D Printing in Aviation Market