
 ASEAN Waste Management Market | 2026-2036
ASEAN Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Waste Management Market Outlook
Municipal collection networks across ASEAN capitals is reconfiguring as state-owned and private operators split territorial concessions. Sembcorp Environmental Management Pte Ltd anchors Singapore's integrated waste-to-energy and water reclamation hub model. Veolia Environmental S.A extends its operational footprint through long-term service contracts with industrial zones in Vietnam and Thailand. ALBA Group Asia specializes in e-waste recovery infrastructure, leveraging German process technology licensed for Southeast Asian feedstock compositions.
ASEAN waste management encompasses the collection, transportation, treatment, and disposal of solid, liquid, and hazardous refuse across ten member economies, with engineered landfills achieving methane capture rates above 60 percent and waste-to-energy plants operating at 25-30 percent electrical efficiency. Recycling dominates formal investment flows but remains structurally underdeveloped for plastics sorting and contamination control. Incineration and waste-to-energy segments attract the fastest capacity additions in Indonesia and Thailand, where land scarcity elevates tipping fees. Collection services generate the most stable revenue pools through municipal concession structures, while hazardous waste treatment commands premium pricing due to limited licensed facility availability.
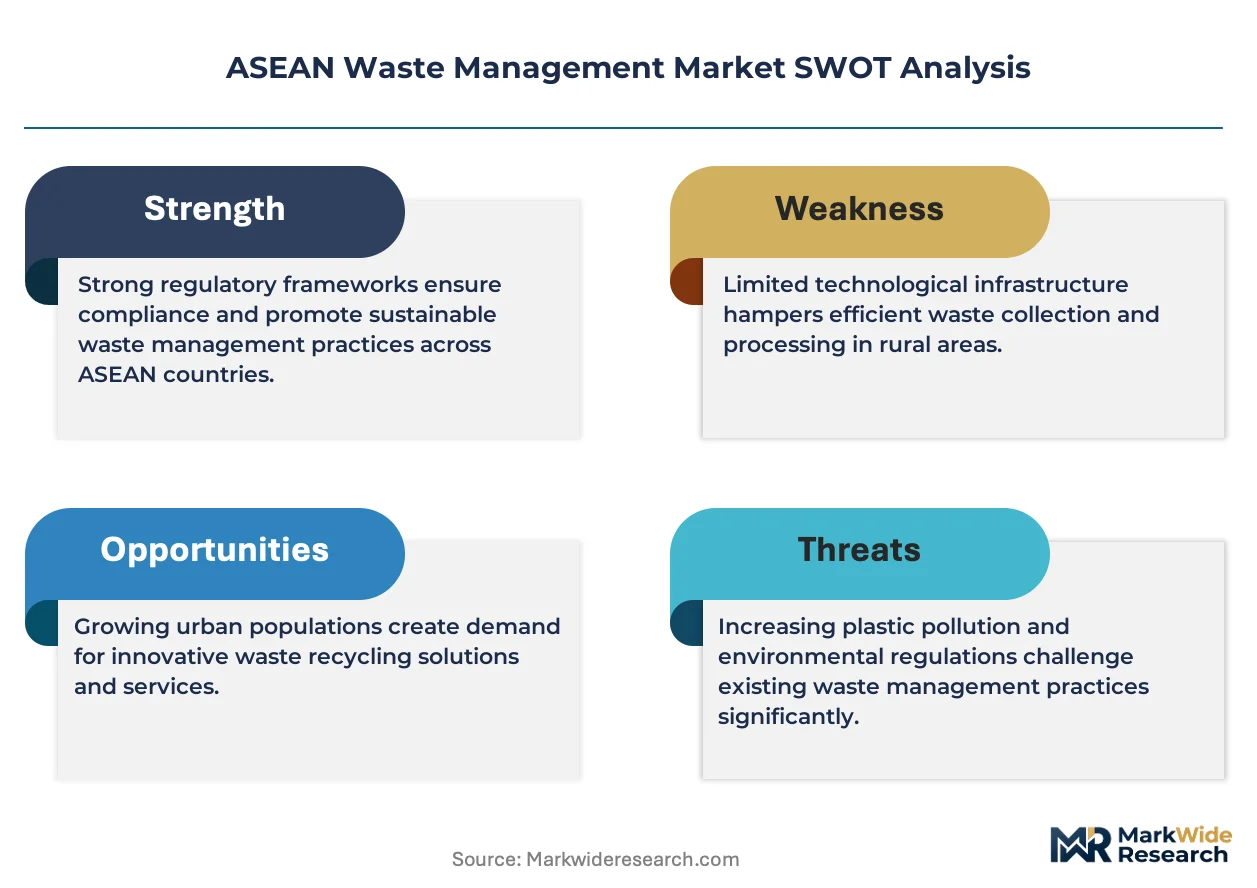
Indonesia's Ministry of Environment and Forestry enforces Extended Producer Responsibility regulations for packaging waste, compelling brand owners to fund collection systems. Thailand's Pollution Control Department and Singapore's National Environment Agency both mandate progressive landfill diversion targets that tighten annually. Malaysia's SWCorp administers solid waste concessions under federal jurisdiction in designated states, creating fragmented compliance obligations. Stakeholders must monitor regulatory divergence across ASEAN member states when structuring cross-border service platforms and technology licensing arrangements.
Market Dynamics
Indonesia's Extended Producer Responsibility regulations for packaging waste are forcing brand owners to fund collection systems, reshaping capital allocation across ASEAN waste management infrastructure and accelerating landfill diversion procurement in Greater Jakarta.
Growth Catalysts
- Malaysia's SWCorp concessions:Federal jurisdiction over solid waste in designated states is channeling investment into separation infrastructure and treatment capacity expansion.
- Landfill methane capture mandates:Thailand's Pollution Control Department tightening annual diversion targets is elevating waste-to-energy project economics in Bangkok metropolitan clusters.
- E-waste recovery specialization:German-licensed process technology adapted for Southeast Asian feedstock compositions is unlocking formal recycling investment flows previously blocked by contamination control gaps.
Market Restraints
- Plastics sorting cost volatility:Contamination rates in municipal streams above 30 percent are compressing margins for mechanical recycling operators across Vietnam and the Philippines.
- Hazardous waste facility scarcity:Limited licensed treatment capacity in Indonesia and Myanmar is forcing generators to bear premium transport costs for cross-border disposal.
- Land scarcity tipping fee escalation:Singapore's near-exhaustion of landfill airspace is pricing out small-scale collectors from island-wide service contracts.
Strategic Opportunities
- Myanmar's underpenetrated collection networks:Yangon and Mandalay municipalities lack formal concession structures, creating first-mover positioning for integrated operators.
- Industrial zone service bundling:Vietnam's processing manufacturing exporters are consolidating water reclamation with hazardous waste treatment under single-contract procurement.
- Waste-to-energy technology convergence:Combustion efficiency improvements above 25 percent electrical output are aligning with Singapore's integrated hub model for regional technology licensing.
Industry Challenges
- Waste characterization skill gaps:ASEAN laboratories lack certified technicians for calorific value testing required by waste-to-energy plant feedstock specifications.
- Concession integration complexity:Fragmented state-federal jurisdiction in Malaysia's SWCorp-designated versus non-designated states is forcing operators to maintain dual compliance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Waste Management Market |
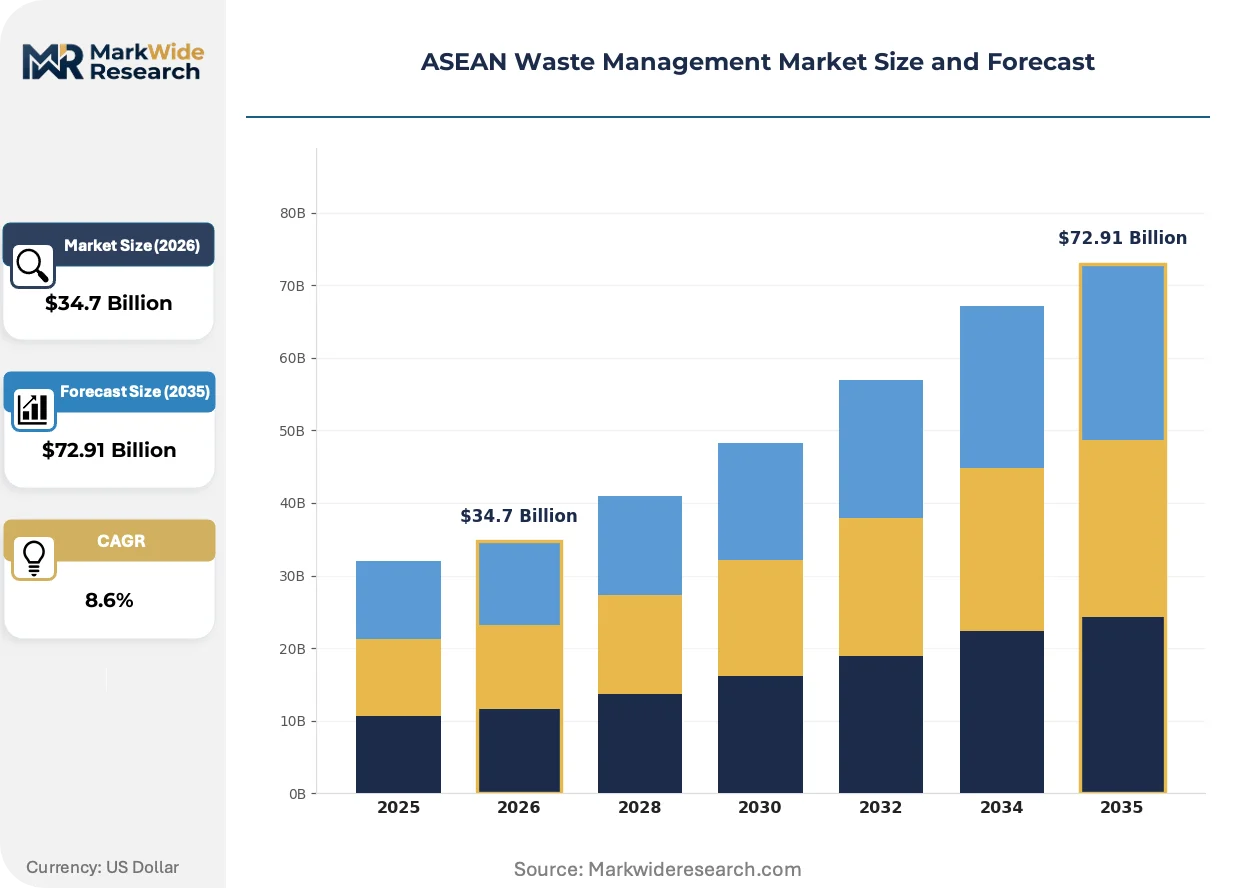
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Recycling, Incineration, Landfilling, Composting End User: Households, Municipalities, Industries, Commercial Enterprises Service Type: Collection, Treatment, Disposal, Waste-to-Energy Waste Type: Organic, Plastic, Hazardous, Electronic |
| Companies Covered | PT Prasadha Pamunah Limbah Industri (PPLI), Remondis, Sembcorp Environmental Management Pte Ltd, Blue Planet Environmental Solutions, ALBA Group Asia, Veolia Environmental S.A, Colex Holdings, Greenway Environmental, SUEZ, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Waste Management Market Strategic Shifts
Digital tracking systems and automated sorting technologies are compressing operational margins for manual-collection dependent operators while elevating capital barriers to market entry across ASEAN municipal concessions.
AI-powered optical sorting for plastic resin identification is rendering obsolete manual picking lines in Thailand's formal recycling facilities. Bangkok-based material recovery facility operators are deploying these systems at throughput rates exceeding 15 tonnes per hour. The technology is rendering obsolete the labor-cost arbitrage that previously sustained informal sector competitiveness in PET and HDPE recovery.
Singapore's National Environment Agency mandates progressive landfill diversion targets that tighten annually, compelling Sembcorp's integrated hub to expand waste-to-energy capacity ahead of schedule. The policy framework is accelerating procurement for advanced combustion systems with emissions controls meeting European Industrial Emissions Directive benchmarks. Industrial zone operators in Vietnam and Thailand are now specifying these same emission standards in long-term service contracts to preempt regulatory alignment costs.
Brand owners under Indonesia's Extended Producer Responsibility framework are direct-contracting collection cooperatives in Greater Jakarta, bypassing municipal intermediaries. This disintermediation is compressing concession fee structures for traditional waste management operators while transferring operational risk to packaging producers. The pattern is most visible in beverage and fast-moving consumer goods verticals where diversion targets are enforced through quarterly compliance reporting to the Ministry of Environment and Forestry.
ASEAN Waste Management Market Segmentation
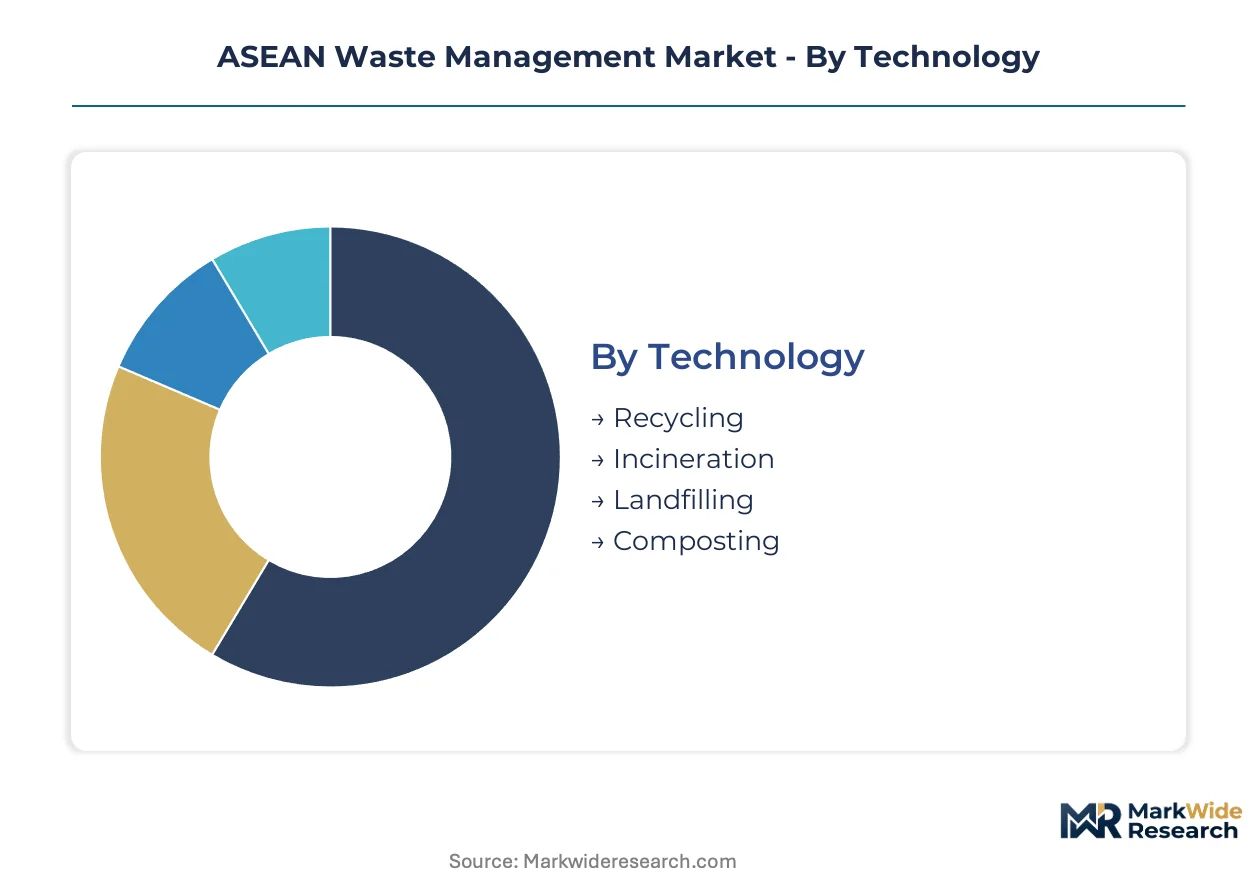
Technology choice determines capital intensity and regulatory exposure across ASEAN waste management procurement. Service configuration and waste stream composition further differentiate revenue stability and margin profiles for operators bidding municipal concessions.
Technology:
Recycling facilities turn over feedstock in hours while waste-to-energy plants amortize over decades, creating diverging capital recovery cycles across the technology mix.
- Recycling:Mechanical sorting lines processing contaminated municipal streams require continuous calibration. Thailand's material recovery facilities and Indonesia's informal sector cooperatives compete for PET and HDPE feedstock, with optical sorting investments displacing manual labor cost advantages.
- Incineration:Grate combustion systems achieve 25-30 percent electrical efficiency in Singapore's integrated hubs. Bangkok metropolitan clusters specify identical emission benchmarks preemptively, tightening procurement standards across Thailand's industrial zones.
- Landfilling:Engineered cells with methane capture above 60 percent dominate residual disposal in Vietnam and Myanmar. Singapore's near-exhausted airspace and Indonesia's diversion mandates compress long-term viability.
- Composting:Aerobic digestion of organic fractions serves Vietnam's agricultural feedstock demand and Indonesia's palm oil mill clusters.
Landfilling anchors the volume base while incineration gains share at the steepest rate.
End User:
Contract structures range from household tariff collection to industrial hazardous waste premiums, with municipalities offering longest tenors and steadiest cash flows.
- Households:Door-to-door collection in Indonesia's Greater Jakarta and Vietnam's Hanoi operates through municipal concessions with per-capita fee structures. Malaysia's SWCorp-designated states impose mandatory separation upstream, altering collection economics.
- Municipalities:Bangkok and Singapore specify integrated service bundles combining collection, transport, and treatment. Procurement cycles span 15-25 years, locking in operator returns through tipping fee escalators tied to landfill scarcity.
- Industries:Manufacturing exporters in Vietnam's processing zones consolidate water reclamation with hazardous waste treatment under single-contract procurement. Premium pricing reflects limited licensed facility availability.
- Commercial Enterprises:Retail and hospitality generators in Thailand's urban corridors face tightening diversion targets from the Pollution Control Department, accelerating outsourced collection adoption.
Municipalities anchor the volume base while industries gain share at the steepest rate.
Service Type:
Front-end collection commands lowest barriers but highest labor intensity, while waste-to-energy requires specialized combustion engineering and emissions compliance.
- Collection:Truck fleets and transfer stations dominate employment across ASEAN's informal sector transition. Myanmar's Yangon and Mandalay lack formal concession structures, creating positioning opportunities for integrated operators.
- Treatment:Mechanical-biological processing and anaerobic digestion handle organic fractions in Thailand's provincial clusters. Hazardous waste treatment capacity concentrates in Singapore and Thailand, forcing Indonesian generators toward cross-border disposal.
- Disposal:Engineered landfill cells with leachate management serve residual streams in Vietnam and the Philippines. Tipping fees escalate with land scarcity in metropolitan cores.
- Waste-to-Energy:Advanced combustion with European Industrial Emissions Directive alignment attracts procurement in Singapore and Bangkok. Technology licensing opportunities extend to Indonesia's Greater Jakarta diversion mandates.
Collection anchors the volume base while waste-to-energy gains share at the steepest rate.
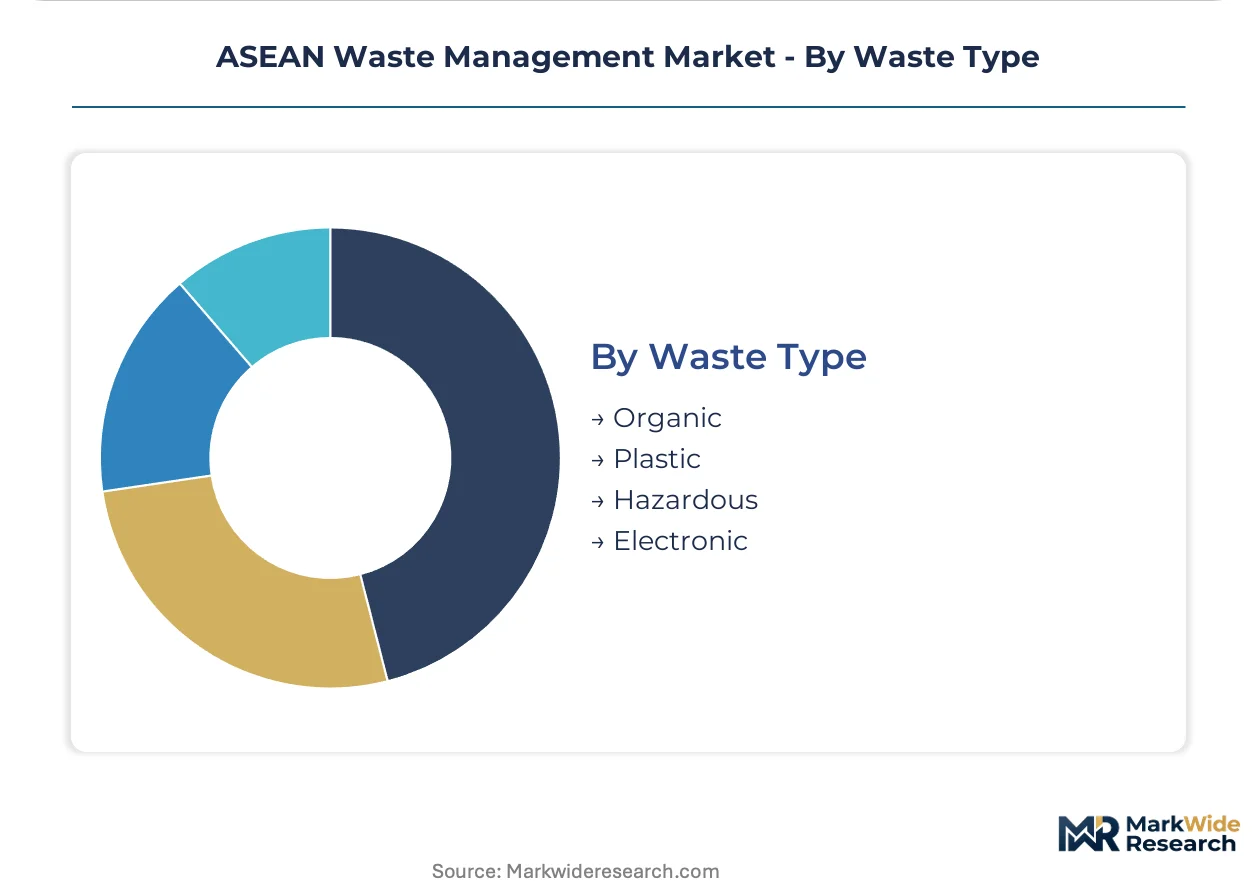
Waste Type:
Organic fractions decompose fastest, electronics retain highest value recovery potential, and hazardous streams command strictest handling protocols.
- Organic:Food waste and agricultural residues comprise 50-60 percent of ASEAN municipal generation. Composting and anaerobic digestion capacity expands in Vietnam's Mekong Delta and Indonesia's palm oil regions.
- Plastic:Contamination rates above 30 percent in Philippine and Vietnamese streams compress mechanical recycling margins. Indonesia's Extended Producer Responsibility regulations force brand owners to fund separate collection systems.
- Hazardous:Industrial chemicals and medical waste require licensed treatment facilities scarce outside Singapore and Thailand. Generators in Indonesia and Myanmar bear premium transport costs for compliant disposal.
- Electronic:E-waste recovery infrastructure leverages German-licensed process technology adapted for Southeast Asian feedstock compositions. ALBA Group Asia's specialized facilities target precious metal and rare earth recovery.
Organic waste anchors the volume base while electronic waste gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Straits of Malacca shipping corridor underwrites ASEAN's waste management logistics, connecting collection networks across Indonesia, Malaysia, Singapore, Thailand, and Vietnam through integrated port-to-plant supply chains.
Indonesia
Greater Jakarta's landfill diversion mandates are accelerating procurement for waste-to-energy infrastructure. The Ministry of Environment and Forestry enforces Extended Producer Responsibility regulations compelling brand owners to fund packaging collection systems. Industrial zones in Bekasi and Tangerang are consolidating hazardous waste treatment capacity to serve manufacturing exporters.
Singapore
Near-exhaustion of Semakau Landfill airspace is elevating tipping fees and pricing out small-scale collectors from island-wide contracts. The National Environment Agency mandates progressive annual diversion targets that tighten compliance obligations. Sembcorp's integrated waste-to-energy and water reclamation hub anchors the Tuas industrial cluster with European Industrial Emissions Directive-aligned combustion systems.
Thailand
Bangkok metropolitan clusters are specifying advanced emission benchmarks preemptively for waste-to-energy procurement. The Pollution Control Department tightens landfill diversion targets annually, reshaping project economics for combustion facilities. Material recovery facilities in Pathum Thani deploy AI-powered optical sorting at throughput rates exceeding fifteen tonnes per hour.
Vietnam
Processing manufacturing exporters in Ho Chi Minh City's industrial zones consolidate water reclamation with hazardous waste treatment under single-contract procurement. Provincial clusters in the Mekong Delta expand composting and anaerobic digestion capacity for agricultural feedstock demand. Hanoi operates door-to-door collection through municipal concessions with per-capita fee structures.
Malaysia
The Solid Waste and Public Cleansing Management Act channels federal jurisdiction over designated states into separation infrastructure investment. SWCorp-administered concessions in Peninsular Malaysia create fragmented compliance obligations across state boundaries. Selangor and Johor are accelerating treatment capacity expansion to meet mandatory upstream separation requirements.
ASEAN Waste Management Market Competitive Environment
On the supply side, the industry is consolidating around integrated operators with combustion engineering capabilities and long-term municipal concession experience. State-linked entities and European multinationals split territorial concessions across ASEAN capitals, while specialized e-waste and hazardous waste operators carve out premium niches. Three archetypes dominate: integrated hub operators with water-energy-waste synergies, regional concession holders with fleet-based collection networks, and technology licensors with German or European process specialization. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with operators securing twenty-five year procurement cycles to lock in returns through tipping fee escalators.
Within the integrated hub tier, Sembcorp Environmental Management Pte Ltd and Veolia Environmental S.A exemplify operators combining waste-to-energy with water reclamation under single-site configurations. ALBA Group Asia occupies a specialist position in e-waste recovery infrastructure, leveraging licensed German process technology adapted for Southeast Asian feedstock compositions. These three anchors demonstrate how geographic origin and corporate structure—Singapore-based Pte Ltd, French S.A., and German-licensed Asian subsidiary—map to distinct strategic positioning across collection, treatment, and technology licensing vectors.
| Leading Market Players |
|---|
| PT Prasadha Pamunah Limbah Industri (PPLI) |
| Remondis |
| Sembcorp Environmental Management Pte Ltd |
| Blue Planet Environmental Solutions |
| ALBA Group Asia |
| Veolia Environmental S.A |
| Colex Holdings |
| Greenway Environmental |
| SUEZ |
| Others |
Value Chain & Pricing Dynamics
Landfill scarcity tipping fee escalation determines both the premium-mid-economy pricing differentiation across service tiers and the supply chain shape favoring integrated hub operators over fragmented collection networks. Municipal concession structures in Singapore and Bangkok metropolitan clusters compress margins for small-scale collectors while elevating returns for combustion-capable incumbents.
Pricing Analysis
Volume-discount tiering structures separate integrated hub operators from fleet-based collectors from informal sector cooperatives across ASEAN municipal procurement. Price differentiation rests on certification grade for European Industrial Emissions Directive alignment and geographic delivery cost to landfill-scarce metropolitan cores. Cost compression in mechanical recycling is intensifying because contamination rates above 30 percent erode feedstock yields. Industrial zone exporters in Vietnam exhibit least price sensitivity due to bundled water reclamation contracts, while Philippine municipal governments demonstrate highest sensitivity under per-capita fee structures.
Supply Chain Analysis
Upstream feedstock availability draws from Indonesia's Greater Jakarta municipal streams, Thailand's Bangkok metropolitan clusters, and Vietnam's Mekong Delta agricultural residues. Critical inputs include German-licensed optical sorting equipment, European emissions control systems, and specialized combustion engineering expertise. Single-source vulnerability concentrates around German process technology licensors for e-waste recovery infrastructure. Distribution runs through Straits of Malacca shipping corridors connecting collection networks to integrated treatment hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence across ASEAN member states fragments compliance obligations, creating positioning niches for operators with dual-jurisdiction capabilities and technology licensing adaptability.
For Market Incumbents: Build combustion engineering moats through advanced emissions control certification ahead of regulatory tightening in Bangkok and Jakarta. Prioritize capacity addition in Selangor and Johor to capture Malaysia's mandatory separation infrastructure investment. Defend against emerging technology licensors by securing exclusive feedstock agreements with industrial zone exporters consolidating water reclamation and hazardous waste treatment.
For New Entrants and Emerging Players: Pursue Yangon and Mandalay collection network concessions where formal structures remain underpenetrated. Target Myanmar's municipal sector as most penetrable geography given absence of established concession holders. Enter through equipment-leasing partnerships with German technology licensors to bypass capital-intensive combustion engineering barriers.
For Investors and Strategic Acquirers: Specialized hazardous waste treatment operators with cross-border disposal capabilities represent priority acquisition archetypes given facility scarcity outside Singapore and Thailand. Long-term viability concentrates on operators securing 15-25 year procurement cycles with tipping fee escalators tied to landfill diversion mandates. Monitor Indonesia's Extended Producer Responsibility enforcement quarterly compliance reporting as inflection indicator for packaging waste collection system valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | German process technology adaptation for Southeast Asian e-waste feedstock compositions unlocks formal recycling investment flows. |
| Capacity Expansion | Waste-to-energy plant additions in Greater Jakarta align with Ministry of Environment and Forestry landfill diversion mandates. |
| Backward Integration | Collection fleet ownership in Vietnam's industrial zones secures feedstock supply for bundled water reclamation contracts. |
| Joint Venture | Partnerships with SWCorp-designated state operators navigate Malaysia's fragmented federal-state jurisdiction compliance. |
| Green Certification Program | European Industrial Emissions Directive alignment preempts procurement standard tightening across Bangkok metropolitan clusters. |
Study Parameters
The analysis maps collection services, treatment infrastructure, waste-to-energy combustion systems, and hazardous waste facilities, each validated through municipal procurement officers, industrial zone facility managers, technology licensing directors, and environmental compliance consultants. Primary interviews with concession operators and feedstock suppliers combined with secondary validation from customs records, national environment agency filings, and SWCorp concession databases. Bottom-up project pipeline assessment and top-down regulatory mandate analysis provide triangulation.
Assumption-sets held regulatory enforcement timelines and landfill airspace depletion rates fixed while varying feedstock contamination levels and technology licensing fee structures across the projection horizon. Segmentation dimensions modeled include technology choice, service configuration, end-user contract structure, and waste stream composition. CAGRs derive from capacity addition schedules and tipping fee escalation clauses. Forecast inputs incorporate Extended Producer Responsibility compliance cost pass-through rates and optical sorting throughput efficiency improvements.
Sensitivities concentrate around diversion mandate enforcement intensity in Indonesia and Malaysia's federal-state jurisdictional evolution. Forecasts reflect assumptions on technology licensing availability and feedstock supply security. Cross-checking against national environment agency procurement disclosure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
India Municipal Solid Waste Management Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
North America Waste Management Market
Waste Management & Pollution Control
Sharp Waste Disposal Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Qatar Waste Management Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market