
 North America Waste Management Market | 2026-2036
North America Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Waste Management Market Insights
Canadian waste-to-energy facility expansion is realigning North American processing capacity toward thermal recovery pathways. Waste Management, Inc. leverages its integrated landfill-gas-to-energy network across the Upper Midwest to sustain above-average power generation yields. Republic Services, Inc. anchors its competitive position through dense route concentration in Sun Belt metropolitan zones. Clean Harbors, Inc. specializes in hazardous waste treatment infrastructure that occupies a narrow but defensible technical tier.
Waste management encompasses the systematic collection, transport, processing, recycling, and disposal of material residues, with modern operations integrating sensor-based route optimization and leachate containment systems engineered to 0.1 mg/L pollutant discharge thresholds. The primary commercial purpose centers on minimizing environmental externalities while recovering embedded energy and material value from discarded streams. Collection services dominate revenue flow given their recurring contracted nature, while anaerobic digestion represents the fastest-expanding technology segment as utilities seek renewable natural gas feedstock. Industrial end users generate the highest per-account value given complex hazardous characterization requirements and cradle-to-grave liability exposure.
The EPA enforces landfill methane capture mandates under New Source Performance Standards, while state regulators in California and New York implement extended producer responsibility frameworks that shift collection financing onto brand owners. OSHA and DOT jointly govern hazardous waste worker exposure and transport classification, creating layered compliance obligations that elevate capital requirements for new market entrants. Stakeholders must monitor emerging per- and polyfluoroalkyl substances destruction rules that could force substantial incinerator retrofit investment decisions.
Market Dynamics
Landfill methane capture mandates under EPA New Source Performance Standards are forcing capital reallocation toward gas-to-energy infrastructure across the Upper Midwest and Northeast corridor.
Growth Catalysts
- Extended Producer Responsibility Frameworks:California and New York state laws shift collection financing onto brand owners, expanding contracted service volumes for municipal waste operators.
- Renewable Natural Gas Feedstock Demand:Utilities in the US Northeast and Canadian provinces are contracting anaerobic digestion output to meet decarbonization targets.
- Aging Infrastructure Replacement Cycles:Leachate containment systems engineered to 0.1 mg/L discharge thresholds require wholesale facility upgrades across the US Northeast corridor.
Market Restraints
- Capital Intensity of Thermal Recovery:Waste-to-energy facility construction requires $200-400 million per installation, concentrating development among entities with utility-scale balance sheets.
- Permitting Timeline Compression:EPA landfill methane regulations and state siting reviews extend greenfield approval cycles to 5-7 years in dense metropolitan zones.
- Technical Limitation of PFAS Destruction:Emerging per- and polyfluoroalkyl substances rules expose incinerator operators to substantial retrofit investment decisions without proven destruction pathways.
Strategic Opportunities
- Canadian Thermal Recovery Expansion:Ontario and Quebec waste-to-energy buildouts are absorbing stranded US municipal solid waste volumes as domestic landfill capacity tightens.
- Smart Collection Infrastructure:Sensor-based route optimization systems enable dynamic pricing models for commercial accounts in Sun Belt metropolitan zones.
- Hazardous Waste Technical Tier:Cradle-to-grave liability exposure for industrial end users creates defensible margin pools for specialized treatment infrastructure.
Industry Challenges
- Skilled Technician Scarcity:Leachate treatment system operators and landfill gas technicians with EPA certification command 35% wage premiums above general maintenance roles.
- Legacy Route Density Optimization:Sun Belt population dispersal patterns fragment collection efficiency compared to legacy Northeast urban cores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Waste Management Market |
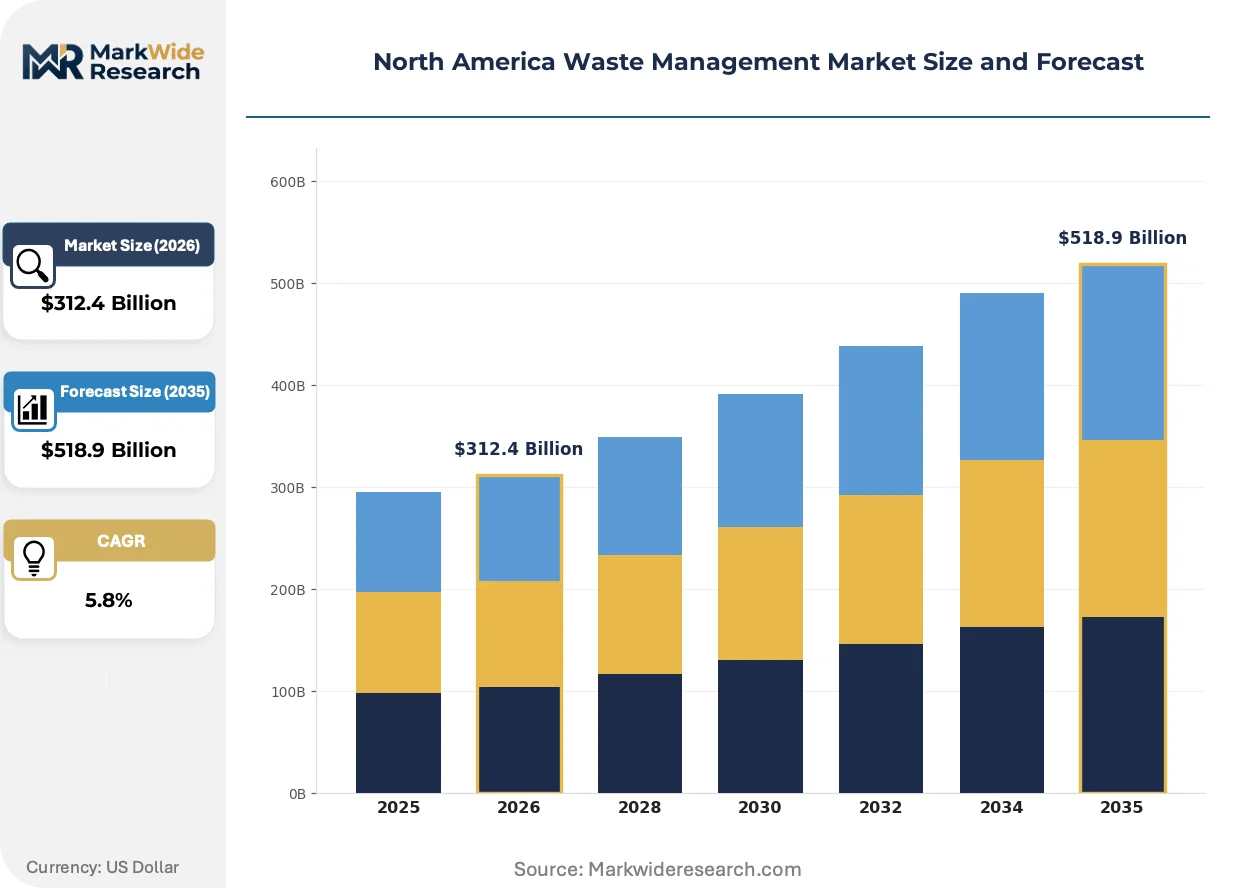
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $518.9 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Recycling, Disposal, Treatment Technology: Composting, Anaerobic Digestion, Incineration, Landfill End User: Residential, Commercial, Industrial, Institutional Waste Type: Municipal Solid Waste, Hazardous Waste, Electronic Waste, Construction Waste |
| Companies Covered | Waste Management, Inc., Republic Services, Inc., Waste Connections, Inc., Clean Harbors, Inc., Veolia North America, GFL Environmental Inc., Stericycle Inc., Covanta Holding Corporation, Casella Waste Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Waste Management Market Trends and Innovations
Digital sensor networks and thermal recovery technologies are compressing the traditional collection-landfill value chain into integrated material-energy recovery systems across North American metropolitan zones.
Anaerobic digestion with biogas upgrading to pipeline-quality renewable natural gas is absorbing organic waste streams previously routed to composting or landfill disposal. Food processors and grocery chains in California and the Pacific Northwest are contracting dedicated digestion capacity at 15-year fixed-price terms. This technology is absorbing margin from conventional landfill tipping fees while capturing methane value that regulatory frameworks now prohibit from atmospheric release.
EPA enforcement of New Source Performance Standards for landfill methane is tightening compliance timelines for existing facilities. Operators in Texas and Florida face 2026 deadlines for gas collection system expansion that will redirect capital from greenfield landfill development. The industrial waste segment is most affected, with generators now required to characterize methane potential prior to off-site disposal.
Commercial waste buyers are consolidating vendor relationships under multi-service contracts spanning collection, recycling, and energy recovery. Large retail and logistics operators in the US Southeast are bundling hazardous and non-hazardous streams with single providers to reduce administrative burden. This concentration is most visible in Atlanta and Dallas-Fort Worth metropolitan zones where national operators have achieved route density thresholds supporting dynamic pricing.
North America Waste Management Market Segmentation
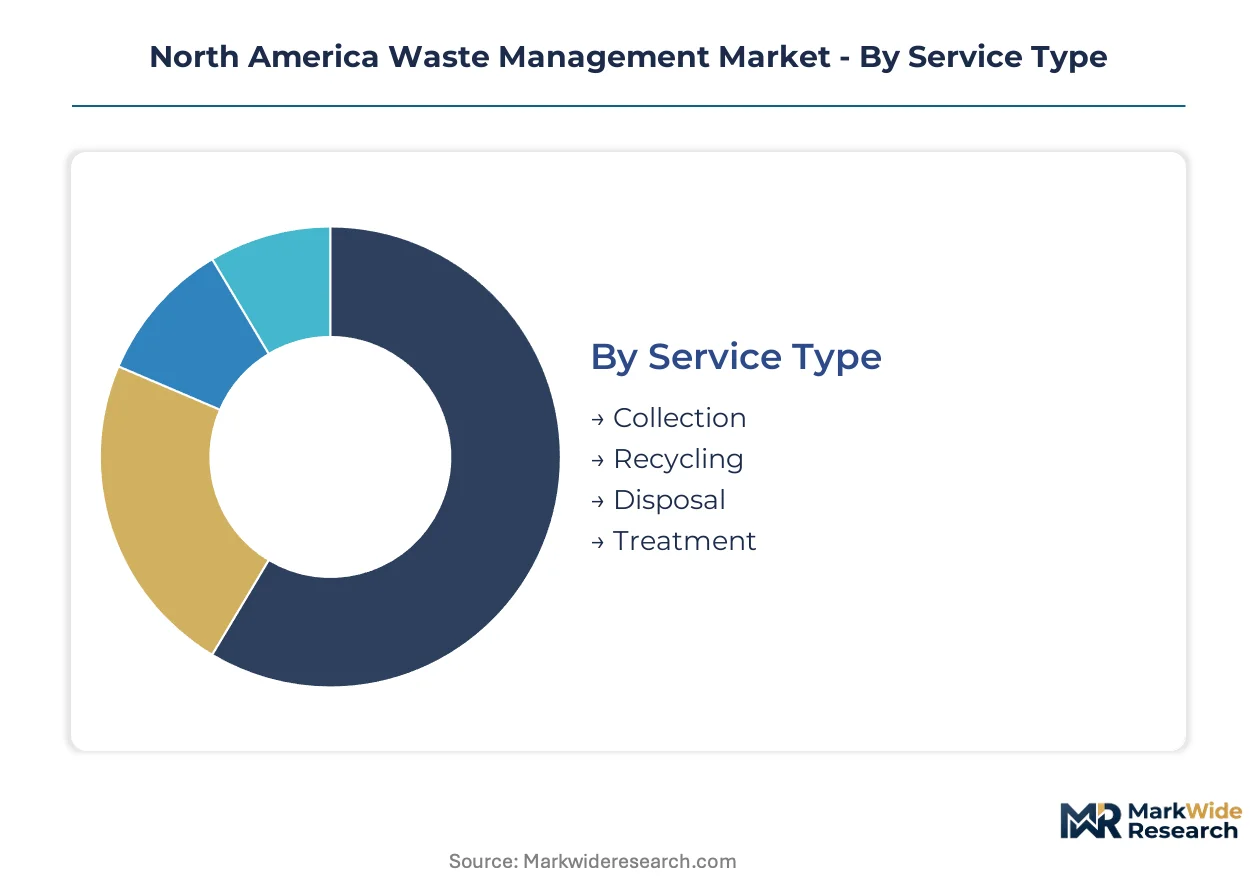
Segmentation in North American waste management reveals how capital allocation, regulatory pressure, and customer concentration create divergent margin structures across service tiers. Each axis exposes distinct competitive dynamics that shape operator specialization and geographic positioning.
Service Type:
Technology and infrastructure requirements define competitive intensity across service tiers, with capital deployment patterns varying dramatically by operational complexity.
- Collection:Recurring contracted routes generate predictable revenue streams through municipal franchise agreements and commercial account density. Sun Belt metropolitan zones concentrate new contract awards as population dispersal creates fragmented but high-volume pickup networks requiring dynamic route optimization.
- Recycling:Commodity price exposure and contamination rates compress margins despite EPR framework expansion in California and New York. MRF operators in the US Northeast corridor face acute pressure from China's National Sword policy legacy and domestic end-market scarcity for mixed paper and plastics.
- Disposal:Landfill airspace scarcity in dense metropolitan zones supports premium tipping fees, though EPA methane capture mandates redirect capital toward gas-to-energy infrastructure.
- Treatment:Specialized hazardous and medical waste processing commands defensible margins through cradle-to-grave liability structures and EPA permitting barriers.
Mature deployment sits with Collection. Newer deployment is concentrated in Treatment as industrial characterization requirements tighten.
Technology:
Capital intensity and regulatory compliance timelines segment technology adoption, with permitting duration and utility offtake contracts determining viable deployment geographies.
- Composting:Yard trimmings and food waste diversion programs in California and Pacific Northwest states absorb organic streams previously landfilled, though odor control and market development for finished compost constrain expansion.
- Anaerobic Digestion:Biogas upgrading to pipeline-quality renewable natural gas captures methane value that regulatory frameworks now prohibit from atmospheric release. Utilities in the US Northeast and Canadian provinces contract digestion output at 15-year fixed-price terms to meet decarbonization targets.
- Incineration:Waste-to-energy facilities require $200-400 million per installation, concentrating development among entities with utility-scale balance sheets. Ontario and Quebec buildouts absorb stranded US municipal solid waste volumes as domestic landfill capacity tightens.
- Landfill:Leachate containment systems engineered to 0.1 mg/L discharge thresholds demand wholesale facility upgrades across the US Northeast corridor, while Texas and Florida operators face compressed timelines for gas collection system expansion.
Capital deployment clusters in Landfill. Steepest expansion trajectory belongs to Anaerobic Digestion.
End User:
Account value and service complexity diverge sharply across customer categories, with liability exposure and waste characterization requirements determining operator specialization.
- Residential:Municipal franchise contracts provide volume stability but limit pricing flexibility, with smart collection infrastructure enabling dynamic service models in Sun Belt growth corridors.
- Commercial:Multi-service bundling of collection, recycling, and energy recovery concentrates vendor relationships under single-provider contracts in Atlanta and Dallas-Fort Worth metropolitan zones.
- Industrial:Complex hazardous characterization requirements and cradle-to-grave liability exposure generate the highest per-account value. Clean Harbors and specialized operators occupy narrow but defensible technical tiers serving chemical, pharmaceutical, and manufacturing generators.
- Institutional:Healthcare and university systems generate regulated medical waste and specialized organic streams requiring dedicated processing infrastructure and compliance documentation.
Revenue concentration favors Industrial. Volume expansion concentrates in Commercial as retail and logistics operators consolidate vendor relationships.
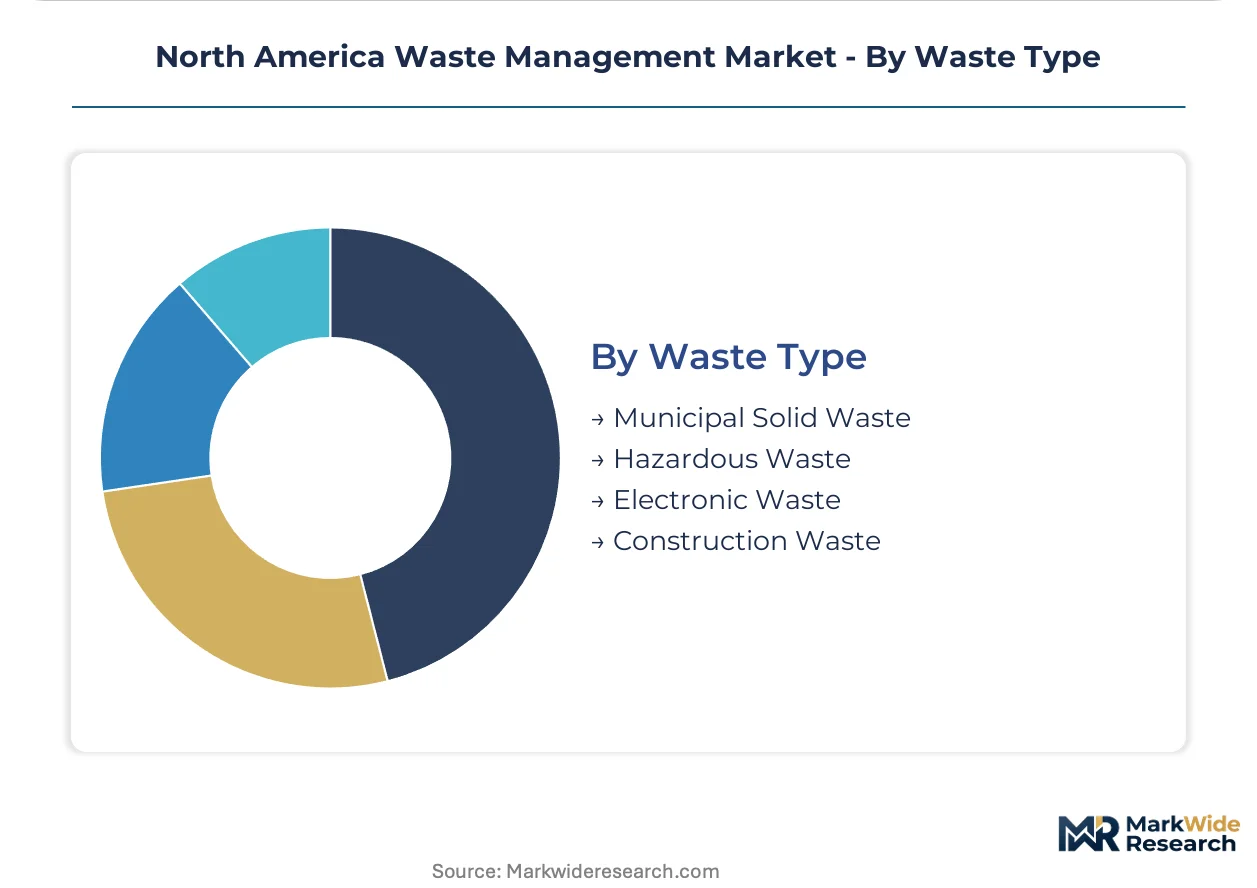
Waste Type:
Regulatory classification and disposal pathway constraints create distinct market structures, with hazardous and electronic waste segments commanding specialized handling premiums.
- Municipal Solid Waste:The baseline volume stream flows predominantly to landfill and emerging digestion capacity, with Canadian thermal recovery expansion absorbing stranded US volumes.
- Hazardous Waste:EPA and DOT joint governance of transport classification and worker exposure elevates capital requirements, creating layered compliance obligations that exclude new market entrants.
- Electronic Waste:State-level extended producer responsibility laws in New York and California shift collection financing onto brand owners, expanding contracted service volumes for certified recyclers.
- Construction Waste:Inert debris and demolition materials support higher recycling rates through concrete crushing and wood recovery, though asbestos and lead contamination require specialized abatement handling.
Processing maturity sits with Municipal Solid Waste. Regulatory pressure is accelerating fastest in Electronic Waste.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian forestry residuals and Upper Midwest agricultural feedstocks anchor North American waste-to-energy supply chains. Municipal solid waste generation concentrates along the US Northeast corridor and Ontario-Quebec industrial belt. Regulatory divergence between EPA methane mandates and provincial extended producer responsibility laws shapes cross-border processing flows.
United States
EPA New Source Performance Standards compress landfill methane compliance timelines across Texas and Florida facilities. The Infrastructure Investment and Jobs Act channels federal funding toward leachate containment upgrades in aging Northeast corridor sites. Atlanta and Dallas-Fort Worth metropolitan zones concentrate smart collection infrastructure deployment as commercial waste buyers consolidate vendor relationships.
Canada
Ontario and Quebec waste-to-energy buildouts absorb stranded US municipal solid waste volumes as domestic landfill capacity tightens. Provincial extended producer responsibility frameworks shift collection financing onto brand owners, expanding contracted service volumes. Toronto and Montreal industrial corridors anchor thermal recovery capacity expansion with utility-scale balance sheet concentration.
Mexico
Informal recycling networks dominate material recovery in Mexico City and Guadalajara metropolitan zones while formal collection infrastructure remains underdeveloped. Federal environmental regulations lack enforcement capacity equivalent to US EPA standards, creating compliance gaps for cross-border waste flows. Northern border states concentrate maquiladora industrial waste generation requiring specialized hazardous characterization.
North America Waste Management Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue anaerobic digestion and smart collection technology licensing. The market structure consolidates around three national operators with dense route networks, while regional specialists defend narrow technical tiers in hazardous and medical waste processing. Strategic archetypes include integrated landfill-gas-to-energy developers, Sun Belt route density optimizers, and cradle-to-grave liability specialists. Dominant competitive moves include multi-service contract bundling and Canadian thermal recovery capacity expansion.
Among US-based integrated operators, Waste Management, Inc. and Republic Services, Inc. exemplify scale-driven route concentration archetypes. Clean Harbors, Inc. occupies a specialized technical tier serving industrial generators with complex hazardous characterization requirements. These three entities represent distinct competitive positioning vectors within a market where capital intensity and permitting timelines exclude new entrants.
| Leading Market Players |
|---|
| Waste Management, Inc. |
| Republic Services, Inc. |
| Waste Connections, Inc. |
| Clean Harbors, Inc. |
| Veolia North America |
| GFL Environmental Inc. |
| Stericycle Inc. |
| Covanta Holding Corporation |
| Casella Waste Systems, Inc. |
| Others |
Pricing and Supply Chain Analysis
Certified hazardous handling premiums versus commodity municipal collection diverge sharply across North American operator portfolios, with EPA-permitted treatment facilities commanding 40-50% margin spreads over landfill-dependent competitors while supply chain configurations concentrate specialized equipment procurement through Upper Midwest fabrication clusters.
Pricing Analysis
Long-term service bundling with 10-15 year municipal franchise agreements anchors pricing stability, while unbundled spot-market tipping fees fluctuate with regional landfill airspace scarcity. Price differentiation rests on EPA hazardous waste certification tiers and route density optimization in Sun Belt metropolitan zones. Cost compression in recycling streams intensifies because commodity contamination erodes MRF yields. Commercial multi-service buyers show lowest price sensitivity; small residential haulers face highest sensitivity to fuel surcharge pass-throughs.
Supply Chain Analysis
Specialized leachate treatment membranes and landfill gas collection piping rest on German and Japanese industrial suppliers, with domestic fabrication concentrated in Ohio and Pennsylvania steel corridors. Raw material dependencies include high-density polyethylene geomembranes, activated carbon filtration media, and biogas upgrading catalysts. Single-source vulnerability sits with advanced membrane bioreactor systems for 0.1 mg/L discharge compliance. Distribution runs through regional equipment distributors serving municipal procurement offices and integrated operator capital programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
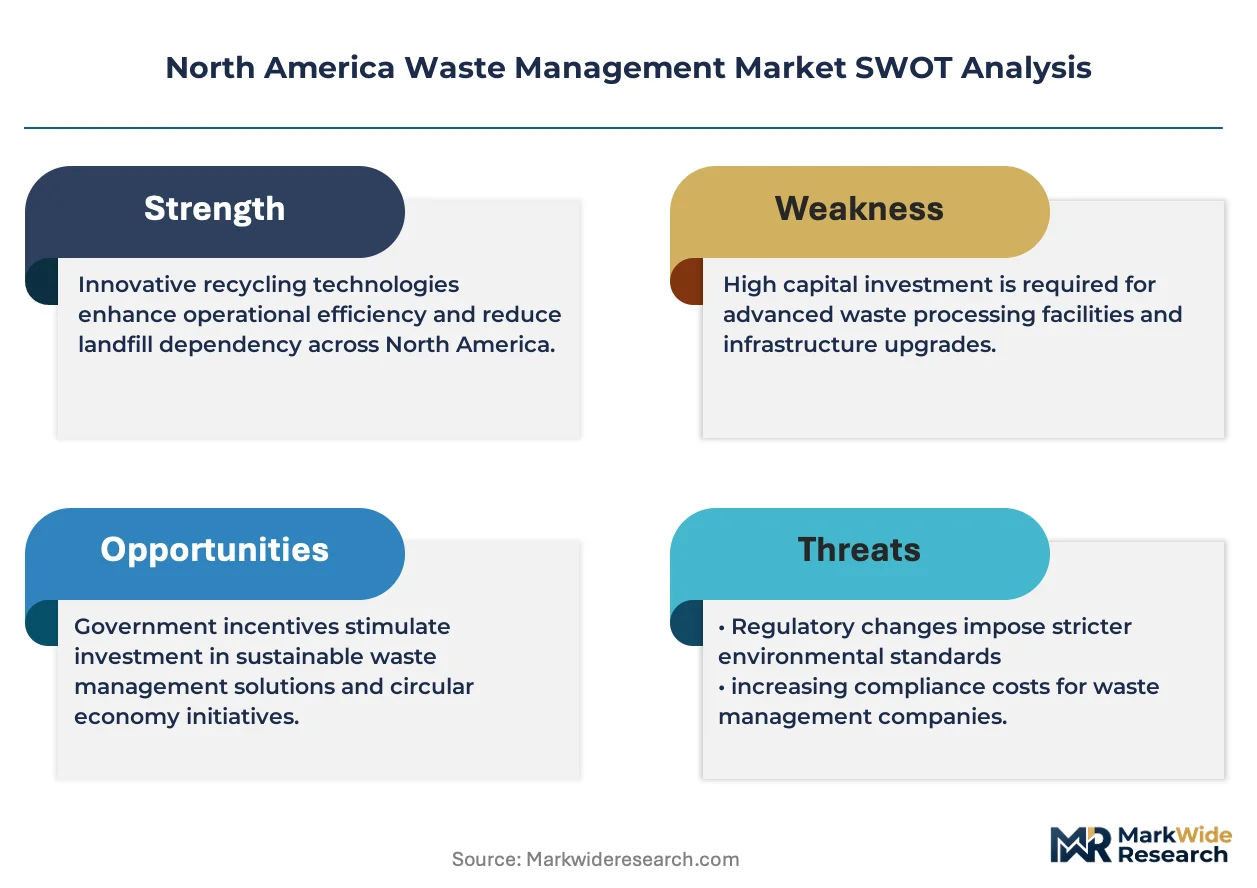
North American waste management operates as a supply-constrained market where landfill airspace scarcity in the Northeast corridor props pricing power for permitted operators despite capital intensity pressures.
For Market Incumbents: Lock in route density thresholds through municipal franchise renewals in Sun Belt growth corridors before population dispersal fragments collection efficiency. Secure anaerobic digestion offtake contracts with Northeast utilities to defend margin position against Canadian thermal recovery expansion absorbing stranded US volumes.
For New Entrants and Emerging Players: Sensor-based dynamic routing algorithms offer the most penetrable wedge for commercial account acquisition in Atlanta and Dallas-Fort Worth metropolitan zones. Target hazardous waste characterization services for industrial generators in Texas and Florida where EPA certification barriers exclude commoditized competitors. Pursue licensing partnerships with established equipment vendors rather than greenfield facility development.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized hazardous treatment operators given emerging PFAS destruction retrofit mandates accelerating consolidation. Long-term viability favors entities with utility-scale balance sheets capable of $200-400 million waste-to-energy installations. Monitor EPA enforcement timelines for landfill methane capture as the primary inflection signal for capital reallocation toward gas-to-energy infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Landfill-Gas-to-Energy Capacity Expansion | EPA New Source Performance Standards compliance redirects capital from greenfield development in Texas and Florida facilities. |
| Anaerobic Digestion Utility Partnerships | 15-year fixed-price RNG offtake contracts with Northeast utilities lock in methane value recovery from organic waste streams. |
| Smart Collection Infrastructure Deployment | Sensor-based route optimization enables dynamic pricing models for commercial accounts in Sun Belt metropolitan zones. |
| Hazardous Waste Certification Investment | EPA-permitted treatment infrastructure occupies defensible technical tiers serving chemical and pharmaceutical generators. |
| Canadian Thermal Recovery Joint Venture | Ontario and Quebec waste-to-energy buildouts absorb stranded US municipal solid waste volumes as domestic capacity tightens. |
Research Methodology
EPA enforcement databases, state regulatory filings, and municipal procurement records formed the secondary backbone, supplemented by interviews with landfill operations directors, hazardous waste facility managers, utility renewable energy procurement officers, and leachate treatment system engineers. Primary fieldwork triangulated against customs data on geomembrane imports, SEC 10-K disclosures from integrated operators, and FERC interconnection queue data for gas-to-energy projects. Bottom-up facility capacity tallies and top-down waste generation estimates were cross-validated.
Bottom-up modeling aggregated individual facility throughput, permitting status, and capital expenditure pipelines across the analysis window, while top-down approaches calibrated against EPA waste generation surveys and state-level diversion rate targets. Segmentation dimensions included service type, technology pathway, end-user category, and waste stream classification. CAGRs derived from facility-level capacity expansion announcements and utility offtake contract volumes, with sensitivity testing against methane capture compliance deadlines and EPR framework implementation timelines.
Several conditions sit outside the modeled scope, including potential federal PFAS destruction rulemaking, abrupt commodity market shifts affecting recycling economics, and unanticipated state-level landfill moratoria. Forecasts reflect documented assumptions regarding permitting timeline continuity and utility renewable natural gas demand trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Trash Rakes Market