
 Municipal Solid Waste Management Market | 2026-2036
Municipal Solid Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Municipal Solid Waste Management Market Analysis
Recycled plastics and biocomposites are restructuring container economics across collection fleets. Waste Management Inc. leverages its vertically integrated hauling and landfill network to capture margin across the entire service chain. Republic Services Inc. anchors its competitive position through dense route concentration in Sun Belt metros. Veolia North America differentiates via advanced anaerobic digestion facilities that process organic streams into renewable natural gas.
Municipal solid waste management encompasses the systematic collection, transportation, processing, recycling, and disposal of refuse generated by households, commercial establishments, and institutions, typically involving material streams with calorific values ranging from 8 to 12 MJ per kilogram and moisture content between 20 and 50 percent depending on regional diet and climate patterns. The primary purpose is to safeguard public health, minimize environmental contamination, and recover embedded energy and materials for return to productive use. Collection services dominate revenue volume due to their labor-intensive, recurring nature and essential utility status, while anaerobic digestion represents the fastest-expanding technology segment as utilities and industrial offtakers seek decarbonized biogas supply. Commercial enterprises constitute a concentrated margin pool because their waste streams offer more predictable composition and higher recovery value than residential sources.
The US EPA landfill methane regulations, EU Waste Framework Directive recycling targets, and China's MEE solid waste import restrictions collectively shape facility investment priorities, technology selection, and cross-border material flows. Compliance with these frameworks determines market access, operating permits, and eligibility for green financing instruments. Stakeholders must monitor regulatory tightening on methane emissions and extended producer responsibility schemes, as these mechanisms will determine which technology configurations and service models capture disproportionate value in the next planning cycle.
Market Dynamics
EU Green Deal circular economy mandates are redirecting capital flows from landfill infrastructure toward anaerobic digestion and composting facilities, compressing traditional disposal margins while elevating integrated waste-to-energy operators.
Growth Catalysts
- Feed-in Tariff Structures:Germany's renewable energy compensation mechanisms for biogas injection into natural gas grids have created Europe's most advanced integrated waste-to-energy cluster, attracting equipment vendors and project financiers.
- Smart City Sensor Deployment:Urban municipalities are accelerating sensor-based collection optimization, reducing fleet fuel consumption and labor hours through dynamic routing algorithms triggered by fill-level monitors.
- Landfill Diversion Targets:The EU Waste Framework Directive's binding recycling targets are forcing member states to construct alternative processing capacity, directly stimulating anaerobic digestion and mechanical-biological treatment investments.
Market Restraints
- Digestate Market Saturation:Germany's advanced anaerobic digestion sector faces localized digestate oversupply, depressing output prices and threatening project economics for new facility developments.
- Collection Labor Scarcity:Dense metropolitan areas in the United States confront persistent driver shortages for commercial hauling fleets, constraining route expansion and service density improvements.
- Contamination Rate Volatility:Single-stream recycling programs generate unpredictable feedstock quality, damaging sorting equipment and degrading recovered commodity values at materials recovery facilities.
Strategic Opportunities
- Industrial RNG Offtake Contracts:Utilities and transportation fleets seeking decarbonized fuel supply are signing long-term renewable natural gas purchase agreements, de-risking anaerobic digestion project finance.
- Sensor-Route Convergence:Integration of IoT fill sensors with predictive analytics platforms is opening subscription-based service models for municipalities seeking to outsource collection optimization.
- Extended Producer Responsibility Expansion:Packaging waste regulations across EU member states are shifting financial responsibility upstream to brand owners, creating fee-based compliance services for waste management operators.
Industry Challenges
- Mechanical Sorting Technician Shortage:Advanced materials recovery facilities require skilled operators for optical and robotic sorting lines, but vocational training pipelines remain underdeveloped relative to deployment timelines.
- Legacy Fleet Electrification Costs:Collection vehicle electrification demands substantial charging infrastructure investment and depot electrical upgrades, straining municipal capital budgets and procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Municipal Solid Waste Management Market |
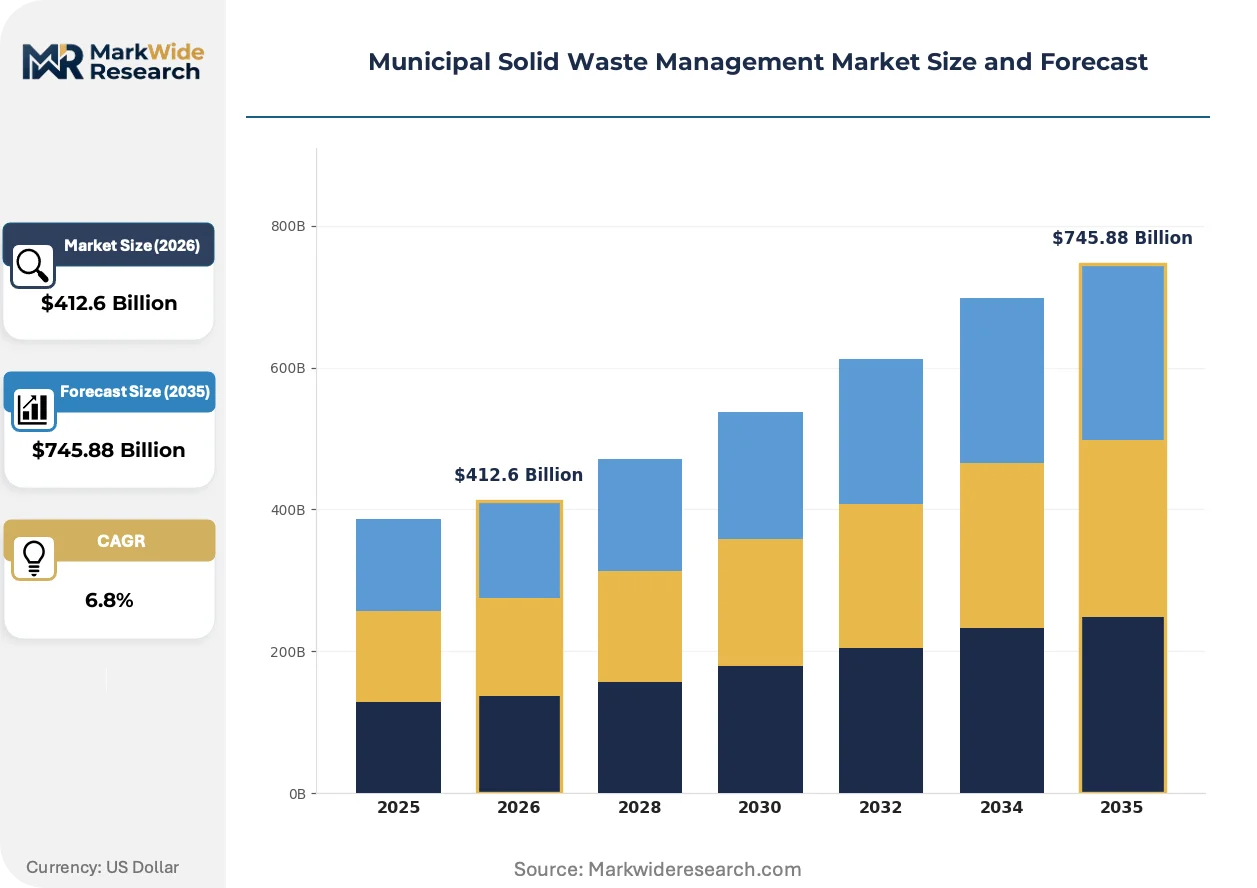
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $745.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Transportation, Recycling, Disposal Technology: Composting, Anaerobic Digestion, Incineration, Landfilling End User: Households, Municipalities, Commercial Enterprises, NGOs Waste Type: Organic Waste, Plastic Waste, E-Waste, Hazardous Waste |
| Companies Covered | GFL Environmental Inc., Casella Waste Systems Inc., Waste Management Inc., Stericycle Inc., Clean Harbors Inc., Republic Services Inc., Veolia North America, Covanta Holding Corporation, Waste Connections Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Municipal Solid Waste Management Market Emerging Trajectories
Digitalization of collection logistics and biological processing automation are compressing operating margins for conventional operators while creating premium service tiers for technology-advantaged competitors.
Optical sorting systems paired with artificial intelligence classification algorithms are overtaking manual picking stations at materials recovery facilities. European operators in the Netherlands and Belgium have achieved near-total automation of container streams, reducing headcount per ton processed by over half. This compression of labor inputs is enabling 24-hour processing cycles and higher purity in recovered paper and plastic fractions.
The EU Green Deal's methane reduction targets are accelerating landfill gas capture retrofits across member states with older disposal sites. Operators in France and Italy face binding emission reduction schedules that require immediate capital deployment into gas collection wellfields and flaring infrastructure. Compliance deadlines are compressing project timelines and elevating engineering contractor utilization rates.
Commercial waste generators are consolidating vendor relationships around integrated service providers capable of handling collection, processing, and sustainability reporting through single contracts. Large retail and food service chains in Germany and the United States now demand consolidated waste diversion data for corporate ESG disclosures. This bundling preference is squeezing specialized haulers and elevating full-service operators with in-house processing assets.
Municipal Solid Waste Management Market Segmentation
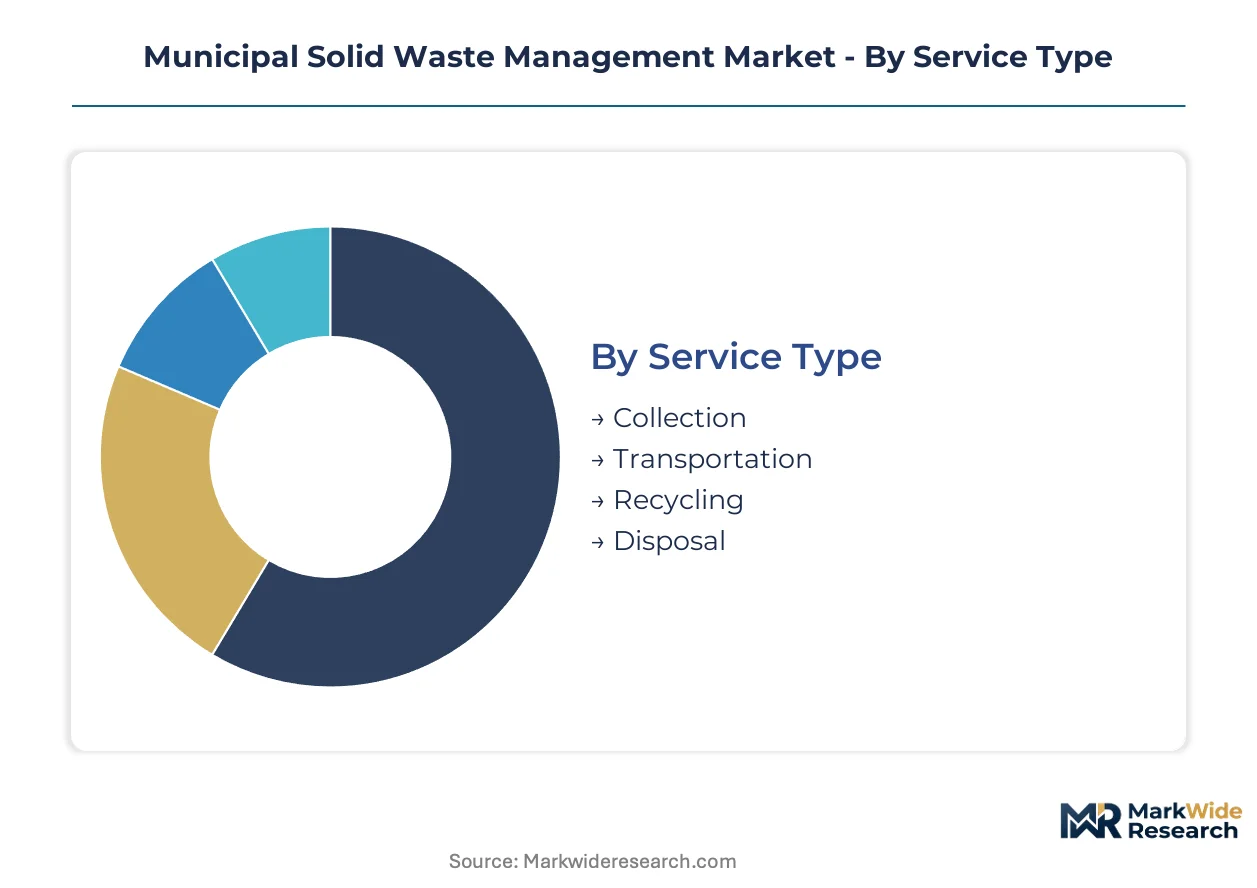
Segmentation in municipal solid waste management reveals distinct capital requirements, regulatory exposure, and margin profiles across service models and processing technologies. Understanding these divisions enables operators to align asset deployment with regional infrastructure gaps and policy incentives.
Service Type:
Capital intensity varies sharply across this dimension, with fixed infrastructure segments demanding substantially higher upfront investment than fleet-based operations.
- Collection:Labor-intensive recurring services utilizing specialized compacting vehicles and container fleets. Dense route concentration in Sun Belt metros and German urban corridors generates the strongest margin pools as fuel and labor optimization technologies mature.
- Transportation:Long-haul logistics connecting collection nodes to processing facilities, typically involving transfer station infrastructure and rail or barge intermodal capacity. The EU Waste Framework Directive's landfill diversion mandates are accelerating investment in dedicated organic waste transport corridors linking urban generators to rural digestion facilities.
- Recycling:Materials recovery facilities employing optical sorting and robotic separation systems. Contamination rate volatility from single-stream programs degrades equipment performance and recovered commodity values.
- Disposal:Landfill operations with gas capture infrastructure and leachate management systems. US EPA methane regulations and EU emission reduction schedules are compressing project timelines for retrofit investments.
Most installed capacity flows through Collection. Expansion is steepest in Recycling as extended producer responsibility schemes shift financial responsibility upstream.
Technology:
Technology selection determines regulatory compliance positioning, energy recovery potential, and residual liability exposure across operating portfolios.
- Anaerobic Digestion:Biological processing of organic streams into biogas and digestate, requiring enclosed reactor vessels and gas upgrading equipment. Germany's feed-in tariff structures have created Europe's most advanced integrated cluster, though localized digestate oversupply now threatens project economics.
- Composting:Aerobic decomposition of organic waste into soil amendments, involving windrow or in-vessel systems with odor and leachate controls. French and Italian operators face binding EU methane reduction deadlines that favor composting retrofits at older facilities.
- Incineration:Thermal treatment with energy recovery through steam turbine generation. Air emission controls and residual ash management dominate capital allocation decisions.
- Landfilling:Engineered disposal with liner systems, leachate collection, and gas extraction infrastructure. EU Green Deal circular economy mandates are redirecting capital flows away from greenfield landfill development.
Processing volume concentrates in Landfilling. Biological alternatives are climbing the fastest as renewable natural gas offtake contracts de-risk anaerobic digestion project finance.
End User:
Customer type shapes contract structure, service predictability, and sustainability reporting requirements across municipal and commercial relationships.
- Commercial Enterprises:Retail and food service chains generating predictable, high-value waste streams with consolidated vendor preferences. Large German and US operators now demand bundled diversion data for corporate ESG disclosures.
- Municipalities:Local government contracts for residential collection and processing, typically awarded through competitive bidding with extended terms. Smart city sensor deployments are enabling subscription-based optimization services.
- Households:Individual residential generators served through municipal systems or private subscription models. Collection labor scarcity in dense US metropolitan areas constrains service density improvements.
- NGOs:Non-governmental organizations operating community-based collection and recycling programs, often in informal sector contexts with limited capital access.
Contract value pools deepest with Commercial Enterprises. Municipality technology upgrades are expanding most quickly through IoT-enabled collection optimization.
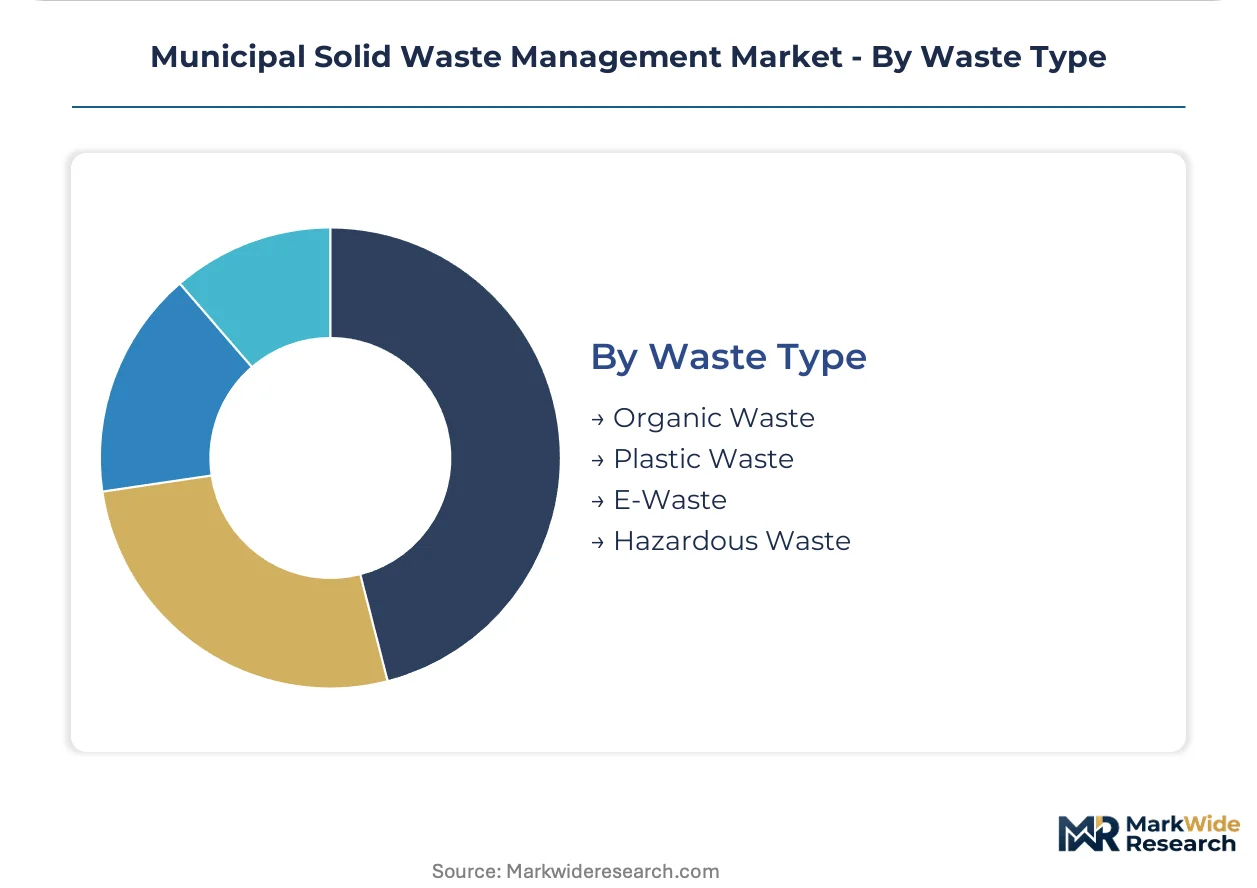
Waste Type:
Material composition dictates processing technology compatibility, recovery economics, and regulatory handling requirements across inbound streams.
- Organic Waste:Biodegradable fractions including food scraps and yard trimmings with calorific values of 8-12 MJ per kilogram. EU landfill diversion targets and biogas feed-in tariffs are concentrating processing investment in Germany and France.
- Plastic Waste:Synthetic polymers requiring sorting, cleaning, and reprocessing infrastructure. China's MEE solid waste import restrictions have reshaped cross-border material flows and domestic sorting capacity needs.
- E-Waste:Discarded electronics containing recoverable metals and regulated hazardous components. Extended producer responsibility frameworks are shifting collection financing to brand owners.
- Hazardous Waste:Materials requiring specialized handling, treatment, and disposal under strict regulatory protocols. Permitting complexity limits competitive entry and sustains premium pricing.
Tonnage volumes flow heaviest through Organic Waste. E-Waste recovery infrastructure is gaining share fastest as electronics consumption cycles compress and metal recovery economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's integrated waste-to-energy cluster around Munich and Stuttgart anchors the industry's most advanced processing infrastructure. The EU Green Deal's circular economy mandates are redirecting capital flows across member states, while feed-in tariff structures concentrate biogas investment in specific national markets.
United States
Commercial hauling fleets in Sun Belt metros face persistent driver shortages constraining route expansion. US EPA landfill methane regulations are compressing project timelines for gas capture retrofits at older disposal sites. Dense metropolitan clusters in Texas and Florida are consolidating vendor relationships around integrated service providers.
Germany
Renewable energy compensation mechanisms for biogas injection have created Europe's most advanced integrated waste-to-energy cluster. The EU Waste Framework Directive's binding recycling targets are forcing construction of alternative processing capacity. Equipment vendors and project financiers concentrate around Munich, Stuttgart, and the Rhine-Ruhr corridor.
France
Binding EU methane reduction schedules are accelerating landfill gas capture investments at older disposal sites. French operators face immediate capital deployment requirements into gas collection wellfields and flaring infrastructure. Engineering contractor utilization rates are elevating across the Paris Basin and Lyon industrial corridor.
China
MEE solid waste import restrictions have reshaped cross-border material flows and domestic sorting capacity needs. Smart city sensor deployments are accelerating in tier-one municipalities for collection optimization. Yangtze River Delta cities are piloting dynamic routing algorithms triggered by fill-level monitors.
United Kingdom
Extended producer responsibility schemes for packaging waste are shifting financial responsibility upstream to brand owners. London and Southeast England operators are developing fee-based compliance services for consolidated waste diversion data. Materials recovery facilities in the Midlands face contamination rate volatility from single-stream programs.
Municipal Solid Waste Management Market Vendor Landscape
Strategic partnerships dominate the current landscape as operators seek to bundle collection, processing, and sustainability reporting capabilities. The vendor base concentrates around integrated full-service providers with in-house processing assets, while specialized haulers face margin compression. Three archetypes define competitive positioning: vertically integrated majors with landfill and digestion networks, regional specialists with dense route concentration, and technology-forward operators with advanced sorting infrastructure. M&A activity and capacity expansion in anaerobic digestion represent the dominant competitive moves.
Among North American integrated providers, Waste Management Inc., Republic Services Inc., and Waste Connections Inc. exemplify the scale-driven archetype with broad geographic coverage and captive disposal infrastructure. GFL Environmental Inc. and Casella Waste Systems Inc. represent regional specialists with concentrated route density in specific metropolitan corridors. Veolia North America anchors the technology-forward tier through European parent-company transfer of anaerobic digestion expertise.
| Leading Market Players |
|---|
| GFL Environmental Inc. |
| Casella Waste Systems Inc. |
| Waste Management Inc. |
| Stericycle Inc. |
| Clean Harbors Inc. |
| Republic Services Inc. |
| Veolia North America |
| Covanta Holding Corporation |
| Waste Connections Inc. |
| Others |
Supply Flow & Price Mechanics
Municipal procurement offices in dense German urban corridors anchor pricing power for integrated collection and processing contracts, locking in long-term service agreements that compress margins for standalone haulers competing on spot rates.
Pricing Analysis
Input-cost pass-through from diesel fuel and specialized vehicle chassis dominates contract renegotiation cycles. Three-tier pricing structure across premium technology-enabled, standard integrated, and economy disposal-only levels differentiates operators. Cost compression in economy-tier landfilling is intensifying because EU Green Deal diversion mandates strand residual capacity. Commercial enterprises show least price sensitivity due to bundled ESG reporting requirements, while small municipalities exhibit highest sensitivity to per-ton tipping fees.
Supply Chain Analysis
Freight costs for organic waste transport from urban generators to rural digestion facilities consume disproportionate margin in collection-dense corridors. Equipment manufacturing concentrates in Germany, the United States, and China. Supply chains draw from specialized compacting vehicle chassis, optical sorting components, and biogas upgrading membranes. Single-source vulnerability around German-engineered digester vessels creates bottleneck risk. Distribution runs through municipal procurement channels and commercial waste broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Germany's feed-in tariff-supported biogas premium and France's methane compliance-driven landfill retrofit urgency.
For Market Incumbents: Anticipate margin compression from sensor-based route optimization vendors by consolidating municipal contracts into multi-service bundles. Backward integration into anaerobic digestion capacity in the Rhine-Ruhr corridor captures renewable natural gas offtake premiums before digestate saturation spreads. For New Entrants and Emerging Players: Enter via commercial food service chains in Texas and Florida metros, where driver scarcity has incumbents ceding service density. White-space concentration sits with subscription-based IoT collection optimization for mid-sized municipalities lacking in-house analytics capability. For Investors and Strategic Acquirers: European utilities seeking decarbonized fuel supply are the most active acquirer in this space, prioritizing anaerobic digestion platforms with secured feedstock agreements. Target regional specialists with dense route concentration in Sun Belt corridors. Watch for digestate market saturation spreading beyond Germany as the inflection signal for project finance risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Anaerobic Digestion Capacity Expansion | Secures renewable natural gas offtake contracts with utilities seeking decarbonized supply. |
| Sensor-Route Integration Partnership | Enables subscription-based optimization services for municipalities outsourcing collection logistics. |
| Extended Producer Responsibility Compliance Service | Captures fee-based revenue from brand owners facing EU packaging waste regulations. |
| Landfill Gas Capture Retrofit | Addresses binding EU methane reduction deadlines at older French and Italian disposal sites. |
| Commercial Account Consolidation | Bundles collection, processing, and ESG reporting for retail chains seeking single-vendor relationships. |
Methodological Framework
Bottom-up municipal procurement modeling reconciled against top-down waste generation tracking forms the analytical core of this study. Primary interviews with collection fleet managers, anaerobic digestion facility operators, municipal sustainability officers, and commercial waste brokers were validated against EPA landfill data, EU Waste Framework Directive implementation reports, German biogas association statistics, and SEC 10-K disclosures from integrated providers. Triangulation between generator-reported volumes and processor-reported throughput ensures consistency.
Input-output matrices map waste stream composition through processing technology configurations across the projection horizon. Segmentation dimensions include service type, technology selection, end-user category, and waste material composition. CAGRs derive from facility capacity buildout pipelines and contract renewal velocity. Forecast inputs incorporate feed-in tariff adjustment schedules and landfill diversion target enforcement timelines.
Inputs from regulatory filing databases and trade association statistics were available through the study window; gaps in informal sector collection volumes introduce uncertainty bands around developing economy estimates. Forecasts reflect documented assumptions about policy continuity and technology cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Waste Management Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Singapore Waste Management Market