
 Vietnam Waste Management Market | 2026-2036
Vietnam Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Waste Management Market Analytics
Southern Vietnam is rewriting the competitive map for waste services as industrial zone expansion near Long An and Dong Nai multiplies collection volumes. Vietnam Waste Solutions leverages its southern hub network to anchor hazardous waste contracts with electronics manufacturers. CITENCO sustains dominance in municipal collection across Ho Chi Minh City through long-term service concessions. INSEE Ecocycle differentiates via co-processing technology leadership in cement kiln waste recovery.
Vietnam waste management encompasses the systematic handling, treatment, and disposal of solid and liquid refuse streams through engineered processes including mechanical sorting, thermal oxidation, and biological decomposition, with facility designs typically specifying leachate containment systems and emission control thresholds. The sector serves industrial compliance, public health protection, and material recovery objectives for a manufacturing-intensive economy. Recycling services command widening margin pools as Extended Producer Responsibility frameworks tighten material recovery obligations for packaging and electronics. Waste-to-Energy installations represent the fastest-expanding technology segment, driven by landfill capacity constraints near major urban centers. Collection services remain the most mature category, with price competition intensifying in provincial municipalities outside the two primary metropolitan zones.
The Ministry of Natural Resources and Environment shapes market access through environmental impact assessments and landfill operating permits, while provincial People's Committees control service concession awards that determine regional competitive boundaries. National technical standards on solid waste classification, issued under the Law on Environmental Protection, mandate source separation protocols that alter collection logistics and equipment specifications. Stakeholders must monitor how circular economy decrees reshape material recovery obligations across manufacturing supply chains.
Market Dynamics
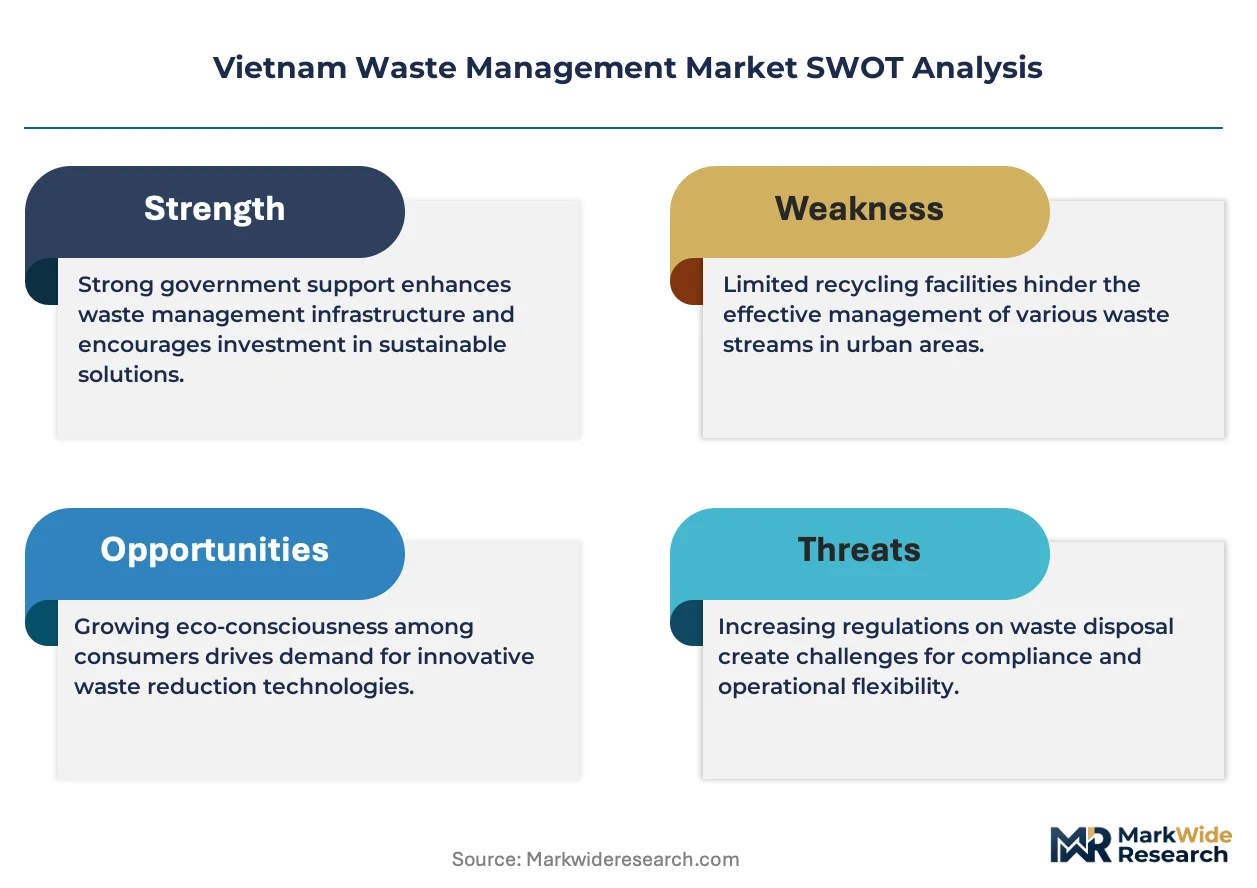
The Ministry of Natural Resources and Environment is compressing landfill capacity through stricter leachate containment mandates, forcing operators toward thermal oxidation and biological treatment infrastructure.
Growth Catalysts
- Extended Producer Responsibility mandates:Packaging and electronics manufacturers now bear material recovery obligations, expanding fee-based collection services and recycling throughput requirements.
- Ho Chi Minh City industrial clustering:Electronics and textile manufacturing concentration generates hazardous waste streams requiring specialized handling certifications.
- Waste-to-Energy technology maturation:Incineration with energy recovery addresses landfill scarcity near dense urban centers while producing grid-connectable power.
Market Restraints
- Land acquisition constraints:Greenfield landfill development faces mounting resistance in the Red River Delta agricultural zones.
- Imported equipment dependency:Sorting lines and emission control systems rely on European and Japanese suppliers, exposing operators to currency volatility.
- Technical limitation in mixed plastic sorting:Multi-layer packaging and contaminated films resist mechanical separation at commercial scale.
Strategic Opportunities
- Central Highlands underpenetration:Da Lat and Pleiku municipalities lack integrated collection networks, creating first-mover concession potential.
- Cement kiln co-processing convergence:Hazardous waste fuel substitution meets cement sector decarbonization targets while diverting materials from landfills.
- Digital payment integration:Mobile wallet adoption enables household-level waste fee collection in previously cash-dominated provincial markets.
Industry Challenges
- Hazardous waste chemist scarcity:Certified laboratory personnel for toxic characterization remain concentrated in Hanoi and Ho Chi Minh City.
- Legacy collection fleet integration:Compactor trucks with incompatible hydraulic systems complicate standardized maintenance protocols across merged municipal contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Waste Management Market |
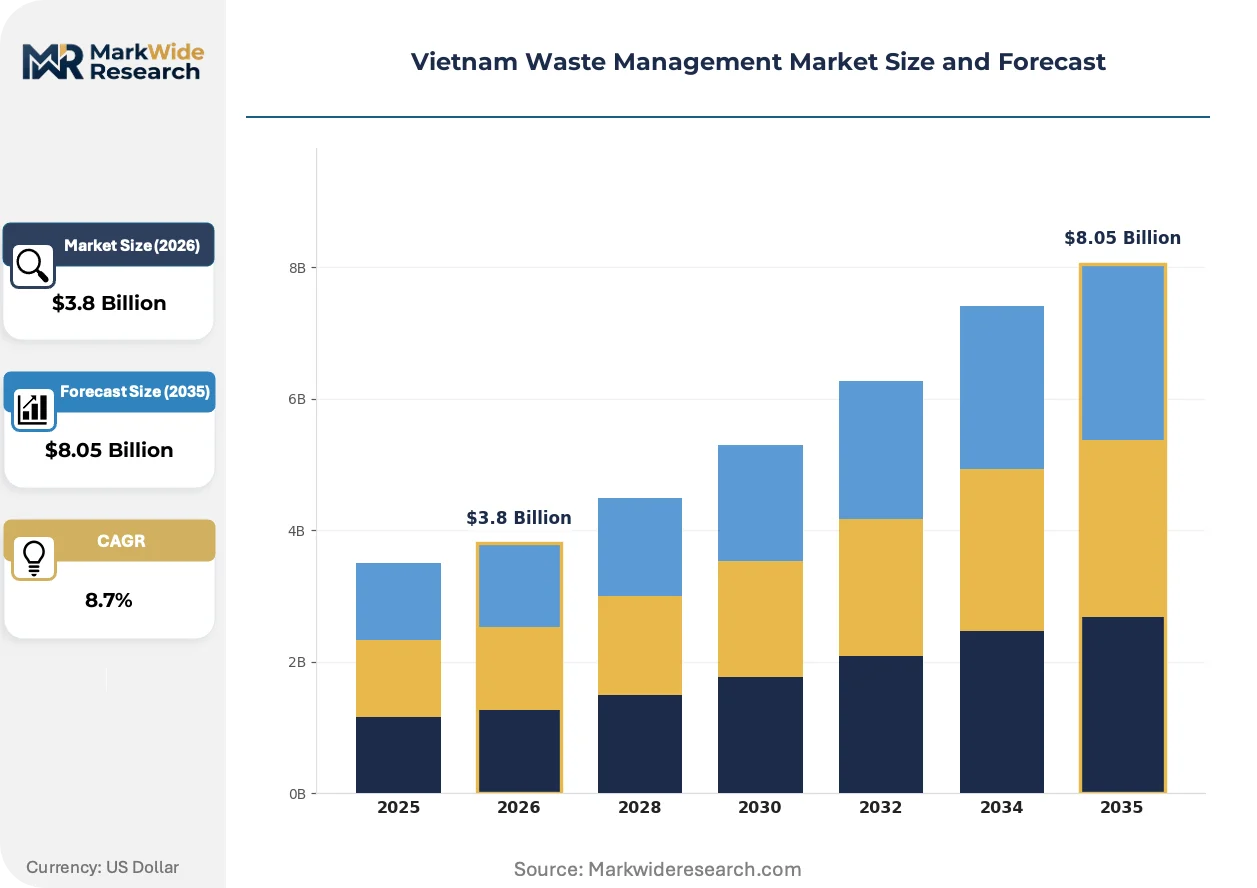
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Recycling, Landfill, Incineration Waste Type: Household Waste, Industrial Waste, Hazardous Waste, E-Waste Technology: Composting, Anaerobic Digestion, Waste-to-Energy, Mechanical Biological Treatment End User: Municipalities, Construction, Healthcare, Manufacturing |
| Companies Covered | Vietnam Waste Solutions, Green Environment Production Services Trade Co Ltd, CITENCO, Vietnam Australia Environment JSC, Vietstar Environment, URENCO (Urban Environment Company Hanoi), SGS Vietnam, Dai Lam Son Co Ltd (DALASO), INSEE Ecocycle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Waste Management Market Evolving Landscape
Mechanical sorting automation and thermal treatment scaling are compressing traditional manual collection margins while regulatory enforcement tightens material traceability requirements.
Optical sorting systems employing near-infrared detection and artificial neural networks are collapsing the cost differential between virgin and post-consumer resin feedstocks. Electronics assembly plants in Bac Ninh and Hai Phong are adopting these systems to meet brand owner recycled content specifications. The technology is collapsing secondary material price volatility by standardizing output quality previously dependent on manual labor consistency.
Vietnam's revised Law on Environmental Protection mandates source separation at household level, with provincial People's Committees issuing implementation decrees through 2025. Industrial parks must now operate centralized waste exchanges matching generator outputs with processor inputs. Electronics and automotive component manufacturers face the steepest compliance timelines due to hazardous substance disclosure requirements.
Brand owners are consolidating vendor relationships around integrated service providers offering collection, treatment, and recovery verification through single contracts. Electronics exporters serving EU markets prioritize processors with EMAS-equivalent certification over price-competitive local alternatives. This concentration is most pronounced in the northern industrial corridor where Samsung and LG supply chain audits drive supplier selection criteria.
Vietnam Waste Management Market Segmentation
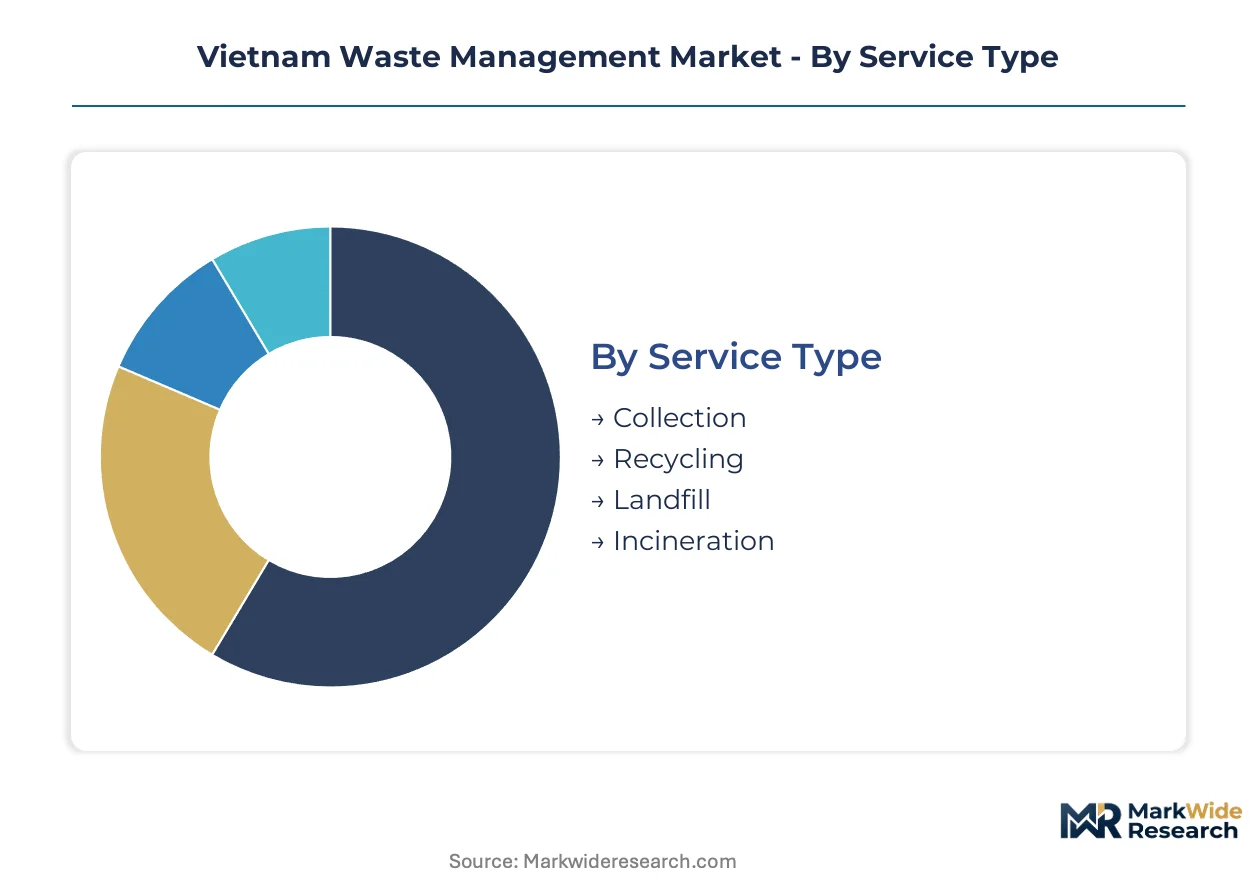
Waste service configurations in Vietnam diverge sharply between dense urban corridors and dispersed provincial markets, with technology choices constrained by landfill availability and regulatory enforcement capacity. Segment boundaries shift as Extended Producer Responsibility obligations force manufacturers into direct contracting relationships previously mediated by municipal collection networks.
Service Type:
Service configurations span from labor-intensive street collection to capital-intensive thermal treatment, with margin structures inversely related to regulatory compliance complexity.
- Collection:Compactor trucks and containerized bin systems dominate Ho Chi Minh City and Hanoi, where municipal concessions lock in decade-long operator relationships. Provincial municipalities outside these cores rely on fragmented informal networks that resist standardization.
- Recycling:Post-consumer material recovery concentrates in craft villages near Hanoi, where manual sorting of plastics and metals supplies regional reprocessing mills. Quality inconsistency limits feedstock acceptance by export-oriented manufacturers.
- Landfill:Engineered containment with leachate collection systems faces capacity exhaustion in the Red River Delta, forcing waste transfer to distant southern sites.
- Incineration:Grate combustion and rotary kiln configurations serve industrial parks generating consistent high-calorific refuse streams.
Established volume favors Collection; emerging adoption favors Recycling.
Waste Type:
Generator categories determine handling protocols, with hazardous streams requiring certified transport and treatment infrastructure concentrated in industrial zones.
- Household Waste:Mixed organic and packaging material dominates tonnage flows, with source separation mandates under the Law on Environmental Protection altering collection logistics. Ho Chi Minh City households generate the highest per-capita volumes nationally.
- Industrial Waste:Textile dye sludge and electronics assembly scrap require specialized handling certifications that concentrate supply relationships with Vietnam Waste Solutions and CITENCO. Dong Nai and Binh Duong provinces generate the densest flows.
- Hazardous Waste:Toxic characterization and manifest tracking obligations restrict transport to licensed carriers with laboratory verification capacity.
- E-Waste:Circuit boards and battery assemblies contain recoverable precious metals alongside regulated hazardous substances.
Household Waste commands dominant tonnage; E-Waste shows the steepest expansion trajectory.
Technology:
Treatment technology selection hinges on waste calorific value, moisture content, and end-product specifications for energy or compost output.
- Waste-to-Energy:Incineration with grid-connected electricity generation addresses landfill scarcity near Ho Chi Minh City while meeting cement sector decarbonization targets through co-processing arrangements. INSEE Ecocycle anchors this segment with cement kiln integration.
- Composting:Windrow and in-vessel aerobic decomposition processes agricultural and food waste into soil amendments for Mekong Delta rice cultivation.
- Anaerobic Digestion:Biogas capture from organic waste streams supplies captive energy for industrial park operations.
- Mechanical Biological Treatment:Combined sorting and biological stabilization reduces landfill-bound material volume while recovering secondary commodities.
Composting retains cost advantage for rural applications; Waste-to-Energy gains policy preference near urban centers.
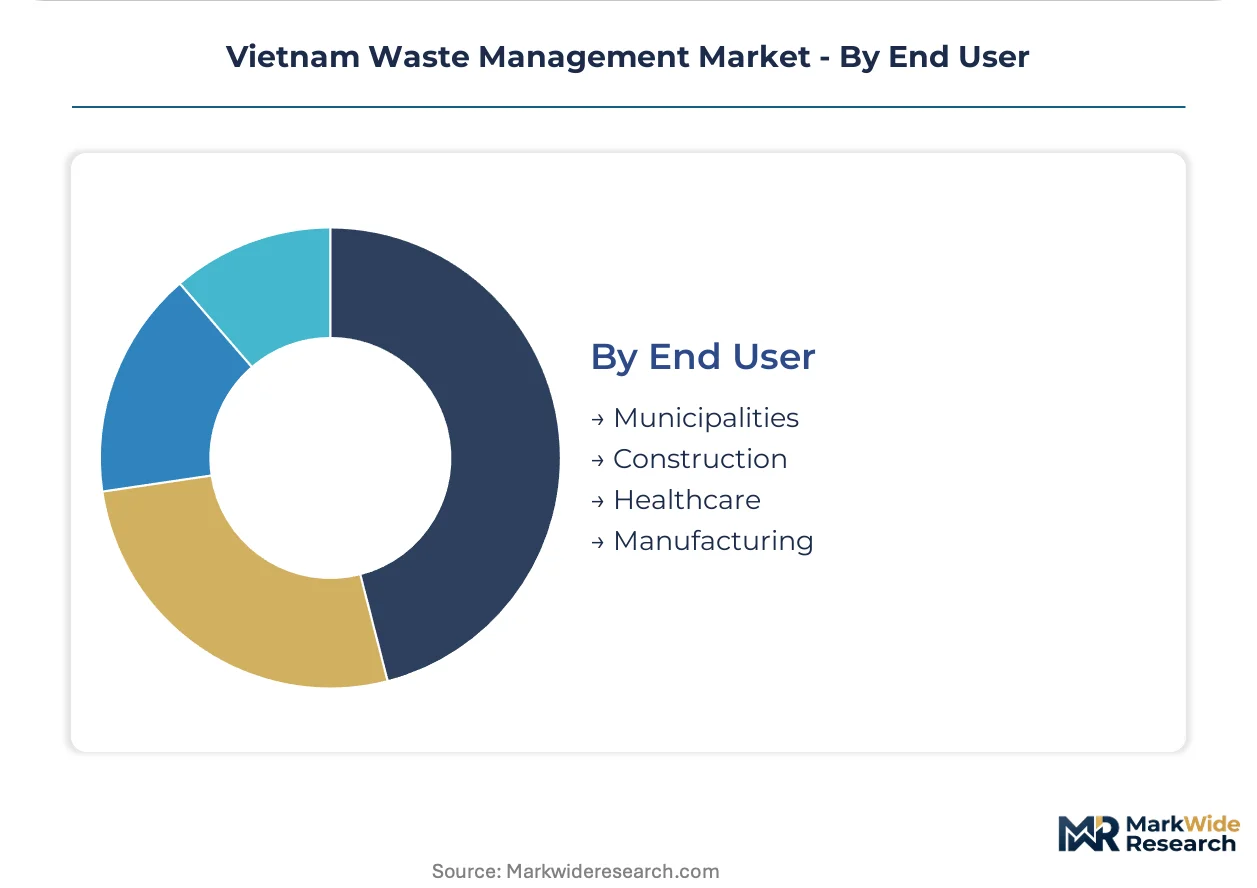
End User:
Customer procurement patterns range from municipal budget cycles to industrial compliance mandates, with payment security varying accordingly.
- Municipalities:Provincial People's Committees award service concessions through competitive bidding, with Ho Chi Minh City and Hanoi representing the most contractually sophisticated clients. Revenue stability depends on household fee collection rates.
- Manufacturing:Electronics and automotive component producers face supply chain audit requirements from EU and US brand owners, prioritizing processors with EMAS-equivalent certification over price-competitive alternatives.
- Construction:Demolition debris and excavation spoil require disposal site coordination with limited environmental controls.
- Healthcare:Infectious waste sterilization and sharps containment obligations concentrate demand around major hospital clusters.
Municipalities provide baseline volume; Manufacturing drives premium service specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Waste service configurations diverge sharply across Vietnamese sub-regions, with southern industrial corridors prioritizing hazardous waste handling while northern metropolitan zones emphasize source separation compliance and landfill containment upgrades.
Ho Chi Minh City and Surrounding Industrial Provinces
Electronics manufacturing clusters in Binh Duong and Dong Nai generate concentrated hazardous waste streams requiring specialized transport and treatment infrastructure. The Ministry of Natural Resources and Environment mandates manifest tracking for toxic characterization through licensed carriers. Vietnam Waste Solutions anchors its southern hub network here, securing long-term contracts with semiconductor and textile dyeing facilities.
Hanoi and Red River Delta Corridor
Municipal collection concessions dominate revenue flows, with URENCO maintaining service relationships across the capital's dense urban wards. The Law on Environmental Protection requires household-level source separation protocols, altering logistics for compactor truck fleets. Craft villages in Bac Ninh and Hai Duong provinces concentrate manual sorting operations for plastics and metals feeding regional reprocessing mills.
Mekong Delta Agricultural Zone
Organic waste volumes from rice cultivation and aquaculture processing drive composting facility deployment across Can Tho and An Giang provinces. Provincial People's Committees award concessions for windrow and in-vessel aerobic decomposition systems. Leachate containment standards under revised environmental protection laws force upgrades to existing landfill engineering.
Central Highlands and Coastal Provinces
Da Lat and Pleiku municipalities lack integrated collection networks, creating first-mover opportunities for concession bidding. The Ministry of Natural Resources and Environment is tightening landfill operating permits, restricting greenfield development in agricultural zones. Tourism-driven waste generation in Da Nang and Nha Trang concentrates demand around hospitality sector collection contracts.
Northern Industrial Corridor
Samsung and LG supply chain audits drive processor selection criteria in Bac Ninh and Hai Phong, prioritizing EMAS-equivalent certification over price-competitive alternatives. Electronics assembly plants adopt optical sorting systems to meet brand owner recycled content specifications. Hazardous waste chemist scarcity concentrates laboratory verification capacity in Hanoi.
Vietnam Waste Management Market Competitive Landscape
Capability concentration sits with specialized hazardous waste handlers; scale advantage sits with municipal concession holders. The market structures around three tiers: integrated service providers spanning collection through recovery verification, regional specialists dominating single geographies, and technology-focused operators leveraging cement kiln co-processing or waste-to-energy installations. Strategic moves center on concession renewal positioning in Ho Chi Minh City and Hanoi, plus technology licensing partnerships for optical sorting and anaerobic digestion systems.
Among integrated service providers, Vietnam Waste Solutions and CITENCO occupy positions anchoring hazardous waste contracts with southern electronics manufacturers and municipal collection across Ho Chi Minh City respectively. INSEE Ecocycle exemplifies the technology-focused archetype through cement kiln waste recovery leadership. These three represent distinct competitive vectors: geographic network density, long-term concession relationships, and thermal treatment integration.
| Leading Market Players |
|---|
| Vietnam Waste Solutions |
| Green Environment Production Services Trade Co Ltd |
| CITENCO |
| Vietnam Australia Environment JSC |
| Vietstar Environment |
| URENCO (Urban Environment Company Hanoi) |
| SGS Vietnam |
| Dai Lam Son Co Ltd (DALASO) |
| INSEE Ecocycle |
| Others |
Value Network & Pricing Analysis
Single-source dependency on European and Japanese sorting equipment suppliers compresses pricing power across Vietnamese waste operators while forcing tiered service differentiation between hazardous-certified handlers and commodity collectors. This import reliance widens cost spreads between premium thermal treatment contracts and basic municipal collection, reshaping procurement toward long-term equipment leasing to hedge currency volatility.
Pricing Analysis
Ho Chi Minh City commands 40-60% premiums over provincial municipalities for equivalent collection services, driven by hazardous waste certification requirements and industrial park proximity. Three-tier pricing structure across certified hazardous handlers, standard municipal operators, and informal recyclers reflects compliance cost differentials. Cost compression in basic collection is intensifying because provincial People's Committees bundle concessions with fee collection guarantees. Electronics manufacturers show least price sensitivity due to supply chain audit requirements, while agricultural processors remain most sensitive.
Supply Chain Analysis
Tariff exposure between Vietnam and equipment-exporting nations in Europe and Japan dominates supply chain risk planning for incineration and optical sorting investments. Domestic supply draws from local steel fabrication for container bins and truck bodies, but rests on imported near-infrared sensors, emission control catalysts, and hydraulic compaction systems. Single-source vulnerability concentrates in German and Japanese suppliers of leachate treatment membranes. Distribution runs through Ministry of Natural Resources and Environment-licensed carriers for hazardous streams, with municipal fleets handling general waste.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's waste sector is approaching a platform-economics inflection as industrial park waste exchanges and digital payment integration create interoperability between previously fragmented collection, treatment, and verification services.
For Market Incumbents: Entrench concession relationships in Ho Chi Minh City and Hanoi through fleet modernization and laboratory certification investments before Extended Producer Responsibility mandates tighten. Cement kiln co-processing partnerships represent the priority lever for securing hazardous waste volume commitments against emerging thermal competitors. Defend against technology-focused entrants by locking in 10-year industrial park service agreements. For New Entrants and Emerging Players: Pursue first-mover concessions in Da Lat, Pleiku, and Central Highlands municipalities where integrated collection networks remain underdeveloped. The most penetrable segment lies in agricultural waste composting for Mekong Delta rice cultivation, where provincial People's Committees actively seek operators. A go-to-market angle combining mobile wallet fee collection with windrow composting technology addresses both revenue assurance and organic waste diversion mandates. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated service providers with hazardous waste certification and concession depth over pure-technology plays. Long-term viability hinges on exposure to manufacturing compliance spending rather than municipal budget cycles. Acquisition targets should demonstrate cement kiln partnerships or waste-to-energy grid connections. The signal to watch is provincial implementation decrees under the Law on Environmental Protection that accelerate source separation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Cement Kiln Co-Processing Partnership | INSEE Ecocycle demonstrates how hazardous waste fuel substitution meets decarbonization targets while diverting materials from landfills. |
| Optical Sorting Technology Licensing | Near-infrared detection systems from European suppliers enable electronics assembly plants to meet brand owner recycled content specifications. |
| Provincial Concession Expansion | Central Highlands municipalities lack integrated networks, creating first-mover opportunities for operators with mobile payment integration. |
| Hazardous Waste Laboratory Certification | Certified chemist scarcity in Hanoi and Ho Chi Minh City creates defensive moats for incumbents with in-house toxic characterization capacity. |
| Waste-to-Energy Grid Connection | Incineration with electricity generation addresses landfill scarcity near dense urban centers while producing grid-connectable power. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal environmental department directors, industrial park waste exchange managers, hazardous waste transport fleet operators, cement kiln co-processing coordinators, and optical sorting system technicians. Secondary validation drew from Ministry of Natural Resources and Environment permitting databases, provincial People's Committee concession award records, Law on Environmental Protection implementation decrees, and industrial park waste manifest tracking systems. Bottom-up volume estimates from facility-level throughput data were triangulated against top-down market sizing from national waste generation statistics.
Calibration against historical concession award patterns and technology adoption curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include service type, waste category, treatment technology, and end-user procurement pattern. CAGRs were derived from slope analysis of logged value trajectories. Key inputs encompassed landfill capacity exhaustion timelines near Ho Chi Minh City, Extended Producer Responsibility compliance cost pass-through assumptions, and cement sector decarbonization target impacts on co-processing demand.
Sensitivities concentrate around provincial implementation pace for source separation mandates, currency volatility effects on imported equipment procurement, and hazardous waste chemist training pipeline expansion. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and industrial park clustering trends. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
Municipal Solid Waste Incineration Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Construction Waste Management Market
Waste Management & Pollution Control
Incinerator Market
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
Sharp Waste Disposal Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market