
 Sharp Waste Disposal Market | 2026-2036
Sharp Waste Disposal Market Size, Share, and Industry Trends Forecast 2026-2036
Sharp Waste Disposal Market Analytics
Aftermarket service revenue from container collection, treatment, and documentation is reshaping profit pools away from one-time product sales. Stericycle leverages its North American route density to sustain logistics advantages in high-frequency pickup schedules. Daniels Health differentiates through reusable sharps container programs that reduce plastic waste and anchor long-term customer contracts.
Sharp waste disposal encompasses the containment, transport, and terminal processing of biohazardous sharps including needles, scalpels, and lancets, typically using puncture-resistant containers engineered to ASTM F2132 impact standards and treated through incineration or autoclaving at minimum 121°C saturated steam. Containers dominate product-type revenue due to mandated replacement cycles and spill containment requirements, while autoclaving gains share against incineration as mercury and dioxin emissions face tighter scrutiny. Home care represents the fastest-growing usage context as self-injection therapies for diabetes and autoimmune conditions expand the decentralized generator population.
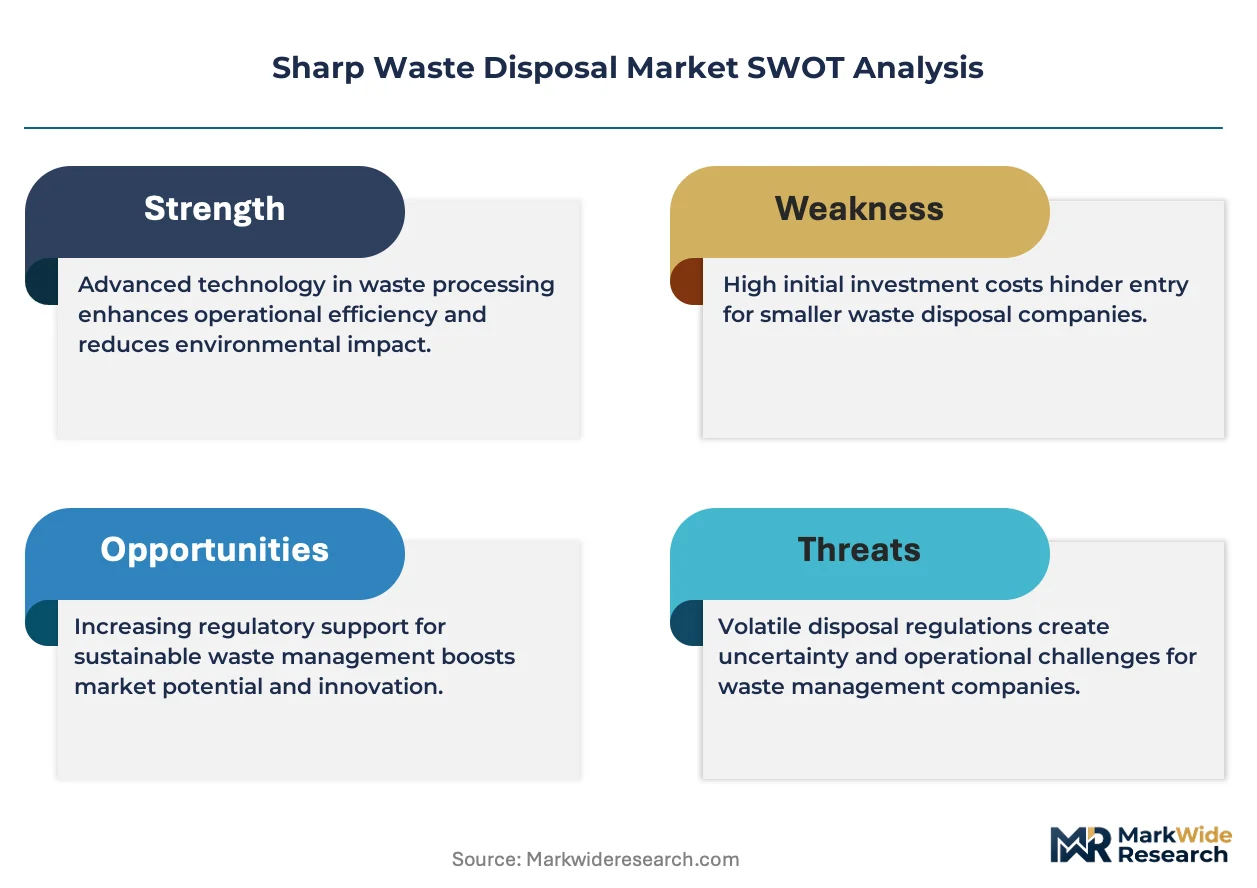
OSHA Bloodborne Pathogens Standard and EPA Resource Conservation and Recovery Act framework govern container performance, worker training, and cradle-to-grave tracking across the United States, with state-level medical waste statutes adding registration and manifest layers that elevate compliance costs for smaller generators. FDA sharps injury prevention guidance and ISO 23907 puncture resistance specifications further constrain product design and market access for non-certified suppliers. Stakeholders must weigh capital deployment between reusable container infrastructure and disposable unit expansion as regulatory pressure on plastic waste intensifies.
Market Dynamics
The aftermarket service layer is capturing margin from commoditized container hardware as logistics density and compliance documentation become the primary competitive moats. Waste generators now contract for cradle-to-grave liability transfer rather than purchasing standalone containment products.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Sharpened enforcement around needlestick injury prevention mandates puncture-resistant containment systems in all US healthcare settings, expanding replacement cycle frequency.
- Home infusion therapy:Self-injection therapies for diabetes and autoimmune conditions are decentralizing waste generation beyond hospital walls into residential settings requiring specialized collection logistics.
- Reusable container systems:FDA-cleared durable containment is displacing single-use plastics as sustainability procurement criteria harden in integrated delivery networks.
Market Restraints
- High-density polyethylene resin:Petroleum-derived container feedstock faces price volatility that compresses margins on standardized disposable units.
- Route density thresholds:Rural and exurban geographies lack sufficient generator concentration to support economically viable collection frequencies.
- Incineration capacity:Mercury and dioxin emission limits under EPA Maximum Achievable Control Technology standards are constraining terminal processing availability.
Strategic Opportunities
- Extended Producer Responsibility frameworks:EU Green Deal packaging waste directives are creating mandated take-back obligations that favor vertically integrated service providers.
- Retail pharmacy collection kiosks:Community-based sharps return programs are opening new channel access points for container manufacturers with reverse logistics capabilities.
- Radio-frequency identification tracking:Convergence of container tagging with cloud-based manifest systems is enabling real-time chain-of-custody verification for liability-sensitive generators.
Industry Challenges
- ISO 23907 certification timelines:Third-party puncture resistance testing creates 12-18 month product approval windows that delay market entry for new container designs.
- Legacy manifest system integration:State medical waste tracking databases require custom API development that fragments IT deployment across multi-state service operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sharp Waste Disposal Market |
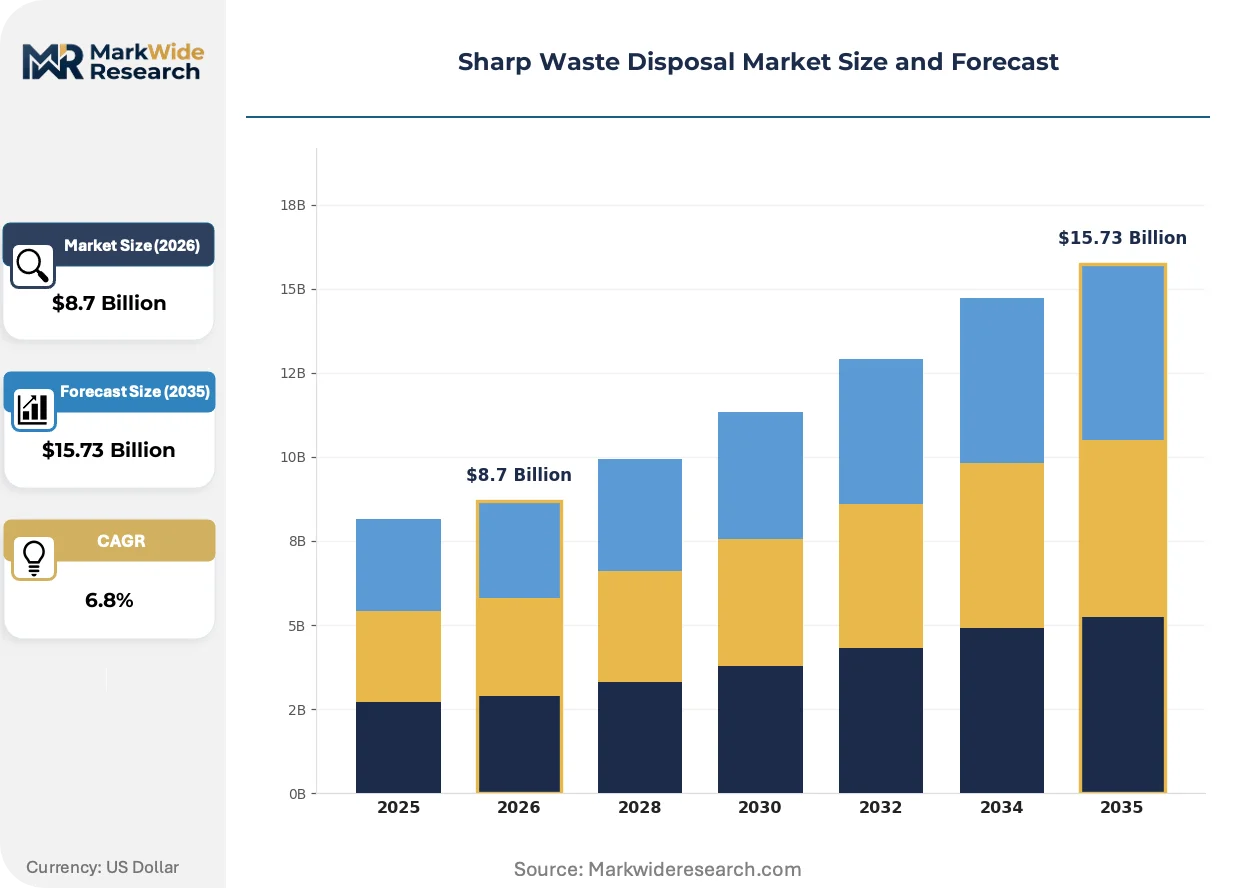
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Bags, Carts, Boxes Usage Context: Hospitals, Clinics, Laboratories, Home Care Disposal Method: Incineration, Autoclaving, Landfilling, Recycling Regulatory Compliance: OSHA Standards, EPA Guidelines, Local Regulations, International Standards |
| Companies Covered | Stericycle, Sharps Compliance, Inc., Daniels Health, BD, MedPro Disposal, Cardinal Health, Thermo Fisher Scientific, Bondtech Corporation, EnviroTain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sharp Waste Disposal Market Evolving Landscape
Container intelligence and treatment technology are converging to transform sharps waste from a cost center into a data-generating compliance asset. Three developments are restructuring competitive positioning.
Smart containers equipped with fill-level sensors and cellular connectivity are hybridizing physical containment with digital inventory management. Hospital materials management departments are piloting these units to optimize exchange schedules and reduce stockout risk. The technology is compressing service intervals from fixed calendars to dynamic demand signals.
EPA Resource Conservation and Recovery Act subtitle C revisions are tightening cradle-to-grave tracking requirements for pharmaceutical-contaminated sharps. Generators must now document destruction certificates within 90 days of pickup. Small outpatient clinics lacking dedicated compliance staff are outsourcing documentation to full-service waste vendors.
Hospital procurement departments are unbundling after-sales service from hardware acquisition. Traditional capital purchase models are giving way to per-procedure or per-bed service fees that transfer regulatory liability to waste contractors. This shift is most visible in United States integrated delivery networks consolidating vendor relationships under single-source national agreements.
Sharp Waste Disposal Market Segmentation
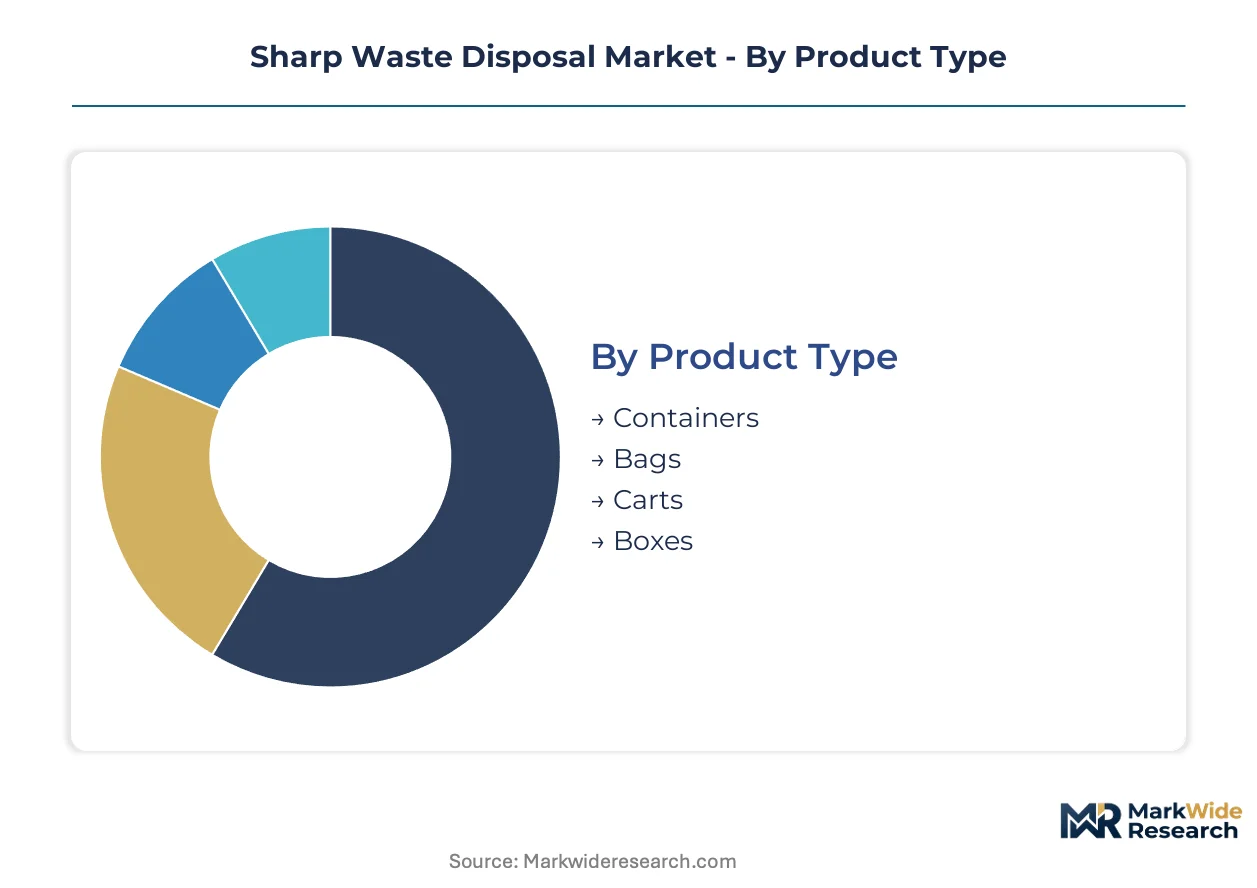
Segmentation in sharp waste disposal reveals how containment hardware, treatment infrastructure, and compliance frameworks intersect to determine vendor profitability and customer switching costs. Each dimension carries distinct capital intensity and regulatory exposure that shapes competitive positioning.
Product Type:
Healthcare facilities deploy containment solutions across a spectrum of durability requirements, from single-use disposal to multi-cycle reusable systems governed by FDA 510(k) clearance pathways.
- Containers:Puncture-resistant vessels engineered to ASTM F2132 impact standards dominate procurement volume. Hospital systems in the United States are consolidating purchases under national agreements that favor reusable container programs with embedded logistics services.
- Bags:Secondary containment for non-sharp biohazardous waste, typically red polyethylene film meeting OSHA color-coding mandates. Demand concentrates in outpatient surgical centers where lower waste volumes justify lighter-weight solutions.
- Carts:Mobile collection units for high-volume generator environments. Large integrated delivery networks deploy these for point-of-use consolidation before transport.
- Boxes:Corrugated fiberboard mail-back systems for rural and home care generators lacking scheduled pickup access. USPS-authorized designs expand reach into exurban geographies.
The dominant share belongs to Containers, while Bags are closing the gap fastest through ambulatory surgery center expansion.
Usage Context:
Generator scale and regulatory sophistication vary dramatically across care settings, from OSHA-inspected hospital environments to patient-managed home injection scenarios.
- Hospitals:Acute care facilities generate the highest per-facility waste volumes and face Joint Commission accreditation audits. These sites command premium service tiers with cradle-to-grave documentation.
- Clinics:Outpatient settings including dialysis centers and infusion suites produce moderate volumes with intermittent pickup schedules. Staffing constraints drive outsourcing of compliance documentation to full-service vendors.
- Laboratories:Research and diagnostic facilities handle contaminated glassware and pipettes alongside medical sharps. Biosafety level classifications add containment specification layers.
- Home Care:Self-injection therapies for diabetes and autoimmune conditions are decentralizing waste generation. Retail pharmacy return kiosks and mail-back programs are emerging as critical collection infrastructure.
Hospital procurement retains the largest revenue pool, though Home Care is expanding most quickly as therapeutic administration shifts beyond facility walls.
Disposal Method:
Treatment technology selection hinges on emission regulations, energy costs, and waste stream contamination profiles that determine terminal processing eligibility.
- Incineration:High-temperature destruction at 1,800-2,000°F eliminates all organic contaminants and pharmaceutical residues. EPA Maximum Achievable Control Technology standards are constraining permitted capacity.
- Autoclaving:Steam sterilization at minimum 121°C saturated steam is gaining share as mercury and dioxin scrutiny intensifies. Treated waste can achieve non-hazardous classification for landfill disposal.
- Landfilling:Disposal of pre-treated sharps waste in permitted hazardous waste cells. Limited to autoclaved material meeting EPA characteristic waste exclusion criteria.
- Recycling:Emerging mechanical and chemical processes for metal recovery from treated sharps. Stainless steel needle content drives pilot programs at select treatment facilities.
Autoclaving has captured the dominant treatment position, while Recycling is climbing the fastest through sustainability procurement criteria in integrated delivery networks.
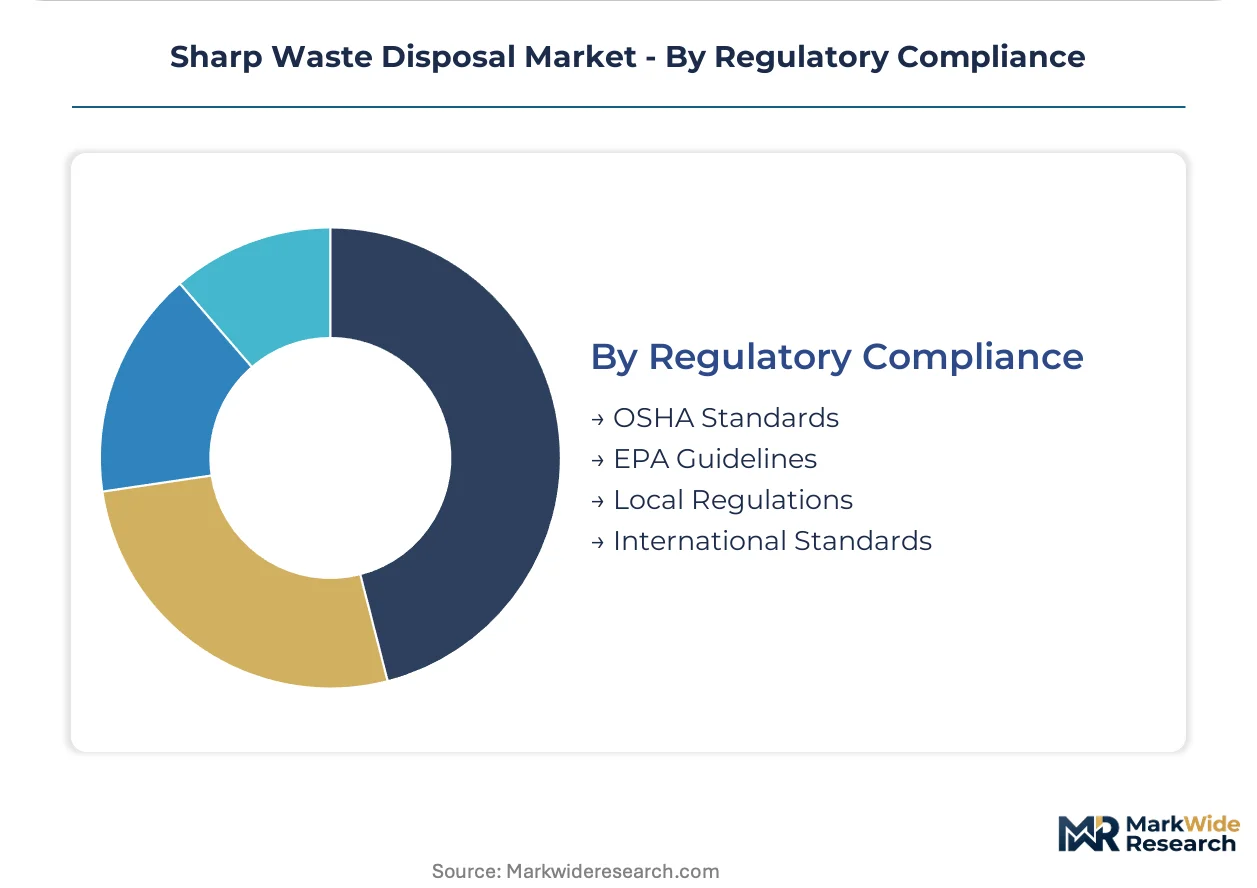
Regulatory Compliance:
Multi-layered oversight creates compliance cost differentiation between large generators with dedicated staff and smaller facilities outsourcing liability transfer.
- OSHA Standards:Bloodborne Pathogens Standard mandates puncture-resistant containment, worker training, and exposure control plans. Sharpened enforcement is accelerating container replacement cycles.
- EPA Guidelines:Resource Conservation and Recovery Act cradle-to-grave tracking governs manifest documentation and 90-day accumulation limits. Subtitle C revisions are tightening pharmaceutical-contaminated sharps oversight.
- Local Regulations:State medical waste statutes add registration, manifest, and transportation permitting layers. California and New York impose additional treatment facility certification requirements.
- International Standards:ISO 23907 puncture resistance specifications constrain product design and market access. Third-party certification creates 12-18 month approval timelines for new container designs.
OSHA Standards anchor the compliance framework, though Local Regulations are gaining operational weight as state-level enforcement resources expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States healthcare systems deploy reusable sharps containers at three times the rate of European counterparts, while Asia-Pacific markets favor single-use disposables due to lower logistics infrastructure density and fragmented generator landscapes.
United States
Outpatient surgical volume expansion and home infusion therapy proliferation are decentralizing waste generation beyond acute care facilities. OSHA Bloodborne Pathogens Standard enforcement has intensified container replacement cycles and puncture-resistance certification requirements. The Dallas-Fort Worth metroplex anchors a cluster of treatment facility operators serving the Southwest's integrated delivery networks.
Germany
EU Green Deal packaging waste directives are accelerating Extended Producer Responsibility adoption among hospital procurement departments. ECHA REACH compliance adds material traceability layers to container supply chains that elevate costs for non-integrated vendors. The Rhine-Ruhr industrial corridor concentrates autoclave manufacturing capacity serving Central European healthcare systems.
Japan
Aging demographics and rising diabetes prevalence are expanding self-injection therapy waste streams in residential settings. METI circular economy guidelines incentivize reusable container programs through procurement preference schemes. The Kansai region around Osaka hosts specialized treatment facilities processing pharmaceutical-contaminated sharps under PMDA oversight.
United Kingdom
NHS sustainability targets are embedding carbon footprint criteria into sharps containment procurement decisions. Health Technical Memorandum 07-01 mandates segregation protocols that favor standardized container specifications across Trust boundaries. Greater Manchester's healthcare infrastructure is piloting RFID-tracked container programs for real-time compliance documentation.
India
Rapid expansion of dialysis centers and oncology clinics is generating sharps waste volumes that outpace municipal treatment capacity. CDSCO medical device rules are tightening container performance standards that previously admitted unclassified imports. Maharashtra's pharmaceutical manufacturing belt is developing captive sharps treatment infrastructure to serve contract research organizations.
Sharp Waste Disposal Market Competitive Landscape
Capability concentration sits with specialized container engineers holding ISO 23907 certifications; scale advantage sits with route-dense service operators commanding logistics networks. The market structures around three tiers: full-service waste management conglomerates, reusable container system specialists, and disposable hardware fabricators. Two dominant competitive moves are emerging: backward integration into treatment infrastructure to capture terminal processing margins, and technology licensing partnerships for smart container sensor deployment.
Within the full-service tier, Stericycle and Daniels Health exemplify divergent strategic positions—Stericycle anchors North American route density advantages while Daniels Health occupies the reusable system specialization vector. Sharps Compliance, Inc. represents the compliance-documentation archetype, embedding liability transfer services into container procurement contracts. These three entities collectively illustrate how vendor selection now hinges on cradle-to-grave service bundling rather than standalone hardware specifications.
| Leading Market Players |
|---|
| Stericycle |
| Sharps Compliance, Inc. |
| Daniels Health |
| BD |
| MedPro Disposal |
| Cardinal Health |
| Thermo Fisher Scientific |
| Bondtech Corporation |
| EnviroTain |
| Others |
Value Network & Pricing Analysis
The I-35 corridor connecting Dallas-Fort Worth treatment facilities to Southwestern integrated delivery networks anchors cost structures that cascade through container procurement tiers. Freight density differentials between urban route clusters and exurban collection zones sharpen price spreads across reusable system contracts and disposable unit spot purchases.
Pricing Analysis
Long-term service contracts with embedded liability transfer dominate hospital procurement, displacing spot purchases of standalone containers. Pricing stratifies across premium FDA-cleared reusable tiers, standard disposable units, and economy mail-back boxes for home care generators. Cost compression in single-use plastics intensifies as petroleum-derived resin volatility feeds through manufacturing margins. Small outpatient clinics exhibit highest price sensitivity, while acute care systems prioritize cradle-to-grave compliance documentation over unit economics.
Supply Chain Analysis
Extended payment terms from North American hospital GPOs cascade through container fabricators toward high-density polyethylene resin suppliers in the United States, Germany, and Saudi Arabia. Manufacturing draws from petroleum feedstocks, stainless steel needle components, and RFID sensor modules. Single-source vulnerability concentrates in specialized puncture-resistant polymer formulations. Distribution runs through Stericycle and Daniels Health route networks serving generator clusters with scheduled pickup density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container replacement cycles and home infusion therapy expansion are driving a cyclical recovery as deferred hospital procurement resumes post-pandemic backlog clearance.
For Market Incumbents: Build route density moats through acquisition of regional collection operators in underserved exurban corridors. Stericycle should consolidate Southwest logistics nodes before Daniels Health expands reusable container penetration. FDA 510(k) certification investment anchors switching costs against disposable hardware commoditization.
For New Entrants and Emerging Players: Pursue retail pharmacy kiosk deployment as the most penetrable channel, targeting CVS and Walgreens reverse logistics partnerships. Home care mail-back programs offer white-space expansion beyond hospital-centric incumbents. Lead with RFID-enabled container intelligence as differentiated go-to-market positioning against legacy manifest systems.
For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical manufacturing captive waste units seeking operational focus. Five-to-ten year viability hinges on Extended Producer Responsibility framework adoption accelerating vertical integration mandates. Monitor EPA Maximum Achievable Control Technology enforcement intensity as inflection signal for autoclave versus incineration capacity valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Container Program Expansion | Daniels Health leverages FDA-cleared durability to displace single-use plastics under sustainability procurement criteria. |
| Route Density Acquisition | Stericycle consolidates Southwest logistics nodes to defend scheduled pickup frequency advantages. |
| RFID Tracking Integration | Smart container sensor deployment enables real-time chain-of-custody verification for liability-sensitive generators. |
| Retail Pharmacy Partnership | CVS and Walgreens kiosk networks extend collection infrastructure into decentralized home care waste streams. |
| Autoclave Capacity Buildout | Treatment facility operators capture share from constrained incineration capacity under EPA emission limits. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement directors, biomedical engineering leads, waste management logistics coordinators, and GPO contract administrators. Secondary validation drew from EPA enforcement databases, FDA 510(k) clearance records, OSHA inspection reports, and state medical waste manifest systems. Bottom-up container shipment analysis triangulated against top-down healthcare expenditure tracking.
Calibration against historical replacement cycle data and outpatient surgical volume trajectories shaped projections across the analysis window. Segmentation modeling incorporated product durability tiers, generator scale categories, treatment technology types, and regional regulatory clusters. CAGRs derived from logistic curve fitting to adoption saturation patterns, with inputs including home infusion therapy prescription growth and reusable container penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed regional consolidators would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Trash Rakes Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
Polyfluoroalkyl Substances (PFAS) Waste Management Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
Scrap Metal Recycling Market
Waste Management & Pollution Control
Global Pharmaceutical Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
ASEAN Waste Management Market
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
Food Waste Management Market