
 Battery Leakage Detection Sensor Market | 2026-2036
Battery Leakage Detection Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Leakage Detection Sensor Market Outlook
East Asian sensor foundries is restructuring capacity allocations toward automotive-grade leak detection modules as battery pack densities rise. Robert Bosch GmbH leverages its Tier 1 automotive channel control to embed detection systems directly into battery management platforms. INFICON anchors the precision instrument segment with mass spectrometry-based trace gas detection for laboratory and production line validation. Texas Instruments Incorporated competes through semiconductor integration, combining sensor front-ends with signal processing on single chip architectures.
Battery leakage detection sensors are electrochemical or physical transducers designed to identify electrolyte seepage, gas emission, or pressure anomalies in sealed cell assemblies, typically operating at detection thresholds below parts-per-million sensitivity for volatile organic compounds. These devices serve critical safety and predictive maintenance functions across lithium-ion, solid-state, and flow battery installations where uncontrolled leakage precipitates thermal runaway or capacity degradation. Chemical sensors dominate current deployment in electric vehicle battery packs due to direct electrolyte vapor specificity, while IoT Integration represents the fastest-expanding technology dimension as fleet operators demand cloud-connected predictive diagnostics. Pressure sensors retain mature utility in stationary power storage cabinets where slow-forming seal breaches generate measurable differential signatures before chemical emission becomes detectable.
The EU Green Deal and associated F-Gas Regulation constrain fluorinated electrolyte handling practices, compelling European battery assemblers to install continuous monitoring infrastructure. China's GB standards and SAMR certification requirements mandate leak detection in transit and stationary energy storage systems above specified capacity thresholds. NHTSA defect investigation protocols in the United States elevate manufacturer liability for thermal events traceable to undetected cell breaches. Stakeholders must evaluate whether to prioritize chemical specificity for early-stage detection or multi-parameter fusion architectures that reduce false alarm rates across variable operating temperatures.
Market Dynamics
Cell chemistry densification and pack-level integration mandates are compressing sensor response windows from minutes to milliseconds, forcing electrochemical detection architectures toward sub-ppm sensitivity thresholds.
Growth Catalysts
- EU Green Deal battery safety mandates:European assemblers must install continuous electrolyte monitoring infrastructure to comply with F-Gas Regulation constraints on fluorinated compound handling.
- China's lithium-ion production clusters:Shenzhen and Ningde cell manufacturers require real-time leak detection to prevent thermal runaway incidents in high-density pack configurations.
- Solid-state battery commercialization:Next-generation cell architectures demand novel pressure-differential sensing modalities as liquid electrolyte volumes decline.
Market Restraints
- Automotive-grade semiconductor foundry concentration:Taiwan and South Korea capacity allocation constraints limit sensor module availability for tier suppliers.
- Specialized polymer membrane input costs:Perfluorinated ionomer materials for chemical specificity layers face price volatility from fluorochemical feedstock markets.
- False-positive rate calibration complexity:Multi-parameter fusion algorithms require extensive thermal cycling validation before OEM deployment approval.
Strategic Opportunities
- India's stationary energy storage buildout:Grid-scale battery installations under CEA guidelines create demand for cabinet-level pressure monitoring systems.
- IoT-cloud predictive maintenance convergence:Fleet operators seek edge-computing sensor nodes with cellular backhaul for distributed battery health analytics.
- Second-life battery repurposing channels:Decommissioned EV packs for stationary applications require retrofitted leak detection to meet insurer liability requirements.
Industry Challenges
- ASIL-D functional safety certification timelines:Automotive sensor qualification cycles extend 18-24 months, compressing product refresh windows.
- Cross-domain talent scarcity:Electrochemistry, signal processing, and automotive systems engineering expertise rarely coexists in single engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Leakage Detection Sensor Market |
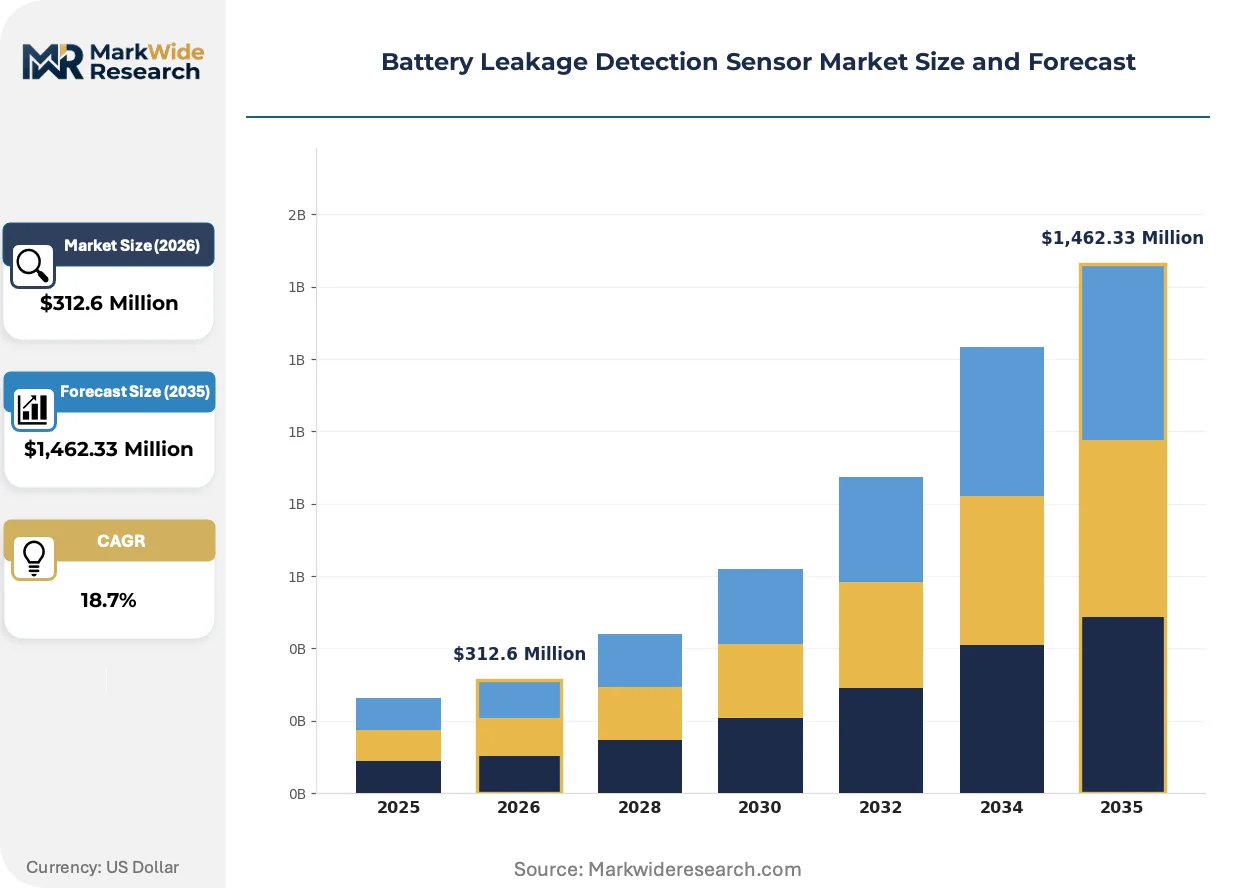
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,462.33 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Chemical Sensors, Infrared Sensors, Pressure Sensors Technology: Wireless Monitoring, Wired Monitoring, IoT Integration, Electronic Alerts End User: Manufacturing, Automotive, Aerospace, Renewable Energy Application: Power Storage, Electric Vehicles, Portable Electronics, Industrial Equipment |
| Companies Covered | INFICON, Agilent Technologies, Pfeiffer Vacuum, Continental AG, Robert Bosch GmbH, Furukawa Electric Co., Ltd., NXP Semiconductors, Texas Instruments Incorporated, HELLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Leakage Detection Sensor Market Strategic Shifts
Detection architectures are fragmenting across chemical, pressure, and optical modalities as battery formats diversify from cylindrical cells to prismatic and solid-state configurations.
Photonic interferometry is decentralizing leak localization from pack-level aggregate measurements to individual cell monitoring. Tier 1 battery integrators in Germany and Japan are piloting fiber-optic sensor arrays embedded within module interconnects. This modality is decentralizing maintenance protocols from scheduled inspections to condition-based interventions triggered by refractive index shifts.
REACH substance restriction amendments are accelerating substitution of perfluorinated sensing membranes with bio-based polymer alternatives. European chemical suppliers face reformulation deadlines that compress qualification timelines for new electrolyte-specific layers. Automotive OEMs in Germany and France are responding by dual-sourcing membrane materials to mitigate supply continuity risk.
Fleet operators are unbundling sensor hardware procurement from battery management system contracts. Logistics companies operating electric truck depots in California and the Netherlands now specify standalone leak detection units with open API architectures. This pattern is most visible in heavy-duty commercial vehicle segments where third-party telematics providers intermediate between cell manufacturers and end-users.
Battery Leakage Detection Sensor Market Segmentation
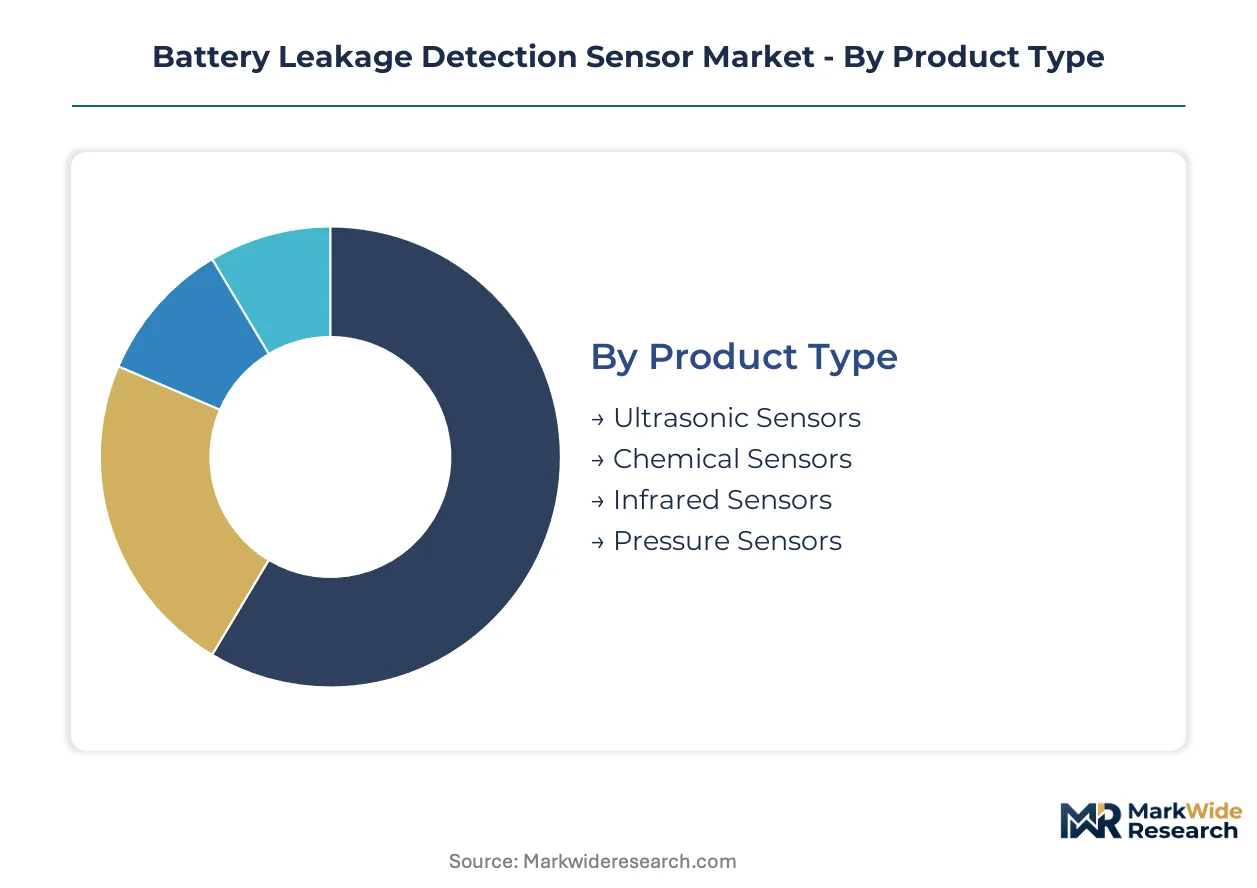
Segmentation in battery leakage detection sensors reflects divergent technical requirements across cell formats and operating environments. Chemical specificity demands vary sharply between stationary cabinets and electric vehicle packs, while connectivity architectures split between legacy wired installations and cloud-native IoT deployments.
Product Type:
Supply concentration in electrochemical sensor membranes shapes competitive positioning across detection modalities, with specialty polymer foundries in Germany and Japan controlling critical input materials.
- Chemical Sensors:Electrochemical transducers employing perfluorinated ionomer membranes detect electrolyte vapor at sub-ppm thresholds. Shenzhen and Ningde cell manufacturers deploy these extensively in high-density lithium-ion packs where thermal runaway prevention mandates direct vapor specificity.
- Pressure Sensors:Differential pressure transducers monitor seal integrity through minute gas accumulation signatures. Stationary energy storage operators in India and Germany favor these for slow-forming breach detection where chemical emission remains below electrochemical sensor thresholds.
- Ultrasonic Sensors:Acoustic emission detectors identify electrolyte seepage through fluid displacement signatures.
- Infrared Sensors:Optical absorption spectrometers target volatile organic compound signatures through non-contact measurement.
Today's leader: Chemical Sensors. Tomorrow's challenger: Pressure Sensors.
Technology:
Cost tier differentiation separates retrofit-capable wireless nodes from integrated wired architectures, with IoT-enabled systems commanding premium positioning for fleet-scale deployments.
- IoT Integration:Edge-computing sensor nodes with cellular backhaul enable cloud-connected predictive diagnostics. California and Netherlands electric truck depot operators specify these standalone units with open API architectures, unbundling procurement from battery management system contracts.
- Wireless Monitoring:Battery-powered radio frequency modules eliminate cabling in retrofit applications. Second-life battery repurposing channels deploy these for decommissioned EV packs converted to stationary storage, meeting insurer liability requirements without pack disassembly.
- Wired Monitoring:Hardwired sensor arrays integrate directly into battery management platforms through CAN bus or Ethernet protocols.
- Electronic Alerts:Local alarm systems trigger immediate shutdown sequences without external connectivity.
Current volume concentrates in Wired Monitoring. Steepest expansion trajectory belongs to IoT Integration.
End User:
Application maturity varies across customer types, with automotive qualification cycles extending 18-24 months while industrial deployments move faster through less stringent safety certifications.
- Automotive:Electric vehicle manufacturers face ASIL-D functional safety mandates requiring extensive thermal cycling validation. German OEMs embed detection systems directly into battery management platforms through Tier 1 supplier channels, compressing response windows from minutes to milliseconds.
- Renewable Energy:Grid-scale battery installations under India's CEA guidelines create demand for cabinet-level monitoring. These stationary configurations prioritize pressure-differential sensing for slow-forming seal breaches over chemical specificity.
- Manufacturing:Cell production lines require mass spectrometry-based trace gas detection for laboratory and production validation.
- Aerospace:Aviation battery systems demand ultra-high reliability detection with redundant architectures.
Dominant demand source: Automotive. Fastest-climbing segment: Renewable Energy.
Application:
Geography-driven deployment patterns concentrate electric vehicle sensor demand in China's production clusters while power storage applications distribute across India's grid buildout and European stationary installations.
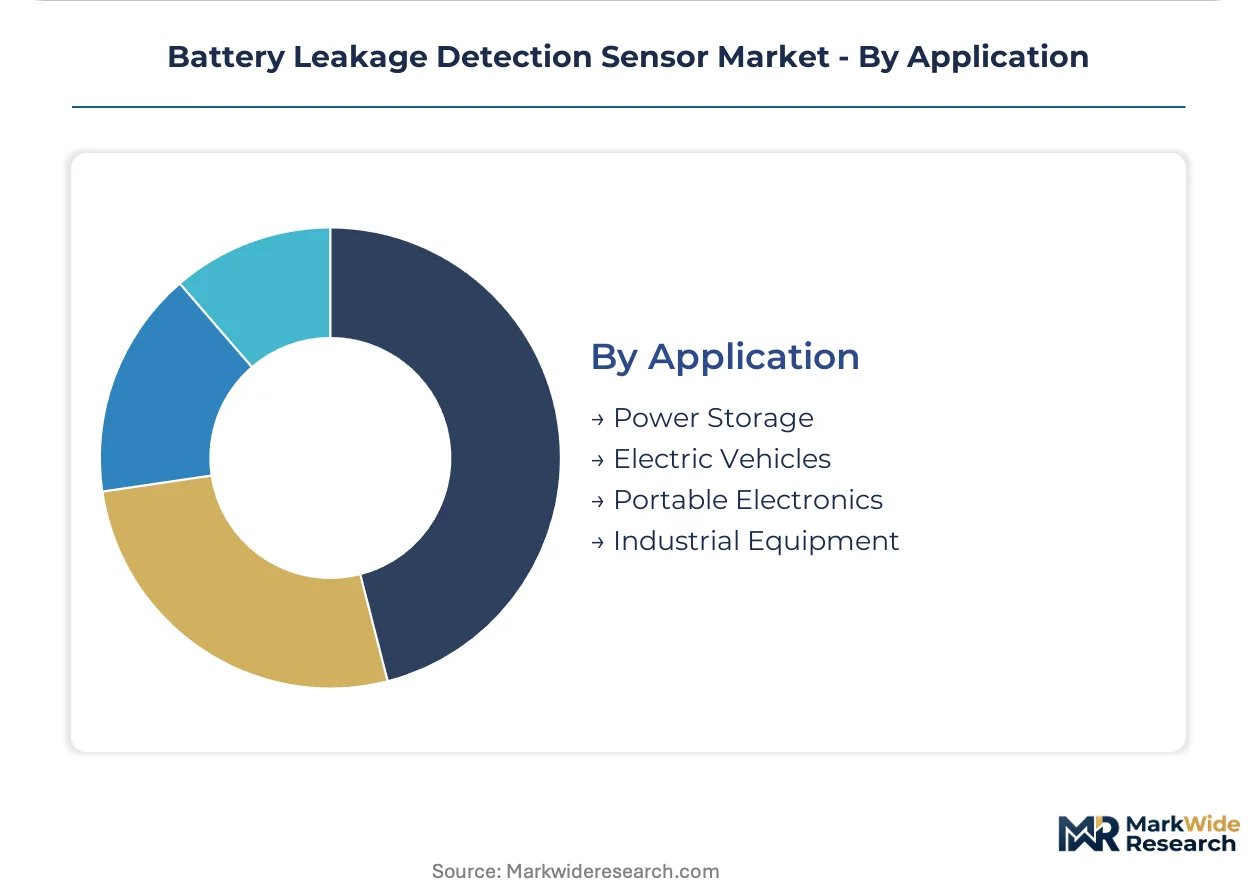
- Electric Vehicles:High-voltage pack architectures in passenger and commercial vehicles require millisecond-response detection. EU Green Deal F-Gas Regulation constraints compel European assemblers to install continuous electrolyte monitoring infrastructure, driving procurement from German and French OEMs.
- Power Storage:Utility-scale and commercial battery cabinets prioritize pressure monitoring for thermal management. India's stationary energy storage buildout under CEA guidelines generates concentrated demand for systems with extended calibration intervals.
- Portable Electronics:Consumer device manufacturers specify compact chemical sensors for smartphone and laptop battery protection.
- Industrial Equipment:Forklift and material handling battery systems require ruggedized detection for high-vibration environments.
Revenue concentration sits with Electric Vehicles. Power Storage gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as battery assemblers migrate toward jurisdictions with harmonized safety certification regimes. Cost-of-compliance gaps between the EU Green Deal framework and emerging economy standards are accelerating sensor procurement decisions in manufacturing clusters with streamlined approval pathways.
China
GB standards and SAMR certification requirements mandate leak detection in energy storage systems above specified capacity thresholds. Shenzhen and Ningde host concentrated lithium-ion production clusters where cell manufacturers deploy real-time electrolyte monitoring to prevent thermal runaway in high-density pack configurations. MIIT guidelines on battery safety management systems are tightening integration specifications for automotive-grade sensors.
Germany
EU Green Deal F-Gas Regulation constraints on fluorinated compound handling compel domestic assemblers to install continuous monitoring infrastructure. KBA type-approval processes for electric vehicle battery systems extend qualification timelines, favoring established Tier 1 supplier relationships. Stuttgart and Munich anchor automotive OEM procurement networks embedding detection systems directly into battery management platforms.
United States
NHTSA defect investigation protocols elevate manufacturer liability for thermal events traceable to undetected cell breaches. California electric truck depot operators specify standalone leak detection units with open API architectures, unbundling procurement from battery management system contracts. EPA emissions tracking requirements for industrial battery installations are expanding addressable demand in stationary power applications.
India
CEA guidelines for grid-scale battery installations generate concentrated demand for cabinet-level pressure monitoring systems. Maharashtra and Gujarat host emerging cell manufacturing investments where domestic content requirements under PLI schemes are localizing sensor assembly operations. BIS certification timelines for automotive battery safety components remain elongated, creating procurement lead-time advantages for pre-qualified import suppliers.
Japan
METI roadmaps for solid-state battery commercialization are driving novel pressure-differential sensing requirements as liquid electrolyte volumes decline. Nagoya and Osaka manufacturing corridors concentrate precision instrument production for laboratory and production line validation applications. JIS standards for automotive battery safety are converging with UN ECE regulations, simplifying export qualification pathways for domestic sensor fabricators.
Battery Leakage Detection Sensor Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue IoT-cloud predictive maintenance convergence and second-life battery retrofit channels. The vendor base stratifies across automotive Tier 1 integrators, precision instrument specialists, and semiconductor platform providers. Three archetypes dominate: chemical specificity specialists leveraging membrane material expertise; pressure-differential incumbents with stationary power storage relationships; and semiconductor integrators combining sensor front-ends with signal processing architectures. Capacity expansion and strategic partnerships represent the dominant competitive vectors as qualification timelines compress product refresh windows.
Within the precision instrument tier, INFICON anchors mass spectrometry-based trace gas detection for laboratory and production validation. Robert Bosch GmbH exemplifies Tier 1 automotive channel control, embedding detection systems through direct battery management platform integration. Texas Instruments Incorporated represents semiconductor integration archetypes, combining sensor front-ends with signal processing on single-chip architectures. These three occupy positions spanning the value chain from validation equipment to embedded automotive electronics.
| Leading Market Players |
|---|
| INFICON |
| Agilent Technologies |
| Pfeiffer Vacuum |
| Continental AG |
| Robert Bosch GmbH |
| Furukawa Electric Co., Ltd. |
| NXP Semiconductors |
| Texas Instruments Incorporated |
| HELLA |
| Others |
Value Chain & Pricing Dynamics
Automotive electrochemistry specialists concentrated in Stuttgart and Munich drive labor-cost differentials that widen pricing-tier spreads between ASIL-D certified modules and economy-grade retrofit units. Tier 1 integrators leverage embedded software engineering talent pools to command premium positioning, while offshore assembly operations in Eastern European contract manufacturing zones compress margins for standardized sensor hardware.
Pricing Analysis
Distributor markups of 15-25 percentage points separate factory-gate pricing from fleet-operator procurement costs for IoT-enabled detection nodes. Three-tier pricing structure across premium ASIL-D certified, standard automotive-grade, and economy retrofit levels reflects certification investment recovery timelines and thermal cycling validation depth. Cost compression in the economy tier intensifies as Chinese membrane suppliers scale perfluorinated ionomer output. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while German OEMs prioritize functional safety compliance over unit cost.
Supply Chain Analysis
Returns and refurbishment flows for decommissioned EV battery packs are creating secondary component channels that compete with virgin sensor procurement in stationary energy storage retrofit applications. Specialty polymer membrane production concentrates in Germany, Japan, and South Korea, with perfluorinated ionomer feedstocks drawing from fluorochemical complexes in China and the United States. Single-source vulnerability in automotive-grade semiconductor foundry capacity constrains module availability for Tier 2 suppliers. Distribution runs through direct OEM integration contracts, aftermarket service networks, and emerging third-party telematics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has entered a late-cycle quality phase where ASIL-D certification and millisecond-response specifications separate viable suppliers from commodity players. The demand shift toward predictive maintenance platforms with edge-computing architectures favors vendors with embedded software integration capabilities.
For Market Incumbents: Lock in membrane material supply through captive offtake agreements with German and Japanese specialty polymer foundries before REACH reformulation deadlines compress input availability. Deepen automotive channel control by embedding detection algorithms directly into battery management platform firmware, raising switching costs against semiconductor integrators entering from the signal-processing tier.
For New Entrants and Emerging Players: The 40-60 percent price-point gap between premium ASIL-D modules and economy wireless retrofit units offers entry space for mid-tier IoT-native architectures. India's stationary energy storage buildout under CEA guidelines represents the most penetrable geography, with compressed certification timelines relative to automotive qualification cycles. Pursue open-API standalone unit positioning to intercept fleet-operator procurement decisions before battery management system contract bundling solidifies.
For Investors and Strategic Acquirers: Tier 1 automotive suppliers with battery platform integration mandates are the most active acquirer in this space, seeking electrochemical sensing IP to complement existing power electronics portfolios. Acquisition targets with dual expertise in polymer membrane formulation and automotive functional safety certification command structural scarcity premiums. Monitor NHTSA defect investigation closure rates and EU Green Deal implementation enforcement intensity as inflection indicators for liability-driven procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Functional Safety Certification | Unlocks Tier 1 automotive procurement channels with 18-24 month qualification timelines. |
| Perfluorinated Ionomer Backward Integration | Secures membrane supply continuity against REACH substance restriction volatility. |
| IoT-Cloud Platform Integration | Captures fleet-operator predictive maintenance spend through cellular-enabled edge nodes. |
| Second-Life Battery Retrofit Channel Development | Addresses insurer liability requirements for decommissioned EV pack stationary applications. |
| Solid-State Battery Pressure Sensing R&D | Positions for METI roadmap commercialization as liquid electrolyte volumes decline. |
Study Parameters
Coverage spans China, Germany, the United States, India, and Japan, with primary inputs from each market cluster. The research combines structured interviews with Tier 1 supplier procurement directors, automotive platform engineers, stationary energy storage project developers, and specialty polymer membrane technical directors with secondary validation from MIIT battery safety guidelines, KBA type-approval documentation, NHTSA defect investigation records, CEA grid-scale installation reports, and METI solid-state battery roadmaps. Bottom-up sensor unit demand modeling and top-down battery pack production forecasts were triangulated to establish market sizing.
Rate-of-change decomposition across the projection horizon separates volume growth from value expansion drivers. The analytical framework models segmentation dimensions including detection modality, connectivity architecture, end-use certification tier, battery chemistry format, and regional regulatory cluster. CAGRs were derived from installed base accumulation curves and replacement cycle assumptions, with cross-reference to lithium-ion cell production capacity announcements and electric vehicle platform launch schedules.
Caveats apply where ASIL-D certification timeline extensions, fluorochemical feedstock price spikes, or solid-state battery commercialization acceleration could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and automotive qualification cycle stability. Practitioners should monitor EU F-Gas Regulation amendment progress and China SAMR certification requirement expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Micropump Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
India Industrial Sensors and Transmitters Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Microsensor Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Battery Free Wireless Sensor Market