
 Automotive MEMS Sensor Market | 2026-2036
Automotive MEMS Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive MEMS Sensor Market Analysis
China's semiconductor fabrication expansion is reconfiguring supply security for automotive MEMS components. Robert Bosch GmbH leverages captive wafer processing to sustain cost leadership across inertial sensor categories. STMicroelectronics anchors European supply through its dedicated MEMS foundry in Agrate Brianza, Italy. Infineon Technologies competes on silicon-germanium process variants optimized for pressure sensing in powertrain modules.
Automotive MEMS sensors integrate micromachined silicon structures, typically 1–100 micrometers in scale, that transduce physical quantities such as acceleration, pressure, or angular velocity into electrical signals via capacitive or piezoresistive mechanisms; these devices enable real-time closed-loop control in vehicle safety, propulsion, and chassis systems. Pressure sensors dominate value contribution due to mandatory tire pressure monitoring and manifold absolute pressure applications, while gyroscopes represent the fastest-expanding category as electronic stability control and autonomous navigation architectures multiply degrees of freedom requirements. OEM procurement of silicon-based accelerometers already occupies the largest volume tier, though piezoelectric variants gain traction in knock detection for downsized turbocharged engines.
NHTSA mandates drive demand precision for rollover detection and crash sensing in the United States, while EU Green Deal emissions targets enforced by EMA and national type-approval bodies tighten tolerance specifications for powertrain feedback loops. China's MIIT issues GB standards for connected vehicle sensor interoperability that shape market access for foreign suppliers. Stakeholders must monitor divergence between regional certification regimes when allocating R&D across pressure, inertial, and acoustic sensing portfolios.
Market Dynamics
MEMS sensor procurement is concentrating around captive fabrication strategies as OEMs seek supply security for safety-critical inertial and pressure sensing modules. Euro 7 emissions mandates and NHTSA rollover detection requirements are tightening performance tolerances faster than process node migration can absorb.
Growth Catalysts
- Emissions Compliance Mandates:Euro 7 standards from EMA require manifold absolute pressure sensors with ±1% accuracy for real-time fuel trim optimization in downsized powertrains.
- Silicon Photonics Integration:Optical MEMS gyroscopes are penetrating autonomous navigation stacks where fiber-optic gyroscope cost structures previously blocked adoption.
- Stuttgart-Munich Corridor Concentration:Germany's automotive supplier belt generates clustered demand for tire pressure monitoring and chassis control sensors.
Market Restraints
- 200mm Wafer Supply Bottleneck:Automotive-qualified MEMS fabs rely on mature-node silicon supply that concentrates among three Asian substrate vendors.
- Leadframe Alloy Volatility:Copper-nickel-palladium plating chemistry cost swings compress gross margins on pressure sensor packages.
- Functional Safety Certification Burden:ISO 26262 ASIL-D qualification timelines extend 18-24 months for new accelerometer designs.
Strategic Opportunities
- India PLI Scheme Incentives:Production-linked incentives for automotive electronics manufacturing are drawing MEMS packaging investment to Tamil Nadu and Gujarat.
- Lidar Beam-Steering MEMS:Micro-mirror arrays for solid-state lidar represent unserved volume as robotaxi fleets scale in California and Arizona.
- Vehicle-to-Everything Interoperability:China's MIIT GB standards for connected vehicle sensor data protocols create specification windows for compliant foreign suppliers.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:Finite-element modeling of thermo-mechanical stress in packaged MEMS structures requires rare cross-trained mechanical-electrical engineers.
- Legacy Powertrain Integration Friction:New pressure sensor form factors must interface with engine control modules designed for 1990s-era analog signal conditioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive MEMS Sensor Market |
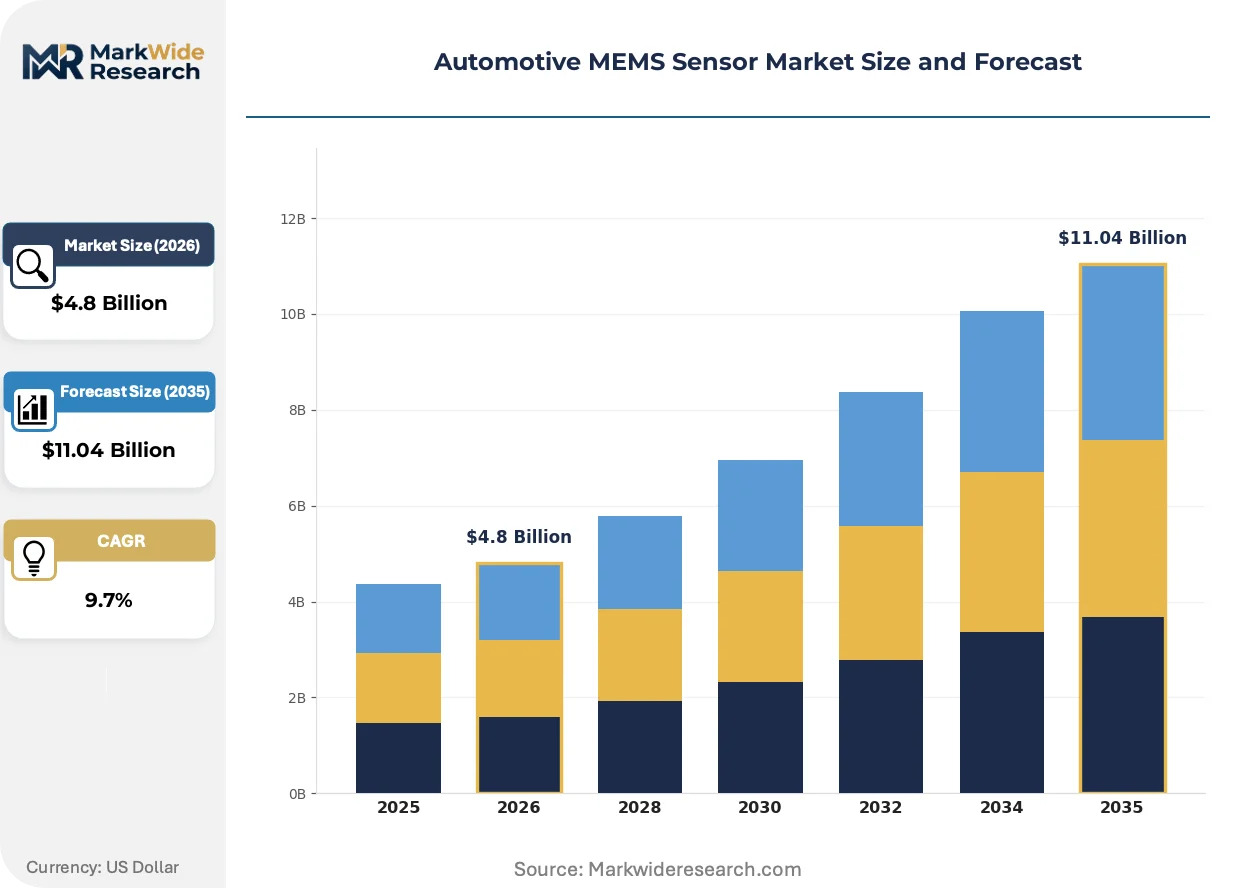
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Accelerometers, Gyroscopes, Microphones Application: Safety Systems, Engine Control, Tire Pressure Monitoring, Navigation End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Silicon-Based, Piezoelectric, Capacitive, Optical |
| Companies Covered | Robert Bosch GmbH, STMicroelectronics, Analog Devices, Infineon Technologies, Denso Corporation, NXP Semiconductors, Sensata Technologies, Murata Manufacturing, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive MEMS Sensor Market Emerging Trajectories
Sensor fusion architectures are collapsing discrete component counts while elevating software compensation complexity. This shift redefines value capture from silicon transduction toward algorithmic calibration and thermal drift correction.
Capacitive MEMS accelerometers with integrated temperature reference circuits are digitizing crash-detection signal chains previously reliant on analog front-end discrete components. Tier 1 suppliers in Germany and Japan are qualifying these devices for side-impact and pedestrian protection systems. The elimination of external ADC and filtering stages is compressing module bill-of-materials while raising firmware validation burdens.
Euro 7 emissions frameworks enforced by EMA and national type-approval bodies are mandating 10Hz minimum sampling rates for manifold absolute pressure sensors in gasoline direct-injection engines. This performance floor disqualifies legacy piezoresistive designs lacking sufficient bandwidth. Powertrain module suppliers are redesigning intake tract sensor pods to accommodate faster MEMS variants with integrated digital outputs.
Fleet operators in North America are unbundling sensor calibration services from hardware procurement contracts. Commercial vehicle leasing companies now demand separate pricing for initial installation and recurring drift-correction intervals. This disintermediation of service revenue is visible most acutely in long-haul trucking segments where tire pressure monitoring system accuracy directly affects fuel economy guarantees.
Automotive MEMS Sensor Market Segmentation
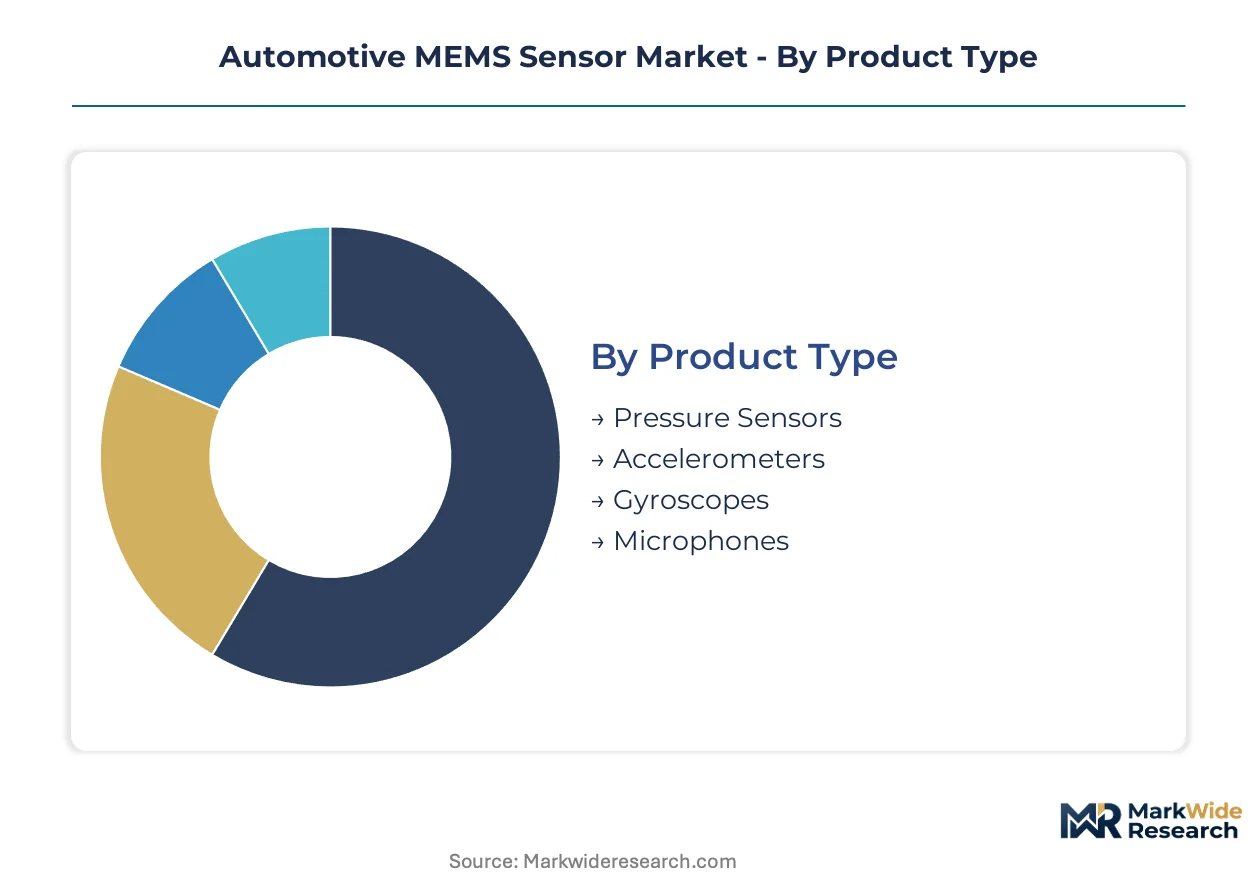
Automotive MEMS sensor procurement diverges sharply across transduction physics and vehicle integration depth. Tier-1 suppliers and OEMs allocate R&D budgets differently depending on whether the target application demands raw signal fidelity or embedded algorithmic compensation.
Product Type:
Mature pressure sensing dominates installed value while emerging optical modalities capture autonomous vehicle design wins.
- Pressure Sensors:Piezoresistive silicon diaphragms transduce manifold absolute pressure and tire pressure with ±1% accuracy under Euro 7 mandates. Stuttgart-Munich corridor OEMs specify these for downsized turbocharged powertrains where real-time fuel trim optimization is mandatory.
- Accelerometers:Capacitive MEMS structures with integrated temperature reference circuits digitize crash-detection signal chains for NHTSA-compliant rollover sensing. Side-impact and pedestrian protection systems in Germany and Japan are absorbing these devices fastest as external ADC elimination compresses module bill-of-materials.
- Gyroscopes:Angular velocity sensing enables electronic stability control architectures.
- Microphones:Acoustic MEMS support in-cabin voice recognition and active noise cancellation.
Pressure sensors retain volume leadership; gyroscopes hold the steepest expansion curve.
Application:
Cost tier stratification separates safety-critical mandates from convenience-driven navigation upgrades.
- Safety Systems:Airbag deployment and pedestrian protection modules demand ASIL-D qualified inertial sensing with sub-millisecond latency. NHTSA rollover detection requirements and EU type-approval bodies enforce redundant accelerometer channels for signal integrity verification.
- Engine Control:Manifold absolute pressure feedback loops govern air-fuel ratio precision in gasoline direct-injection architectures. EMA-enforced 10Hz minimum sampling rates are disqualifying legacy piezoresistive designs lacking sufficient bandwidth for real-time emissions compliance.
- Tire Pressure Monitoring:Direct measurement systems are mandatory for new vehicle homologation.
- Navigation:Dead-reckoning augmentation for autonomous positioning stacks.
Safety systems command premium pricing; engine control applications scale fastest with powertrain electrification.
End User:
Supply concentration favors captive fabrication strategies among integrated vehicle assemblers over distributed aftermarket channels.
- OEMs:Volkswagen Group and Toyota Motor Corporation source MEMS through qualified supplier lists with multi-year volume commitments. These buyers specify process node requirements and functional safety certification tiers that lock out second-source alternatives.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG integrate MEMS die into chassis control and powertrain modules. Their captive wafer processing capabilities insulate margin structures from 200mm substrate supply bottlenecks.
- Vehicle Assemblers:Contract manufacturers with limited sensor design authority.
- Aftermarket Providers:Independent distributors serving replacement and retrofit demand.
Tier-1 suppliers capture the deepest value-add; aftermarket providers face margin compression from calibration service unbundling.
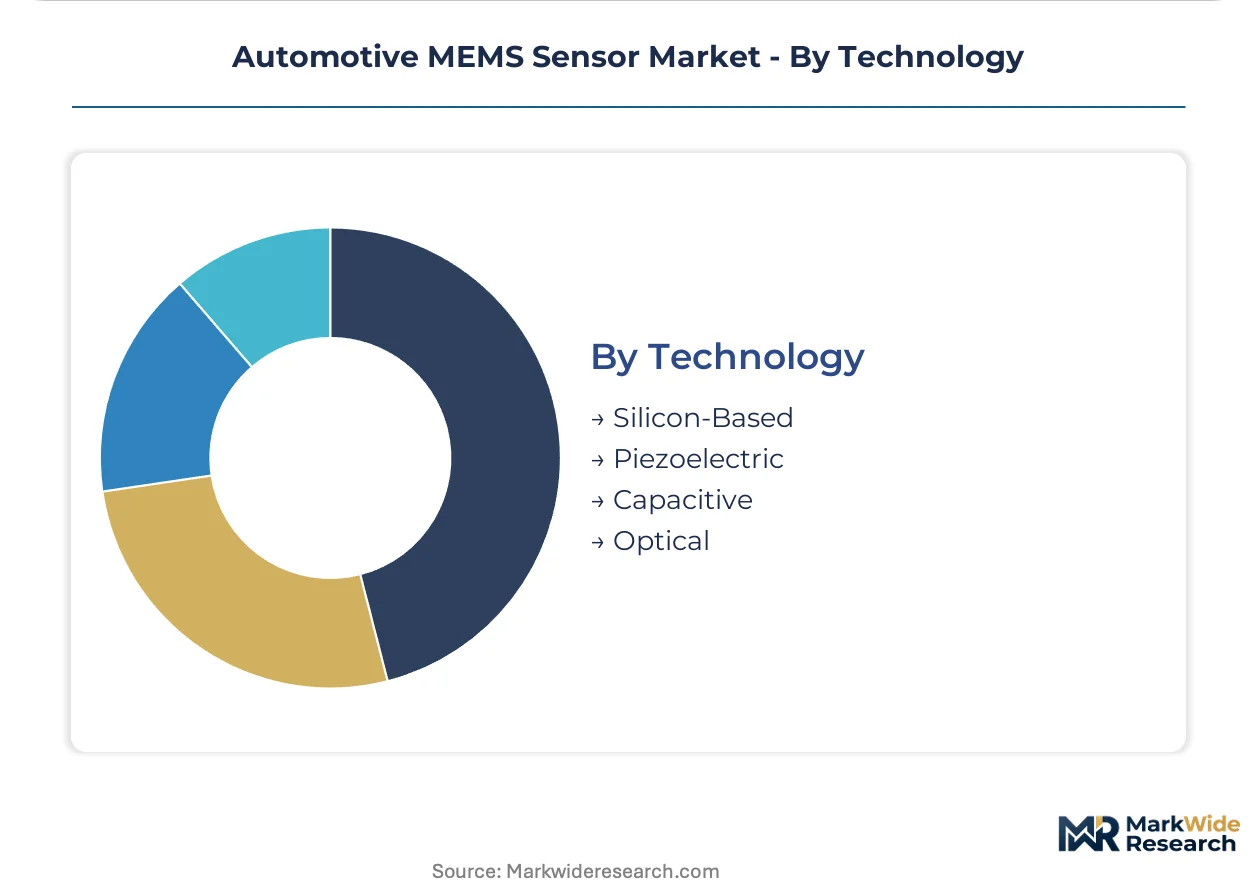
Technology:
Silicon micromachining maturity contrasts with piezoelectric niche penetration and optical MEMS emergence.
- Silicon-Based:Bulk and surface micromachining dominate automotive-qualified production with established reliability datasets. STMicroelectronics anchors European supply through its Agrate Brianza MEMS foundry serving multiple OEM programs.
- Capacitive:Differential capacitance measurement enables temperature-stable acceleration sensing. Digitized outputs with integrated self-test circuits are displacing analog front-end discrete components in next-generation crash sensing modules.
- Piezoelectric:Ceramic thin-film transduction for knock detection in downsized engines.
- Optical:Micro-mirror arrays and interferometric structures for lidar beam-steering.
Silicon-based processes retain manufacturing scale; optical MEMS gain share fastest in autonomous navigation design cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive MEMS sensor consumption patterns diverge sharply across geographies. Germany's supplier corridor demands precision-engineered pressure and inertial modules for powertrain integration, while China's fabrication expansion prioritizes cost-optimized scale for domestic EV platforms. The United States emphasizes safety-critical certification under NHTSA mandates, contrasting with India's emerging packaging hub strategy.
United States
NHTSA rollover detection mandates and crash-sensing precision requirements drive accelerometer procurement for advanced driver-assistance systems. The regulator enforces sub-millisecond latency thresholds for airbag deployment signal chains. Detroit's automotive engineering cluster absorbs silicon-based inertial sensors for pedestrian protection modules.
Germany
EMA-enforced Euro 7 emissions standards require manifold absolute pressure sensors with ±1% accuracy for real-time fuel trim optimization. The Stuttgart-Munich supplier corridor concentrates demand for tire pressure monitoring and chassis control MEMS modules. Robert Bosch GmbH leverages captive wafer processing to sustain cost leadership across inertial sensor categories.
China
MIIT-issued GB standards for connected vehicle sensor interoperability shape market access protocols for foreign suppliers. The country's semiconductor fabrication expansion reconfigures supply security for automotive MEMS components. Yangtze River Delta foundries are scaling 200mm wafer capacity for pressure sensor die production.
Japan
METI industrial policy supports domestic MEMS foundry retention for automotive safety system supply. JIS standards govern functional safety certification timelines for accelerometer designs destined for electronic stability control. Nagoya's automotive supplier network integrates gyroscopes for autonomous navigation architectures.
India
PLI scheme production-linked incentives for automotive electronics manufacturing draw MEMS packaging investment to Tamil Nadu and Gujarat. BIS technical standards for vehicle safety systems create compliance pathways for imported sensor modules. Gujarat's semiconductor assembly ecosystem is qualifying pressure sensor packages for powertrain module integration.
Automotive MEMS Sensor Market Vendor Landscape
Capability concentration sits with integrated Tier-1 suppliers possessing captive fabrication; scale advantage sits with diversified semiconductor houses serving multiple OEM programs. The market structure tiers between vertically integrated chassis module specialists and fabless design houses dependent on external foundry access. Dominant archetypes include captive wafer processors, European MEMS foundry anchors, and diversified analog semiconductor portfolios. Competitive moves center on backward integration into substrate supply and strategic partnerships for 200mm wafer allocation security.
Among European-based fabricators, STMicroelectronics anchors supply through its dedicated MEMS foundry in Agrate Brianza, Italy, exemplifying the captive-production archetype. Robert Bosch GmbH represents integrated Tier-1 capability extending from wafer processing through module assembly. Infineon Technologies occupies a position within the diversified semiconductor tier, competing on process variants optimized for pressure sensing applications. These three entities collectively illustrate the capability-scale tension shaping procurement negotiations with Volkswagen Group and Toyota Motor Corporation.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| STMicroelectronics |
| Analog Devices |
| Infineon Technologies |
| Denso Corporation |
| NXP Semiconductors |
| Sensata Technologies |
| Murata Manufacturing |
| TDK Corporation |
| Others |
Supply Flow & Price Mechanics
200mm wafer supply from Taiwan, Japan, and South Korea concentrates upstream margin capture for automotive MEMS die production, while downstream module assembly pools value in Germany's Stuttgart-Munich corridor and China's Yangtze River Delta packaging hubs.
Pricing Analysis
Long-term offtake agreements dominate procurement between Tier-1 suppliers and OEM qualified vendor lists, with three-tier pricing structure across premium ASIL-D certified, standard ISO-compliant, and economy-grade aftermarket tiers. Price differentiation separates ASIL-D qualified accelerometers for airbag deployment from standard-grade tire pressure monitoring modules. Pricing pressure stems from leadframe alloy volatility in copper-nickel-palladium plating chemistry. Fleet operators exhibit highest price sensitivity as they unbundle calibration services from hardware contracts.
Supply Chain Analysis
Export control regimes on advanced lithography equipment limit 200mm capacity expansion outside East Asia, constraining European and North American MEMS fabrication autonomy. Taiwan, Japan, and South Korea anchor wafer substrate supply. Raw material dependencies include silicon wafers, palladium for leadframe plating, and specialized ceramic packages. Single-source vulnerability concentrates in three Asian substrate vendors. Distribution runs through Tier-1 module suppliers integrating die into chassis and powertrain systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive MEMS sensor procurement builds defensive moats through ISO 26262 certification entrenchment, where ASIL-D qualification timelines of 18-24 months lock out second-source alternatives and embed switching costs across OEM platforms.
For Market Incumbents: Insulate margin structures through captive 200mm wafer processing investments in Italy and Germany, matching Robert Bosch GmbH's cost leadership model. Counter emerging Chinese foundry scale by deepening ASIL-D certification portfolios for safety-critical inertial sensing. Channel control over qualified supplier lists at Volkswagen Group and Toyota Motor Corporation remains the priority lever.
For New Entrants and Emerging Players: India's Tamil Nadu and Gujarat packaging corridors offer underpenetrated entry points for pressure sensor module assembly under PLI scheme incentives. Target aftermarket calibration service contracts where fleet operators have disintermediated hardware procurement. Pursue go-to-market partnerships with European Tier-1s seeking second-source alternatives for tire pressure monitoring systems.
For Investors and Strategic Acquirers: Capital is best deployed toward European MEMS foundry anchors with established OEM program relationships and Agrate Brianza-class captive production assets. Long-term viability over the projection horizon favors entities with backward integration into 200mm wafer allocation security. Watch for MIIT GB standard compliance windows as inflection indicators for China market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Investment | STMicroelectronics' Agrate Brianza facility secures OEM program lock-in through dedicated capacity. |
| ASIL-D Certification Acceleration | Fast-track ISO 26262 qualification compresses 18-24 month timelines for airbag deployment sensors. |
| India Packaging Hub Establishment | PLI scheme incentives in Tamil Nadu draw pressure sensor module assembly from European incumbents. |
| Silicon Photonics Integration | Optical MEMS gyroscope development penetrates autonomous navigation stacks previously blocked by fiber-optic costs. |
| 200mm Wafer Allocation Security | Strategic partnerships with Taiwanese and Japanese substrate vendors mitigate supply bottleneck exposure. |
Methodological Framework
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, MEMS foundry operations managers, and aftermarket distribution heads provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, vehicle production databases, IHS Markit registration data, and customs trade records. Bottom-up die shipment tracking and top-down OEM content-per-vehicle estimates were triangulated for volume reconciliation.
Scenario-bracketing framed low-base and high-base cases across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from segment-level shipment trajectories and average selling price evolution. Forecast inputs included Euro 7 emissions mandate compliance deadlines, NHTSA rollover detection rulemakings, and MIIT GB standard implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese foundries or accelerated silicon photonics substitution would shift outcomes. Material shifts in 200mm wafer supply allocation, export control regime tightening, or Euro 7 enforcement delay would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Sensor Patch Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Safety Sensors Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
Condition Monitoring Sensors Market