
 Proximity Switches Market | 2026-2036
Proximity Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Proximity Switches Market Analytics
Market Context
IP69K-rated proximity switches is redrawing competitive boundaries in harsh-environment industrial sensing. OMRON Corporation leverages its factory automation heritage to dominate Japanese and European automotive lines. KEYENCE CORPORATION sustains premium positioning through direct sales channels and rapid customization turnaround. Balluff GmbH specializes in inductive proximity solutions for metalworking and welding applications across German-speaking manufacturing clusters.
Technical Definition and Segment Structure
Proximity switches are non-contact sensors that detect the presence or absence of an object through electromagnetic fields, capacitive coupling, or ultrasonic waves, typically operating at switching frequencies between 1 Hz and 5 kHz with sensing distances from 0.6 mm to 60 mm depending on technology and target material. These devices serve as critical input elements in automated machinery, conveyor systems, and safety interlocks where mechanical limit switches would fail from wear or contamination. Inductive proximity switches occupy the largest share of industrial installations due to proven reliability against metal targets in oil-drenched environments, while capacitive variants are gaining ground in level detection and non-metallic object sensing within food processing equipment. Flush mount installation types command preference in space-constrained machinery panels, though through-hole configurations retain stronghold in retrofit applications where wiring access remains limited.
Regulatory Framework and Outlook
CE marking under the EU Machinery Directive, IEC 60947-5-2 performance standards, and OSHA machine guarding regulations in the United States collectively mandate fail-safe sensor performance in automated equipment, directly influencing product certification requirements and design validation protocols. REACH compliance and RoHS substance restrictions further constrain material selection for housings and potting compounds, particularly affecting plastic and metal segment suppliers. Stakeholders must monitor evolving functional safety ratings as IEC 61508-derived standards extend deeper into non-safety-critical automation tiers.
Market Dynamics
IP69K sealing certification is fragmenting supplier tiers in harsh-environment proximity sensing, as automotive and food processing OEMs mandate ingress protection that eliminates commodity sensor vendors from qualified supplier lists.
Growth Catalysts
- Factory automation mandates:Automotive assembly plants in Germany and Japan are deploying inductive proximity switches at weld stations and paint lines to replace mechanical limit switches prone to contamination failure.
- IEC 60947-5-2 standardization:European machinery OEMs now require CE-marked proximity switches with documented switching frequency validation, creating specification pull through EU supply chains.
- Capacitive sensing expansion:Food processing equipment manufacturers are specifying capacitive proximity switches for level detection in non-metallic containers, opening applications inductive sensors cannot serve.
Market Restraints
- Semiconductor input volatility:Proximity switch ASICs and signal conditioning chips face allocation pressure from competing automotive electronics demand, squeezing gross margins for mid-tier sensor assemblers.
- German sensor component concentration:Critical ferrite cores and precision wound coils for inductive proximity switches concentrate in Baden-Württemberg supplier clusters, creating geographic single-point vulnerability.
- Ultrasonic substitution threat:Long-range object detection applications above 60 mm sensing distance are migrating to ultrasonic sensors with programmable detection windows, compressing inductive switch addressable scope.
Strategic Opportunities
- Indian industrial automation buildout:PLI scheme incentives for manufacturing automation are creating first-time specification opportunities for IP67-rated proximity switches in Pune and Chennai automotive component plants.
- IO-Link protocol convergence:Smart proximity switches with integrated IO-Link communication are capturing predictive maintenance data streams, enabling sensor-as-a-service revenue models in German automotive Tier-1 supply chains.
- Direct-to-machine-builder channels:Sensor vendors are bypassing traditional industrial distribution by establishing application engineering offices in Stuttgart, Munich, and Nagoya to capture specification authority at design stage.
Industry Challenges
- Functional safety certification timelines:IEC 61508 SIL-rated proximity switches require 18-24 month validation cycles, delaying product launches and freezing development roadmaps for safety-critical automation tiers.
- Legacy PLC integration friction:Smart sensor deployments face protocol translation complexity with 1990s-era programmable logic controllers still operating in brownfield manufacturing facilities across Midwest US industrial corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proximity Switches Market |
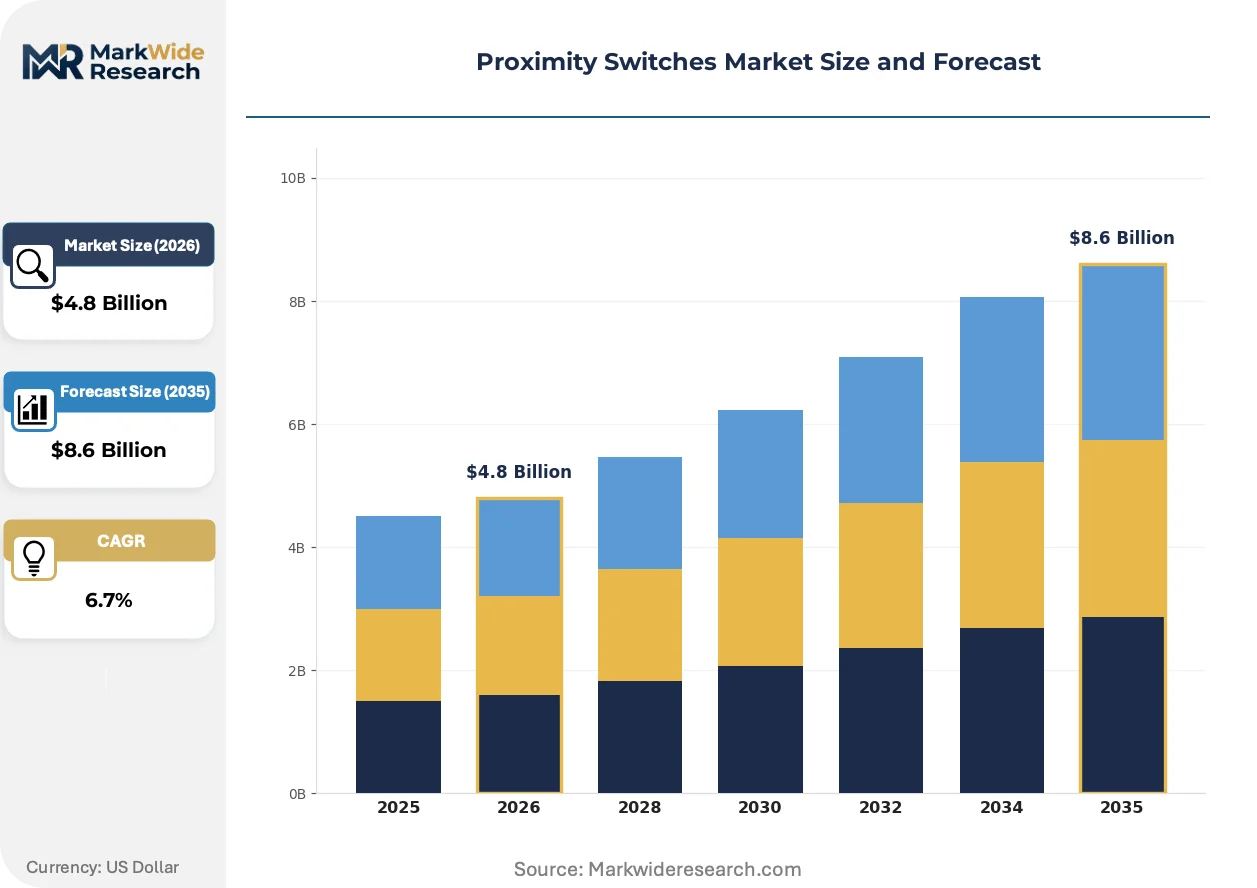
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Capacitive, Inductive, Magnetic, Ultrasonic End Use: Automated Machinery, Consumer Electronics, Automotive, HVAC Systems Material: Plastic, Metal, Glass, Silicon Installation Type: Panel Mount, Flush Mount, Through-Hole, Surface Mount |
| Companies Covered | OMRON Corporation, KEYENCE CORPORATION, Panasonic Corporation, SICK AG, STMicroelectronics, Honeywell International Inc., Schneider Electric SE, Rockwell Automation, Balluff GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proximity Switches Market Evolving Landscape
Proximity switch architecture is bifurcating between sealed commodity sensors for standard automation and intelligent, connected variants that embed diagnostic capability at the sensing edge.
Magnetostrictive position sensing is decomposing traditional inductive proximity switch applications in hydraulic cylinder feedback and linear motion control. Mobile equipment OEMs in construction and agriculture are specifying magnetostrictive sensors for stroke measurement above 100 mm. This displacement is compressing the premium tier of long-range inductive proximity switches into shorter-distance, cost-sensitive applications.
REACH substance restrictions are constraining potting compound formulations for proximity switch housings, forcing reformulation of epoxy and polyurethane encapsulants to eliminate SVHC candidates. Sensor vendors serving EU machinery OEMs must revalidate thermal cycling performance and dielectric strength with alternative chemistries. German automotive supply chains are absorbing 8-12 month qualification delays as compound suppliers resubmit technical files to ECHA.
Machine builders are unbundling sensor specification from bundled automation procurement, establishing independent vendor qualification programs that bypass traditional distributor influence. Automotive Tier-1 suppliers in Stuttgart and Munich now maintain approved sensor lists with direct technical audits. This disintermediation is visible most acutely in German-speaking manufacturing clusters where OEMs seek traceability to component-level test data.
Proximity Switches Market Segmentation
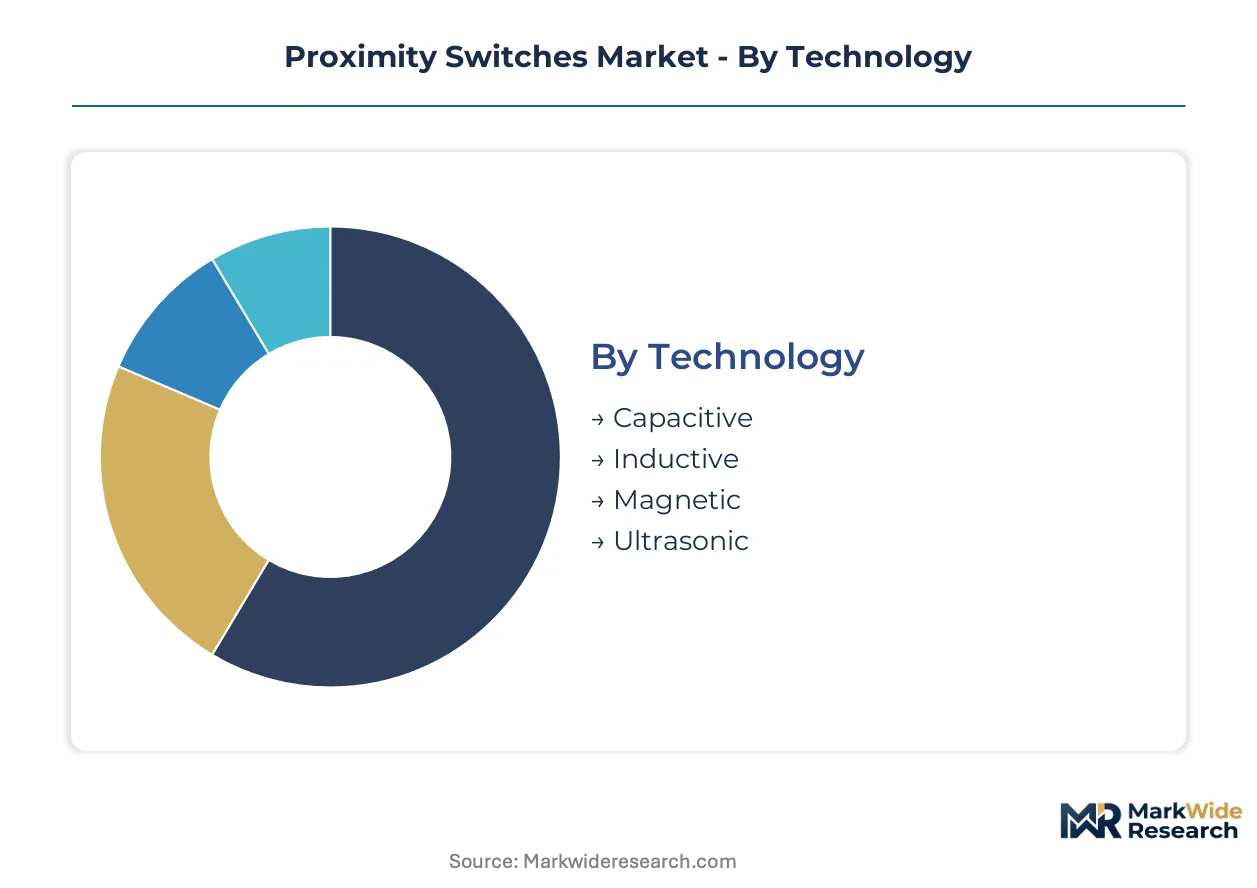
Proximity switch procurement channels diverge sharply by technology tier, with inductive variants flowing through distributor networks while smart capacitive and ultrasonic sensors move via direct OEM specification. Material selection and installation geometry further fragment sourcing strategies across automotive, food processing, and mobile equipment verticals.
Technology:
Channel mix splits between high-volume distributor SKUs for standard inductive sensors and direct application engineering for programmable ultrasonic variants with IO-Link integration.
- Inductive:Electromagnetic field detection of ferrous and non-ferrous metals dominates weld stations and conveyor positioning in Stuttgart automotive corridors. German Tier-1 suppliers specify these for IP69K-rated paint line environments where mechanical switches fail from chemical exposure.
- Capacitive:Dielectric sensing enables level detection in non-metallic containers and plastic packaging machinery. Food processing OEMs in Bavaria are specifying these for dairy tank monitoring where inductive technologies cannot penetrate container walls.
- Magnetic:Hall-effect and reed switch variants serve position feedback in pneumatic cylinders and valve actuators.
- Ultrasonic:Time-of-flight measurement extends sensing range beyond 60 mm for liquid level and bulk material applications.
By volume, Inductive leads. By growth pace, Capacitive is expanding most quickly.
End Use:
Cost tier separation is pronounced, with automotive lines absorbing premium IP69K-rated sensors while HVAC contractors specify economy-grade plastic-housed variants through wholesale channels.
- Automotive:Assembly plants in Germany and Japan deploy weld-resistant inductive sensors with ceramic-coated faces at body-in-white stations. IP69K sealing mandates from BMW and Toyota are disqualifying commodity suppliers from approved vendor lists.
- Automated Machinery:Packaging and material handling OEMs specify flush-mount inductive switches for conveyor positioning and safety interlocks. Stuttgart machine builders are unbundling sensor procurement from bundled automation packages to enforce direct technical audits.
- HVAC Systems:Duct-mounted capacitive sensors monitor filter status and airflow presence in commercial building automation.
- Consumer Electronics:Miniaturized magnetic proximity switches enable lid-close detection in laptops and smartphone accessories.
By revenue concentration, Automotive dominates. By specification velocity, Automated Machinery is gaining share fastest.
Material:
Supply concentration for precision components creates margin tiering, with nickel-plated brass and stainless steel commanding premiums over thermoplastic housings in corrosive environments.
- Metal:Nickel-plated brass and 316 stainless steel housings withstand welding spatter and caustic washdown in food processing and automotive applications. REACH SVHC restrictions on chrome plating are forcing German suppliers to validate alternative surface finishes with 8-12 month qualification delays.
- Plastic:PBT and PA66 housings serve cost-sensitive automation where chemical resistance requirements are moderate. Injection molding capacity for sensor housings concentrates in Baden-Württemberg supplier clusters.
- Glass:Borosilicate faceplates protect sensing elements in high-temperature foundry and glass manufacturing environments.
- Silicon:MEMS-based proximity sensing elements are emerging in miniaturized consumer and medical device applications.
By unit shipment, Plastic leads. By specification pull-through in premium automation, Metal shows the steepest expansion trajectory.
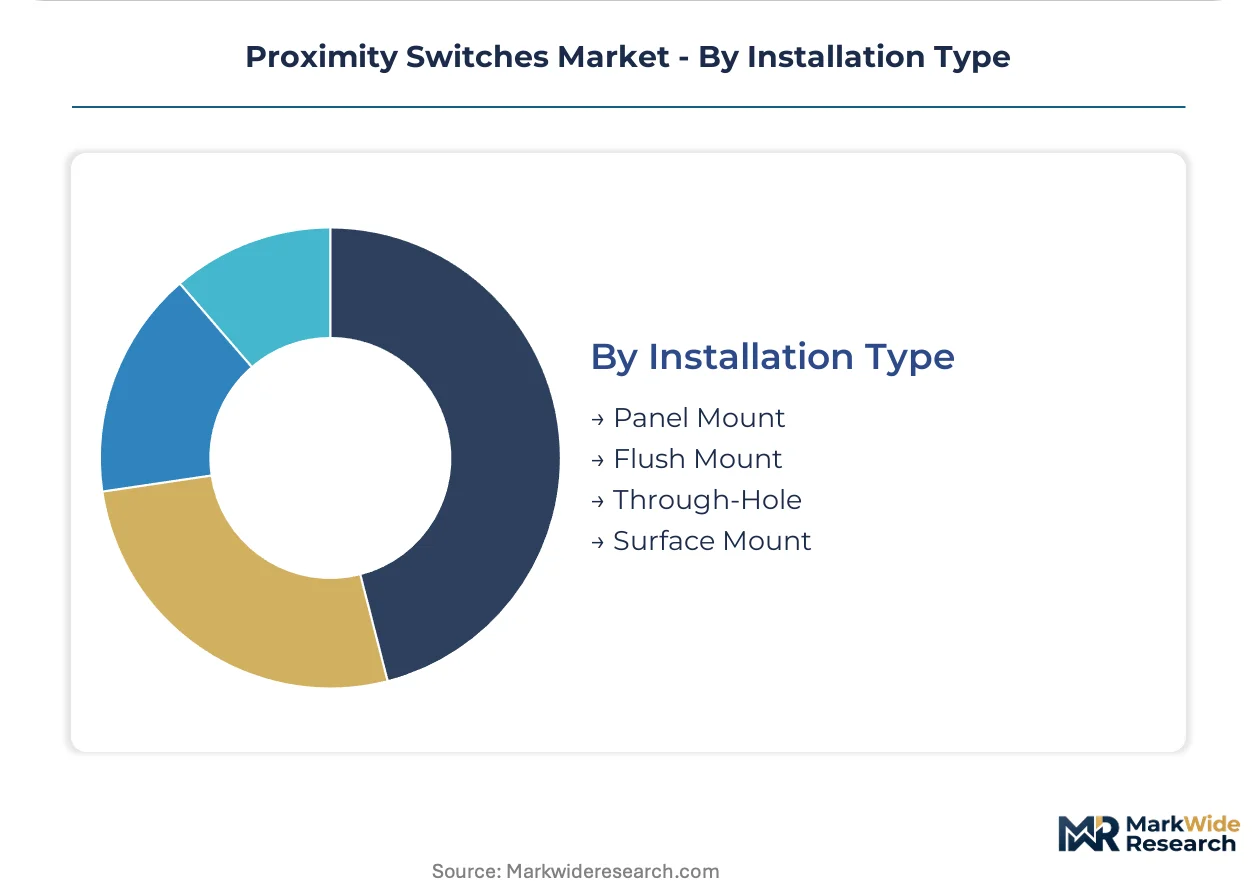
Installation Type:
Customer type segmentation separates retrofit contractors favoring through-hole wiring access from OEM machine builders specifying flush-mount integration in space-constrained panels.
- Flush Mount:Embedded installation with sensing face aligned to metal surface dominates new machinery design in space-constrained automotive tooling panels. German automotive OEMs specify these for robotic end-effector integration where protruding sensors risk collision.
- Through-Hole:Threaded barrel mounting with rear wiring access retains dominance in brownfield retrofit applications across Midwest US manufacturing corridors. Legacy PLC integration requirements favor these for compatibility with 1990s-era control architectures.
- Panel Mount:Front-access installation with nut retention serves switchboard and control cabinet applications.
- Surface Mount:Adhesive or clip-mounted variants address miniaturized electronics and battery-powered mobile equipment.
By installed base, Through-Hole retains the largest footprint. By new specification velocity, Flush Mount is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German proximity switch manufacturers export heavily into Japanese automotive assembly corridors, creating a trans-Eurasian supply artery for IP69K-rated industrial sensors.
Germany
Automotive OEMs in Stuttgart and Munich mandate IEC 60947-5-2 certified proximity switches for weld-resistant body-in-white stations. REACH compliance through ECHA constrains potting compound formulations, forcing 8-12 month requalification cycles. Baden-Württemberg supplier clusters concentrate precision ferrite core production for inductive sensor coils.
Japan
Factory automation lines at Toyota and Honda deploy ceramic-faced inductive sensors for paint shop environments. METI industrial standards enforce switching frequency validation for CE-marked exports to Europe. Nagoya's Chubu region anchors sensor specification authority through direct machine-builder relationships.
United States
OSHA machine guarding regulations mandate fail-safe sensor performance in automated equipment across Midwest manufacturing corridors. Brownfield facilities in Michigan and Ohio retain 1990s-era PLCs, creating protocol friction for smart sensor deployments. Detroit automotive Tier-1 suppliers maintain independent vendor qualification programs bypassing traditional distribution.
India
PLI scheme incentives for manufacturing automation create first-time specification opportunities in Pune and Chennai automotive component plants. BIS certification requirements for industrial electronics constrain import channels for non-compliant vendors. Tamil Nadu's industrial corridor sees fastest uptake of IP67-rated proximity switches in new greenfield assembly plants.
China
MIIT standards for industrial automation equipment drive local content requirements in domestic machinery procurement. Yangtze River Delta manufacturing clusters absorb capacitive proximity switches for food processing equipment in Shanghai and Jiangsu province. GB standard harmonization with IEC 60947-5-2 accelerates technical file alignment for export-oriented sensor vendors.
Proximity Switches Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded automation conglomerates facing off against family-owned German sensor houses. The vendor base stratifies around IP69K sealing capability, fragmenting commodity suppliers from qualified automotive tiers. Three archetypes dominate: full-line automation conglomerates with captive sensor divisions, specialized inductive sensor houses with regional manufacturing footprints, and semiconductor firms supplying ASICs and signal conditioning chips. Competitive moves center on direct-to-machine-builder channel establishment and IO-Link protocol integration for predictive maintenance data capture.
Among Japanese-listed automation conglomerates, OMRON Corporation and KEYENCE CORPORATION exemplify divergent go-to-market structures, with the former leveraging distributor networks and the latter sustaining premium positioning through direct sales engineering. SICK AG anchors the German specialist tier alongside Balluff GmbH, representing family-owned precision sensor houses with deep integration into Stuttgart automotive supply chains. These three firms occupy distinct competitive positions without overlapping strategic postures.
| Leading Market Players |
|---|
| OMRON Corporation |
| KEYENCE CORPORATION |
| Panasonic Corporation |
| SICK AG |
| STMicroelectronics |
| Honeywell International Inc. |
| Schneider Electric SE |
| Rockwell Automation |
| Balluff GmbH |
| Others |
Value Network & Pricing Analysis
Scale economies in ferrite core winding and precision coil manufacturing concentrate production among Baden-Württemberg suppliers, compressing price floors for standard inductive sensors while elevating premiums for IP69K-certified variants. This geographic clustering reinforces tiered pricing stratification across automotive, machinery, and retrofit channels.
Pricing Analysis
Technology-generation pricing gaps separate legacy inductive sensors from IO-Link-enabled smart variants and emerging MEMS-based miniaturized units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked IP69K sensors commanding substantial premiums over uncertified alternatives. Price erosion runs through economy-grade plastic-housed units as Chinese manufacturers expand capacity for HVAC and consumer electronics applications. Automotive OEMs in Stuttgart demonstrate lowest price sensitivity due to qualification lock-in, while Midwest US retrofit contractors absorb highest sensitivity from legacy PLC compatibility requirements.
Supply Chain Analysis
Germany and Japan anchor precision ferrite core and ceramic-faced sensor production, with Taiwan feeding semiconductor ASICs for signal conditioning modules. Critical inputs draw from nickel-plated brass stock, epoxy potting compounds, and rare-earth magnet materials for Hall-effect variants. Single-source vulnerability concentrates in Baden-Württemberg coil winding capacity, where REACH-driven compound reformulation has extended qualification timelines. Distribution runs through authorized industrial distributors for standard SKUs, while direct application engineering channels capture smart sensor specifications at machine-builder design stages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward automotive Tier-1 suppliers and machine builders unbundling sensor procurement from bundled automation packages, fragmenting traditional distributor influence across German-speaking manufacturing clusters.
For Market Incumbents: Shield specification authority by deepening direct technical audit relationships with Stuttgart and Munich automotive OEMs, while accelerating IO-Link protocol integration to capture predictive maintenance data streams. Magnetostrictive position sensing threatens long-range inductive applications above 100 mm, demanding R&D investment in multi-technology sensor platforms. Backward integration into ferrite core production mitigates geographic single-point vulnerability in Baden-Württemberg supplier clusters. For New Entrants and Emerging Players: Lead with IP67-rated inductive sensors targeting Pune and Chennai automotive component plants under India's PLI scheme incentives, where first-time specification windows remain open. Food processing equipment in Bavaria offers penetrable white space for capacitive level detection sensors, as dairy tank monitoring applications expand beyond inductive technology limitations. Establish application engineering offices in Nagoya's Chubu region to bypass entrenched distributor relationships through direct machine-builder specification capture. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized inductive sensor houses with captive IP69K certification capabilities and established automotive supply chain integration. Long-term viability hinges on IO-Link protocol adoption rates and functional safety certification depth across IEC 61508-derived standards. Watch for inflection signals in Indian greenfield assembly plant sensor procurement volumes, as PLI scheme manufacturing automation buildout accelerates specification authority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| IO-Link Protocol Integration | Enables predictive maintenance data capture in German automotive Tier-1 supply chains. |
| Direct-to-Machine-Builder Channel Establishment | Bypasses distributor influence by embedding application engineers in Stuttgart and Nagoya design offices. |
| IP69K Certification Investment | Qualifies vendors for BMW and Toyota paint line environments, excluding commodity competitors. |
| Backward Integration into Ferrite Core Production | Reduces dependency on Baden-Württemberg supplier concentration for precision coil components. |
| REACH-Compliant Compound Reformulation | Addresses ECHA substance restrictions with validated alternative potting chemistries for EU market access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association publications across the proximity switch value chain. Interviews with maintenance directors at automotive assembly plants, OEM procurement teams in Stuttgart and Munich, and aftermarket service heads informed demand-side validation. Secondary sources encompassed IEC 60947-5-2 technical documentation, ECHA REACH substance restriction updates, and SEC filings from listed automation conglomerates. Bottom-up sensor shipment estimates triangulated against top-down industrial automation capex projections.
Segmentation dimensions modeled include technology tier, end-use vertical, housing material, installation geometry, and regional regulatory cluster across the projection horizon. CAGRs derived from installed base growth rates, replacement cycle analysis, and technology substitution patterns for magnetostrictive and ultrasonic alternatives. Forecast inputs incorporated automotive production schedules, PLI scheme incentive disbursement timelines, and IO-Link protocol adoption curves in German supply chains.
The analysis sits within stated boundaries; outcomes outside sustained automotive automation investment, stable semiconductor supply, or harmonized IEC-GB standard alignment would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and REACH substance restriction evolution. Recalibration cycles align with material shifts in functional safety standard adoption, Indian manufacturing automation policy implementation, and magnetostrictive sensor cost-performance trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Fusible Switches Market
Switches
Australia Switchgear Market
Switches
Transfer Switch Market
Switches
Campus Switches Market
Switches
Surface Mount Switch Market
Switches
ASEAN Switchgear Market
Switches
Global Disconnector Switch Market
Switches
Mexico Rocker Switch Market
Switches
Electric Switch Market
Switches
Rocker Switch Market
Switches
Haptic Feedback Switch and Button Platforms Market
Switches
Brazil Switchgear Market
Switches
Navigation Switches Market
Switches
India Reed Sensors Switches Market
Switches
Static Transfer Switches Market
Switches
Timer Switch Socket Market