
 Safety Sensors Market | 2026-2036
Safety Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Sensors Market Intelligence
Market Context
Functional safety certification to SIL 3 and PLe tiers is rotating demand toward sensors with redundant architectures and diagnostic coverage above 99 percent. Pepperl+Fuchs leverages its intrinsically safe portfolio to dominate hazardous environment deployments across chemical and oil and gas facilities. Siemens anchors European industrial automation with integrated safety PLC and sensor bundles that reduce commissioning complexity for machine builders. SICK AG specializes in optoelectronic safety sensors with patented transceiver designs for high-reliability perimeter guarding.
Technical Definition and Segment Structure
Safety sensors are electromechanical or solid-state devices engineered to detect hazardous conditions including proximity breaches, gas leaks, thermal excursions, or smoke particles, typically operating with response latencies under 10 milliseconds to trigger protective shutdowns or alerts. Infrared technology leads industrial safety applications due to proven immunity to ambient light interference and established supply chains for LED emitters and photodiode receivers; MEMS-based gas sensors represent the fastest-expanding technology segment as wafer-level fabrication cuts unit costs for distributed environmental monitoring networks. Proximity sensors command the largest product type revenue pool in manufacturing automation, while building automation applications for smoke detectors and temperature sensors extract steadier margins through recurring replacement cycles and regulatory-mandated inspection schedules.
Regulatory Framework and Outlook
ISO 13849, IEC 62061, and the EU Machinery Directive shape product design by mandating quantified reliability metrics and documented failure mode analysis for sensors deployed on production equipment. OSHA lockout/tagout enforcement in the United States and Japan's Industrial Safety and Health Act inspections amplify replacement demand for legacy non-compliant installations. Stakeholders must monitor evolving cybersecurity annexes to functional safety standards, as networked safety sensors face new conformity requirements that will reshape R&D priorities and vendor qualification timelines.
Market Dynamics
Functional safety certification mandates are compressing product development cycles while expanding the addressable market for sensors capable of SIL 3 and PLe performance tiers, forcing vendors to absorb validation costs or exit industrial segments entirely.
Growth Catalysts
- EU Machinery Directive enforcement:Mandatory documented failure mode analysis for production equipment is rotating replacement demand toward certified sensors with quantified reliability metrics and diagnostic coverage above 99 percent.
- Automotive collision avoidance deployment:OEMs are expanding sensor arrays for occupant protection and autonomous emergency braking, pulling MEMS accelerometers and infrared proximity units into high-volume procurement.
- Japan's Industrial Safety and Health Act inspections:Regulatory audits are amplifying retrofit demand for legacy installations that lack compliant lockout/tagout integration with sensor-triggered shutdown systems.
Market Restraints
- Wafer supply concentration:MEMS gas sensor fabrication depends on limited foundry capacity in Taiwan and South Korea, exposing environmental monitoring networks to allocation risk during semiconductor cycle peaks.
- Certification timeline friction:ISO 13849 and IEC 62061 validation cycles extend 14-18 months for new redundant architectures, delaying revenue recognition for product refreshes.
- Optoelectronic component cost volatility:Indium phosphide and gallium arsenide substrate prices fluctuate with 5G infrastructure buildouts, compressing margins on infrared emitter-receiver pairs for perimeter guarding.
Strategic Opportunities
- Battery manufacturing expansion:Gigafactory construction in Hungary and Poland is creating concentrated demand for thermal runaway detection sensors with sub-10 millisecond response latencies.
- Cybersecurity annex convergence:Emerging IEC 62443 integration requirements for networked safety sensors are opening premium positioning for vendors with pre-certified secure communication stacks.
- Aftermarket service unbundling:Predictive maintenance contracts for smoke and gas detection systems are extracting recurring revenue from building automation customers previously captured by equipment-only sales.
Industry Challenges
- Functional safety engineering talent scarcity:Qualified professionals capable of fault tree analysis and mean time to dangerous failure calculations remain concentrated at tier-one automation vendors, constraining mid-tier R&D scaling.
- Legacy PLC integration complexity:Brownfield manufacturing sites operate proprietary fieldbus protocols that require gateway development for modern safety sensor deployment, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Sensors Market |
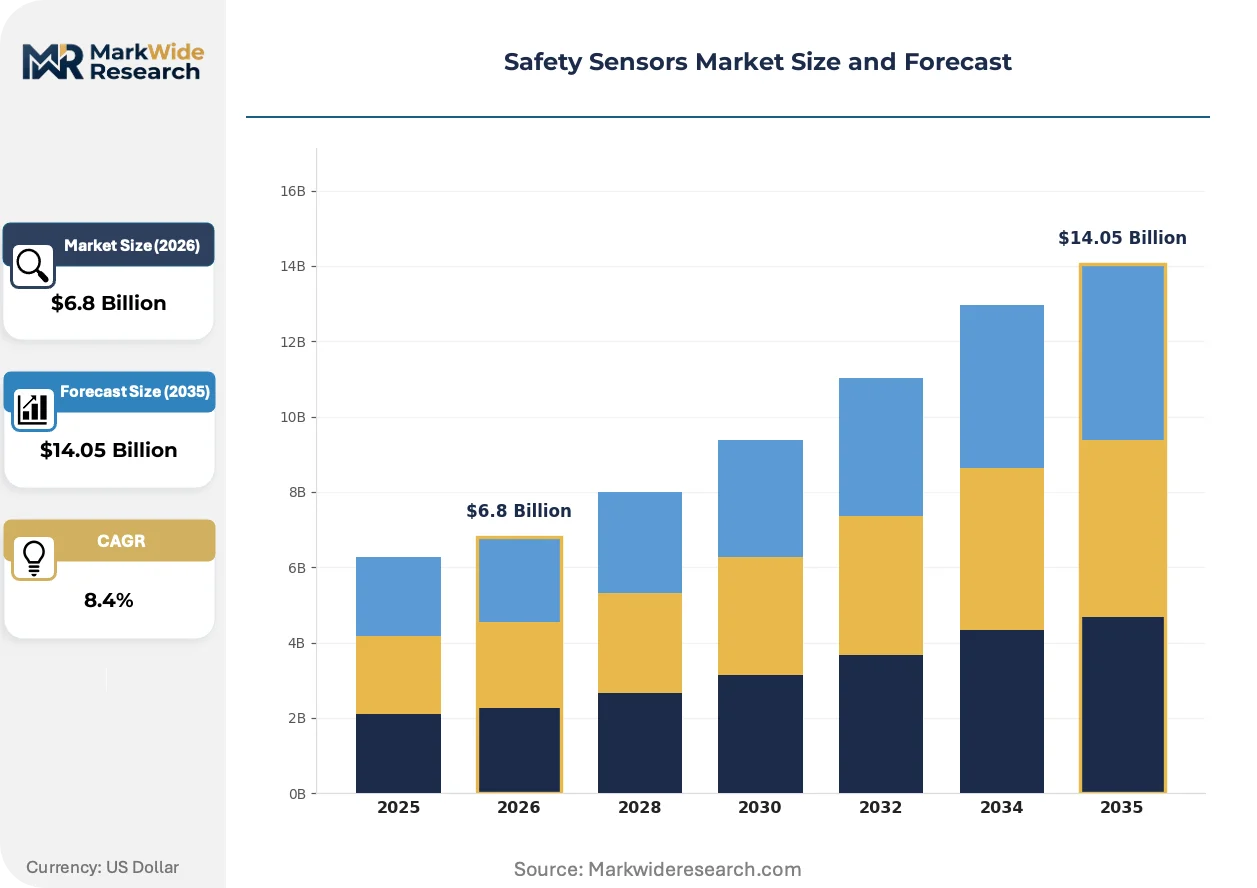
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smoke Detectors, Gas Sensors, Proximity Sensors, Temperature Sensors Technology: Infrared, Ultrasonic, Laser, MEMS End User: Aerospace, Automotive, Manufacturing, Home Security Application: Industrial Safety, Building Automation, Personal Safety, Environmental Monitoring |
| Companies Covered | ABB, Rockwell Automation, Siemens, Schneider Electric, Pepperl+Fuchs, SICK AG, OMRON Corporation, Pilz GmbH & Co. KG, Sensata Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Sensors Market Strategic Shifts & Innovations
Redundant sensor architectures and edge-processing capabilities are fragmenting traditional safety system value chains, compressing the role of centralized safety PLCs while elevating semiconductor content at the sensing node.
Time-of-flight infrared arrays are decomposing the market for mechanical safety interlocks and light curtain systems by enabling programmable detection zones without physical guarding infrastructure. Automotive OEMs and logistics automation buyers are adopting these solid-state alternatives at accelerating pace for flexible manufacturing lines. The technology is decomposing incumbent optoelectronic vendors' installed base by eliminating alignment-sensitive transmitter-receiver pairs and reducing commissioning labor.
REACH substance restrictions on lead-based solders and cadmium plating are forcing sensor housing manufacturers toward tin-bismuth alloys and stainless steel enclosures, raising unit costs but unlocking EU market access. Industrial automation suppliers with pre-validated material declarations are capturing specification preference from machine builders facing downstream due diligence requirements. The chemical compliance burden falls heaviest on small sensor assemblers lacking in-house regulatory affairs capacity, consolidating procurement toward integrated safety system vendors.
Machine builders are unbundling safety sensor specification from mechanical engineering departments and centralizing it within dedicated functional safety teams with direct vendor negotiation authority. This organizational shift is shortening qualification timelines for certified products while extending evaluation periods for uncertified alternatives. German automotive suppliers and packaging machinery manufacturers exhibit the most advanced procurement centralization, compressing vendor count and elevating technical support expectations.
Safety Sensors Market Segmentation
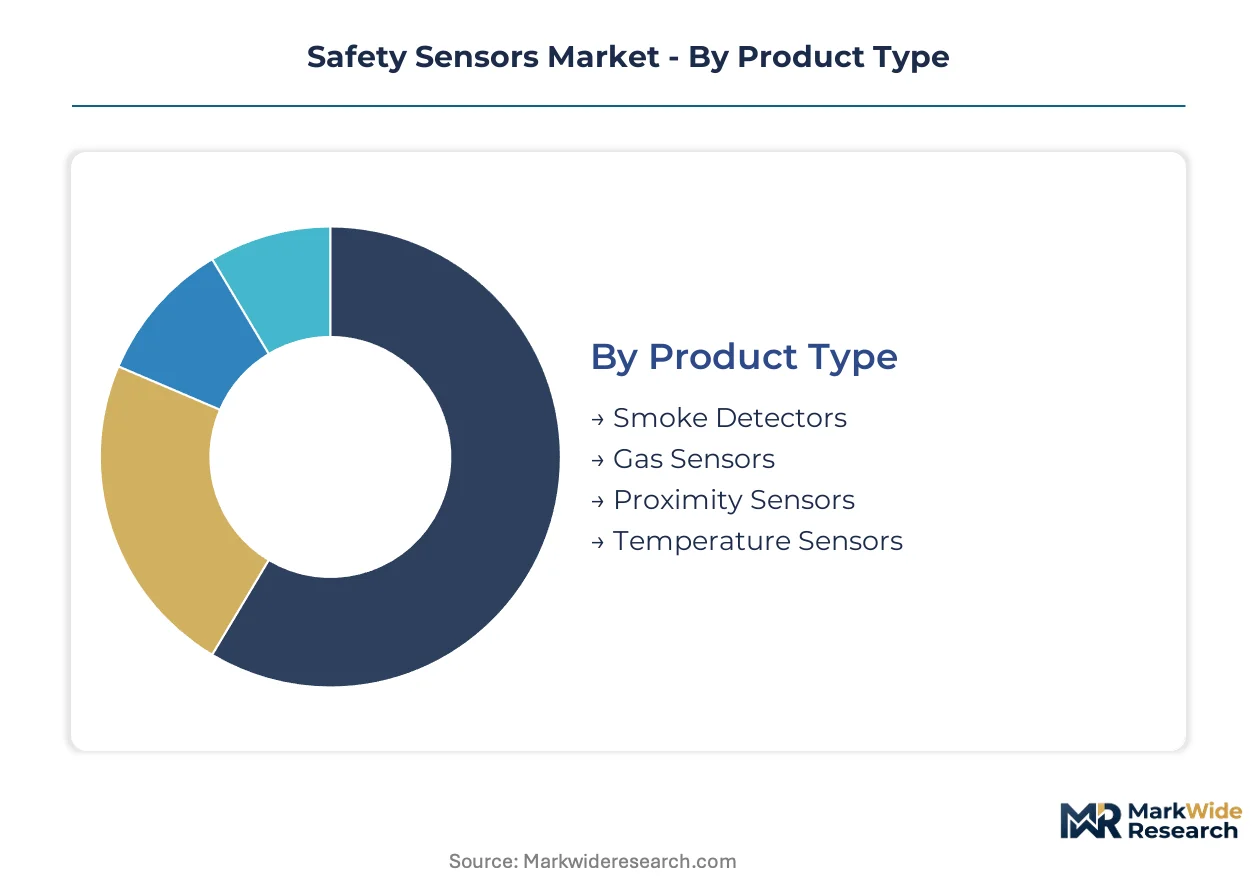
Segmentation in safety sensors reveals divergent margin structures and certification burdens across product architectures. Understanding substitution dynamics and end-use concentration helps vendors prioritize R&D investment and channel strategy.
Product Type:
Smoke detectors face the most acute substitution pressure from multi-sensor environmental nodes that consolidate detection capabilities into single housings.
- Smoke Detectors:Ionization and photoelectric variants dominate building automation with mandatory inspection schedules driving replacement revenue. Germany and France enforce recurring certification audits that lock in incumbent suppliers.
- Proximity Sensors:Inductive and capacitive architectures anchor manufacturing automation with sub-millisecond response latencies for perimeter guarding. Automotive OEMs in Stuttgart and Wolfsburg pull high-volume procurement for collision avoidance integration.
- Gas Sensors:Electrochemical and semiconductor elements detect toxic leaks in chemical processing facilities.
- Temperature Sensors:Thermocouple and RTD configurations monitor thermal excursions in battery manufacturing.
Proximity sensors anchor the volume base while gas sensors gain share at the steepest rate.
Technology:
Cost tier stratification separates mature infrared implementations from premium laser systems commanding threefold unit prices.
- Infrared:LED-photodiode pairs deliver proven ambient light immunity for industrial perimeter guarding with established supply chains. REACH substance restrictions on lead-based solders are forcing housing material transitions toward tin-bismuth alloys.
- MEMS:Wafer-level fabrication cuts unit costs for distributed environmental monitoring networks. Taiwan and South Korean foundry concentration exposes allocation risk during semiconductor cycle peaks.
- Ultrasonic:Piezoelectric transducers enable non-contact distance measurement in harsh environments.
- Laser:Time-of-flight arrays decompose mechanical interlock demand with programmable detection zones.
Infrared technology captures the largest installed base while MEMS is expanding most quickly through cost-down trajectories in gas detection.
End User:
Customer type determines procurement centralization intensity and technical support expectations.
- Automotive:OEMs specify SIL 3 and PLe certified sensors for autonomous emergency braking and occupant protection systems. German suppliers centralize functional safety teams with direct vendor negotiation authority.
- Manufacturing:Machine builders face ISO 13849 and EU Machinery Directive mandates for documented failure mode analysis. Brownfield sites struggle with proprietary fieldbus protocol integration.
- Aerospace:DO-178C and DO-254 certification requirements extend qualification timelines.
- Home Security:Residential installations prioritize cost minimization over diagnostic coverage metrics.
Manufacturing anchors demand volume while automotive is climbing the fastest on electrification and automation deployment.
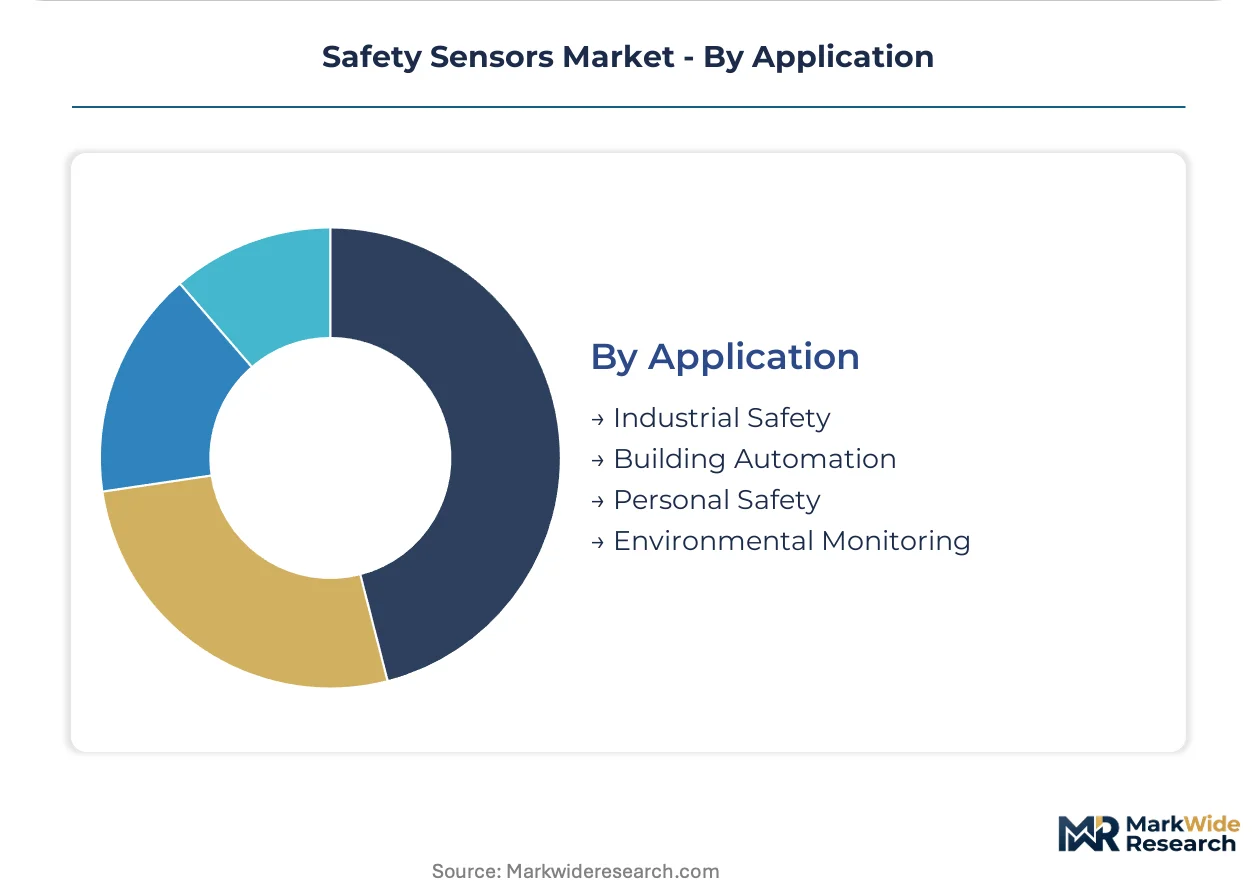
Application:
Application scope determines margin stability through recurring revenue potential versus one-time equipment sales.
- Industrial Safety:Perimeter guarding and lockout/tagout integration command premium pricing with mandatory replacement cycles. OSHA enforcement in the United States and Japan's Industrial Safety and Health Act amplify retrofit demand.
- Building Automation:Smoke detection and environmental monitoring extract steadier margins through inspection-mandated maintenance contracts.
- Environmental Monitoring:Distributed gas detection networks serve chemical and oil and gas facilities.
- Personal Safety:Wearable and portable devices serve confined space entry protocols.
Industrial safety anchors the revenue base while environmental monitoring is gaining share fastest on gigafactory construction in Hungary and Poland.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer foundry capacity for MEMS gas sensors concentrates in Taiwan and South Korea, creating allocation vulnerability during semiconductor upcycles. German automotive OEMs and industrial automation clusters pull disproportionate procurement volumes for SIL 3 certified devices.
Germany
Stuttgart and Wolfsburg automotive OEMs specify PLe certified proximity sensors for collision avoidance integration. The EU Machinery Directive mandates documented failure mode analysis for production equipment, compressing vendor qualification timelines. Munich and Stuttgart functional safety teams centralize procurement authority, elevating technical support expectations for certified suppliers.
United States
OSHA lockout/tagout enforcement amplifies retrofit demand for legacy installations lacking sensor-triggered shutdown systems. NHTSA autonomous emergency braking mandates rotate procurement toward MEMS accelerometers and infrared proximity units. Detroit automotive suppliers and Gulf Coast chemical facilities anchor regional demand concentration.
Japan
Industrial Safety and Health Act inspections drive replacement cycles for non-compliant gas detection networks in Osaka manufacturing corridors. METI carbon neutrality roadmaps accelerate battery manufacturing expansion, pulling thermal runaway detection sensors with sub-10 millisecond response latencies. Nagoya automotive clusters integrate redundant sensor architectures for occupant protection systems.
China
Gigafactory construction in Yangtze River Delta and Pearl River Delta concentrates demand for distributed environmental monitoring networks. GB standards for functional safety tighten certification requirements for industrial automation deployments. Shenzhen and Suzhou machine builders face brownfield integration complexity with proprietary fieldbus protocols.
South Korea
Seoul Capital Area semiconductor foundries supply wafer-level MEMS fabrication for cost-down trajectories in gas detection. MFDS medical device regulations spill over into industrial sensor quality assurance expectations. Busan-Ulsan petrochemical complexes deploy intrinsically safe sensors for hazardous environment monitoring.
Safety Sensors Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Integrated automation conglomerates bundle safety PLCs with certified sensors to reduce commissioning complexity for machine builders. Specialized optoelectronic vendors defend position through patented transceiver designs and perimeter guarding expertise. Component-scale suppliers compete on wafer-level fabrication economics for distributed environmental monitoring networks. Dominant competitive moves include strategic partnerships for secure communication stack pre-certification and geographic expansion into Hungarian and Polish battery manufacturing corridors.
Among German industrial automation specialists, Pepperl+Fuchs GmbH, SICK AG, and Pilz GmbH & Co. KG exemplify distinct archetype positioning. Pepperl+Fuchs anchors the intrinsically safe tier for hazardous environment deployments. SICK AG occupies a position within optoelectronic specialization for high-reliability perimeter guarding. Pilz represents the integrated safety system model combining certified sensors with control logic. These three entities collectively illustrate how functional safety engineering concentration at tier-one vendors constrains mid-tier R&D scaling across the European industrial base.
| Leading Market Players |
|---|
| ABB |
| Rockwell Automation |
| Siemens |
| Schneider Electric |
| Pepperl+Fuchs |
| SICK AG |
| OMRON Corporation |
| Pilz GmbH & Co. KG |
| Sensata Technologies |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with Taiwan and South Korean MEMS foundries lock in wafer supply access and price visibility for safety sensor vendors serving industrial automation and automotive OEMs. These arrangements insulate tier-one suppliers from spot-market volatility while compressing margin flexibility for mid-tier players lacking comparable procurement scale.
Pricing Analysis
ISO 13849 and IEC 62061 certification tiers dictate the pricing structure across the safety sensors landscape. Three-tier pricing stratification separates SIL 3/PLe certified premium units from standard industrial-grade sensors and economy-tier uncertified alternatives. Pricing pressure intensifies in the economy tier as Chinese manufacturers scale MEMS production for distributed environmental monitoring networks. Automotive OEMs exhibit the lowest price sensitivity due to liability exposure and mandatory functional safety compliance, while building automation contractors prioritize cost minimization over diagnostic coverage metrics.
Supply Chain Analysis
Strategic stockpiling of indium phosphide and gallium arsenide substrates dominates inventory strategy among optoelectronic safety sensor manufacturers exposed to 5G infrastructure demand cycles. Wafer-level MEMS fabrication concentrates in Taiwan and South Korea, drawing from specialized foundry capacity for electrochemical gas sensor elements. Supply chain risk centers on single-source vulnerability for infrared emitter-receiver pairs during semiconductor upcycles. Distribution runs through integrated automation distributors in Germany and direct OEM supply agreements in Stuttgart and Wolfsburg automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The safety sensors market is accelerating through regulatory inflection as IEC 62443 cybersecurity annexes reshape certification requirements for networked industrial devices. This convergence of functional safety and secure communication standards creates premium positioning opportunities for pre-certified vendors.
For Market Incumbents: Secure redundant foundry relationships beyond Taiwan and South Korea to mitigate allocation risk during semiconductor cycle peaks. Anchor certification investment in IEC 62443 pre-validation to defend against emerging entrants with native secure communication stacks. Prioritize backward integration into MEMS wafer fabrication for cost control in distributed gas detection networks.
For New Entrants and Emerging Players: SIL 2 fast-track certification pathways offer entry into manufacturing automation segments with shorter validation timelines than SIL 3 tiers. Target aftermarket service contracts for smoke and gas detection systems in building automation, where incumbent equipment-only vendors leave recurring revenue unclaimed. Pursue white-label partnerships with Hungarian and Polish battery manufacturers for thermal runaway detection sensor deployment.
For Investors and Strategic Acquirers: Component-scale MEMS specialists with wafer-level fabrication economics represent compelling acquisition targets as environmental monitoring networks expand. Long-term viability hinges on cybersecurity certification readiness and foundry relationship depth. Watch for IEC 62443 implementation deadlines as inflection indicators that will reshape vendor qualification timelines and consolidate procurement toward pre-certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Communication Stack Pre-Certification | IEC 62443 compliance unlocks premium positioning for networked safety sensors in German automotive supply chains. |
| MEMS Foundry Capacity Reservation | Long-term wafer agreements with Taiwan and South Korean suppliers insulate against semiconductor cycle allocation risk. |
| Aftermarket Service Unbundling | Predictive maintenance contracts extract recurring revenue from building automation customers beyond equipment-only sales. |
| Battery Manufacturing Corridor Expansion | Gigafactory construction in Hungary and Poland concentrates demand for thermal runaway detection sensors with sub-10 millisecond response. |
| Redundant Architecture R&D Investment | Diagnostic coverage above 99 percent satisfies EU Machinery Directive mandates for SIL 3 and PLe tier procurement. |
Research Approach
Initial hypotheses were tested against primary input from functional safety engineering directors, automotive OEM procurement leads, industrial automation system integrators, and MEMS foundry operations managers, then refined through secondary validation. Primary fieldwork combined structured interviews with plant engineers at Stuttgart and Wolfsburg manufacturing facilities, regulatory affairs specialists at German TÜV organizations, and channel partners distributing Pepperl+Fuchs and SICK AG portfolios. Secondary sources encompassed EU Machinery Directive implementation guidance, ISO 13849 and IEC 62061 certification databases, SEC filings from listed automation conglomerates, and customs trade data for infrared optoelectronic component flows. Bottom-up sensor shipment estimates triangulated against top-down industrial automation capital expenditure projections.
Variance decomposition across technology segments, end-user industries, and geographic production clusters anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product architecture, certification tier, response latency specification, and regional regulatory enforcement intensity. CAGRs derived from installed base turnover rates, replacement cycle compression from mandate enforcement, and technology substitution curves for time-of-flight infrared arrays displacing mechanical interlocks. Industry-specific forecast inputs incorporated OSHA inspection frequency data and Japan's Industrial Safety and Health Act audit schedules.
Underlying assumptions cover sustained EU Machinery Directive enforcement, stable Taiwan and South Korean foundry capacity allocation, and REACH substance restriction compliance timelines, with deviation risk concentrated in semiconductor cycle volatility and cybersecurity standard implementation delays. Revision becomes warranted when IEC 62443 adoption thresholds cross regulatory enforcement tipping points or MEMS foundry allocation constraints exceed contracted reservation volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Anemometer Market
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Photoelectric Sensor Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Contact Steering Torque Sensor Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Europe Human Machine Interface Market