
 BRIC Performance Coatings Market | 2026-2036
BRIC Performance Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
BRIC Performance Coatings Market Analysis
Maintenance and recoating service contracts is expanding as a recurring revenue layer across the BRIC Performance Coatings Market, shifting supplier economics from one-time product sales to lifecycle coverage agreements. PPG Industries leverages its global technical service network to anchor long-term industrial maintenance programs in Brazil and Russia. Akzo Nobel N.V. competes through specialized marine recoating solutions tied to port infrastructure cycles. Sherwin-Williams Company dominates architectural maintenance channels through controlled distribution networks in urban India and China.
Performance coatings are engineered film-forming systems comprising binders, pigments, solvents, and functional additives, applied to substrates to confer corrosion resistance, thermal stability, or chemical protection in aggressive operating environments. Waterborne technology leads formulation transitions across the BRIC region as environmental compliance tightens, while powder coatings represent the fastest-growing technology segment driven by automotive and consumer goods manufacturing scale-up in India and China. Acrylic formulations occupy mature volume positions in construction applications, whereas polyurethane systems concentrate margin pools in aerospace and specialized industrial end uses.
BIS certification requirements and China's NMPA environmental standards are reshaping product registration and import protocols, forcing reformulation investments and local manufacturing partnerships. India's PLI scheme for chemical manufacturing and Brazil's ANVISA industrial chemical frameworks further condition market access and technology transfer terms. Stakeholders must monitor regulatory divergence across the four BRIC jurisdictions to align R&D pipelines with diverging compliance timelines and local content expectations.
Market Dynamics
Waterborne technology transitions across Brazil, Russia, India, and China are compressing solventborne capacity and forcing reformulation investments at manufacturing facilities clustered near automotive OEM plants and port infrastructure.
Growth Catalysts
- Automotive OEM procurement:Brazil and India anchor demand expansion as vehicle manufacturers specify high-durability finishes for export markets and domestic fleet replacement cycles.
- China's NMPA environmental standards:Tightening VOC limits accelerate waterborne adoption in industrial coating applications, creating compliance-driven replacement demand.
- India's PLI scheme for chemical manufacturing:Production-linked incentives attract domestic capacity expansion for coating raw materials and finished formulations.
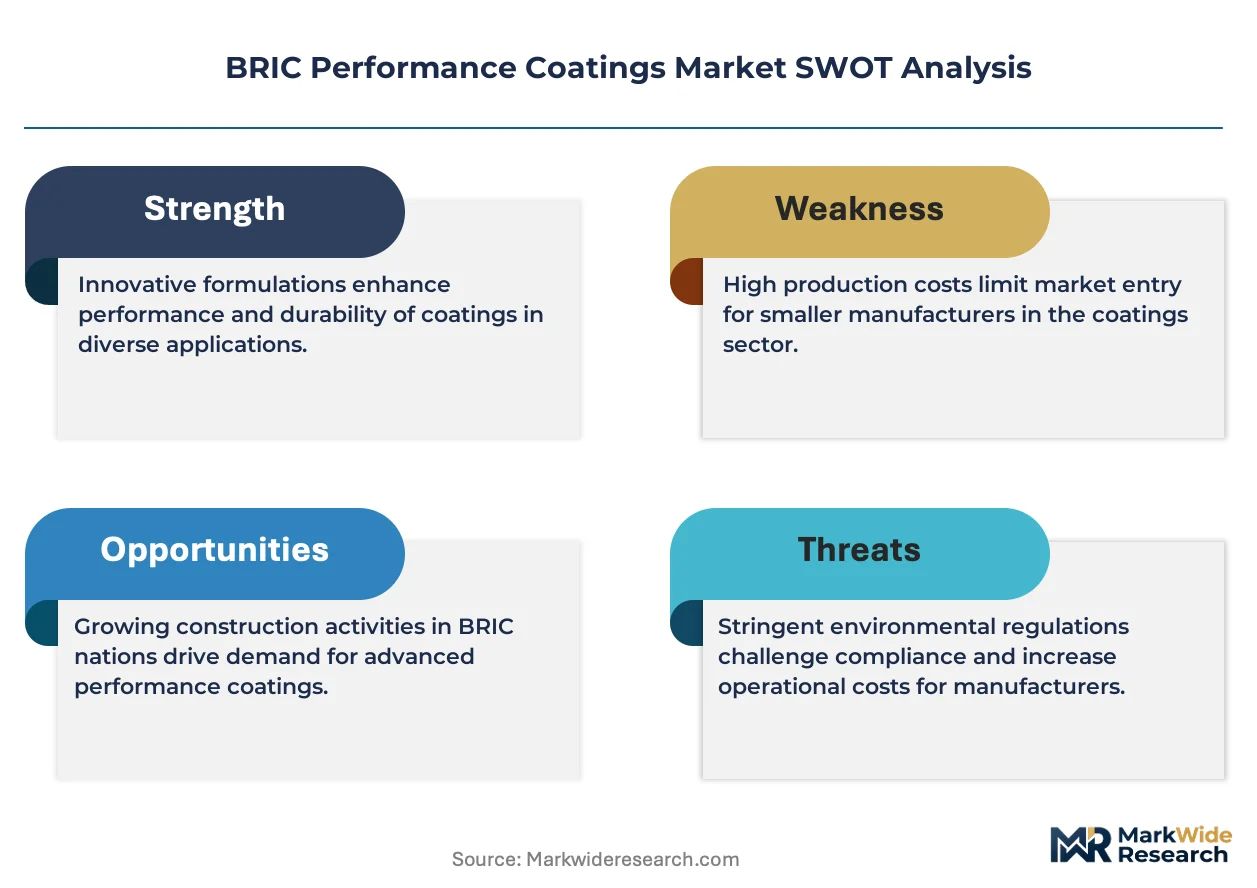
Market Restraints
- Petrochemical feedstock volatility:Epoxy resins and isocyanates face price swings tied to crude oil derivatives, compressing margin predictability for formulators.
- Import dependency in specialty additives:Russia and Brazil rely on concentrated Asian supply for corrosion inhibitors and rheology modifiers.
- Technical limitations in extreme climates:Waterborne systems struggle with cure reliability in high-humidity monsoon conditions across India's western industrial corridor.
Strategic Opportunities
- Marine recoating in Russian Far East ports:Ice-class vessel maintenance and Arctic infrastructure expansion create specialized demand for cold-temperature curing systems.
- Brazil's ANVISA industrial chemical frameworks:Regulatory harmonization with Mercosur standards opens cross-border formulation registration pathways.
- Digital coating specification platforms:Online technical selection tools are penetrating architectural maintenance channels in tier-2 Chinese cities.
Industry Challenges
- Formulation chemist scarcity:Waterborne technology expertise gaps constrain R&D velocity at mid-size Brazilian and Indian producers.
- BIS certification timeline compression:India's Bureau of Indian Standards review queues extend product launch windows for imported specialty coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRIC Performance Coatings Market |
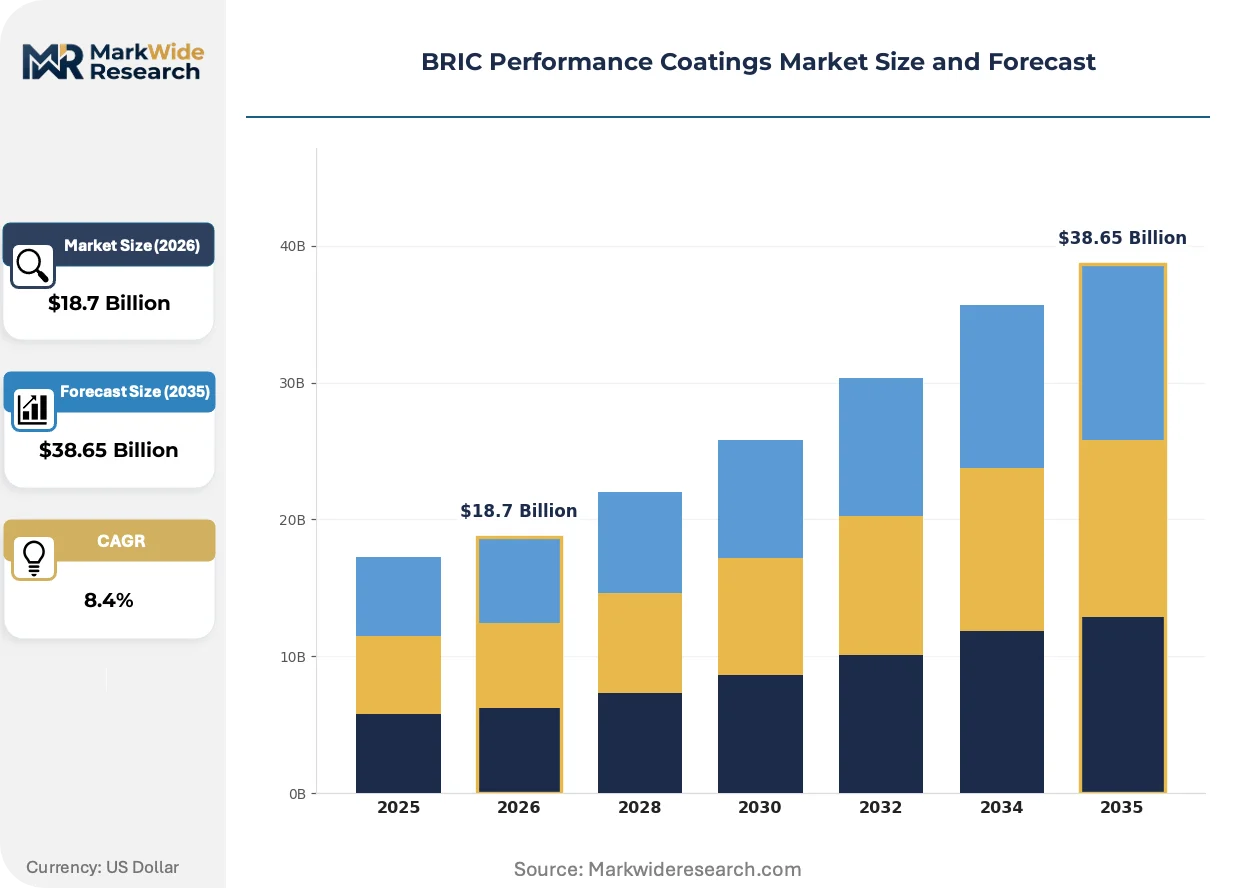
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
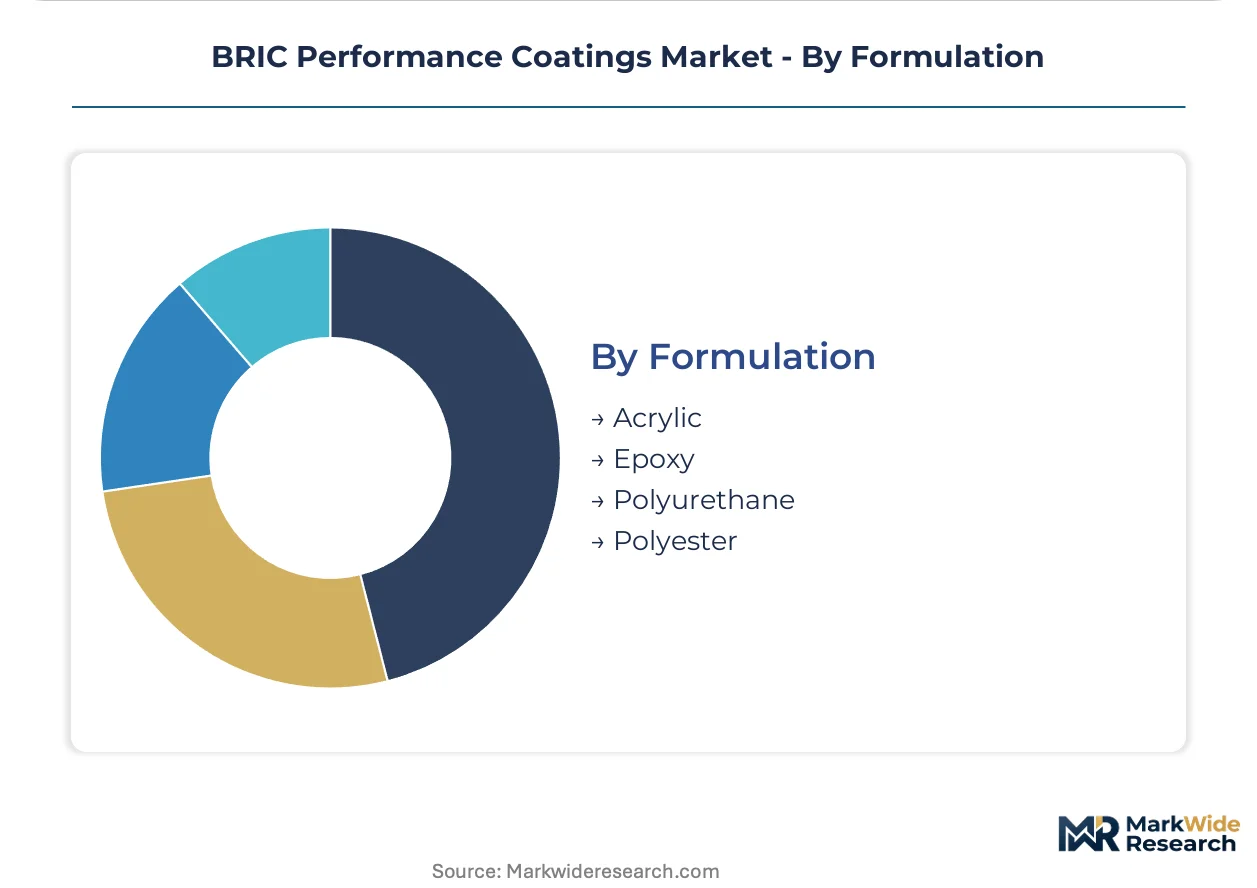
| Segmentation | Product Type: Architectural Coatings, Industrial Coatings, Automotive Coatings, Marine Coatings Technology: Waterborne, Solventborne, Powder Coatings, UV-Curable End User: Construction, Automotive, Aerospace, Consumer Goods Formulation: Acrylic, Epoxy, Polyurethane, Polyester |
| Companies Covered | PPG Industries, Inc., Akzo Nobel N.V., Sherwin-Williams Company, Kansai Nerolac Paints Limited, Axalta Coating Systems Ltd., BASF SE, Berger Paints India Ltd., Jotun A/S, Hempel A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRIC Performance Coatings Market Emerging Trajectories
Formulation chemistry, compliance architecture, and procurement interfaces are undergoing simultaneous transformation across BRIC manufacturing corridors.
Self-healing coating systems incorporating microencapsulated repair agents are electrifying protective applications in offshore oil platforms and chemical processing equipment. Russian energy operators and Indian refinery operators pilot these systems to extend maintenance intervals in corrosive environments. The technology is compressing traditional recoating cycles and repositioning supplier relationships around performance guarantees rather than material volume.
China's NMPA environmental standards now mandate real-time VOC monitoring at coating application facilities, forcing capital deployment into emissions control infrastructure. Industrial plants in Shanghai and Guangdong provinces retrofit solvent recovery systems or convert lines entirely to waterborne processes. Powder coating installations accelerate fastest in automotive parts manufacturing where electrostatic application efficiency offsets equipment upgrade costs.
Maintenance service contracts now bundle coating supply with surface preparation and application labor, unbundling the traditional product-only sale. Brazilian shipyards and Chinese wind turbine operators favor integrated lifecycle agreements over transactional procurement. This restructuring concentrates purchasing power with facility owners and rewards suppliers with technical service networks spanning multiple coating chemistries and substrate preparation protocols.
BRIC Performance Coatings Market Segmentation
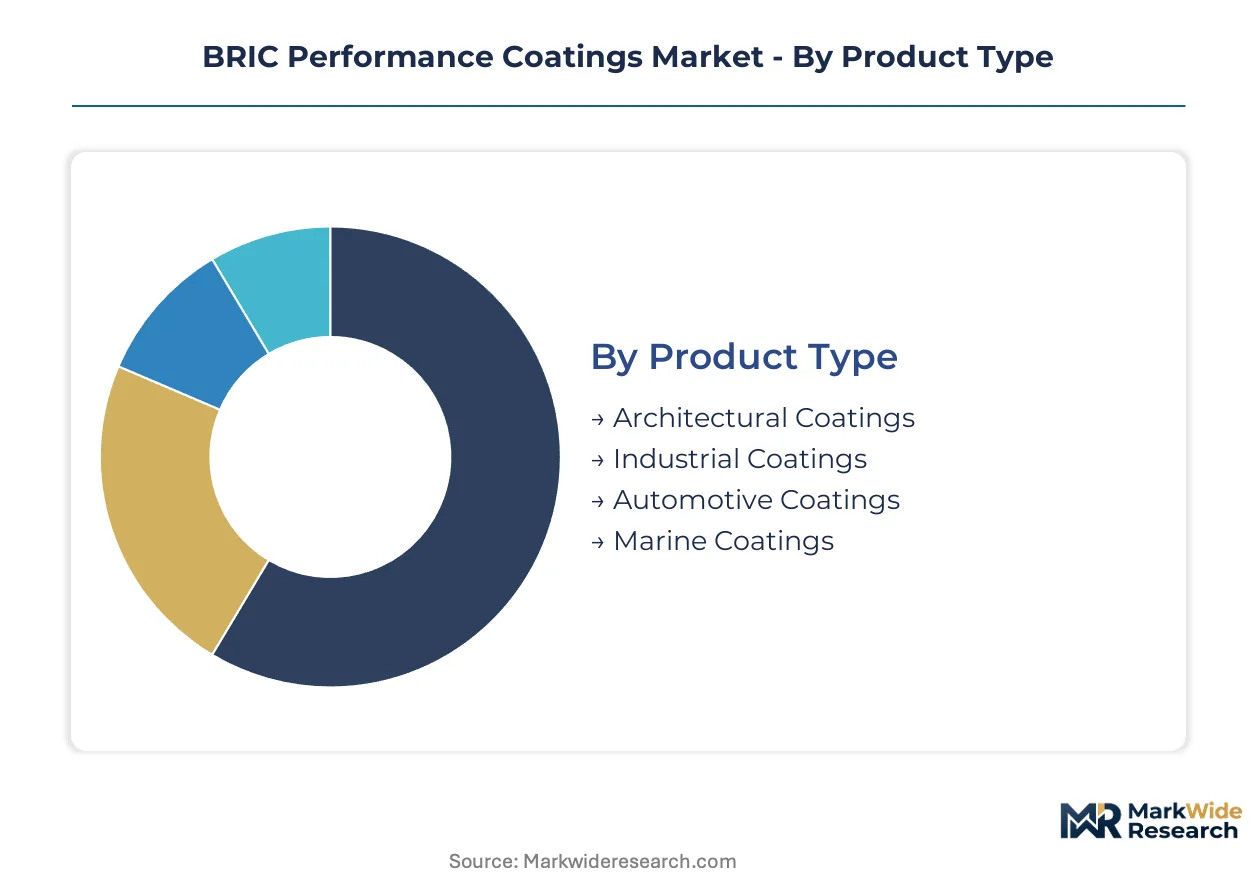
Performance coatings in Brazil, Russia, India, and China serve divergent substrate protection requirements across climatic extremes and regulatory regimes. Segmentation reveals how formulation chemistry, application technology, and end-use specifications concentrate margin pools and dictate supplier capability investments. Each axis exposes distinct competitive positioning opportunities tied to local manufacturing scale and environmental compliance timelines.
Product Type:
Formulation chemistry and film thickness specifications define performance thresholds across substrate categories.
- Architectural Coatings:Exterior-grade acrylic and silicone-modified systems dominate facade protection in coastal Indian cities and high-humidity Brazilian metros. BIS certification for weathering resistance and China's GB standards for VOC content force reformulation cycles every 3-4 years.
- Industrial Coatings:Heavy-duty epoxy and polyurethane systems protect steel infrastructure in Russian Arctic terminals and Indian refinery complexes. Demand clusters near port infrastructure and steel production zones where corrosion rates accelerate maintenance intervals.
- Automotive Coatings:OEM clearcoats and basecoat systems in São Paulo and Chennai manufacturing corridors specify chip resistance and gloss retention for tropical UV exposure.
- Marine Coatings:Fouling-release and ice-class systems serve Vladivostok port operations and Brazilian offshore platforms.
Mature deployment sits with Architectural Coatings. Newer deployment is concentrated in Marine Coatings.
Technology:
Application method and cure chemistry determine capital intensity and regulatory compliance pathways.
- Waterborne:Acrylic and polyurethane dispersions lead transitions in Shanghai and Guangdong industrial zones where NMPA VOC mandates force solventborne displacement. Cure reliability challenges persist in monsoon conditions across India's western industrial corridor.
- Solventborne:High-solids epoxy and alkyd systems retain share in Russian Far East applications where low-temperature cure demands exceed waterborne capability envelopes.
- Powder Coatings:Thermoset polyester and epoxy hybrids gain fastest in automotive parts manufacturing across Pune and Chongqing where electrostatic efficiency offsets equipment costs.
- UV-Curable:Acrylate oligomer systems penetrate consumer goods and electronics finishing in Shenzhen and Bangalore where line speed and energy reduction justify capital investment.
Established infrastructure supports Solventborne. Steepest expansion trajectory belongs to Powder Coatings.
End User:
Substrate value and failure cost magnitude drive specification stringency and supplier qualification requirements.
- Construction:Protective and decorative systems for concrete and steel structures in Brazilian urban expansion corridors and Indian smart city projects.
- Automotive:OEM assembly plants in São Paulo and Chennai specify coating durability for 10-year corrosion warranties in export markets.
- Aerospace:Polyurethane and epoxy primers for MRO facilities in Moscow and Bangalore where temperature cycling and chemical exposure demand qualified product lists.
- Consumer Goods:Appliance and electronics finishing in Guangdong and Maharashtra manufacturing clusters.
Volume concentration rests with Construction. Premium specification intensity peaks in Aerospace.
Formulation:
Polymer backbone chemistry determines adhesion, chemical resistance, and weathering performance trade-offs.
- Acrylic:Waterborne emulsions and thermoplastic dispersions dominate architectural maintenance in urban India and Brazil where UV durability and color retention command specification priority.
- Epoxy:Bisphenol-A and novolac systems anchor industrial protection in Russian oil terminals and Indian chemical processing zones where immersion service and solvent resistance justify material cost premiums.
- Polyurethane:Aliphatic isocyanate-cured systems serve aerospace and premium automotive clearcoats requiring gloss retention and flexibility.
- Polyester:Saturated backbone formulations for powder coating applications in automotive parts and consumer goods manufacturing.
Commodity scale favors Acrylic. Technical differentiation concentrates in Epoxy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of coating raw materials consumed across the BRIC bloc, while Brazil and India drive finished product demand through automotive and infrastructure expansion. Russia's domestic production centers on industrial-grade formulations for Arctic and energy applications. Regulatory divergence across the four jurisdictions creates distinct compliance pathways for suppliers.
Brazil
Automotive OEM assembly plants in São Paulo and Minas Gerais specify high-durability finishes for export compliance and domestic fleet renewal. ANVISA industrial chemical frameworks govern formulation registration and cross-border trade within Mercosur. Port infrastructure clusters near Santos and Rio de Janeiro concentrate marine coating demand for offshore platform maintenance.
Russia
Ice-class vessel operators and Arctic energy terminals require cold-temperature curing systems for infrastructure protection. The country's national environmental regulator enforces emissions controls at industrial coating facilities in the Far East. Vladivostok port operations anchor specialized marine recoating demand tied to seasonal navigation windows.
India
Automotive manufacturing corridors in Maharashtra and Tamil Nadu expand procurement of waterborne clearcoats and basecoats for tropical UV exposure. BIS certification mandates compress product launch timelines for imported specialty formulations. The western industrial corridor spanning Gujarat hosts marine and refinery coating facilities near steel production zones and port infrastructure.
China
NMPA environmental standards mandate real-time VOC monitoring at coating application facilities in Shanghai and Guangdong provinces. GB standards for industrial emissions accelerate waterborne technology transitions in automotive parts manufacturing. Pearl River Delta consumer goods producers deploy UV-curable systems for electronics finishing where line speed justifies capital investment.
BRIC Performance Coatings Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across formulation chemistry and application technology segments. The market structures around three tiers: integrated multinationals with captive raw material supply, regional specialists with deep local regulatory expertise, and technology licensors monetizing proprietary resin systems. Consolidation pressures intensify as environmental compliance costs rise and customer procurement shifts toward integrated lifecycle contracts. Dominant competitive moves include backward integration into resin manufacturing and strategic partnerships with automotive OEM technical centers.
Among North American-dominant multinationals, PPG Industries, Sherwin-Williams Company, and Axalta Coating Systems Ltd. occupy positions exemplifying the integrated service-provider archetype. These entities anchor long-term industrial maintenance programs and OEM technical partnerships across Brazilian and Indian manufacturing corridors. Their scale enables simultaneous compliance with China's NMPA standards, India's BIS certification requirements, and Brazil's ANVISA frameworks without fragmenting R&D investment.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| Sherwin-Williams Company |
| Kansai Nerolac Paints Limited |
| Axalta Coating Systems Ltd. |
| BASF SE |
| Berger Paints India Ltd. |
| Jotun A/S |
| Hempel A/S |
| Others |
Supply Flow & Price Mechanics
Backward integration into resin manufacturing anchors supply positioning and pricing power for coating formulators across BRIC manufacturing corridors. Captive production of epoxy intermediates and acrylic dispersions insulates integrated multinationals from petrochemical feedstock volatility while compressing procurement costs for waterborne technology transitions mandated by China's NMPA standards.
Pricing Analysis
Margin tightening in mid-tier industrial coatings reflects epoxy resin and isocyanate cost volatility tied to crude oil derivatives. Three-tier pricing structure across premium, standard, and economy levels separates qualified aerospace formulations from commodity architectural grades. Cost-down pressure on solventborne systems accelerates because waterborne alternatives achieve regulatory compliance at lower lifecycle cost. Construction sector buyers exhibit highest price sensitivity, while aerospace MRO facilities prioritize performance guarantees over unit economics.
Supply Chain Analysis
Formulation chemist scarcity in Brazilian and Indian manufacturing hubs constrains R&D velocity and batch consistency for waterborne technology transitions. Raw material supply concentrates in China for epoxy intermediates, Germany for specialty isocyanates, and India for acrylic monomers. Corrosion inhibitor and rheology modifier inputs rest on concentrated Asian supply channels vulnerable to export licensing delays. Distribution runs through controlled technical service networks for industrial maintenance contracts, bypassing commodity merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating suppliers are racing to secure captive resin capacity and lifecycle service contracts as the primary levers for margin defense. Winners will anchor customer relationships through integrated maintenance programs rather than transactional product sales.
For Market Incumbents: Deploy technical service network expansion to anchor long-term industrial maintenance programs across Brazilian automotive corridors and Indian refinery zones. Consolidate formulation expertise through targeted hiring of waterborne technology specialists to offset chemist scarcity at mid-size competitors. Defend against emerging regional specialists by accelerating BIS certification and ANVISA registration timelines. For New Entrants and Emerging Players: The price-point gap between premium polyurethane aerospace coatings and economy-grade architectural acrylics creates entry space for mid-tier industrial specialists. Marine recoating in Russian Far East ports and tier-2 Chinese architectural maintenance channels represent penetrable white-space targets. Pursue digital coating specification platforms as the primary go-to-market angle to bypass entrenched distribution relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated multinationals seeking regional regulatory expertise and captive resin capacity. Long-term viability hinges on waterborne technology transition completion and compliance with tightening VOC mandates across all four BRIC jurisdictions. Target acquisition archetypes include Brazilian and Indian mid-size formulators with established ANVISA or BIS certification portfolios. Watch for NMPA enforcement acceleration in Guangdong province as the signal for sector consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Captive epoxy and acrylic supply insulates margins from petrochemical volatility in Shanghai and São Paulo corridors. |
| Waterborne Technology Transition | Reformulation investments align with NMPA VOC mandates and BIS certification timelines across industrial application facilities. |
| Lifecycle Service Contract Expansion | Bundled coating supply with surface preparation labor concentrates purchasing power with Brazilian shipyard and Chinese wind turbine operators. |
| Regional Certification Acceleration | ANVISA and BIS registration pipelines compress product launch windows for imported specialty formulations. |
| Digital Specification Platform Deployment | Online technical selection tools penetrate tier-2 Chinese architectural channels outside controlled distribution networks. |
Methodological Framework
Multi-period observation of formulation chemistry transitions, regulatory compliance timelines, and procurement contract structures anchored the trend analysis, supplemented by interviews with plant managers at coating application facilities, procurement leads at automotive OEMs, technical R&D directors at multinational formulators, and distribution channel partners across BRIC manufacturing corridors. Secondary validation drew from customs and trade data, SEC 10-K filings, ANVISA registration databases, BIS certification records, and NMPA environmental compliance disclosures. Bottom-up volume modeling and top-down value triangulation reconciled segment estimates across the analysis window.
Segment-weighting approaches distributed value and volume across formulation chemistry, application technology, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to segment-level baselines, incorporating automotive OEM production forecasts, port infrastructure investment pipelines, and industrial emissions control capital deployment schedules as industry-specific inputs throughout the projection horizon.
Underlying measurement precision varies by segment; waterborne technology transitions and powder coating installations carry tighter precision than solventborne displacement rates in Russian Arctic applications. Forecasts reflect assumptions regarding regulatory enforcement consistency, feedstock price stability, and chemist availability that material deviation in any named trigger warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Vietnam Architectural Coatings Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
South Africa Automotive OEM Coatings Market
Coatings
Trim Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
Europe Thermal Spray Market
Coatings
Global Anti-Corrosion Coating Market
Coatings
Marine Coatings Market
Coatings
Cladding Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
South America Thermal Spray Market
Coatings
Fire Retardant Coatings Market
Coatings
Epoxy Powder Coatings Market
Coatings
Wire Enamels Market
Coatings
Fillers and Coating Market